
 Endoscopy Video Systems Market | 2026-2036
Endoscopy Video Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopy Video Systems Market Analysis
4K resolution specification-tier is collapsing the cost barrier between hospital-grade surgical suites and outpatient clinic settings. Olympus Corporation leverages its optical heritage to dominate gastrointestinal visualization platforms. KARL STORZ SE & Co. KG anchors the rigid endoscopy segment through captive supply of precision-engineered lens assemblies. FUJIFILM Holdings Corporation differentiates via AI-integrated image processing units that reduce physician interpretation time.
Endoscopy video systems comprise camera heads, image processing units, light sources, and display monitors that transmit real-time visual data through fiber-optic or digital sensor pathways to enable minimally invasive diagnostic and therapeutic procedures. These systems typically operate at color temperatures between 5000K and 6500K to ensure accurate tissue differentiation during procedures. Gastroenterology applications command the largest installed base due to screening program volumes, while wireless technology represents the fastest-expanding segment as facilities seek cable-free operating room configurations. Ambulatory surgical centers constitute a concentrated margin pool where compact, all-in-one video cart systems reduce capital deployment and sterilization logistics.
FDA premarket clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access conditions for manufacturers serving Western healthcare systems. ISO 13485 quality management standards and IEC 60601-1 electrical safety specifications govern design verification and clinical validation protocols across all major jurisdictions. Stakeholders must monitor reimbursement coding shifts for office-based endoscopic procedures, as these directly influence capital equipment purchasing cycles and technology upgrade timelines.
Market Dynamics
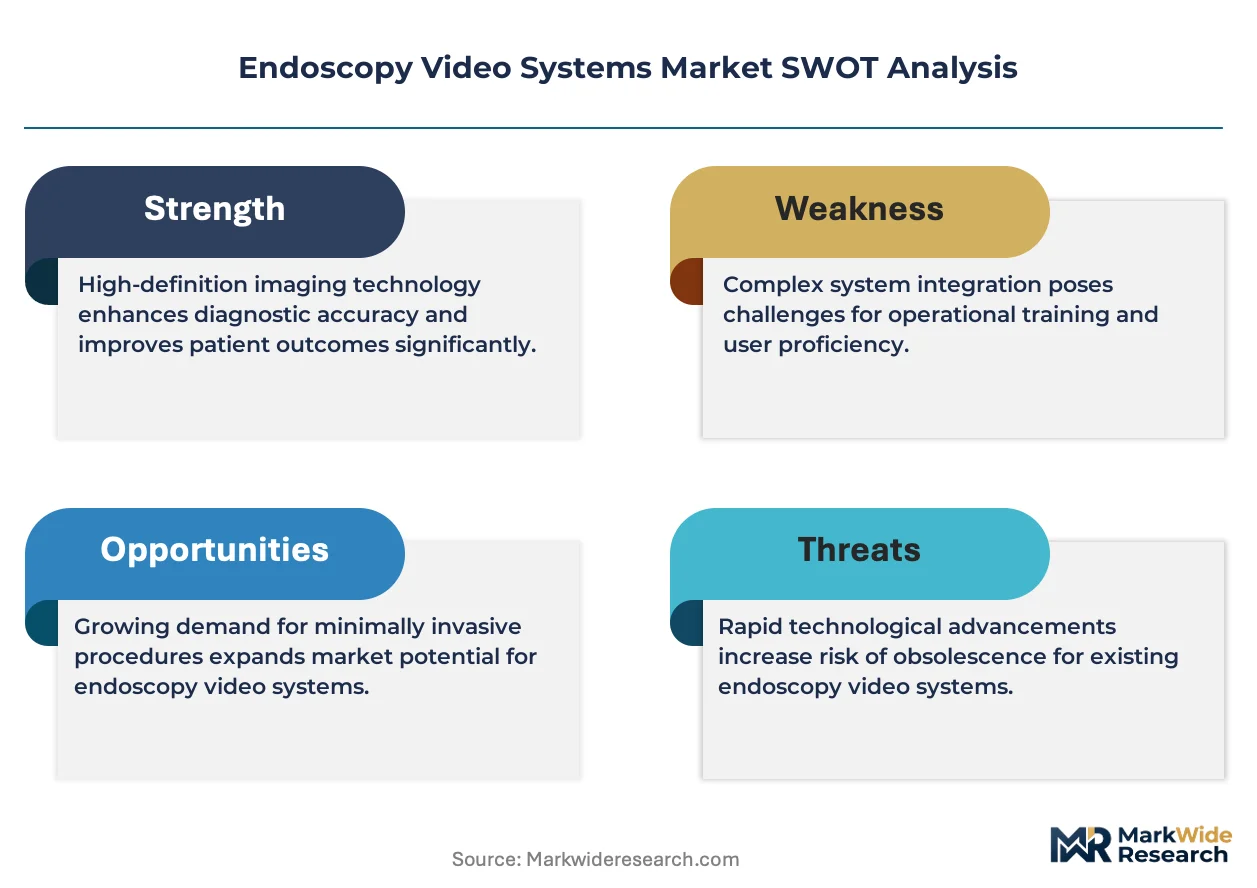
4K resolution adoption is bifurcating the installed base between premium surgical suites and cost-constrained outpatient facilities, compressing upgrade cycles and forcing manufacturers to defend margin across diverging price-performance tiers simultaneously.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter clinical evidence requirements for reusable endoscopic accessories are accelerating hospital replacement of aging video cart systems with compliant platforms that integrate sterilization validation protocols.
- Ambulatory surgical center expansion:United States outpatient facilities are deploying compact all-in-one visualization systems to reduce capital footprint and enable same-day discharge protocols for gastrointestinal procedures.
- Wireless transmission modules:Cable-free camera-to-processor links are eliminating operating room tripping hazards while supporting rapid room turnover demanded by high-volume endoscopy suites.
Market Restraints
- CMOS sensor supply concentration:Precision image sensor fabrication concentrates among a handful of East Asian foundries, exposing manufacturers to allocation risk during semiconductor demand surges.
- IEC 60601-1 electrical safety certification timelines:Third-party testing for medical-grade isolation and electromagnetic compatibility extends product launch windows by 8-14 months for new video processor architectures.
- Single-use endoscope substitution:Disposable bronchoscopy and urology platforms are capturing low-complexity diagnostic volumes that previously sustained reusable system utilization rates.
Strategic Opportunities
- India diagnostic infrastructure expansion:Government screening programs for colorectal and gastric malignancies are creating first-time demand for portable video systems in tier-2 and tier-3 cities.
- AI-integrated image enhancement:Real-time polyp detection algorithms are converging with 4K processors to reduce physician cognitive load and enable nurse-assisted screening protocols.
- Office-based procedure reimbursement codes:United States CMS valuation shifts for in-office endoscopic mucosal resection are incentivizing gastroenterology practices to acquire independent visualization capabilities.
Industry Challenges
- Biomedical engineer specialization gaps:Maintenance of fiber-optic light guides and 4K sensor calibration requires expertise that outpaces training program output in secondary markets.
- Legacy analog-digital integration complexity:Hybrid operating rooms must synchronize SDI, HDMI, and proprietary camera link protocols across multi-vendor equipment stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopy Video Systems Market |
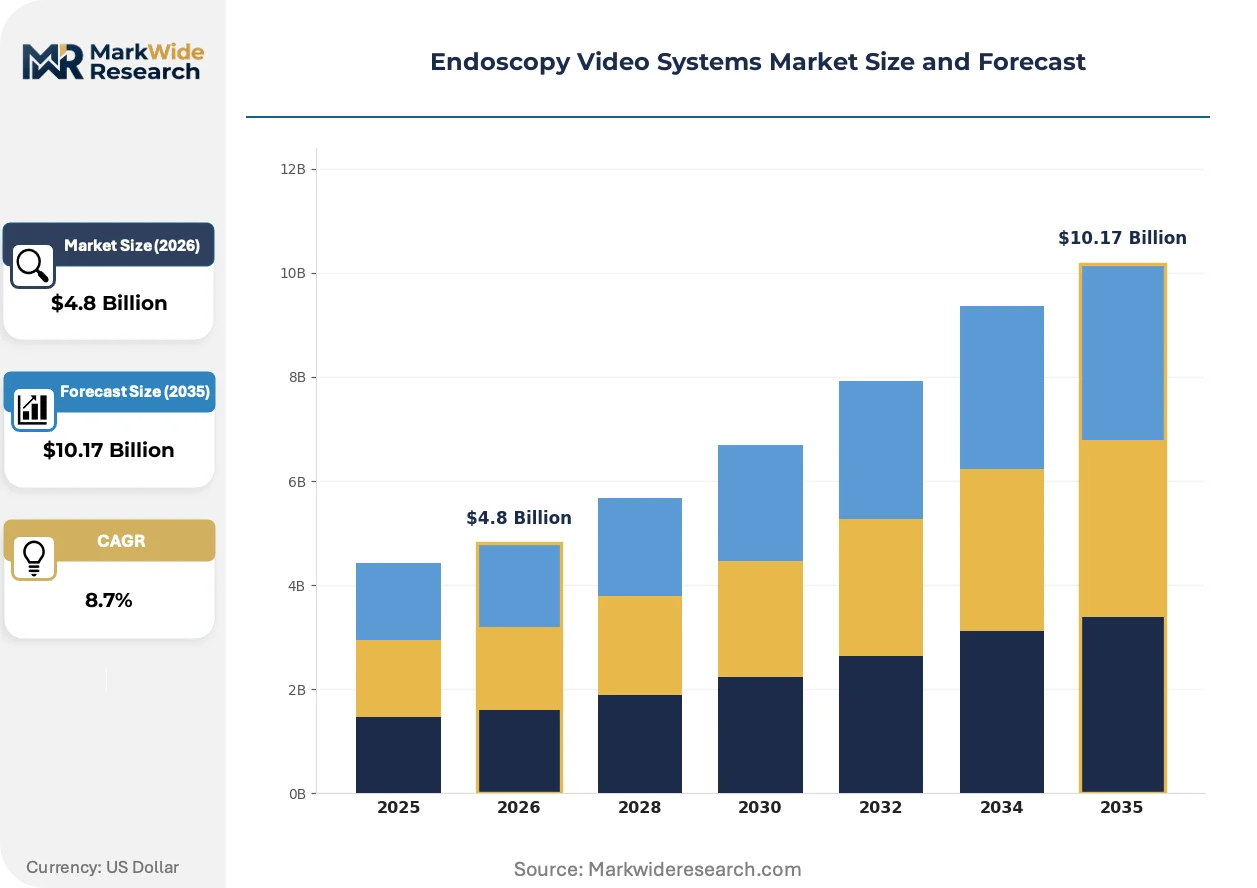
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Endoscopes, Image Processing Units, Light Sources, Accessories Application: Gastroenterology, Urology, Pulmonology, Surgical End User: Hospitals, Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories Technology: HD, 4K, Wireless, Digital |
| Companies Covered | Stryker, Medtronic, Olympus Corporation, Richard Wolf GmbH, Boston Scientific Corporation, FUJIFILM Holdings Corporation, Smith & Nephew plc, CONMED Corporation, KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopy Video Systems Market Emerging Trajectories
Three concurrent developments are restructuring how visualization platforms deliver value: sensor technology divergence, regulatory evidence escalation, and procurement model fragmentation across care settings.
CMOS-based 4K camera heads are bifurcating the product landscape between premium surgical suites demanding full-spectrum color fidelity and outpatient clinics prioritizing cost-optimized 1080p+ upscaling solutions. Ambulatory surgical centers in Germany and the United States are adopting mid-tier platforms with software-upgradeable resolution paths. This technology split is compressing manufacturer R&D budgets across incompatible sensor roadmaps while expanding addressable volume in price-sensitive segments.
EU MDR Article 10 post-market surveillance obligations are extending clinical follow-up requirements for reusable endoscopic video systems from two to five years. Manufacturers must now maintain vigilance databases tracking device-related adverse events across distributed hospital fleets. Gastroenterology platforms with longer field service histories are gaining competitive preference over newly cleared alternatives lacking longitudinal safety data.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, forcing manufacturers to compete for multi-year maintenance agreements on standalone commercial terms. United States health system consolidation is centralizing purchasing authority at integrated delivery network headquarters, displacing individual hospital vendor relationships. This concentration is visible most acutely in the southeastern United States, where regional IDNs now negotiate enterprise-wide video system standardization.
Endoscopy Video Systems Market Segmentation
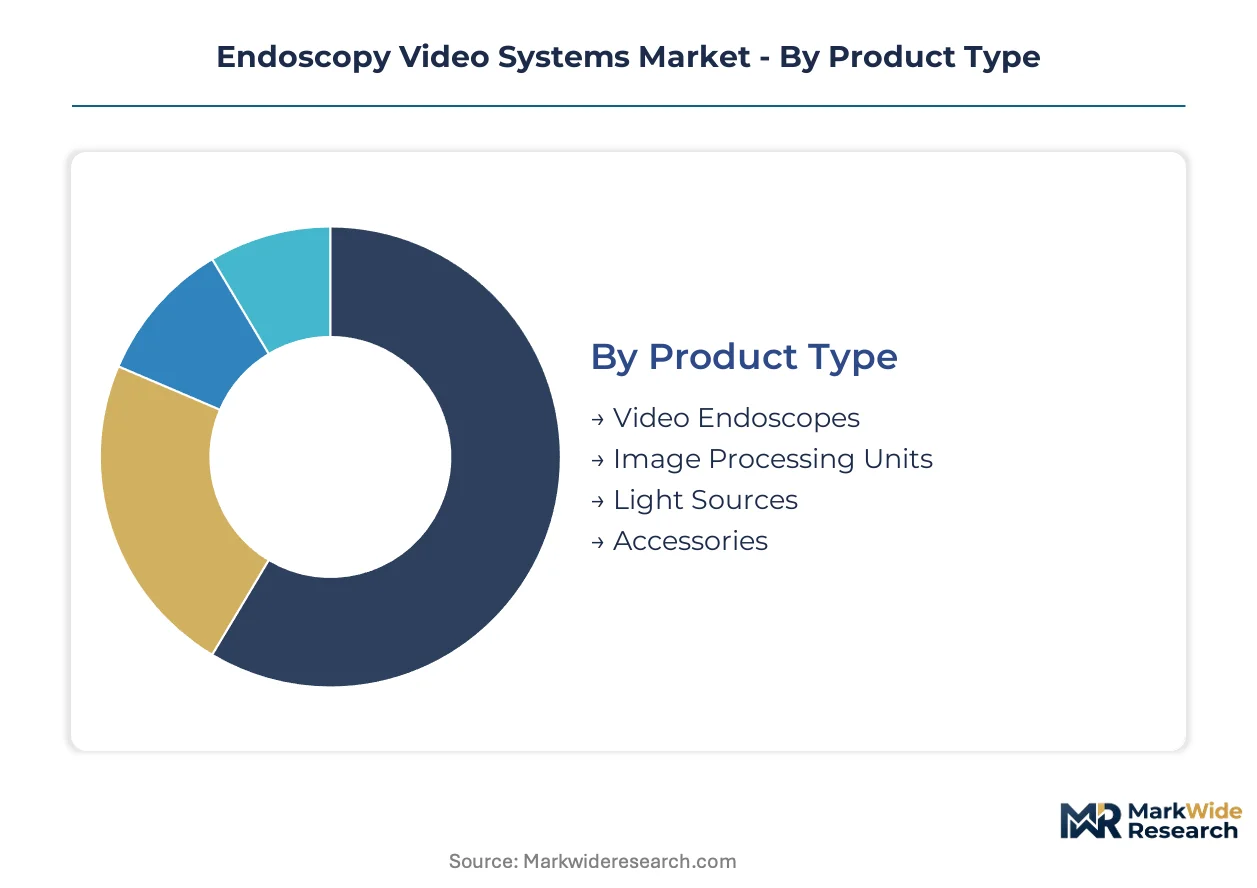
Endoscopy video systems fragment across four intersecting dimensions that determine pricing power, replacement cycles, and competitive defensibility. Product architecture and application severity drive capital intensity, while technology tier and care setting dictate procurement velocity and margin structure.
Product Type:
Disposable endoscope substitution pressures vary sharply by component durability, with semi-consumable accessories facing the steepest erosion from single-use alternatives.
- Video Endoscopes:Flexible insertion tubes housing CMOS or CCD sensors at distal tips, transmitting via fiber-optic bundles or digital chip-on-tip architectures. Demand concentrates in United States academic medical centers upgrading to 4K chip-on-tip platforms for mucosal surface characterization. Reusable sterilization validation costs now rival acquisition price over five-year lifecycles.
- Image Processing Units:Hardware-software platforms executing real-time noise reduction, color calibration, and AI-assisted polyp detection algorithms. German hospital procurement consortiums prioritize these units for software-upgradeable resolution paths that extend depreciation schedules. EU MDR post-market surveillance obligations favor established platforms with longitudinal safety databases.
- Light Sources:LED or xenon lamp assemblies delivering 5000K-6500K color temperature through fiber-optic light guides. United States ambulatory surgical centers favor compact LED units with reduced heat output for outpatient procedure suites.
- Accessories:Biopsy valves, irrigation tubing, and instrument channels subject to high replacement frequency. Single-use substitution advances fastest here as FDA premarket notification pathways for disposable equivalents shorten clearance timelines.
Image processing units anchor the volume base while wireless-enabled video endoscopes gain share at the steepest rate.
Application:
Procedure reimbursement coding creates divergent capital recovery timelines, with screening-dominant applications justifying faster technology refresh rates than interventional specialties.
- Gastroenterology:Esophagogastroduodenoscopy and colonoscopy platforms serving screening program volumes. United States CMS valuation shifts for in-office mucosal resection drive independent practice acquisition of visualization systems. Colorectal cancer screening mandates in India generate first-time demand in tier-2 cities.
- Urology:Cystoscopy and ureteroscopy systems for hematuria evaluation and stone management. Outpatient clinic adoption concentrates in Germany where regional integrated delivery networks standardize on single-vendor platforms.
- Pulmonology:Bronchoscopy platforms navigating the strongest single-use substitution headwinds. Disposable bronchoscopes capture diagnostic volumes that previously sustained reusable system utilization in United States hospitals.
- Surgical:Laparoscopic and arthroscopic visualization for minimally invasive operative procedures. Premium 4K color fidelity requirements concentrate demand in Japan metropolitan hospital systems with dedicated minimally invasive surgery departments.
Gastroenterology commands the largest installed base while surgical applications deliver the highest per-unit pricing.
End User:
Capital deployment flexibility separates institutional purchasers with centralized procurement authority from independent operators financing equipment through procedure revenue.
- Hospitals:Integrated delivery networks with enterprise-wide standardization mandates and dedicated biomedical engineering departments. United States southeastern regional IDNs negotiate multi-year maintenance agreements separate from capital purchases.
- Clinics:Independent gastroenterology practices responding to office-based procedure reimbursement incentives. Compact all-in-one video cart systems reduce sterilization logistics and enable same-day discharge protocols.
- Ambulatory Surgical Centers:High-volume outpatient facilities prioritizing rapid room turnover and cable-free configurations. Germany and United States facilities lead adoption of mid-tier platforms with upgradeable resolution paths.
- Diagnostic Laboratories:Pathology-focused operators with lower procedural throughput and extended equipment depreciation horizons. Cost-optimized 1080p solutions predominate in this tier.
Hospitals retain the deepest replacement budgets while ambulatory surgical centers expand their addressable share most aggressively.
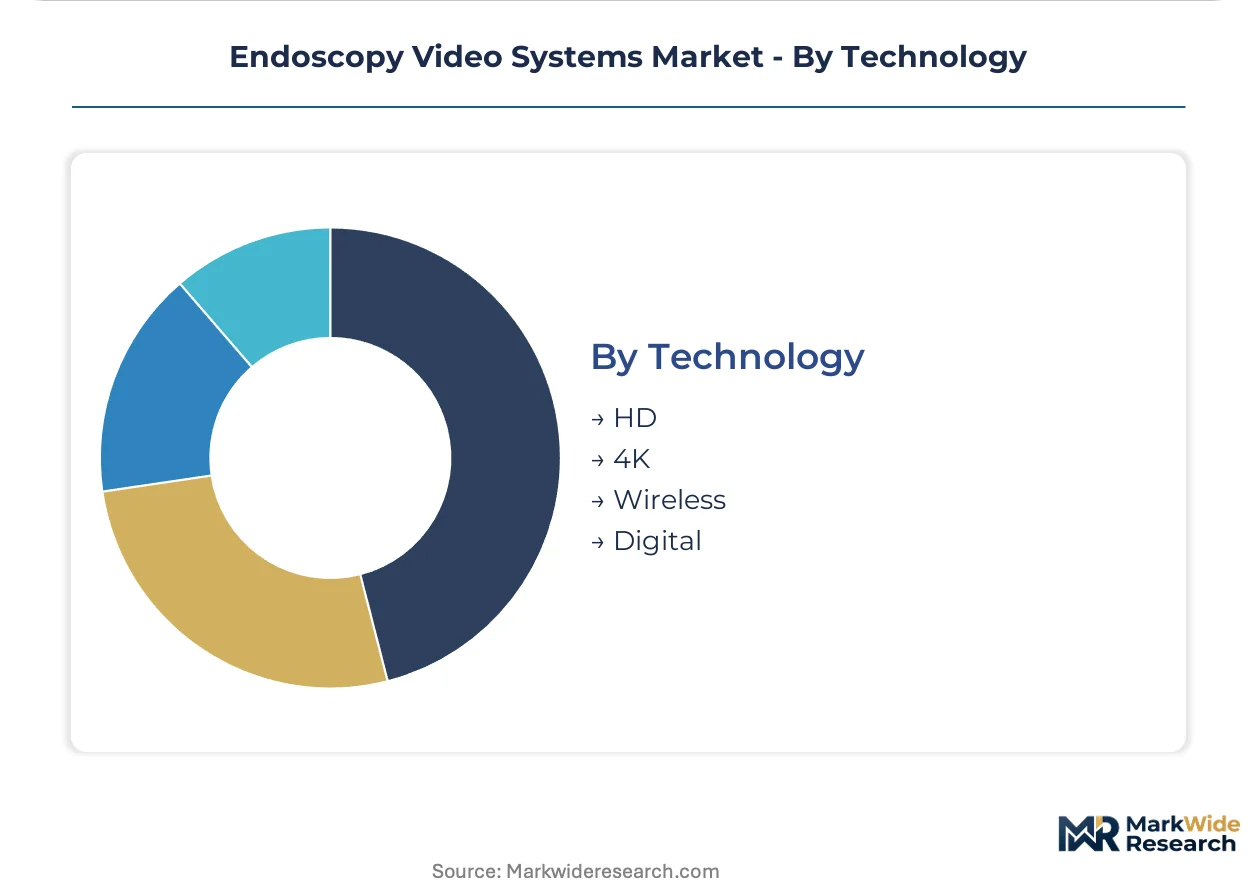
Technology:
Resolution specification tiers now bifurcate R&D investment across incompatible sensor roadmaps, compressing manufacturer margin defense across diverging price-performance requirements.
- HD:1080p systems serving cost-constrained diagnostic laboratories and secondary market clinics. India tier-3 city infrastructure expansion sustains residual demand for proven, serviceable platforms.
- 4K:Ultra-high-definition platforms with full-spectrum color fidelity for surgical suites and academic medical centers. Japanese and German hospital procurement prioritizes these units for mucosal surface characterization accuracy.
- Wireless:Cable-free camera-to-processor transmission eliminating operating room tripping hazards. United States high-volume endoscopy suites adopt these modules for rapid room turnover requirements.
- Digital:Native digital sensor pathways bypassing analog conversion artifacts. Software-upgradeable architectures appeal to ambulatory surgical centers seeking resolution scalability without full system replacement.
HD technology retains the broadest installed footprint while wireless transmission climbs the fastest among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies, with German and Japanese hospital procurement demanding full 4K color fidelity while Indian tier-2 cities and United States ambulatory centers prioritize cost-optimized 1080p platforms with upgradeable software paths.
United States
CMS reimbursement code expansions for office-based endoscopic mucosal resection drive independent gastroenterology practices toward compact all-in-one video cart acquisitions. FDA premarket notification requirements for reusable endoscopic accessories compress product development timelines for domestic manufacturers. Southeastern integrated delivery networks centralize enterprise-wide purchasing authority, displacing individual hospital vendor relationships.
Germany
EU MDR Article 10 post-market surveillance obligations extending clinical follow-up to five years favor established video platforms with longitudinal safety databases. KARL STORZ and Richard Wolf anchor a dense manufacturing cluster in the southwest where precision-engineered lens assembly expertise concentrates. Hospital procurement consortiums prioritize software-upgradeable image processing units that extend depreciation schedules.
Japan
Metropolitan hospital systems with dedicated minimally invasive surgery departments demand premium 4K color fidelity for laparoscopic visualization accuracy. PMDA regulatory pathways align with IEC 60601-1 electrical safety specifications governing design verification protocols. Tokyo and Osaka academic medical centers lead adoption of chip-on-tip platforms for mucosal surface characterization.
India
Government colorectal and gastric cancer screening programs generate first-time demand for portable video systems in tier-2 and tier-3 cities. CDSCO medical device registration requirements shape market access conditions for imported visualization platforms. Maharashtra and Karnataka diagnostic infrastructure expansion concentrates deployment of cost-optimized HD systems with proven serviceability.
China
NMPA medical device approval timelines influence product launch sequencing for domestic and multinational manufacturers. Government diagnostic infrastructure investments in Yangtze River Delta and Pearl River Delta metropolitan areas drive volume demand for mid-tier visualization platforms. Local CMOS sensor fabrication capabilities reduce import dependency for digital camera head components.
Endoscopy Video Systems Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the endoscopy video systems market. Premium-tier manufacturers concentrate in German and Japanese optical engineering clusters where precision lens assembly and full-spectrum color fidelity command pricing power. Mid-tier competitors compete on software-upgradeable resolution paths and compact form factors suited to ambulatory surgical center footprints. Dominant competitive moves include backward integration into CMOS sensor supply relationships and multi-year service contract unbundling from capital equipment sales.
Among diversified medical technology conglomerates, Stryker and Medtronic occupy positions spanning surgical visualization hardware and integrated operating room systems. Olympus Corporation exemplifies the optical heritage archetype, leveraging decades of gastrointestinal platform expertise. KARL STORZ SE & Co. KG represents the rigid endoscopy specialist model through captive supply of precision-engineered components. FUJIFILM Holdings Corporation sits within the imaging technology diversification archetype, applying photographic and digital processing heritage to medical visualization applications.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Olympus Corporation |
| Richard Wolf GmbH |
| Boston Scientific Corporation |
| FUJIFILM Holdings Corporation |
| Smith & Nephew plc |
| CONMED Corporation |
| KARL STORZ SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Eighteen-month order-to-delivery cycles for CMOS image sensors concentrate pricing power among East Asian foundries while forcing manufacturers to pre-position inventory against semiconductor allocation shocks. This lead-time compression binds hospital procurement timelines to sensor fabrication capacity, amplifying cost pass-through when wafer starts tighten.
Pricing Analysis
After-sales service contracts now generate sixty percent of lifetime value across installed video processor bases, shifting manufacturer focus from upfront equipment margin to multi-year maintenance annuity streams. Pricing stratifies across premium 4K surgical suites, mid-tier upgradeable ambulatory platforms, and economy HD systems for diagnostic laboratories. Cost compression in the mid-tier intensifies as German hospital consortiums unbundle service agreements and negotiate standalone commercial terms. Ambulatory surgical centers exhibit highest price sensitivity due to capital-constrained procurement, while Japanese academic medical centers absorb premium pricing for full-spectrum color fidelity.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Busan port corridors have elevated landed costs for German and Japanese precision optical components, compressing manufacturer margin on trans-Pacific deliveries. CMOS sensor fabrication concentrates in Taiwan, South Korea, and Japan, while LED light source assembly clusters in China and Malaysia. Supply chain risk centers on single-source vulnerability for 4K chip-on-tip architectures where Sony and OmniVision dominate sensor supply. Distribution runs through regional medical device distributors with hospital GPO contracting authority in the United States, direct sales forces in Germany, and government tender channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endoscopy video systems are approaching a platform-economics inflection where software-upgradeable image processing units decouple hardware refresh cycles from revenue realization, mirroring the interoperability shift that restructured diagnostic imaging equipment procurement.
For Market Incumbents: Secure captive supply agreements with CMOS foundries to insulate against allocation risk during semiconductor demand surges. Consolidate maintenance contract portfolios into enterprise-wide multi-year agreements before hospital IDN purchasing centralization displaces individual facility relationships. Single-use endoscope substitution in pulmonology and urology threatens reusable system utilization rates and demands defensive software companion development. For New Entrants and Emerging Players: Post-market surveillance database gaps among established platforms create white-space for compliant newcomers with clean longitudinal safety records under EU MDR Article 10 obligations. Target India's tier-2 and tier-3 diagnostic infrastructure expansion where first-time demand for portable HD systems outpaces incumbent service reach. Pursue nurse-assisted screening protocol enablement through AI-integrated polyp detection as the primary go-to-market wedge. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because software-upgradeable architectures extend depreciation schedules and deepen customer switching costs. Acquisition targets should display established FDA 510(k) clearance portfolios with unexploited EU MDR technical documentation. Watch wireless transmission module adoption rates in United States high-volume endoscopy suites as the signal for cable-free configuration standardization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Five-year post-market surveillance obligations favor platforms with existing vigilance databases over newly cleared alternatives. |
| CMOS Foundry Partnership | Backward integration into Sony or OmniVision supply relationships reduces allocation exposure during semiconductor demand cycles. |
| AI-Integrated Image Processing Development | Real-time polyp detection algorithms reduce physician cognitive load and enable nurse-assisted screening protocol expansion. |
| Wireless Transmission Module Launch | Cable-free camera-to-processor links eliminate operating room tripping hazards and support rapid room turnover requirements. |
| Hospital IDN Service Contract Unbundling | Standalone multi-year maintenance agreements compete on commercial terms separate from capital equipment purchases. |
Methodological Framework
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement coding updates, and hospital procurement records. Bottom-up triangulation across component-level sensor shipments and top-down reconciliation against capital equipment expenditure surveys ensures methodological consistency.
Sensitivity analysis across adoption rate assumptions for 4K resolution and wireless transmission modules shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, application severity, technology tier, and care setting procurement authority. CAGRs derive from fitted growth curves against historical replacement cycle data and reimbursement code expansion trajectories. Forecast inputs incorporate EU MDR compliance transition timelines and ambulatory surgical center facility expansion rates.
Material uncertainties — CMOS foundry allocation shocks, FDA premarket notification pathway revisions, and single-use endoscope substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about sterilization validation cost trajectories and hospital IDN consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Colonic Stents Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Global Endoscopes Market
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Gastroscopes Market
Endoscopy
South Korea Endoscopy Devices Market