
 Asia Pacific Endoscopy Devices Market | 2026-2036
Asia Pacific Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Endoscopy Devices Market Outlook
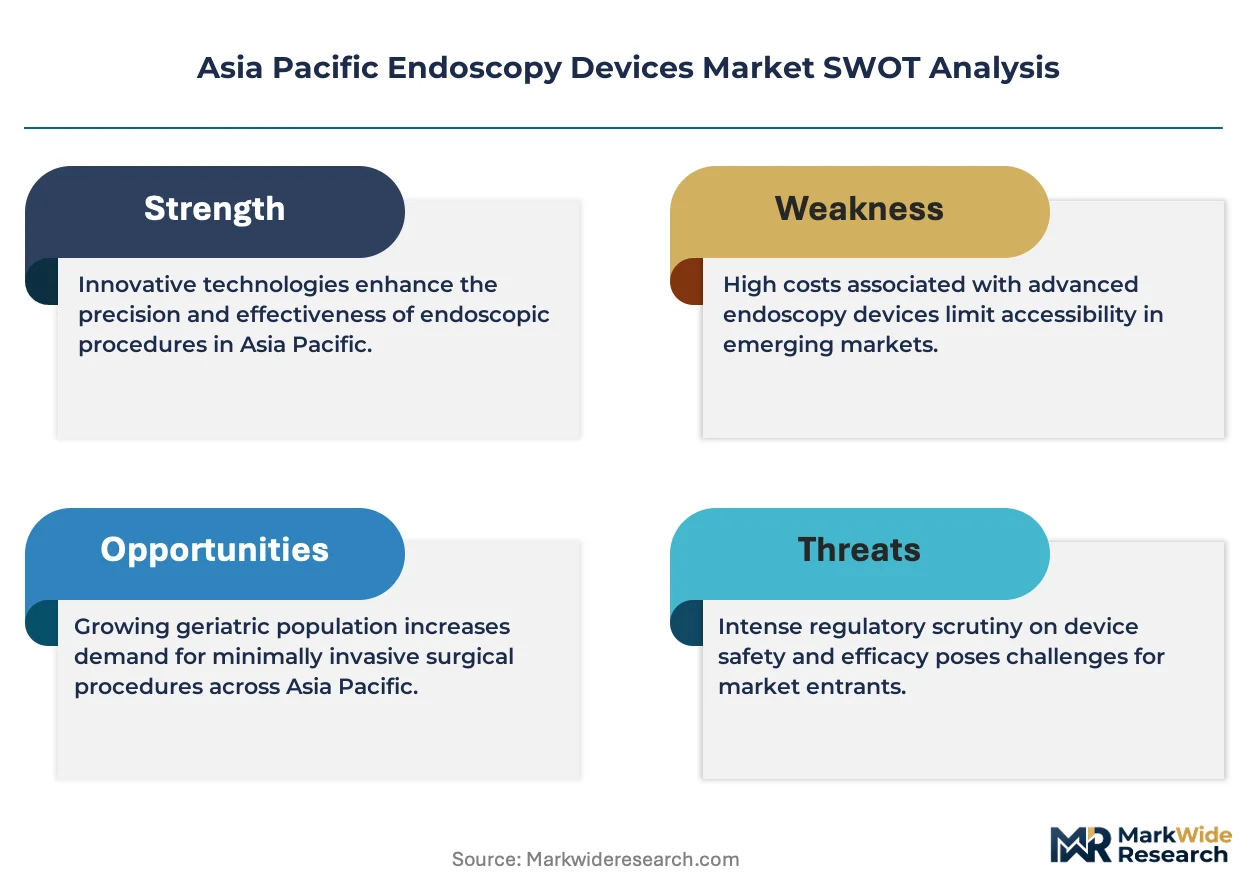
Multi-source component procurement is restructuring supply relationships across the Asia Pacific endoscopy devices sector. Olympus Corporation leverages its captive optical manufacturing base in Japan to control critical lens supply chains. Medtronic plc anchors its regional position through dedicated R&D facilities in Singapore and India. Boston Scientific Corporation competes on interventional gastroenterology platforms calibrated for Asia-specific procedural volumes.
Asia Pacific endoscopy devices comprise instrument systems incorporating rigid or flexible insertion tubes, fiber-optic or digital image transmission channels, and external illumination sources designed for direct visualization of internal body cavities during diagnostic or surgical intervention. Flexible endoscopes dominate procedure volume across gastroenterology applications where navigability through tortuous anatomy proves essential. Visualization systems capture expanding margin pools as hospitals upgrade from standard-definition fiber-optic platforms to 4K digital and 3D-capable video architectures. Accessories represent the fastest-growing product type as disposable channel valves, biopsy valves, and irrigation adapters shift toward single-use formats under intensified infection control protocols.
Japan's PMDA enforces stringent biocompatibility and electrical safety standards under revised Medical Device Single Audit Program alignments, while Australia's TGA mandates enhanced reprocessing documentation for reusable flexible endoscopes. China's NMPA accelerates review timelines for domestically manufactured digital endoscopy systems under updated innovation pathway designations. Stakeholders must monitor divergent national sterilization validation requirements and localize technical documentation to sustain market access across fragmented Asia Pacific regulatory environments.
Market Dynamics
Single-use endoscope economics are compressing reusable system margins across Asia Pacific surgical suites, forcing manufacturers to restructure service revenue models and sterilization-dependent aftermarket streams.
Growth Catalysts
- Japan's PMDA innovation pathway:Accelerated review timelines for domestically manufactured digital endoscopy systems reduce regulatory lag for novel visualization platforms entering clinical use.
- India's tier-1 hospital clusters:Capital investment in minimally invasive surgical infrastructure creates concentrated demand pockets for flexible gastroenterology systems and advanced imaging towers.
- China's provincial medical centers:Government procurement mandates favor domestically produced channel valves and biopsy accessories, stimulating local manufacturing scale-up.
Market Restraints
- Optical component supply concentration:Critical lens assemblies remain captive to Japanese and German precision optics suppliers, exposing downstream manufacturers to allocation risk.
- Australia's TGA reprocessing documentation:Enhanced sterilization validation requirements for reusable flexible endoscopes extend compliance timelines and elevate quality system costs.
- Capital intensity of 4K-3D visualization migration:Hospital budget cycles struggle to absorb simultaneous tower upgrades across multiple surgical departments.
Strategic Opportunities
- Southeast Asia surgical program expansion:Vietnamese and Indonesian hospitals are building de novo endoscopy capabilities without legacy reusable infrastructure, enabling direct single-use adoption.
- South Korea's MFDS AI-enabled device pathway:Regulatory framework for computer-aided detection in colonoscopy creates first-mover advantage for algorithm-integrated platforms.
- Disposable channel valve conversion:Infection control protocol intensification across Singapore and Hong Kong private hospital networks accelerates shift from reprocessable to single-use accessories.
Industry Challenges
- Biomedical technician specialization gap:Complex digital endoscope repair requires expertise in both optical engineering and software diagnostics that regional service networks lack.
- Cross-border sterilization standard harmonization:Divergent validation requirements between Japan's PMDA, Australia's TGA, and China's NMPA fragment technical documentation and quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Endoscopy Devices Market |
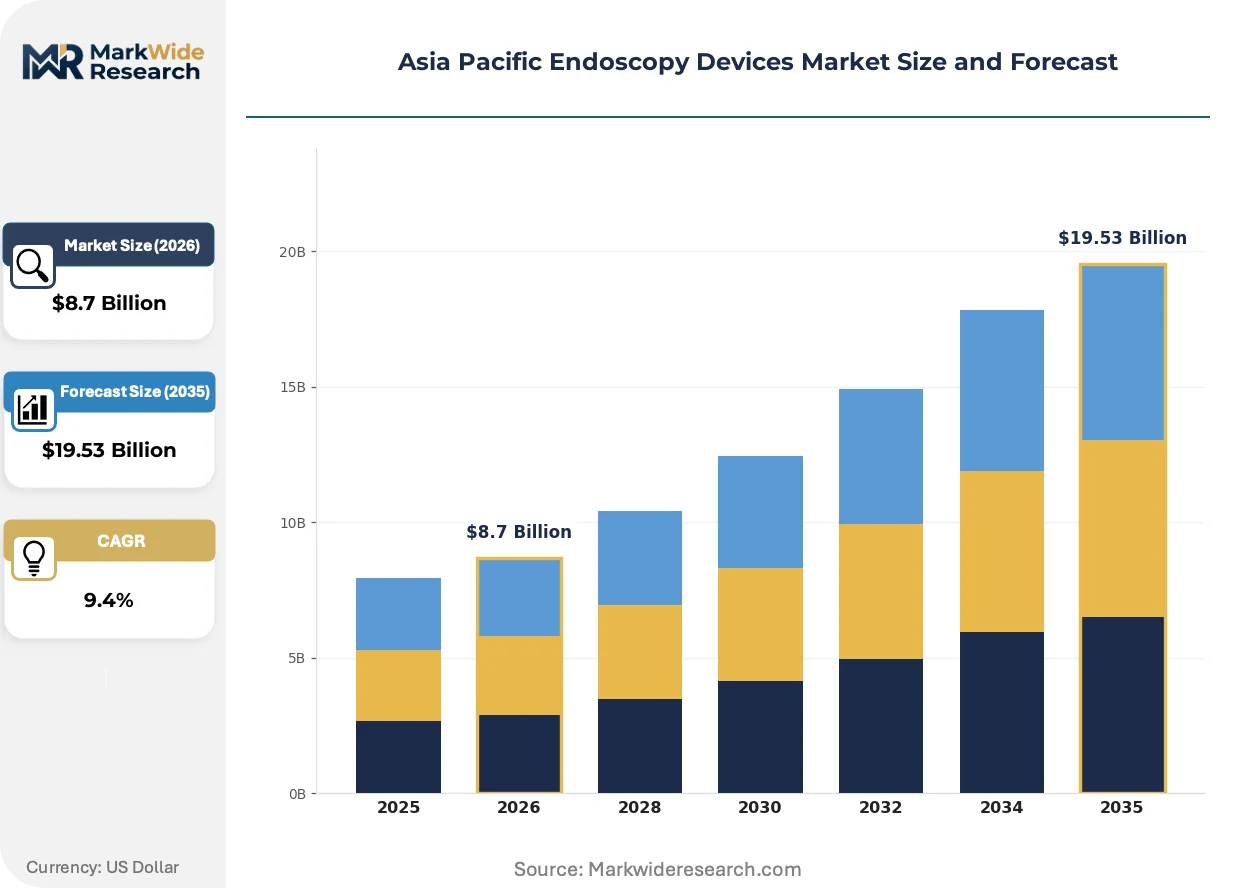
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Visualization Systems, Accessories Application: Gastroenterology, General Surgery, Urology, Pulmonology End User: Hospitals, Clinics, Research Institutions, Ambulatory Surgical Centers Technology: Digital, Fiber-Optic, Ultra-Sound, Video |
| Companies Covered | Stryker Corporation, Medtronic plc, Olympus Corporation, Merit Medical Systems Inc, HOYA Corporation, Fujifilm Holdings Corporation, Karl Storz SE & Co. KG, Smith & Nephew Plc, Boston Scientific Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Endoscopy Devices Market Strategic Shifts
Artificial intelligence inference engines and disposable component architectures are converging to redefine clinical workflow economics and capital deployment patterns across Asia Pacific endoscopy suites.
Digital image transmission systems are integrating on-chip computational capabilities that enable real-time polyp detection and automated documentation. Tertiary hospitals in Tokyo, Seoul, and Shanghai are deploying these platforms in high-volume screening programs where throughput optimization justifies premium acquisition costs. The technology is integrating diagnostic and procedural steps into unified workflow architectures that compress examination duration and reduce specialist time per case.
China's NMPA has established dedicated review queues for domestically developed AI-assisted endoscopy software under revised innovation pathway designations. Domestic manufacturers gain six-to-twelve month timeline advantages over imported equivalents, accelerating localization of algorithm training and validation datasets. Visualization system vendors are responding by partnering with Chinese imaging AI developers to embed region-specific detection models.
Hospital procurement committees across India and Southeast Asia are unbundling service contracts from capital equipment purchases, treating maintenance and upgrade pathways as separately negotiable spend categories. Third-party service providers and independent refurbished equipment dealers are capturing aftermarket revenue that manufacturers previously controlled through bundled offerings. This shift is most pronounced in India's corporate hospital chains where CFO oversight of medical technology spend has intensified post-pandemic liquidity constraints.
Asia Pacific Endoscopy Devices Market Segmentation
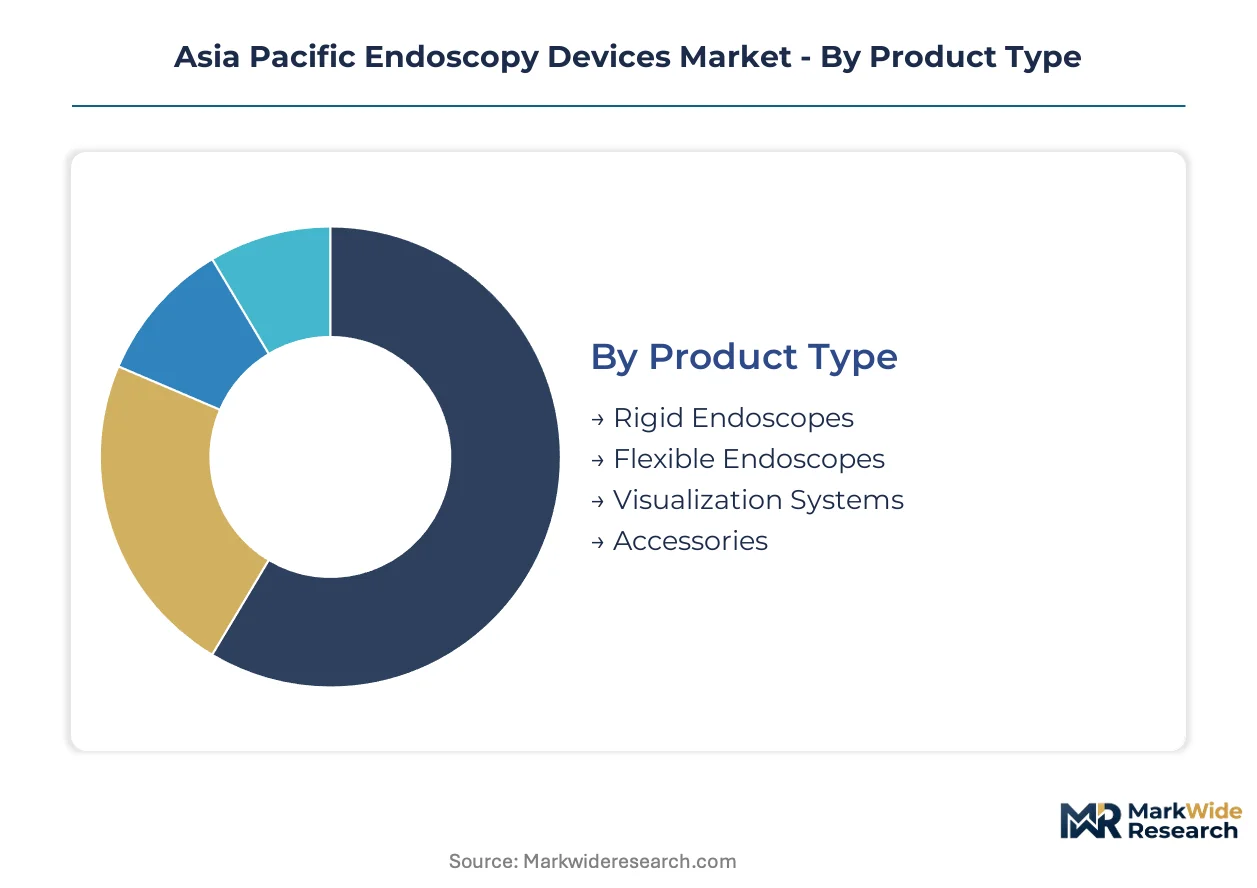
Endoscopy device segmentation in Asia Pacific reflects divergent procurement priorities across hospital tiers and regulatory environments. Procurement committees unbundle capital equipment from service contracts, reshaping how manufacturers position rigid versus flexible systems and reusable versus disposable accessories.
Product Type:
Cost tier separates academic medical centers investing in integrated visualization towers from district hospitals prioritizing functional insertion systems.
- Flexible Endoscopes:These systems incorporate steerable insertion tubes with articulating distal tips enabling navigation through tortuous gastrointestinal anatomy. Demand concentrates in India's tier-1 corporate hospital chains and China's provincial medical centers where gastroenterology screening volumes justify capital deployment. PMDA sterilization validation requirements in Japan are accelerating single-use flexible scope adoption in high-turnover outpatient settings.
- Visualization Systems:4K digital and 3D-capable video processors capture expanding margin pools as hospitals upgrade from fiber-optic platforms. Tertiary hospitals in Seoul, Tokyo, and Shanghai are deploying AI-integrated towers that embed real-time polyp detection algorithms. NMPA innovation pathways favor domestically manufactured digital processors, compressing timeline advantages for Chinese vendors.
- Rigid Endoscopes:Laparoscopic and arthroscopic systems serve orthopedic and general surgery applications with fixed optical pathways.
- Accessories:Disposable channel valves, biopsy valves, and irrigation adapters are shifting toward single-use formats under intensified infection control protocols across Singapore and Hong Kong private networks.
Flexible endoscopes lead volumes today; visualization systems are gaining share fastest.
Application:
Procedure volume and reimbursement calibration determine technology investment intensity across surgical specialties.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy dominate procedure counts across Asia Pacific screening programs. South Korea's MFDS AI-enabled device pathway is accelerating computer-aided detection integration in high-volume colonoscopy suites. MFDS regulatory clarity creates first-mover positioning for algorithm-integrated platforms targeting national cancer screening mandates.
- General Surgery:Laparoscopic cholecystectomy and hernia repair drive rigid endoscope utilization in minimally invasive surgical programs. Vietnamese and Indonesian hospitals are building de novo laparoscopy capabilities without legacy reusable infrastructure, enabling direct single-use adoption.
- Urology:Cystoscopy and ureteroscopy procedures require specialized flexible or semi-rigid insertion systems.
- Pulmonology:Bronchoscopy applications serve interventional lung diagnostics with dedicated flexible scope configurations.
Gastroenterology commands the largest installed base; general surgery shows the steepest expansion trajectory.
End User:
Capital intensity and service network reach segment buyers by infrastructure sophistication and procurement autonomy.
- Hospitals:Tertiary and secondary institutions concentrate demand for integrated endoscopy towers with dedicated maintenance contracts. Australia's TGA reprocessing documentation requirements extend compliance timelines and elevate quality system costs for reusable flexible scope programs. Hospital procurement committees are unbundling service contracts from equipment purchases, treating maintenance as separately negotiable spend categories.
- Ambulatory Surgical Centers:Freestanding facilities prioritize compact, portable systems with rapid turnover capabilities. India's corporate hospital chains are spinning off endoscopy-focused day surgery units where CFO oversight of medical technology spend has intensified post-pandemic liquidity constraints.
- Clinics:Outpatient settings favor cost-optimized fiber-optic platforms for diagnostic procedures.
- Research Institutions:Academic medical centers procure specialized systems for protocol development and training applications.
Hospitals retain dominant purchasing power; ambulatory surgical centers are expanding most quickly.
Technology:
Maturity curve and upgrade cycle timing separate early digital adopters from fiber-optic holdouts.
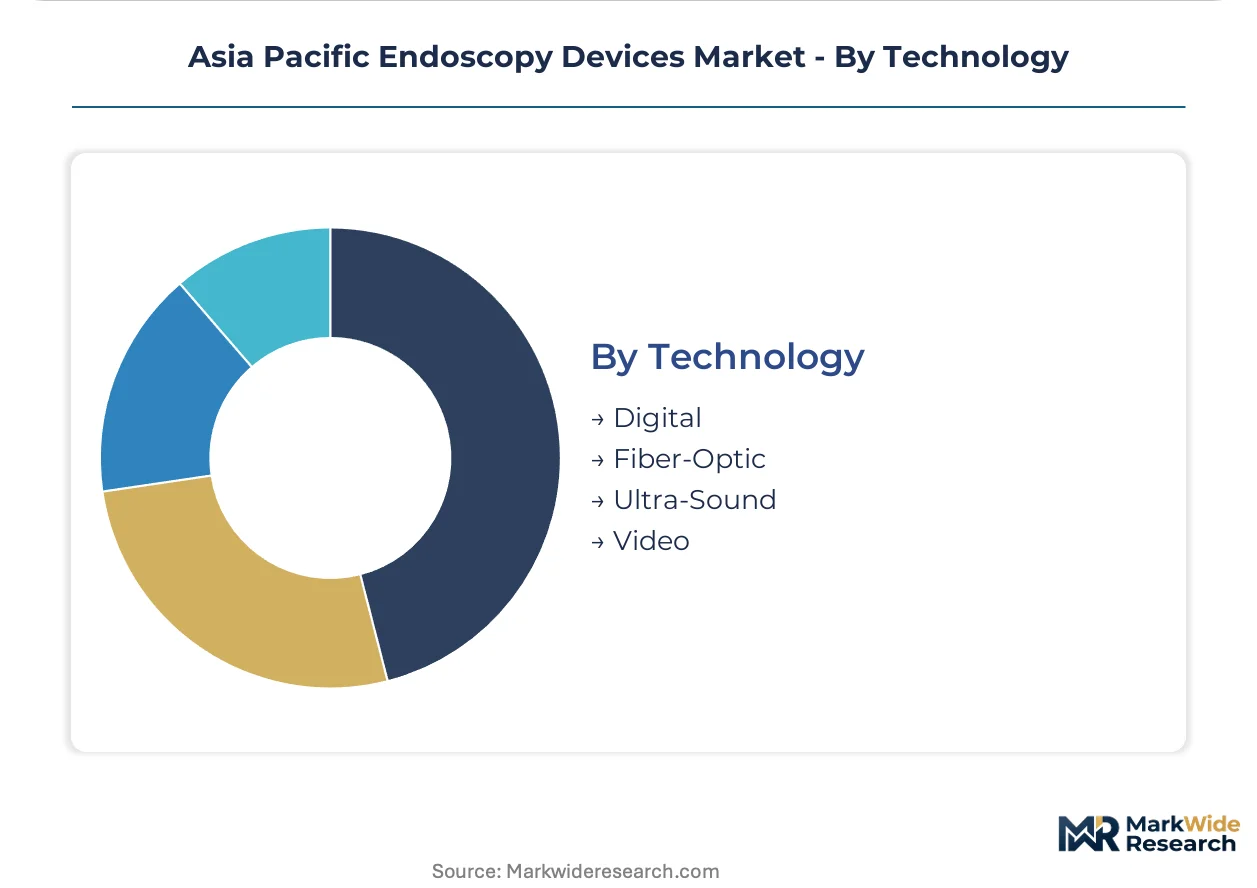
- Digital:CMOS and CCD sensor-based systems with on-chip computational capabilities enable real-time image enhancement and automated documentation. China's NMPA has established dedicated review queues for domestically developed AI-assisted endoscopy software, accelerating localization of algorithm training and validation datasets.
- Video:Standard-definition and high-definition digital transmission architectures serve mid-tier hospital budgets. Domestic Chinese manufacturers gain six-to-twelve month timeline advantages over imported equivalents under revised innovation pathway designations.
- Fiber-Optic:Traditional glass fiber bundles persist in cost-sensitive district hospital deployments.
- Ultra-Sound:Endoscopic ultrasound systems integrate therapeutic and diagnostic capabilities for specialized interventional procedures.
Digital platforms anchor new installations; video technology maintains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kanto region anchors Asia Pacific endoscopy manufacturing through precision optics clusters in Tokyo and Saitama. National screening programs and regulatory innovation pathways concentrate demand across East Asian metropolitan hospital networks.
China
Provincial medical centers in Jiangsu and Guangdong drive digital endoscope procurement under government localization mandates. NMPA innovation pathways compress review timelines for domestically manufactured visualization systems by six-to-twelve months against imported equivalents. Yangtze River Delta manufacturers scale production of single-use channel valves and biopsy accessories for regional hospital networks.
Japan
PMDA sterilization validation requirements accelerate single-use flexible scope adoption in Tokyo and Osaka outpatient clinics. METI innovation pathways support AI-integrated colonoscopy platforms entering national cancer screening programs. Nagoya precision optics suppliers maintain captive lens assembly capacity for integrated device manufacturers.
India
Tier-1 corporate hospital chains in Mumbai and Delhi-NCR unbundle service contracts from capital equipment purchases. CDSCO regulatory alignment with international standards enables faster clearance for refurbished visualization towers. Karnataka's medical technology corridor attracts contract manufacturing for flexible insertion tube components.
South Korea
MFDS AI-enabled device pathways create regulatory clarity for computer-aided detection in Seoul and Busan colonoscopy suites. National cancer screening mandates justify premium acquisition costs for algorithm-integrated visualization platforms. Daegu-Gyeongbuk medical device clusters specialize in CMOS sensor integration for digital endoscopy processors.
Australia
TGA enhanced reprocessing documentation requirements extend compliance timelines for reusable flexible scope programs in Sydney and Melbourne hospital networks. Private health fund procurement criteria favor sterilization validation transparency in ambulatory surgical center equipment selection. Queensland regional hospitals prioritize portable fiber-optic systems for remote diagnostic outreach.
Asia Pacific Endoscopy Devices Market Competitive Environment
Global majors compete with regional champions across visualization technology and infection control product lines. Market structure consolidates around three tiers: integrated system vendors controlling optical supply chains, interventional platform specialists, and disposable component fabricators. Dominant competitive moves include backward integration into precision lens manufacturing and strategic partnerships with domestic AI developers in regulated Asian markets.
Within the integrated system tier, Olympus Corporation and Fujifilm Holdings Corporation exemplify captive optical manufacturing strategies that insulate critical component supply from allocation volatility. Medtronic plc anchors the interventional platform segment through regional R&D infrastructure in Singapore and India. Boston Scientific Corporation occupies a position calibrated to Asia-specific procedural volumes in gastroenterology applications. Stryker Corporation, Karl Storz SE & Co. KG, and Smith & Nephew Plc represent diversified surgical technology portfolios spanning rigid and flexible endoscopy modalities across hospital procurement categories.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic plc |
| Olympus Corporation |
| Merit Medical Systems Inc |
| HOYA Corporation |
| Fujifilm Holdings Corporation |
| Karl Storz SE & Co. KG |
| Smith & Nephew Plc |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Optical glass and CMOS sensor price indices cascade through Asia Pacific endoscopy device supply chains, compressing margins for visualization system assemblers while concentrating pricing power with Japanese precision optics suppliers and Korean sensor fabricators. Hospital procurement committees exploit this concentration to demand unbundled service contracts that separate capital equipment from maintenance spend.
Pricing Analysis
Input-cost pass-through from captive lens suppliers drives three-tier pricing structure across premium, standard, and economy levels in visualization systems. Price differentiation hinges on certification grade under PMDA and NMPA pathways plus volume scale in tier-1 hospital cluster tenders. Pricing pressure stems from single-use endoscope economics displacing reusable system margins. Corporate hospital chains in India exhibit highest price sensitivity; tertiary academic centers in Japan and South Korea show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Japan's PMDA and Australia's TGA force manufacturers to qualify secondary suppliers for critical lens assemblies and CMOS sensors. Geographic supply concentration centers on Japan for precision optics, South Korea for image sensors, and China for disposable channel valves and biopsy accessories. Raw material dependencies include rare-earth doped glass, silicon wafers, and medical-grade polymers. Single-source vulnerability in Japanese optical component supply creates allocation risk during demand surges. Distribution runs through regional device distributors and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific endoscopy devices represent a late-cycle quality story as hospital procurement shifts toward AI-integrated visualization towers with validated sterilization documentation. Premium specifications now dominate capital committee evaluations over bare-bones functional systems.
For Market Incumbents: Anticipate margin compression from single-use scope conversion by deepening backward integration into precision lens manufacturing and expanding captive service networks across India's tier-1 clusters. Lock in multi-year sterilization validation contracts with Australian and Japanese regulators before compliance timelines extend further. For New Entrants and Emerging Players: Launch via refurbished equipment channels targeting India's corporate hospital chains where CFO oversight has unbundled maintenance from capital purchases. White-space targets include disposable channel valves for Southeast Asian de novo surgical programs and AI-integrated towers under South Korea's MFDS pathway. The most penetrable segment remains ambulatory surgical centers in Vietnam and Indonesia lacking legacy reusable infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic Chinese visualization system vendors holding NMPA innovation pathway advantages and six-to-twelve month regulatory lead times over imported equivalents. Long-term viability over the next decade hinges on algorithm training dataset localization and hospital system partnership density. Watch for MFDS AI-enabled device approvals in Seoul and Busan as inflection indicators for regional algorithm-integrated platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures preferred vendor status in India's unbundled procurement environment where CFOs negotiate maintenance separately. |
| Software Companion Development | Enables real-time polyp detection algorithms under South Korea's MFDS AI-enabled device pathway for colonoscopy suites. |
| CE Marking Pathway | Facilitates entry into Australian private health fund networks with sterilization validation transparency requirements. |
| Reimbursement Strategy | Aligns AI-integrated tower pricing with national cancer screening mandates in Tokyo and Seoul metropolitan networks. |
| Backward Integration into Optics | Insulates margin position from Japanese and German precision lens supplier allocation volatility. |
Study Parameters
Coverage spans East Asia, South Asia, Southeast Asia, and Oceania, with primary inputs from each regional cluster combining interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Secondary validation draws from PMDA and NMPA device registration databases, hospital procurement records, TGA sterilization guidance documents, and MFDS AI-enabled device pathway filings. Bottom-up installation base modeling triangulates against top-down market size estimates from trade flow analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application specialty, end-user facility tier, and technology platform maturity. CAGRs derive from installed base turnover rates, upgrade cycle timing, and replacement demand elasticities. Industry-specific forecast inputs incorporate NMPA innovation pathway approval velocity and single-use conversion rates in infection control-intensive hospital networks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden sterilization standard harmonization or optical component supply disruption scenarios. Deviation in PMDA or MFDS regulatory timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Video Laryngoscope Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
AI in Endoscopy Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Nasopharyngoscope Market