
 Endobronchial Valve Market | 2026-2036
Endobronchial Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Endobronchial Valve Market Intelligence
The European Union's Medical Device Regulation (MDR) is consolidating the competitive landscape by increasing clinical evidence requirements for market access. Pulmonx Corporation leverages its extensive clinical data from landmark trials to sustain a leading position. Olympus Corporation specializes in the bronchoscopic delivery systems required for valve placement. Spiration Inc. competes with its distinct umbrella-style valve design and targeted regional presence.
An endobronchial valve is a small, one-way implant placed in the airways via a bronchoscope. Typically constructed from biocompatible silicone or a nitinol frame, it functions to occlude a specific lung lobe or segment. This procedure redirects air to healthier lung portions in patients with severe emphysema. The therapy area is dominated by applications in Chronic Obstructive Pulmonary Disease, while specialty respiratory hospitals and pulmonology clinics are the primary end-user settings for these procedures.
Device approval and market access are governed by stringent regulatory bodies such as the US FDA, Japan's PMDA, and authorities overseeing CE marking in Europe. These agencies mandate comprehensive clinical trials to prove safety and efficacy before granting commercial approval. Consequently, navigating diverse national reimbursement policies remains a critical hurdle for manufacturers seeking broader market penetration.
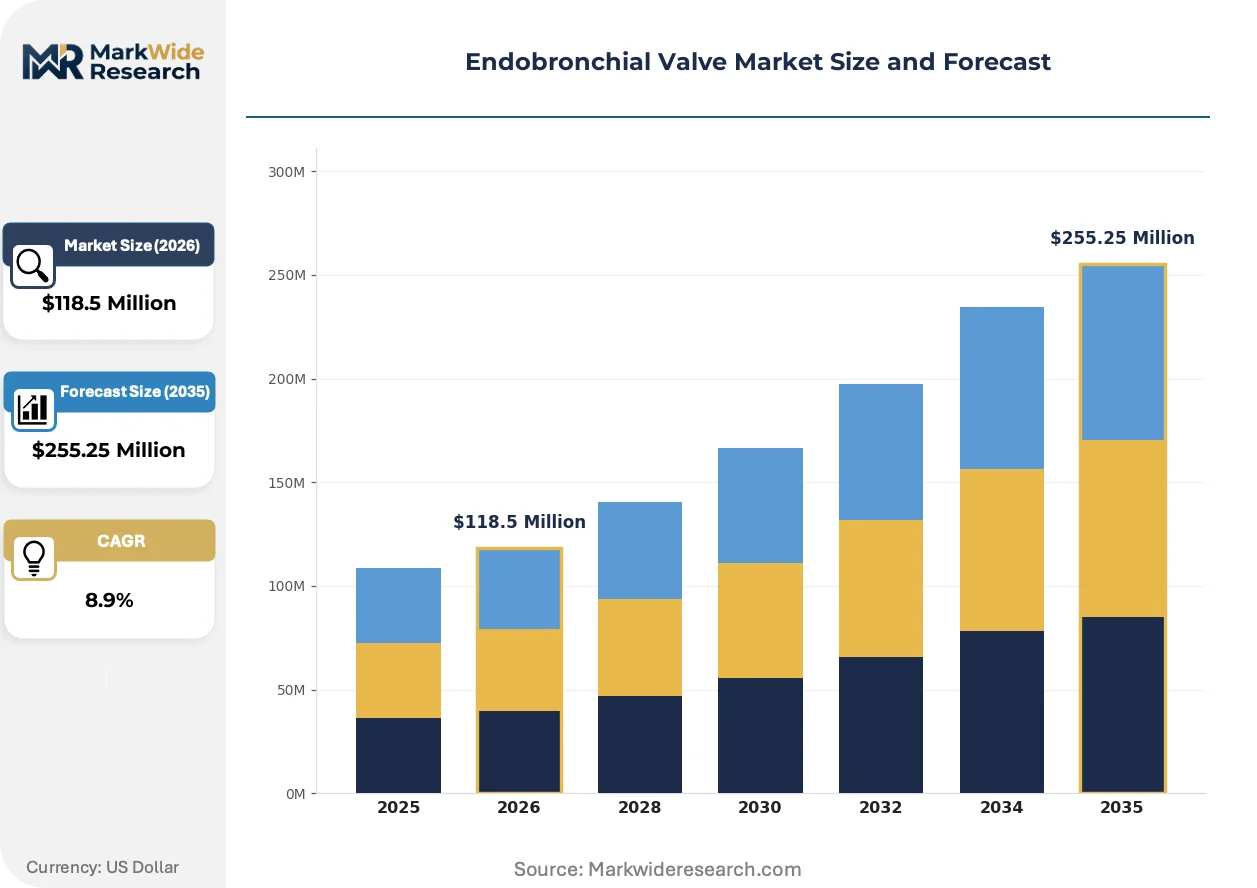
Market Dynamics
The market's competitive structure is being reshaped by heightened regulatory demands for extensive clinical evidence. Frameworks like the European Union's Medical Device Regulation are favoring incumbents with established, long-term trial data, creating significant barriers for new entrants.
Growth Catalysts
- FDA Breakthrough Devices Program:This US program expedites review for novel valve technologies, incentivizing faster innovation and market access for severe emphysema treatments.
- Specialty Hospital Concentration:High procedure volumes within specialized respiratory hospitals in Germany create a skilled end-user base, supporting consistent therapy adoption.
- Biomaterial Advancements:Improved biocompatibility of nitinol and silicone enhances device safety, expanding the addressable patient population for implantation.
Market Restraints
- High Procedure Cost:The expense of the valve implant and bronchoscopic placement limits patient access in healthcare systems with restrictive reimbursement policies.
- Strict Patient Selection:Efficacy depends on the absence of collateral ventilation, a strict anatomical prerequisite that excludes many potential emphysema patients.
- Reimbursement Fragmentation:Inconsistent national reimbursement policies across EU member states create significant administrative hurdles for manufacturers seeking market access.
Strategic Opportunities
- Asia-Pacific Market Entry:Underpenetration in Japan and Australia offers growth potential, driven by aging populations and a high prevalence of chronic respiratory diseases.
- Expanded Clinical Indications:Pursuing regulatory approval for new applications, such as managing persistent air leaks post-surgery, can open new revenue streams.
- AI-Powered Procedure Planning:Integrating artificial intelligence with imaging can optimize patient selection and valve placement, improving clinical outcomes and treatment efficacy.
Industry Challenges
- Interventional Pulmonologist Scarcity:A shortage of physicians trained in bronchoscopic lung volume reduction restricts procedure availability, particularly in non-specialty centers and rural areas.
- Lengthy Regulatory Pathways:The extensive clinical trial data required by the US FDA and for CE marking under the MDR creates long and expensive development cycles for new devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endobronchial Valve Market |
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $255.25 Million |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-way Valve, Biocompatible Valve, Silicone Valve, Nickel Titanium Valve Therapy Area: Chronic Obstructive Pulmonary Disease, Emphysema, Bronchopleural Fistula, Persistent Air Leak End User: Pulmonology Clinics, Medical Research Institutes, Diagnostic Centers, Specialty Respiratory Hospitals Deployment: Inpatient Settings, Outpatient Facilities, Home Healthcare, Ambulatory Surgical Centers |
| Companies Covered | Pulmonx Corporation, Olympus Corporation, Spiration Inc, Boston Scientific, Medtronic, Cook Medical, Teleflex, Veran Medical Technologies, Interventional Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endobronchial Valve Market Strategic Shifts & Innovations
A focus on procedural refinement and patient-specific solutions is defining the next wave of innovation. Device development is shifting from a one-size-fits-all approach toward customized implants and data-driven placement strategies to enhance therapeutic outcomes.
Next-generation valves incorporate bioresorbable materials and sensor technologies to monitor lung function post-implantation. Interventional pulmonology departments in leading academic medical centers are pioneering the use of these smart devices in clinical trials. This integration of real-time data feedback with the physical implant is rewriting the post-procedural patient management paradigm, shifting it from reactive to proactive care.
Japan's PMDA is aligning its device evidence requirements with the FDA and European authorities to streamline global development. This harmonization reduces the need for duplicative, country-specific clinical trials, lowering market entry costs. Consequently, valve manufacturers are accelerating entry strategies for Japan, a country with a significant and underserved COPD patient population.
Hospitals are forming multi-disciplinary lung health committees, including pulmonologists and surgeons, for collective decisions on treatment technologies. This committee-based model displaces single-physician preference, demanding more comprehensive clinical and economic evidence from manufacturers. This shift is most visible in large US hospital networks and Germany's university hospital system.
Endobronchial Valve Market Segmentation
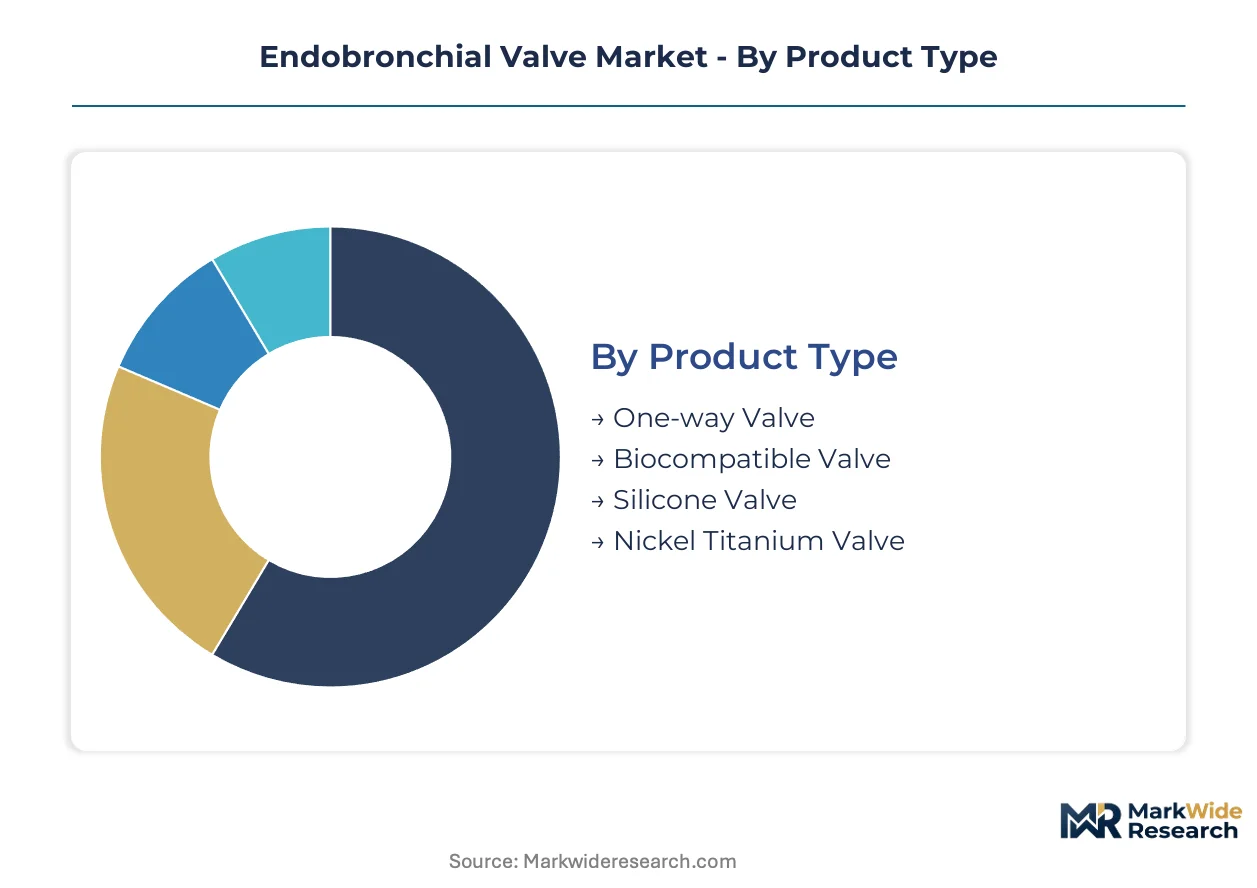
The Endobronchial Valve Market segmentation provides a granular view of product types, therapy applications, end-user settings, and deployment models. This detailed breakdown helps manufacturers align product development with specific clinical needs and regulatory pathways. Understanding these distinct segments is crucial for strategic market penetration and resource allocation.
Product Type:
Product types within the endobronchial valve market are differentiated by their design, material composition, and functional principles, each facing distinct certification burdens. Devices requiring novel material approval, such as certain biocompatible alloys, often undergo more rigorous scrutiny from the US FDA and European authorities.
- One-way Valve:This device permits air to exit a diseased lung segment during exhalation but prevents air from re-entering during inhalation. Its design is fundamental to lung volume reduction, with demand concentrating in specialty respiratory hospitals across Germany for severe emphysema treatment.
- Nickel Titanium Valve:Constructed from nitinol, these valves offer excellent shape memory and biocompatibility, providing a durable and flexible implant solution. Their advanced material properties expand the addressable patient population, particularly in the United States, driving innovation in device performance.
- Biocompatible Valve:These valves are engineered from materials that minimize adverse reactions with human tissue, ensuring long-term patient safety and integration. Material selection is a critical factor for regulatory approval by Japan's PMDA.
- Silicone Valve:Made from medical-grade silicone, these valves are known for their flexibility and ease of placement, often used in initial treatment phases. The material choice simplifies manufacturing processes for many producers.
One-way Valve sits at the top of the volume ranking, with Nickel Titanium Valve climbing the fastest.
Therapy Area:
The therapy area segmentation reflects the diverse clinical conditions treated by endobronchial valves, each presenting unique challenges in patient selection and procedural efficacy. Regulatory bodies like the US FDA require specific clinical trial endpoints tailored to each indication, impacting market access.
- Chronic Obstructive Pulmonary Disease:This is the primary indication for endobronchial valve placement, particularly for patients with severe emphysema. The therapy aims to improve lung function and reduce breathlessness, with strong adoption in major European markets.
- Persistent Air Leak:Valves are increasingly used to manage prolonged air leaks following lung surgery or trauma, offering a less invasive alternative to reoperation. This application presents a significant opportunity for market expansion and new revenue streams.
- Emphysema:A sub-category of COPD, emphysema involves damage to the air sacs in the lungs, leading to air trapping. Endobronchial valves specifically target hyperinflated lobes in these patients.
- Bronchopleural Fistula:This condition involves an abnormal connection between the bronchial tree and the pleural space, which valves can help seal. Its treatment requires highly specialized interventional pulmonology expertise.
Chronic Obstructive Pulmonary Disease dominates the application landscape, while Persistent Air Leak shows strong market penetration gains.
End User:
End-user segmentation highlights the varied healthcare settings where endobronchial valve procedures are performed, each with distinct infrastructure and staffing requirements. The concentration of highly skilled interventional pulmonologists in certain facilities influences procedure volumes.
- Specialty Respiratory Hospitals:These institutions possess dedicated pulmonology departments, advanced imaging capabilities, and experienced medical teams, making them primary centers for complex endobronchial valve procedures. They drive high procedure volumes in countries like Germany.
- Pulmonology Clinics:Offering diagnostic services and follow-up care, these clinics often refer patients to larger centers for valve implantation. They play a critical role in patient identification and post-procedure management across the United States.
- Medical Research Institutes:These facilities are instrumental in conducting clinical trials for new valve technologies and expanded indications, contributing to evidence generation. Their work is vital for securing CE marking in Europe.
- Diagnostic Centers:Focused on identifying lung conditions, these centers perform crucial pre-procedure assessments like high-resolution CT scans. They support the patient selection process for endobronchial valve therapy.
Specialty Respiratory Hospitals command the largest share of procedures, with Pulmonology Clinics demonstrating consistent referral growth.
Deployment:
Deployment segmentation categorizes where endobronchial valve procedures are performed, reflecting access to specialized equipment and medical personnel. Different settings face varying reimbursement policies and logistical challenges.
- Inpatient Settings:Most endobronchial valve implantations currently occur in hospital inpatient settings due to the need for post-procedure monitoring and potential complications. These settings offer comprehensive medical support.
- Outpatient Facilities:As procedural techniques improve and patient selection becomes more refined, a shift towards outpatient valve placement is emerging, offering cost efficiencies. This trend is notable in certain US healthcare networks.
- Ambulatory Surgical Centers:These centers provide a cost-effective alternative for less complex procedures, potentially expanding access to endobronchial valve therapy. Regulatory approvals for such procedures are being explored.
- Home Healthcare:Post-procedure follow-up and long-term monitoring might involve home healthcare services, particularly for patient education and symptom management. This segment supports continuum of care.
Inpatient Settings remain the dominant deployment model, while Outpatient Facilities are gaining momentum for select patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A critical concentration of highly skilled interventional pulmonologists anchors the global endobronchial valve market. These specialized medical professionals drive consistent therapy adoption and procedural volumes across key geographies. Their expertise is crucial for the complex placement and management of these advanced devices, influencing market growth and technology integration in major healthcare systems.
United States
The United States demonstrates strong demand for endobronchial valves due to a significant COPD patient population and advanced healthcare infrastructure. The US FDA's Breakthrough Devices Program expedites market access for novel valve technologies, fostering innovation. Large US hospital networks increasingly form multidisciplinary lung health committees, influencing technology adoption and demanding comprehensive clinical evidence from manufacturers.
Germany
Germany is a central European market, driven by a highly skilled end-user base and consistent therapy adoption within specialized respiratory hospitals. The European Union's Medical Device Regulation (MDR) sets stringent requirements for market access, favoring devices with extensive clinical data. Germany's university hospital system, particularly in major cities, actively utilizes committee-based treatment decisions for endobronchial valve technologies.
Japan
Japan offers significant growth potential for endobronchial valves, driven by its aging population and a substantial COPD patient demographic. The PMDA is harmonizing its device evidence requirements with global authorities, streamlining market entry for manufacturers. Interventional pulmonology departments in leading academic medical centers are pioneering the use of smart devices in clinical trials.
Australia
Australia presents an underpenetrated market for endobronchial valves, with an aging population contributing to a rising prevalence of chronic respiratory diseases. The Therapeutic Goods Administration (TGA) regulates medical device approvals, requiring robust safety and efficacy data. Major metropolitan hospitals, particularly in Sydney and Melbourne, are gradually expanding their interventional pulmonology services.
Endobronchial Valve Market Key Industry Players
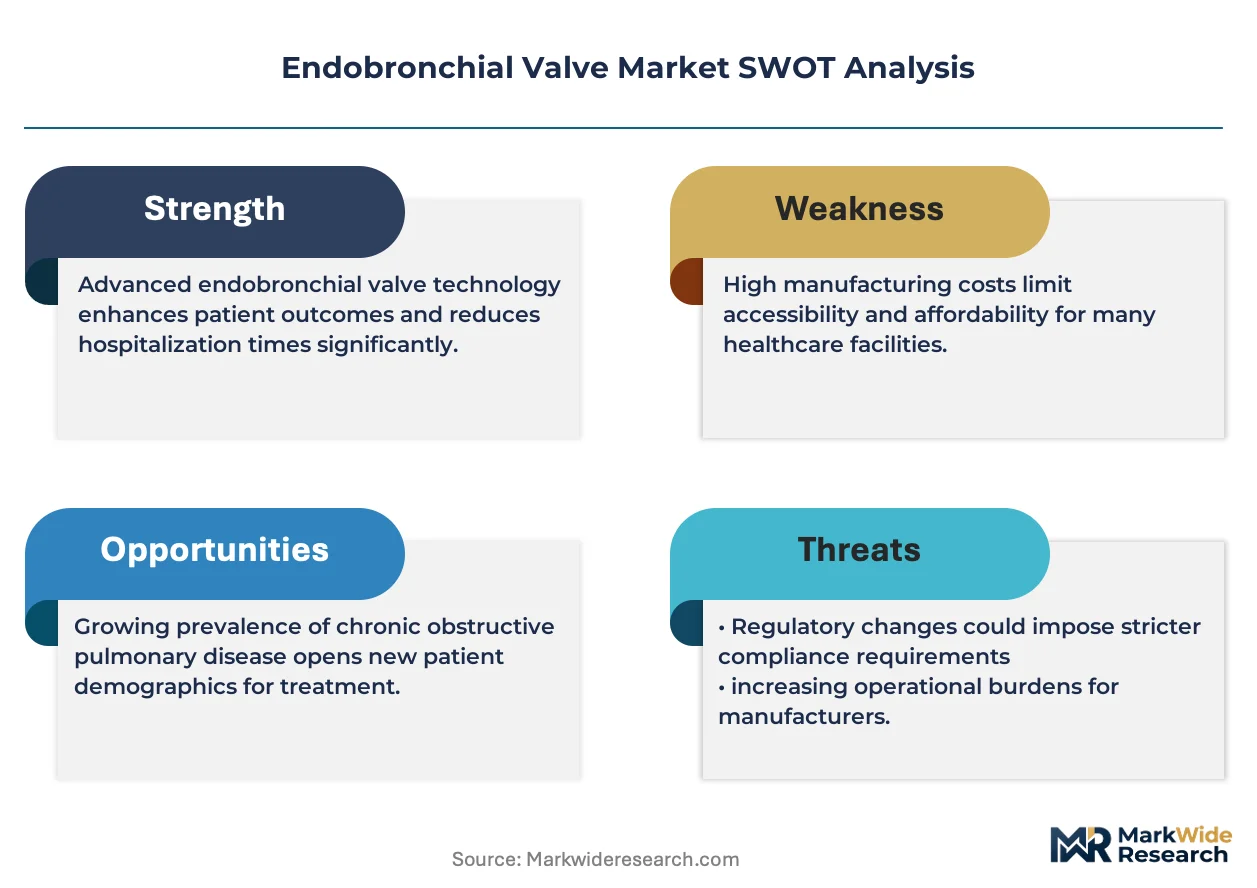
Diversified conglomerates compete with focused pure-play specialists in the endobronchial valve market. The competitive structure is consolidating due to heightened regulatory demands for extensive clinical evidence, favoring incumbents with established data. Strategic archetypes include established valve manufacturers with long-term trial data, specialized providers of bronchoscopic delivery systems, and innovators with distinct valve designs. Companies primarily engage in leveraging existing clinical evidence for market access, targeted geographic expansion, and portfolio diversification to secure their positions.
Within the established market, Pulmonx Corporation represents a leading incumbent, leveraging extensive clinical data from landmark trials to sustain its market position. Olympus Corporation occupies a specialized niche, focusing on the bronchoscopic delivery systems essential for valve placement, crucial for procedural success and efficiency. Spiration Inc. exemplifies an innovator with a distinct umbrella-style valve design, concentrating on targeted regional presence and specific patient segments. These companies navigate stringent regulatory pathways and varying national reimbursement policies, which significantly influence broader market penetration and commercial success.
| Leading Market Players |
|---|
| Pulmonx Corporation |
| Olympus Corporation |
| Spiration Inc |
| Boston Scientific |
| Medtronic |
| Cook Medical |
| Teleflex |
| Veran Medical Technologies |
| Interventional Therapeutics |
| Others |
Cost & Logistics Intelligence
Nickel commodity prices directly influence the manufacturing costs of nitinol-based endobronchial valves. This cost fluctuation can cascade through the supply chain, affecting final product pricing tiers for manufacturers.
Pricing Analysis
Bundled pricing, encompassing the valve implant and associated bronchoscopic delivery systems, is common in the endobronchial valve market. Value-based pricing models are emerging, differentiating based on clinical outcomes and long-term patient benefit. Pricing pressure stems from stringent reimbursement policies in European markets, particularly for newer technologies. Specialty respiratory hospitals, prioritizing clinical efficacy, are less price-sensitive than smaller pulmonology clinics focused on cost containment.
Supply Chain Analysis
Domestic content mandates, particularly for medical devices in the United States, influence sourcing strategies for endobronchial valve components. Production of nitinol frames and medical-grade silicone for valves concentrates in specialized manufacturing hubs across the US and Germany. Single-source vulnerability for advanced biocompatible materials presents a structural risk. Distribution runs through direct sales forces and specialized medical device distributors, primarily targeting hospital networks and pulmonology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endobronchial valve market acts as a regulatory compounder, with the US FDA's Breakthrough Devices Program accelerating innovation and driving demand for novel emphysema treatments. This regulatory support fosters a landscape where compliance and clinical evidence directly translate into market advantage.
For Market Incumbents: Extend clinical evidence generation for existing valve designs, particularly under the EU MDR, to reinforce market access against emerging competitors. Pursue strategic partnerships with interventional pulmonology departments in Germany to control key referral pathways. The threat of less invasive, non-valve therapies necessitates continuous R&D into next-generation devices. Investing in vertical integration for biocompatible material sourcing can mitigate supply chain risks.
For New Entrants and Emerging Players: Specialized medical distributors offer a critical channel for new entrants to gain traction in the endobronchial valve market. Target underpenetrated Asia-Pacific regions like Australia and Japan, focusing on expanded clinical indications beyond severe emphysema. Persistent air leaks post-surgery represent a penetrable application segment with less established competition. A go-to-market angle emphasizing AI-powered procedure planning can differentiate offerings and improve clinical outcomes.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized device manufacturers possessing extensive clinical data and robust regulatory approvals. The market demonstrates long-term viability over the next decade, driven by an aging global population and rising COPD prevalence. Acquisition targets should prioritize firms with innovative valve designs or unique bronchoscopic delivery systems. The signal to watch is PMDA harmonization with FDA and EU MDR, indicating accelerated market entry opportunities in Japan.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Expansion | Supports market access and reimbursement in regulated European and US markets. |
| AI Integration for Planning | Optimizes patient selection and valve placement, enhancing therapeutic outcomes. |
| Asia-Pacific Market Entry | Capitalizes on underserved COPD patient populations in Japan and Australia. |
| Biomaterial R&D Investment | Expands addressable patient populations through improved device safety and biocompatibility. |
| Hospital Network Partnerships | Drives consistent therapy adoption through multidisciplinary lung health committees. |
Research Approach
Direct dialogue with interventional pulmonologists, hospital procurement managers, regulatory affairs specialists, and device engineers formed the primary research backbone. This primary intelligence was cross-referenced with secondary validation from US FDA filings, EU MDR guidance documents, and clinical trial registries. A robust bottom-up and top-down triangulation approach ensured data accuracy. This comprehensive methodology integrated qualitative insights with quantitative market data.
The quantitative model produced volume and value forecasts across the analysis window, integrating historical trends with future projections. Segmentation dimensions modeled included product type, therapy area, end-user, deployment model, and regional regulatory cluster. Compound Annual Growth Rates were derived through a proprietary algorithm considering market dynamics and competitive intensity. Emphysema prevalence rates and regulatory approval timelines served as critical forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving reimbursement policies and technological breakthroughs in non-valve therapies. All forecasts reflect underlying assumptions about market access and clinical adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Interventional Pulmonology Market