
 India Endoscopy Devices Market | 2026-2036
India Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Endoscopy Devices Market Foresight
Modular instrument bundles with single-use disposable components is pivoting procurement patterns across Indian healthcare institutions. Olympus Corporation leverages its established service network to sustain aftermarket revenue streams. Fujifilm Holding Corporation anchors its position through advanced imaging platforms tailored to high-volume gastroenterology suites. Medtronic PLC competes by extending capital equipment financing options that reduce upfront hospital expenditure.
India endoscopy devices encompass visualization systems, insertion tubes, illumination channels, and operative instruments engineered with fiber-optic or digital sensor arrays transmitting real-time images from body cavities for diagnostic and interventional procedures. Stainless steel and polymer-sheathed flexible scopes withstand autoclave sterilization cycles exceeding 134°C while maintaining optical clarity across 10,000+ use cycles. Flexible endoscopes dominate procedure volumes in gastroenterology and pulmonology applications where anatomical navigation demands steerable distal tips. Video endoscopy technology leads installed base expansion as hospitals replace legacy fiber-optic systems with high-definition and 4K imaging platforms. Robotic endoscopy represents the fastest-growing technology segment as surgical suites invest in computer-assisted precision for complex interventions.
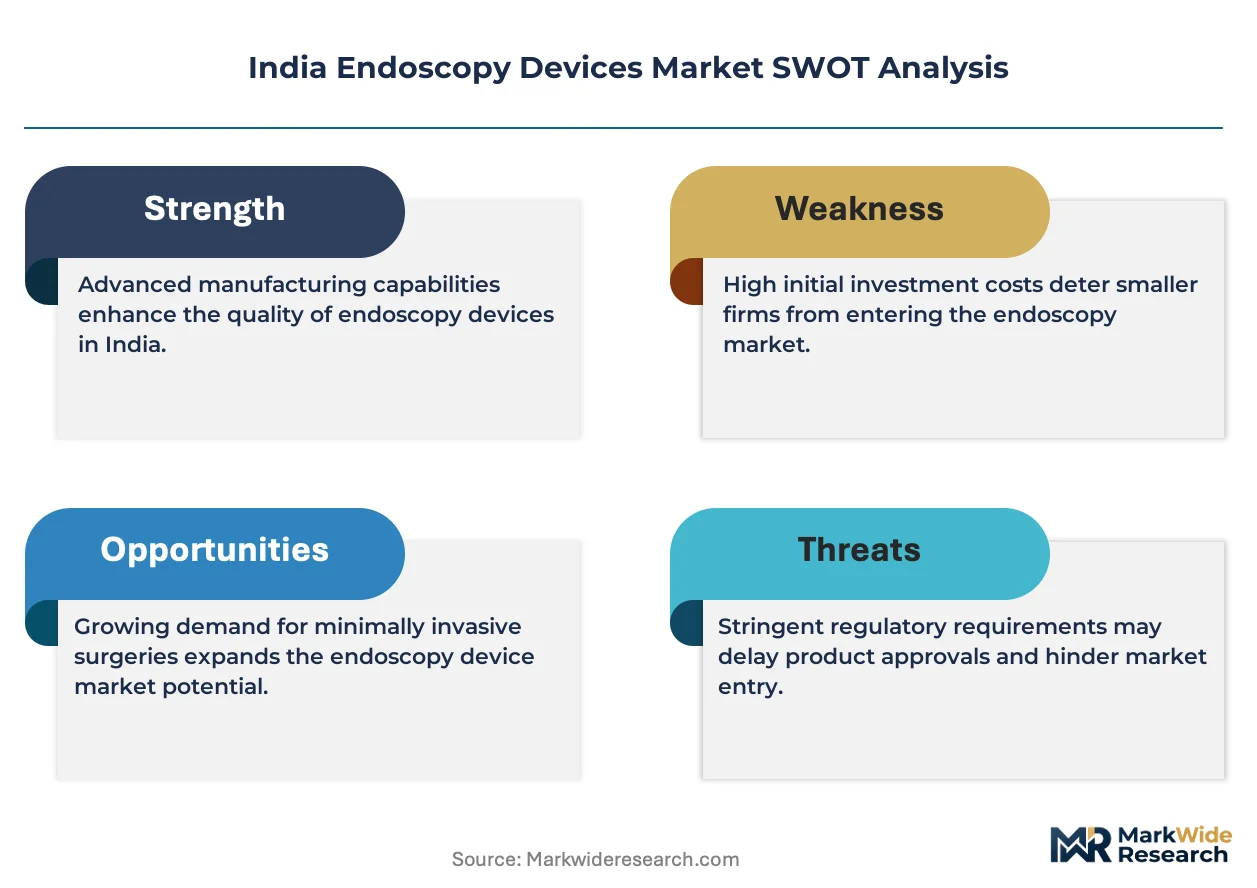
CDSCO mandates quality management system compliance aligned with Medical Device Rules 2017 for all Class A through D device registrations, creating compliance barriers for unorganized domestic manufacturers. BIS certification for electrical safety and electromagnetic compatibility shapes product design requirements for imported and locally assembled equipment. The PLI scheme for medical devices offers production-linked incentives that encourage multinational firms to establish domestic manufacturing footprints. Stakeholders must monitor how CDSCO's forthcoming risk-based classification amendments affect registration timelines and competitive entry dynamics.
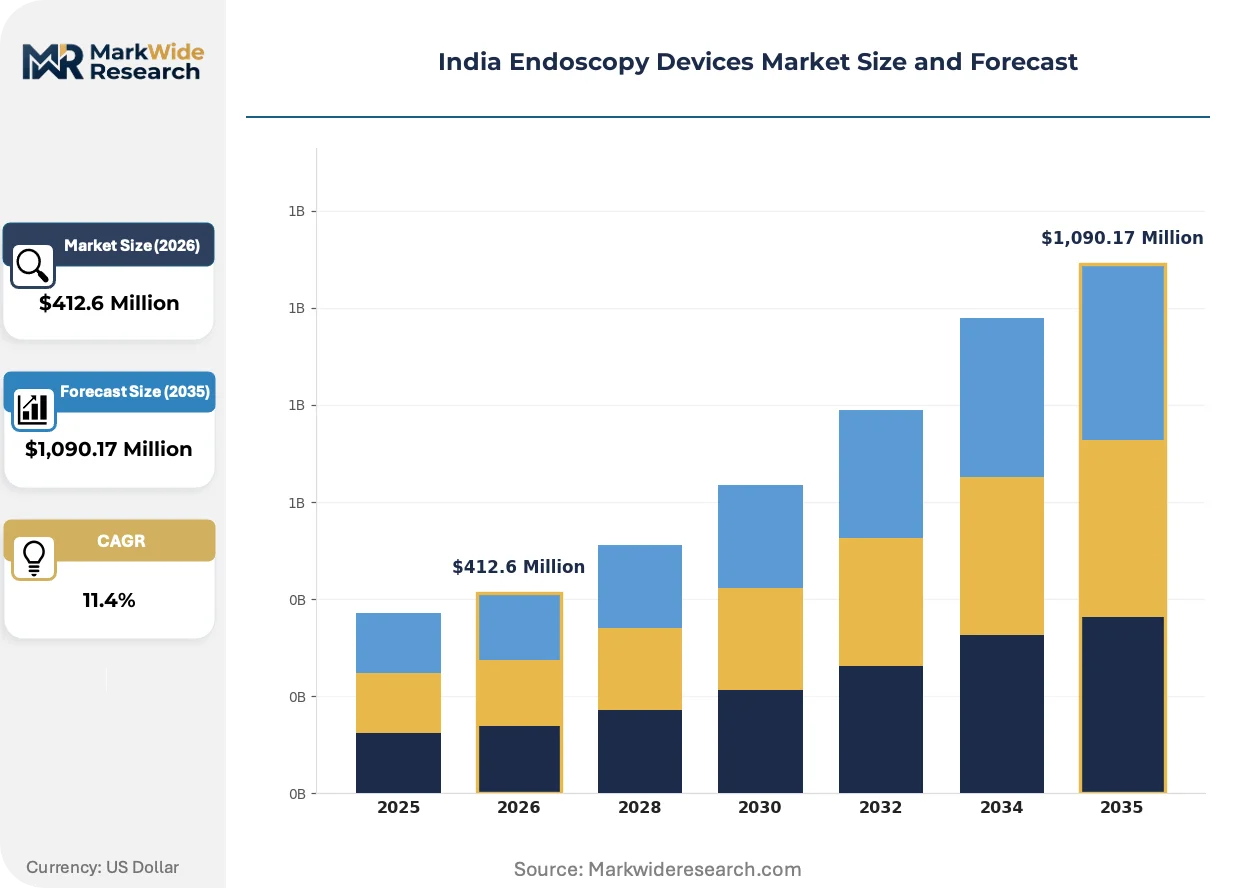
Market Dynamics
CDSCO's risk-based classification amendments are compressing registration timelines for Class C and D endoscopy devices, while Maharashtra and Karnataka hospital chains accelerate dedicated endoscopy center construction. This dual regulatory-demand pressure is restructuring competitive entry patterns and procurement workflows across Indian healthcare institutions.
Growth Catalysts
- PLI scheme incentives:Production-linked incentives under India's medical device PLI scheme are drawing multinational manufacturers toward domestic assembly footprints, reducing import dependency for high-value visualization systems.
- Minimally invasive surgical expansion:Tertiary care hospitals in Mumbai and Delhi are scaling laparoscopic and endoscopic procedure volumes, creating installed base demand for flexible scopes and video processors.
- Single-use disposable adoption:Modular instrument bundles with disposable components are penetrating corporate hospital chains, addressing cross-contamination protocols and reprocessing cost structures.
Market Restraints
- Capital equipment financing constraints:High upfront expenditure for 4K imaging platforms and robotic endoscopy systems limits procurement velocity at mid-tier private hospitals and government medical colleges.
- CDSCO compliance barriers:Quality management system requirements aligned with Medical Device Rules 2017 create registration friction for unorganized domestic manufacturers lacking ISO 13485 certification infrastructure.
- Reprocessing infrastructure gaps:Automated endoscope reprocessor penetration remains concentrated in tier-1 cities, constraining scope utilization rates and infection control standardization.
Strategic Opportunities
- Tier-2 city hospital networks:Underpenetrated markets in Gujarat, Tamil Nadu, and Telangana present whitespace for mobile endoscopy units and refurbished equipment leasing models.
- Artificial intelligence integration:Convergence of computer-aided detection algorithms with high-definition colonoscopy platforms is enabling real-time polyp characterization capabilities.
- Service network unbundling:Third-party preventive maintenance providers are capturing aftermarket revenue streams previously held by original equipment manufacturers.
Industry Challenges
- Gastroenterologist training pipeline:Fellowship program capacity constraints limit specialist availability to operate advanced therapeutic endoscopy platforms at expanding hospital networks.
- BIS electromagnetic compatibility certification:Electrical safety testing timelines for imported video processors create launch delays and inventory holding costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Endoscopy Devices Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Rigid Endoscopes, Flexible Endoscopes, Capsule Endoscopes, Hybrid Endoscopes End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Application: Gastroenterology, Pulmonology, Urology, Gynecology Technology: Video Endoscopy, Ultrasonic Endoscopy, Laser Endoscopy, Robotic Endoscopy |
| Companies Covered | Stryker Corporation, Fujifilm Holding Corporation, Olympus Corporation, Conmed Corporation, Ethicon Inc, Boston Scientific Corporation, KARL STORZ SE & Co. KG, Shaili Endoscopy, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Endoscopy Devices Market Shifts & Advancements
Digital sensor arrays are displacing fiber-optic transmission in Indian hospital procurement specifications, while regulatory streamlining and shifting procurement authority reshape competitive dynamics. These intersecting forces are compressing technology replacement cycles and redistributing value capture across the supply chain.
4K and 3D visualization platforms are unifying diagnostic and interventional workflows within single endoscopy suites. Corporate hospital chains in Bangalore and Hyderabad are prioritizing these systems for new center construction. This capability consolidation is unifying capital budgeting decisions that previously separated imaging procurement from surgical equipment investments.
CDSCO's forthcoming risk-based classification amendments are tightening quality management system requirements for Class C flexible endoscopes. Domestic assemblers must demonstrate ISO 13485 compliance and post-market surveillance infrastructure. Imported video processors and illumination systems face heightened scrutiny, favoring established registrants with dedicated regulatory affairs teams.
Hospital procurement committees are consolidating vendor relationships around comprehensive service agreements that bundle preventive maintenance, software upgrades, and disposable supply contracts. Corporate chains in Maharashtra are displacing transactional equipment purchases with multi-year partnerships. This contractual concentration is most visible at Apollo and Max Healthcare facilities, where standardization across network sites drives volume commitments.
India Endoscopy Devices Market Segmentation
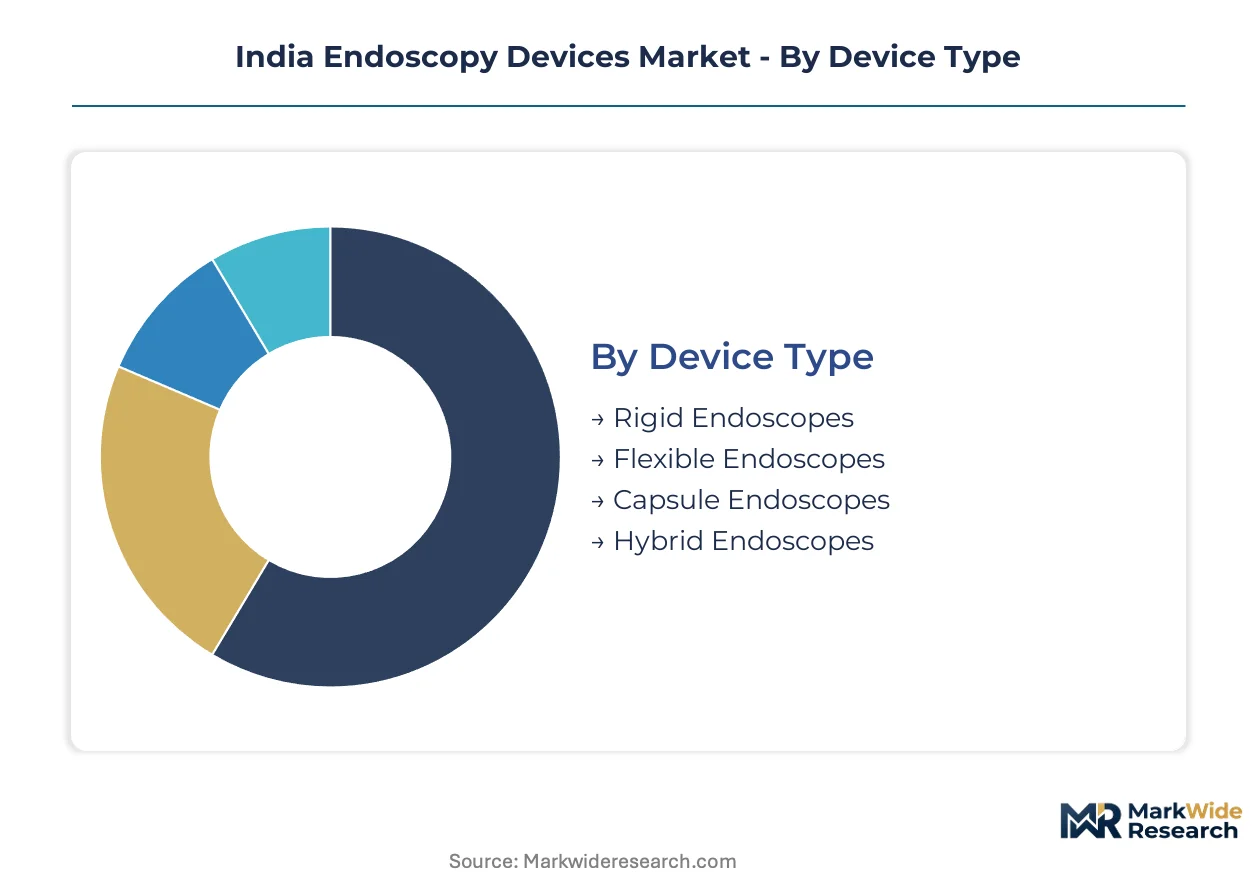
Endoscopy device procurement in India fragments across distinct customer workflows, anatomical applications, and capital intensity tiers. Understanding these divisions clarifies why flexible scopes dominate gastroenterology suites while robotic systems command premium budgets at tertiary centers.
Device Type:
Procurement committees differentiate capital outlays and reprocessing burdens when selecting among insertion tube configurations.
- Rigid Endoscopes:Stainless steel optical systems with fixed lens arrays serve arthroscopy and laparoscopy procedures where anatomical access permits straight-line instrument trajectories. Orthopedic departments at Delhi's AIIMS and Safdarjung Hospital maintain high utilization rates for joint inspection and minimally invasive joint replacement visualization.
- Flexible Endoscopes:Polymer-sheathed insertion tubes with steerable distal tips incorporate fiber-optic or digital sensor arrays for gastrointestinal and pulmonary navigation. Maharashtra and Karnataka hospital chains prioritize these systems for dedicated endoscopy center construction, with Apollo Hospitals and Max Healthcare standardizing procurement across network sites.
- Capsule Endoscopes:Ingestible wireless imaging platforms transmit small bowel visualization data to external receivers, addressing diagnostic gaps in Crohn's disease surveillance where conventional scope insertion fails.
- Hybrid Endoscopes:Dual-modality instruments combining optical channels with therapeutic working ports enable single-session diagnosis and intervention, reducing procedure scheduling complexity at high-volume gastroenterology suites.
Flexible endoscopes lead volumes today; robotic endoscopes are gaining share fastest.
End User:
Facility reimbursement structures and patient throughput determine equipment financing capacity across the care continuum.
- Hospitals:Tertiary care institutions in Mumbai and Delhi deploy comprehensive endoscopy suites with 4K visualization processors and automated reprocessors. Corporate chains leverage PLI scheme incentives to reduce import dependency for high-value capital equipment.
- Ambulatory Surgical Centers:Focused procedure facilities concentrate on same-day diagnostic and interventional endoscopy, prioritizing compact footprint systems with rapid turnover capabilities. Karnataka's expanding ASC network drives demand for modular instrument bundles with disposable components.
- Specialty Clinics:Gastroenterology-focused practices in Bangalore and Hyderabad operate limited-scope installations, often leasing refurbished equipment to manage capital constraints.
- Diagnostic Laboratories:Pathology chains integrate capsule endoscopy reading services, creating downstream demand for image interpretation software and radiologist training programs.
Hospitals absorb the majority of capital expenditure; ambulatory surgical centers are expanding most quickly.
Application:
Anatomical specialization dictates instrument diameter, working channel configuration, and imaging modality requirements.
- Gastroenterology:Upper and lower gastrointestinal procedures utilize flexible scopes with irrigation, suction, and biopsy capability. High-definition colonoscopy platforms with computer-aided detection algorithms concentrate at corporate hospital chains in Maharashtra addressing colorectal cancer screening protocols.
- Pulmonology:Bronchoscopy systems navigate tracheobronchial tree anatomy for lung cancer staging and interstitial lung disease diagnosis. CDSCO's streamlined Class C device approvals are accelerating advanced navigation bronchoscopy platform registration.
- Urology:Cystoscopy and ureteroscopy instruments address benign prostatic hyperplasia and urolithiasis interventions, with rigid configurations dominating operative procedures.
- Gynecology:Hysteroscopy platforms enable diagnostic and operative procedures within the uterine cavity, with demand concentrated at fertility centers in Delhi and Chennai.
Gastroenterology commands the largest installed base; pulmonology is climbing the fastest.
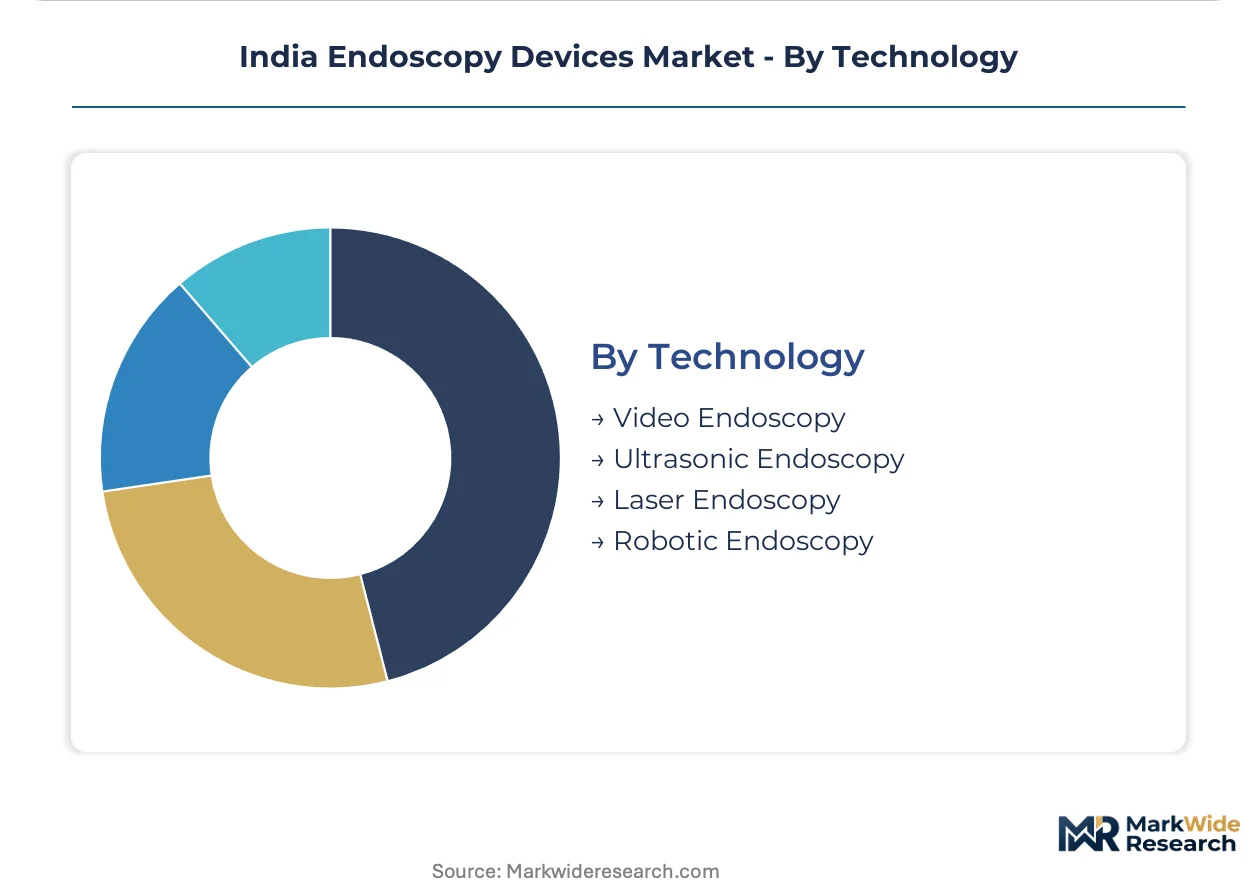
Technology:
Imaging resolution and procedural assistance capabilities separate premium procurement tiers from standard replacements.
- Video Endoscopy:Digital sensor arrays transmit high-definition and 4K resolution images to external processors, displacing legacy fiber-optic systems across Indian hospital procurement specifications. CDSCO mandates BIS electrical safety certification for imported video processors, creating compliance timelines that favor established registrants.
- Ultrasonic Endoscopy:Integrated ultrasound transducers enable real-time tissue characterization and fine-needle aspiration, concentrating at tertiary centers performing pancreaticobiliary interventions.
- Laser Endoscopy:Photocoagulation and lithotripsy capabilities address hemostasis and stone fragmentation, with adoption limited by specialist training availability and capital cost.
- Robotic Endoscopy:Computer-assisted precision platforms enable complex therapeutic procedures with enhanced stability and instrument articulation. Mumbai and Delhi tertiary hospitals are investing in these systems for advanced endoscopic submucosal dissection and natural orifice transluminal endoscopic surgery.
Video endoscopy maintains dominant share; robotic endoscopy shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endoscopy device manufacturing originated in precision optics clusters of Germany and Japan during the mid-20th century, with fiber-optic technology later diffusing to surgical equipment hubs across Asia-Pacific. India emerged as a demand center through tertiary hospital expansion in Mumbai and Delhi, where minimally invasive surgical adoption accelerated through corporate healthcare investment.
Maharashtra
Mumbai's corporate hospital chains anchor India's highest concentration of 4K visualization platforms and robotic endoscopy installations. CDSCO's streamlined Class C and D device approvals compress registration timelines for imported flexible scopes entering this market. Apollo Hospitals and Max Healthcare facilities in Mumbai and Pune standardize procurement across network sites, consolidating vendor relationships around comprehensive service agreements.
Karnataka
Bangalore's expanding ambulatory surgical center network drives demand for modular instrument bundles with single-use disposable components. BIS electromagnetic compatibility certification requirements shape electrical safety testing timelines for video processors entering this corridor. Corporate gastroenterology suites in Bangalore and Hyderabad prioritize compact footprint systems with rapid turnover capabilities for same-day procedures.
Delhi-NCR
AIIMS and Safdarjung Hospital maintain high utilization rates for rigid endoscopes in orthopedic arthroscopy and joint replacement visualization. The PLI scheme for medical devices draws multinational manufacturers toward domestic assembly footprints, reducing import dependency for high-value capital equipment. Tertiary care institutions across Delhi, Gurgaon, and Noida deploy comprehensive endoscopy suites with automated reprocessors.
Gujarat
Ahmedabad and Surat hospital networks represent underpenetrated whitespace for mobile endoscopy units and refurbished equipment leasing models. CDSCO quality management system requirements aligned with Medical Device Rules 2017 create compliance barriers for unorganized domestic manufacturers lacking ISO 13485 certification infrastructure. Private hospital chains in these tier-2 markets concentrate on gastroenterology screening protocols for colorectal cancer detection.
Tamil Nadu
Chennai's fertility centers drive hysteroscopy platform demand for diagnostic and operative uterine cavity procedures. State-level medical device procurement policies influence capital equipment financing options at mid-tier private hospitals and government medical colleges. Diagnostic laboratories in Chennai integrate capsule endoscopy reading services, creating downstream demand for image interpretation software and radiologist training programs.
India Endoscopy Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology tiers and service bundling capabilities in India's endoscopy device market. The vendor structure concentrates around multinational imaging specialists with established regulatory affairs teams and domestic assemblers leveraging PLI scheme incentives. Three archetypes dominate: integrated visualization system providers, flexible scope manufacturers with aftermarket service networks, and modular disposable component suppliers. Capacity expansion through domestic manufacturing footprints and strategic partnerships for regulatory compliance represent the dominant competitive moves reshaping market entry dynamics.
Within the integrated visualization tier, Olympus Corporation and Fujifilm Holding Corporation anchor premium positioning through high-definition and 4K imaging platforms. Medtronic PLC exemplifies the therapeutic intervention specialist archetype, while Stryker Corporation occupies a position bridging rigid endoscopy systems with surgical navigation technologies. These three multinationals represent contrasting strategic postures: Olympus leverages established service infrastructure, Fujifilm anchors through advanced imaging tailored to high-volume gastroenterology suites, and Medtronic extends capital equipment financing options that reduce upfront hospital expenditure burdens.
| Leading Market Players |
|---|
| Stryker Corporation |
| Fujifilm Holding Corporation |
| Olympus Corporation |
| Conmed Corporation |
| Ethicon Inc |
| Boston Scientific Corporation |
| KARL STORZ SE & Co. KG |
| Shaili Endoscopy |
| Medtronic PLC |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up hospital chains in Maharashtra and Karnataka anchor procurement volume concentration, translating network-scale purchasing power into compressed equipment margins and extended payment terms for original equipment manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates 4K robotic platforms from high-definition video systems and refurbished fiber-optic installations. Price differentiation hinges on CDSCO registration tier and ISO 13485 certification status, with Class C device holders commanding service bundling premiums. Cost compression in economy tiers is intensifying because domestic assemblers leverage PLI scheme incentives to undercut import landed costs. Government medical colleges exhibit highest price sensitivity; corporate hospital chains absorb premium tier outlays through equipment financing arrangements.
Supply Chain Analysis
CMOS sensor arrays and precision glass lens assemblies rest on Japanese and German optical component producers, while polymer sheath materials and illumination fiber bundles draw from Chinese and South Korean specialty manufacturers. Supply chain vulnerability concentrates in single-source dependencies for high-resolution digital sensors subject to export control classifications. Distribution runs through authorized dealer networks with regional service depots in Mumbai, Delhi, and Bangalore, supplemented by direct hospital contracts for high-value capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's endoscopy device market stems from CDSCO registration streamlining reducing compliance overhead and single-use disposable adoption shifting revenue toward recurring consumable streams.
For Market Incumbents: Hedge against third-party preventive maintenance providers capturing aftermarket revenue by embedding software lock-in and predictive diagnostics into visualization platforms. Deepen backward integration into domestic CMOS sensor assembly through PLI scheme partnerships, insulating against import tariff exposure on Japanese optical components. For New Entrants and Emerging Players: Capture whitespace in Gujarat and Tamil Nadu tier-2 hospital networks through mobile endoscopy unit leasing and refurbished equipment certification programs. Target ambulatory surgical center expansion in Bangalore and Hyderabad with compact footprint systems bundled with rapid-turnover disposable instrument protocols. For Investors and Strategic Acquirers: Valuations sit cheapest among unorganized domestic manufacturers lacking ISO 13485 infrastructure but holding CDSCO Class A and B registrations. Long-term viability favors targets with demonstrated post-market surveillance capabilities and established relationships with Maharashtra corporate hospital procurement committees. Watch CDSCO risk-based classification amendment implementation timelines as inflection signal for competitive entry dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C Registration Pathway | Accelerates market entry for robotic endoscopy platforms at Mumbai tertiary centers. |
| Hospital System Partnership | Apollo and Max Healthcare network standardization creates multi-year volume commitments. |
| Backward Integration into Domestic Assembly | PLI scheme incentives reduce import dependency for high-value visualization systems. |
| Software Companion Development | Computer-aided detection algorithms differentiate premium colonoscopy platforms. |
| Reimbursement Strategy | Alignment with Ayushman Bharat coverage expansion drives screening protocol adoption. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Delhi-NCR, Gujarat, and Tamil Nadu, with primary inputs from each region combining interviews with hospital procurement committee members, biomedical engineering directors, gastroenterology department heads, and GPO contracts managers alongside secondary validation through CDSCO registration databases, BIS certification records, and corporate hospital chain capital expenditure disclosures. Bottom-up equipment installation tracking triangulates against top-down healthcare infrastructure spending analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions model device type, end-user facility tier, anatomical application, and technology platform. CAGRs derive from installed base replacement cycles, procedure volume elasticity, and capital equipment financing penetration. Industry-specific inputs incorporate CDSCO approval timeline distributions and PLI scheme participant production capacity ramp schedules.
Regulatory amendment delays, PLI scheme incentive revision, and specialist physician training pipeline constraints are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Ultrasound (EUS) Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscopy Device Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Endoscopy Equipment Market