
 Rigid Endoscopes Market | 2026-2036
Rigid Endoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Endoscopes Market Outlook
Recurring maintenance contracts and software-defined imaging upgrades is pivoting how vendors monetize rigid endoscope deployments. KARL STORZ SE & Co. KG leverages its Tuttlingen manufacturing base to sustain premium positioning in laparoscopic systems. Olympus Corporation anchors hospital procurement through integrated visualization platforms. Stryker competes via its broad surgical portfolio and channel density across North American health systems.
A rigid endoscope is a non-flexible tubular optical instrument typically constructed from stainless steel or aluminum alloy housings with rod-lens relay systems or fiber optic bundles, engineered to transmit illumination and return visual images from body cavities during diagnostic or surgical intervention. Laparoscopes dominate procedural volume while digital video technology captures the fastest upgrade cycle as hospitals replace legacy fiber optic stacks. Hospitals remain the anchor end-user segment, though ambulatory surgical centers represent the expanding margin pool as outpatient migration accelerates.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and sterilization validation protocols for manufacturers selling into the United States and European Union. ISO 13485 quality management standards govern production consistency across international supply chains. Stakeholders must monitor reimbursement parity between inpatient and outpatient settings as this determines capital allocation across hospital and ambulatory customer segments.
Market Dynamics
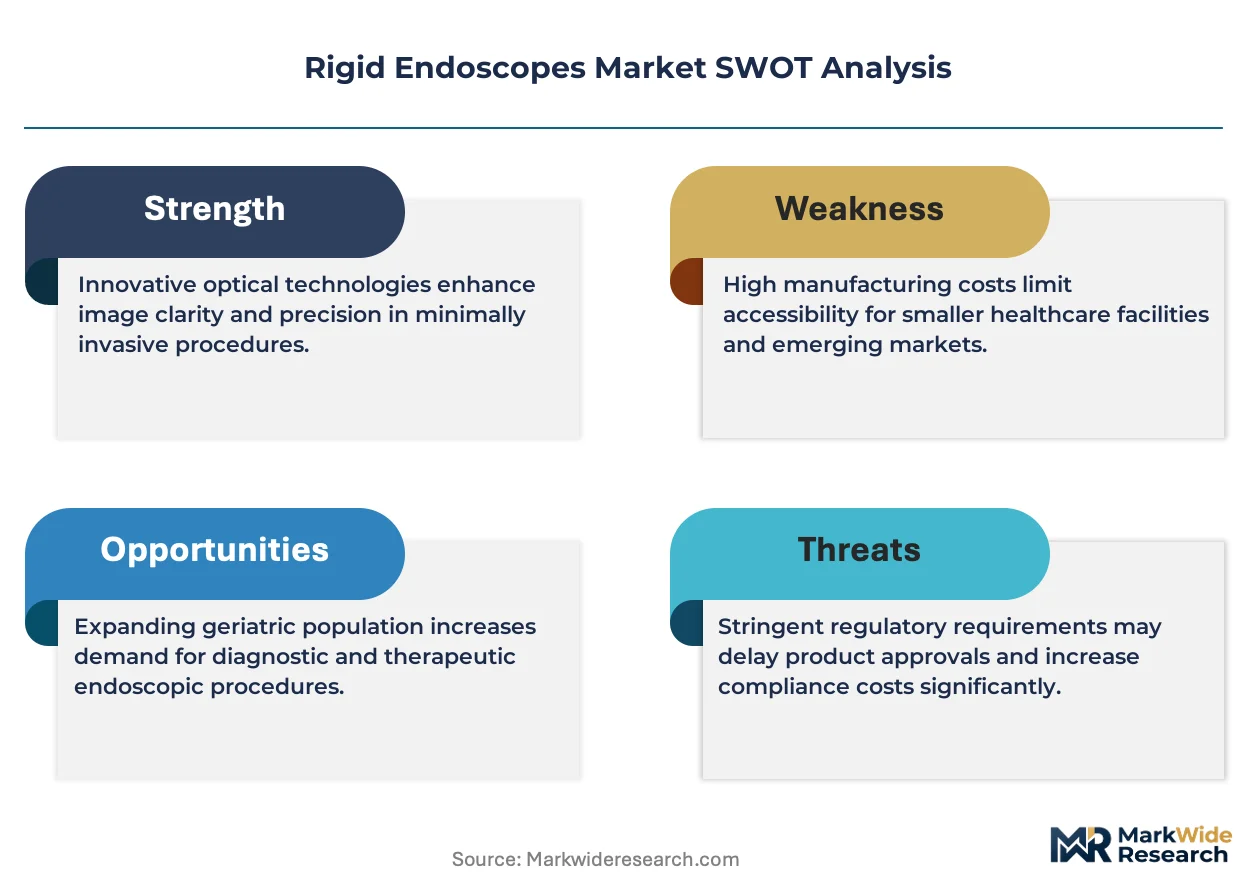
Digital imaging stack replacement cycles are compressing as hospitals prioritize 4K and 3D visualization platforms over legacy fiber optic systems, while EU MDR sterilization validation requirements extend product development timelines for manufacturers serving European surgical centers.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient migration across United States health systems drives capital equipment procurement for minimally invasive suites. Same-day discharge protocols require compact, mobile rigid endoscope towers.
- EU MDR Conformity Requirements:Stricter sterilization validation protocols force manufacturers to redesign reprocessing interfaces. This creates upgrade revenue streams from installed base retrofits.
- 4K Video Technology:Surgical visualization platforms with ultra-high-definition output capture replacement demand from aging fiber optic stacks. German manufacturing clusters around Tuttlingen supply precision optical components for these systems.
Market Restraints
- Rod-Lens Optical Component Concentration:Precision glass grinding capacity concentrates among specialized German and Japanese suppliers. Disruption to these sources stalls production for downstream endoscope assemblers.
- Stainless Steel Alloy Volatility:Surgical-grade 316L stainless steel pricing fluctuates with nickel and molybdenum commodity markets. Input cost swings compress margin predictability for aluminum alloy housing alternatives.
- Reusable Device Sterilization Complexity:Prion inactivation protocols for neuroendoscopes require extended autoclave cycles. Processing bottlenecks limit throughput in high-volume surgical departments.
Strategic Opportunities
- Single-Use Rigid Endoscope Segments:Contamination risk in bariatric and orthopedic procedures creates addressable white space for disposable laparoscope variants. United States ASCs pilot these programs to eliminate reprocessing liability.
- Software-Defined Imaging Upgrades:FPGA-based image processing modules enable hardware platforms to receive computational enhancements without physical replacement. Vendors monetize through recurring firmware licensing.
- India PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing attract component suppliers to establish optical assembly operations. Local value addition targets reduce import dependency for public hospital procurement.
Industry Challenges
- ISO 13485 Auditor Shortage:Qualified quality management system assessors for medical device manufacturing face capacity constraints. Certification backlog delays new product introductions for mid-tier manufacturers.
- Legacy Stack Integration Complexity:New 4K camera heads must interface with installed light source and insufflator fleets from disparate vendors. Adapter development consumes engineering resources without differentiation value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Endoscopes Market |
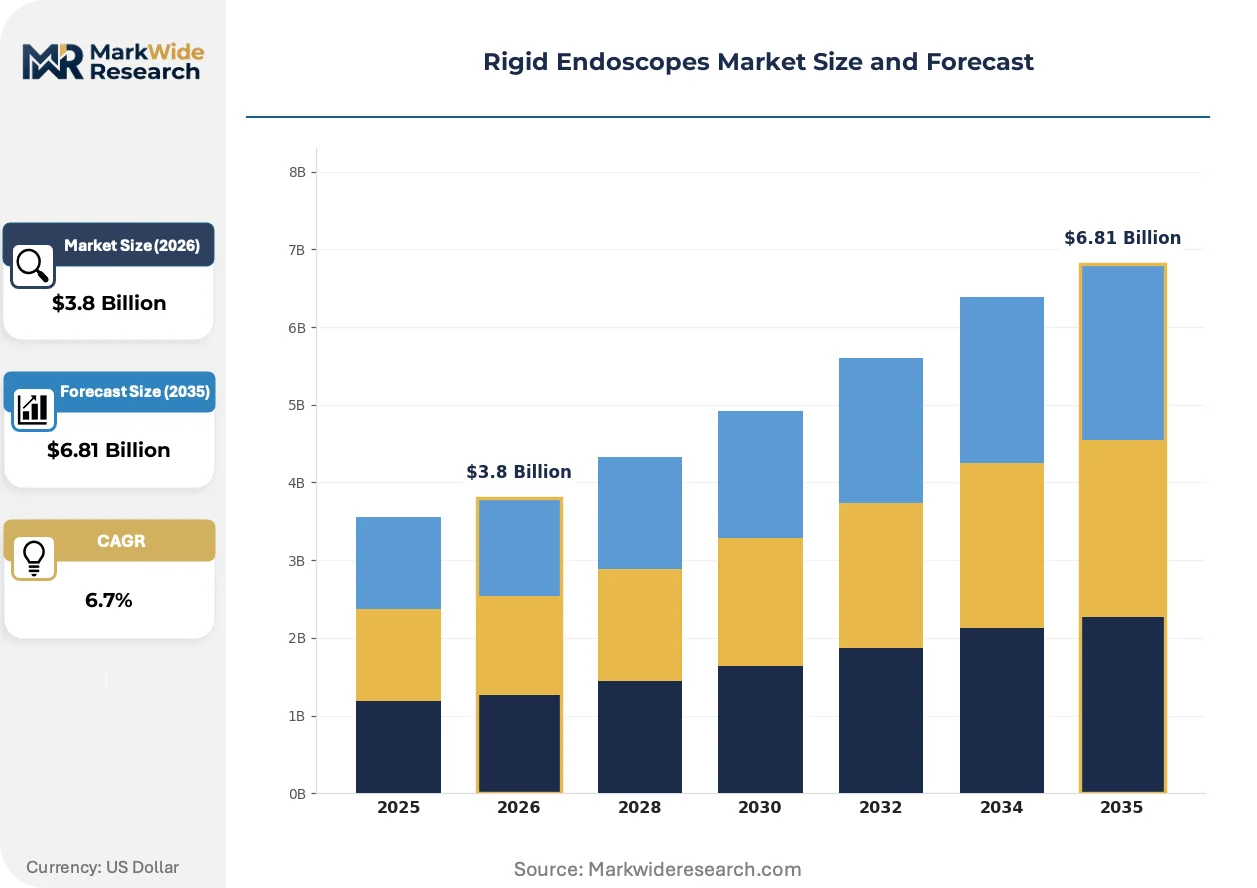
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchoscope, Laparoscope, Cystoscope, Hysteroscope Technology: Optical, Digital, Fiber Optic, Video End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Centers Application: Surgery, Disease Diagnosis, Gastroenterology, Urology |
| Companies Covered | Smith+Nephew, Medtronic, Olympus Corporation, Arthrex Inc., CONMED Corporation, KARL STORZ SE & Co. KG, B. Braun SE, Richard Wolf GmbH, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Endoscopes Market Strategic Shifts
Imaging pipeline digitization is restructuring competitive advantage around computational capabilities rather than pure optical precision, while regulatory sterilization standards force hardware redesigns that favor modular, upgradeable architectures.
CMOS sensor technology is electrifying surgical visualization by replacing CCD arrays with lower-power, higher-dynamic-range alternatives. Academic medical centers in Germany and the United States deploy these sensors in hybrid OR configurations. The shift is electrifying vendor R&D allocation toward in-house semiconductor design partnerships rather than optical component sourcing.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for all Class IIa and above reusable surgical instruments. Manufacturers must compile post-market surveillance data for existing laparoscope portfolios. German notified bodies face application backlogs extending conformity assessment timelines by twelve to eighteen months.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases. Third-party ISO 13485-certified repair shops in Poland and Mexico capture maintenance revenue previously retained by original manufacturers. United States IDN consolidation accelerates this disintermediation as centralized supply chains negotiate direct service agreements.
Rigid Endoscopes Market Segmentation
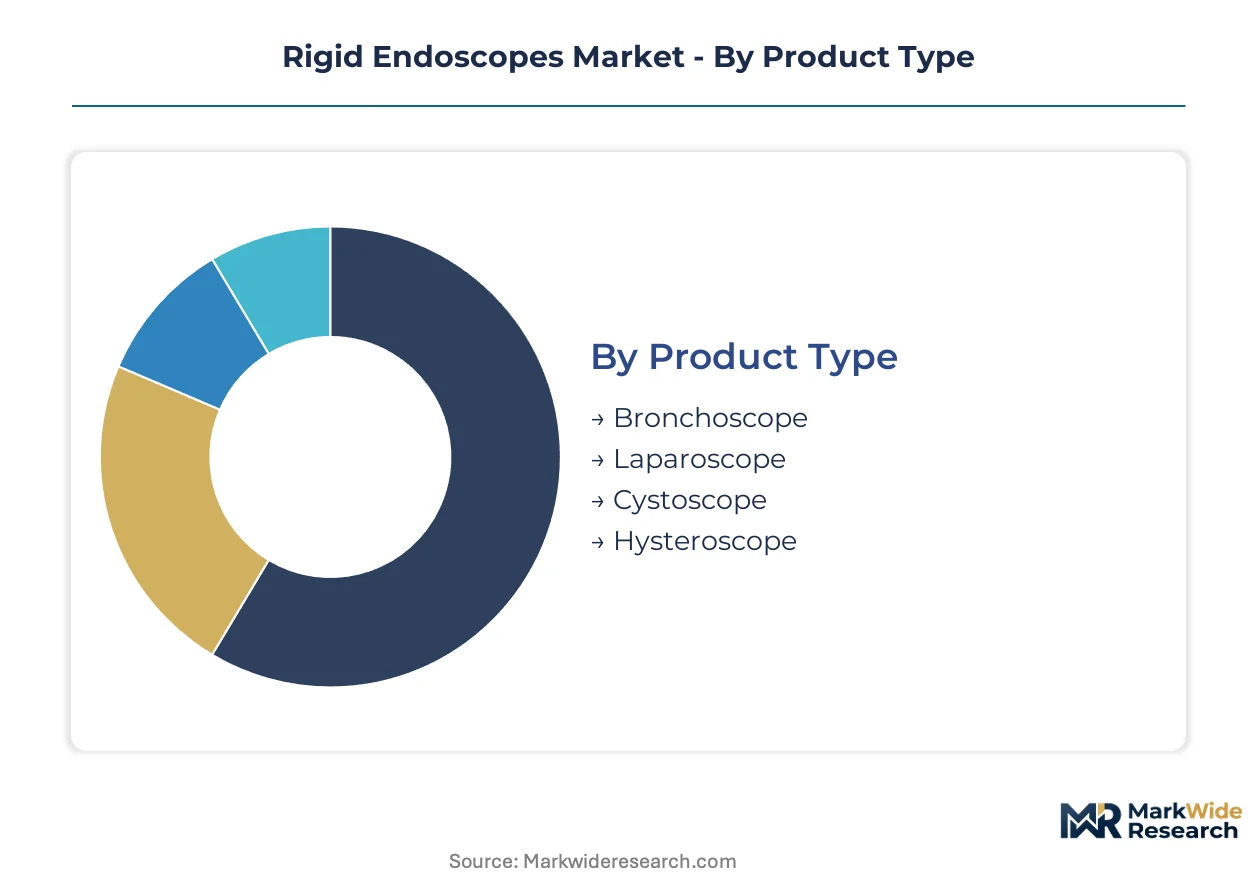
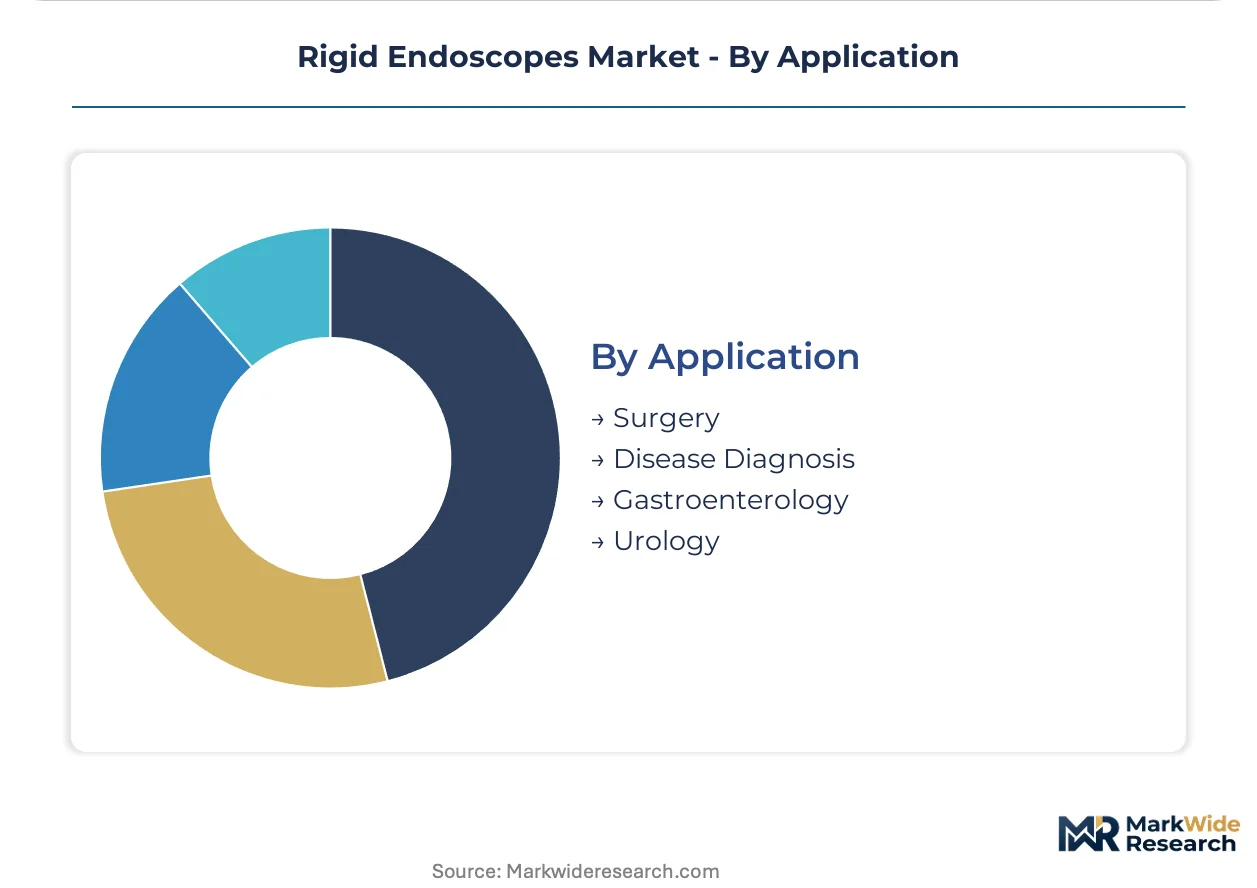
Procurement patterns across the rigid endoscopes market diverge sharply by clinical setting and imaging technology maturity. Vendors must align product configurations with distinct sterilization protocols, capital budgets, and procedural throughput requirements.
Product Type:
Procedural volume concentration and reimbursement parity determine which instrument categories command premium positioning versus commodity pricing.
- Laparoscope:Stainless steel or aluminum alloy housings with rod-lens relay systems dominate abdominal minimally invasive surgery. Demand concentrates in United States hospital systems where bariatric and colorectal procedures drive fleet standardization around 4K-compatible platforms.
- Bronchoscope:Rigid bronchoscopes feature larger working channels for interventional pulmonology and foreign body retrieval. German thoracic surgery departments anchor European procurement volumes, constrained by prion inactivation protocols for neuroendoscope-adjacent sterilization workflows.
- Cystoscope:Short rigid instruments with 0-70 degree viewing angles serve transurethral resection procedures.
- Hysteroscope:Small-diameter diagnostic and operative variants address uterine cavity inspection.
Laparoscopes lead volumes today; hysteroscopes are gaining share fastest as office-based gynecology expands.
Technology:
Replacement cycle timing and image processing architecture separate capital-intensive upgrade paths from maintenance-heavy legacy retention.
- Digital:CMOS sensor-based platforms with FPGA image processing enable software-defined enhancement without hardware replacement. United States academic medical centers pilot these systems in hybrid OR configurations, drawn by lower power consumption and higher dynamic range versus CCD alternatives.
- Video:Integrated camera-head systems with 4K output capture replacement demand from aging fiber optic stacks. Tuttlingen manufacturing clusters supply precision optical components for these visualization platforms.
- Fiber Optic:Illumination bundles with eyepiece viewing persist in cost-constrained settings.
- Optical:Pure rod-lens systems without electronic capture remain limited to teaching institutions.
Video technology anchors installed base revenue; digital platforms show the steepest expansion trajectory.
End User:
Capital allocation authority and reprocessing infrastructure capacity dictate pricing tolerance and service contract structures.
- Hospitals:Integrated delivery networks leverage centralized procurement to negotiate bundled visualization platform contracts. United States IDN consolidation accelerates disintermediation of after-sales service toward third-party ISO 13485-certified repair shops.
- Ambulatory Surgical Centers:Compact, mobile rigid endoscope towers align with same-day discharge protocols and limited floor space. United States ASCs pilot single-use laparoscope programs to eliminate reprocessing liability and throughput bottlenecks.
- Clinics:Lower procedural volumes favor flexible financing and refurbished equipment channels.
- Diagnostic Centers:Imaging-focused settings prioritize rapid turnaround over surgical-grade sterilization validation.
Hospitals retain the largest share of capital expenditure; ambulatory surgical centers are expanding most quickly as outpatient migration accelerates.
Application:
Reimbursement coding specificity and procedure duration requirements shape instrument durability specifications and accessory ecosystem investment.
- Surgery:Laparoscopic, arthroscopic, and hysteroscopic interventions demand autoclavable instruments with modular component replacement. German surgical departments prioritize EU MDR-compliant sterilization validation documentation for reusable device portfolios.
- Urology:Transurethral resection and stone management procedures require specialized working channels and laser fiber compatibility.
- Disease Diagnosis:Biopsy-capable instruments with integrated suction channels serve diagnostic sampling workflows.
- Gastroenterology:Upper and lower GI applications favor flexible endoscopes, limiting rigid instrument penetration to specialized interventions.
Surgery dominates procedural revenue; urology applications are climbing the fastest as stone disease prevalence rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs push assembly toward lower-cost jurisdictions while German precision clusters retain high-value optical component production.
United States
Ambulatory surgical center expansion and hospital IDN consolidation drive capital equipment procurement for minimally invasive suites. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting American health systems. The Southeast and Midwest surgical corridors anchor domestic demand concentration.
Germany
Tuttlingen's medical device manufacturing cluster sustains premium positioning in laparoscopic systems through precision rod-lens grinding capacity. EU MDR sterilization validation requirements extend conformity assessment timelines by twelve to eighteen months. Bavarian and Baden-Württemberg surgical departments prioritize compliant reusable device portfolios.
China
Domestic hospital procurement for 4K visualization platforms accelerates as public health infrastructure upgrades continue. NMPA regulatory harmonization with international standards streamlines import substitution programs. Yangtze River Delta manufacturing bases expand optical assembly operations for regional supply.
India
Public hospital procurement volumes rise under government health insurance expansion schemes. PLI scheme production-linked incentives attract component suppliers to establish domestic optical assembly operations. Maharashtra and Karnataka medical device parks concentrate new manufacturing investments.
Japan
Aging demographics sustain procedural volume growth in diagnostic and surgical endoscopy. PMDA quality management requirements align with ISO 13485 standards for multinational manufacturers. Kanto and Kansai metropolitan hospital networks drive replacement demand for digital imaging stacks.
Rigid Endoscopes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated visualization platform vendors commanding hospital procurement contracts while component suppliers capture recurring optical replacement revenue. The structure concentrates among three tiers: German precision manufacturers with captive Tuttlingen supply bases, diversified surgical conglomerates with broad portfolio breadth, and emerging Asian fabricators scaling through cost-advantaged assembly. Strategic moves center on software-defined imaging upgrades to monetize installed bases and M&A activity targeting sterilization validation capabilities for EU MDR compliance.
Within the German precision tier, KARL STORZ SE & Co. KG and Richard Wolf GmbH exemplify archetypes anchored in Tuttlingen manufacturing clusters. Olympus Corporation occupies a position representing integrated visualization platform vendors with hospital procurement anchoring. Stryker exemplifies the diversified surgical conglomerate archetype with broad portfolio breadth across North American health systems.
| Leading Market Players |
|---|
| Smith+Nephew |
| Medtronic |
| Olympus Corporation |
| Arthrex Inc. |
| CONMED Corporation |
| KARL STORZ SE & Co. KG |
| B. Braun SE |
| Richard Wolf GmbH |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
United States hospital IDN procurement committees concentrate buying power for visualization platforms, compressing vendor margins through bundled contract negotiations that tie capital equipment purchases to multi-year service commitments.
Pricing Analysis
Capacity additions in China's Yangtze River Delta optical assembly corridors are reshaping price floors for CMOS sensor modules and rod-lens subassemblies. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated German instruments from ISO 13485-certified Asian alternatives and refurbished legacy stacks. Price differentiation hinges on sterilization validation documentation completeness and after-sales service bundling. Cost compression in the standard tier intensifies because Indian PLI scheme subsidies attract component suppliers to establish domestic manufacturing. Ambulatory surgical centers exhibit highest price sensitivity due to limited capital budgets, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Singapore coordinate hub-and-spoke patterns for precision optical components and finished instruments. Manufacturing gravity centers on Tuttlingen for rod-lens grinding, Japan for specialized glass alloys, and China for CMOS sensor assembly. Raw material dependencies include surgical-grade 316L stainless steel, molybdenum-doped optical glass, and medical-grade aluminum alloys. Single-source vulnerability concentrates in German precision grinding capacity for relay lens systems. Distribution runs through manufacturer-direct sales for hospital IDNs and specialized medical device distributors for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment timelines extending twelve to eighteen months create geographic-arbitrage opportunities for manufacturers with notified body relationships in Germany versus those dependent on backlogged certification queues.
For Market Incumbents: Anchor market position through captive Tuttlingen supply base consolidation and software-defined imaging firmware licensing programs. Defend against single-use rigid endoscope substitutes by accelerating EU MDR sterilization validation documentation for reusable portfolios. Prioritize vertical integration into CMOS sensor design partnerships to capture computational imaging value migration. For New Entrants and Emerging Players: Launch via third-party ISO 13485-certified repair shop partnerships in Poland and Mexico to bypass manufacturer-direct service contract disintermediation. Target ambulatory surgical center single-use laparoscope pilot programs as the most penetrable white space. Exploit India PLI scheme production-linked incentives to establish cost-advantaged optical assembly operations for public hospital procurement. For Investors and Strategic Acquirers: Diversified surgical conglomerates with broad North American health system channel density are the most active acquirer in this space. Long-term viability favors targets with EU MDR sterilization validation capabilities and installed base monetization through recurring firmware licensing. Monitor FDA 510(k) clearance pathway acceleration versus EU MDR backlog divergence as the critical inflection signal for geographic manufacturing footprint decisions.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Sterilization Validation Investment | Extends conformity assessment timelines but creates upgrade revenue from installed base retrofits in German surgical departments. |
| Software-Defined Imaging Platform Development | Enables FPGA-based computational enhancements without hardware replacement, monetizing through recurring firmware licensing to hospital IDNs. |
| Single-Use Rigid Endoscope Product Line Launch | Eliminates reprocessing liability for United States ASCs piloting contamination-risk reduction in bariatric procedures. |
| CMOS Sensor Semiconductor Partnership | Secures lower-power, higher-dynamic-range alternatives to CCD arrays for academic medical center hybrid OR configurations. |
| India PLI Scheme Manufacturing Footprint | Reduces import dependency for public hospital procurement under government health insurance expansion schemes. |
Study Parameters
Multiple input streams — structured interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers; FDA 510(k) clearance databases and EU MDR technical documentation filings; and hospital procurement database extracts — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K disclosures of listed surgical device manufacturers, CMS Medicare reimbursement schedules, and customs records for optical component trade flows.
Historical shipment data cross-referenced against panel input from Tuttlingen manufacturing cluster executives anchored volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user facility class, and application specialty. CAGRs were derived from procedure volume elasticity to reimbursement parity shifts and capital equipment replacement cycle compression. Industry-specific forecast inputs incorporated EU MDR conformity assessment timeline extensions and ambulatory surgical center outpatient migration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prion inactivation protocol revisions or nickel-molybdenum commodity price spikes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Esophageal Stents Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Endorectal Balloon Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Video Laryngoscope Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Bronchoscopy Market
Endoscopy
Global Endoscopic Stricture Management Device Market