
 Gastrointestinal Endoscopy Devices Market | 2026-2036
Gastrointestinal Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal Endoscopy Devices Market Analysis
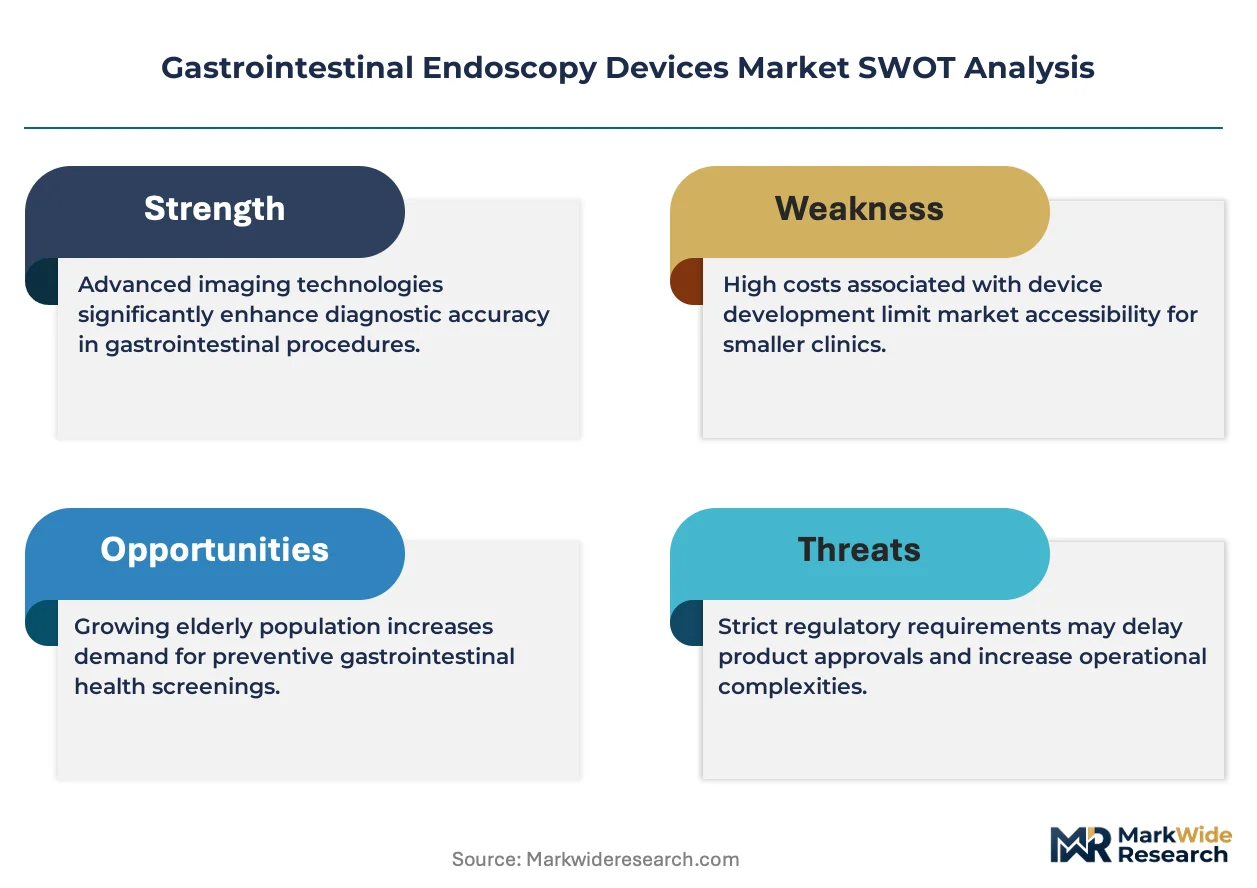
Modular system architecture is shifting buyer preference toward upgradeable endoscopy platforms rather than fixed-configuration capital purchases. Olympus Corporation leverages its captive optics manufacturing to control component quality across generations. Boston Scientific Corporation competes through interventional endoscopy portfolios that bridge diagnostic and therapeutic workflows. Fujifilm Holdings Corporation anchors its position in video imaging systems that integrate with hospital IT infrastructure.
Gastrointestinal endoscopy devices comprise flexible or rigid instrument systems with working channels, illumination fibers, and image sensors designed for visual examination, biopsy sampling, and minimally invasive intervention within the digestive tract. Optical systems historically employed fiber bundles, though digital CMOS and CCD sensors now dominate new installations with resolution parameters exceeding 1080p in premium configurations. Endoscopes command the largest installed base among product type categories, while robotic technology represents the fastest-expanding segment as systems like single-operator platforms reduce procedural variability. Wireless capsule endoscopy occupies a distinct margin pool by eliminating sedation requirements and enabling ambulatory monitoring, though reimbursement coding limits its addressable case mix relative to conventional scopes.
FDA 510(k) clearance pathways govern device introductions in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements that extend certification timelines for novel systems. Japan's PMDA maintains distinct quality management expectations that favor manufacturers with established local technical service networks. Stakeholders must monitor how reimbursement parity between hospital-based and ambulatory settings evolves, as site-of-service payment differentials will determine capital deployment priorities across health system purchasers.
Market Dynamics
Modular system architecture is compressing replacement cycles as hospitals prioritize upgradeable platforms over fixed-configuration capital purchases, forcing manufacturers to restructure hardware and software revenue streams around subscription-based service models.
Growth Catalysts
- Aging Demographics:Screening program expansion in Germany and Japan sustains procedural volume growth among populations over sixty-five.
- FDA 510(k) Pathway:Streamlined premarket notification for iterative device modifications accelerates product refresh timelines relative to EU MDR certification.
- Ambulatory Surgical Centers:Site-of-service payment differentials favoring outpatient settings pull procedure volume away from hospital-based endoscopy suites.
Market Restraints
- EU MDR Compliance:Stricter clinical evidence requirements extend certification timelines and elevate documentation costs for novel system introductions.
- CMOS Sensor Supply:Concentrated fabrication capacity in East Asia creates input vulnerability for digital imaging component sourcing.
- Wireless Capsule Limitations:Reimbursement coding constraints restrict addressable case mix relative to conventional flexible scopes with therapeutic channels.
Strategic Opportunities
- Single-Operator Robotics:Convergence of haptic feedback systems with autonomous navigation reduces staffing requirements and procedural variability.
- India Screening Programs:Underpenetrated colorectal cancer detection infrastructure creates demand for cost-optimized video endoscopy systems.
- IT Infrastructure Integration:PACS and EMR interoperability mandates in the United States favor manufacturers with native hospital information system connectivity.
Industry Challenges
- Specialized Technician Shortage:Reprocessing and maintenance of complex flexible scopes demands certified biomedical engineering talent that health systems struggle to retain.
- Legacy System Interoperability:Hospital capital cycles staggered across generations force vendors to maintain backward compatibility with outdated video processor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal Endoscopy Devices Market |
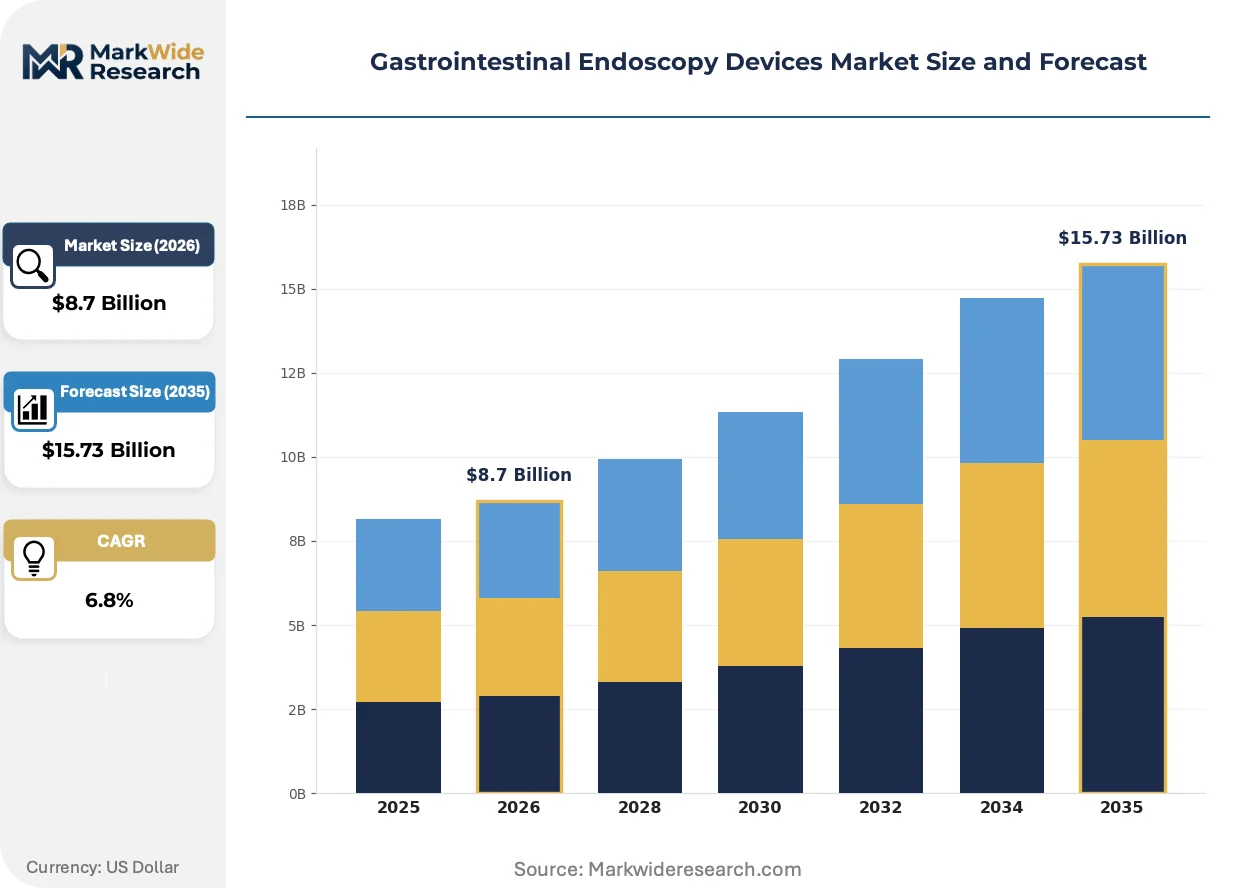
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Biopsy Forceps, Cannulas, Accessories Technology: Optical, Digital, Wireless, Robotic End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Application: Diagnosis, Surgery, Screening, Therapeutics |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Fujifilm Holdings Corporation, Medtronic plc, Johnson & Johnson, KARL STORZ SE & Co. KG, Stryker Corporation, HOYA Corporation, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal Endoscopy Devices Market Emerging Trajectories
Artificial intelligence integration and disposable component architectures are compressing the boundary between diagnostic visualization and real-time therapeutic decision support, restructuring how capital equipment and consumable revenue models interlock.
Computer-aided detection algorithms embedded in video processors are automating polyp identification during colonoscopy, reducing miss rates for diminutive adenomas. Gastroenterology groups in the United States are adopting these systems at accelerating pace as malpractice liability concerns mount. The technology is automating quality benchmarking workflows that previously required manual video review, compressing the interval between procedure completion and documentation.
EU MDR clinical evidence requirements are extending certification timelines for novel endoscope designs, forcing manufacturers to front-load pivotal trials earlier in development cycles. European notified bodies face capacity constraints that create queue bottlenecks for first-time market entrants. Japanese manufacturers with established PMDA technical service networks are redirecting initial launch priority toward domestic and Asian markets while EU dossiers mature.
After-sales service contracts are unbundling from capital equipment purchases as health systems seek operational expenditure flexibility. Independent service organizations are capturing maintenance revenue previously captive to original equipment manufacturers, particularly for video processor and light source repairs. This fragmentation is most pronounced in Germany where hospital procurement consortiums negotiate multi-vendor service aggregation agreements.
Gastrointestinal Endoscopy Devices Market Segmentation
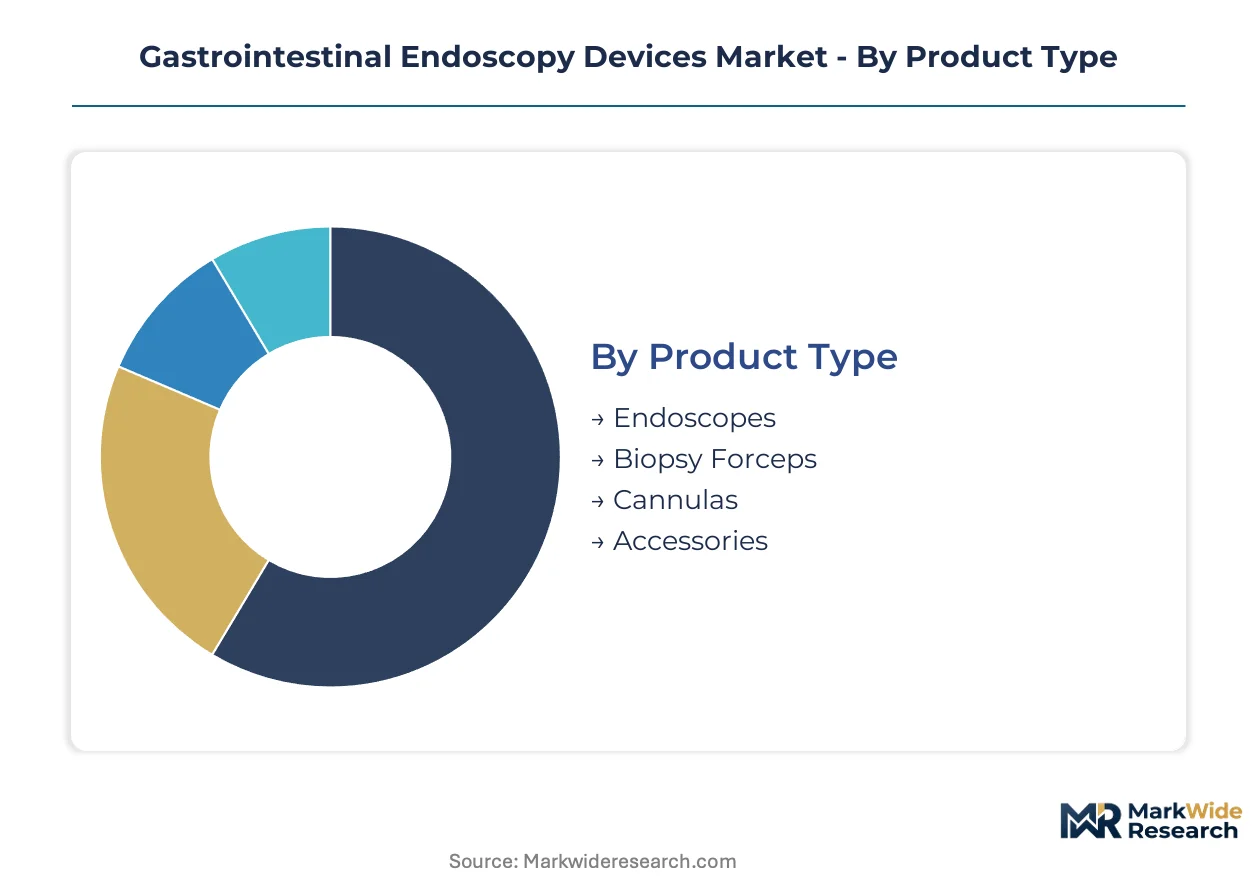
Procurement patterns in gastrointestinal endoscopy diverge sharply between capital-intensive system purchases and high-velocity consumable replenishment. Understanding these segment boundaries clarifies where manufacturers must defend installed base positions versus where they can capture recurring revenue streams.
Product Type:
Capital allocation thresholds determine whether buyers prioritize platform longevity or disposable flexibility in their procurement cycles.
- Endoscopes:Flexible instrument systems with integrated working channels, illumination fibers, and image sensors form the procedural core of every endoscopy suite. Demand concentrates in hospital-based gastroenterology departments across Germany, Japan, and the United States where screening program volumes justify premium digital CMOS configurations and dedicated reprocessing infrastructure.
- Biopsy Forceps:Single-use grasping instruments designed for tissue sampling through endoscope working channels dominate consumable expenditure. Ambulatory surgical centers in the United States favor cost-optimized disposable forceps as procedure migration accelerates toward outpatient settings under site-of-service reimbursement differentials.
- Cannulas:Access devices for fluid delivery, suction, and instrument exchange through endoscope channels.
- Accessories:Ancillary components including irrigation pumps, insufflation units, and bite blocks.
Endoscopes lead on scale; biopsy forceps lead on momentum.
Technology:
Image sensor architecture and procedural automation level separate premium system pricing from value-tier alternatives.
- Digital:CMOS and CCD sensor-based systems with 1080p-plus resolution now dominate new installations across major markets. Hospital procurement in Japan prioritizes PMDA-certified digital platforms with native EMR connectivity to satisfy quality management expectations and IT infrastructure mandates.
- Robotic:Single-operator platforms with haptic feedback and autonomous navigation reduce staffing requirements and procedural variability. FDA 510(k) clearance pathways in the United States are accelerating adoption as malpractice liability concerns drive investment in quality-assurance technology.
- Optical:Legacy fiber bundle systems with limited upgrade paths.
- Wireless:Capsule-based systems eliminating sedation requirements for ambulatory monitoring.
Digital technology leads on scale; robotic systems are expanding most quickly.
End User:
Site-of-service payment differentials and capital cycle flexibility shape purchasing authority across institutional categories.
- Hospitals:Integrated health systems with centralized biomedical engineering departments manage multi-generational endoscope fleets. German hospital procurement consortiums negotiate multi-vendor service aggregation agreements that unbundle maintenance from capital purchases.
- Ambulatory Surgical Centers:Freestanding outpatient facilities expanding endoscopy service lines as reimbursement shifts favor lower-acuity settings. United States ASCs prioritize upgradeable modular platforms over fixed-configuration systems to preserve operational expenditure flexibility.
- Clinics:Physician office-based settings with limited reprocessing infrastructure.
- Research Institutions:Academic medical centers conducting pivotal trials for novel device introductions.
Hospitals lead on scale; ambulatory surgical centers lead on momentum.
Application:
Reimbursement coding precision and clinical outcome metrics determine addressable procedure volumes across therapeutic categories.
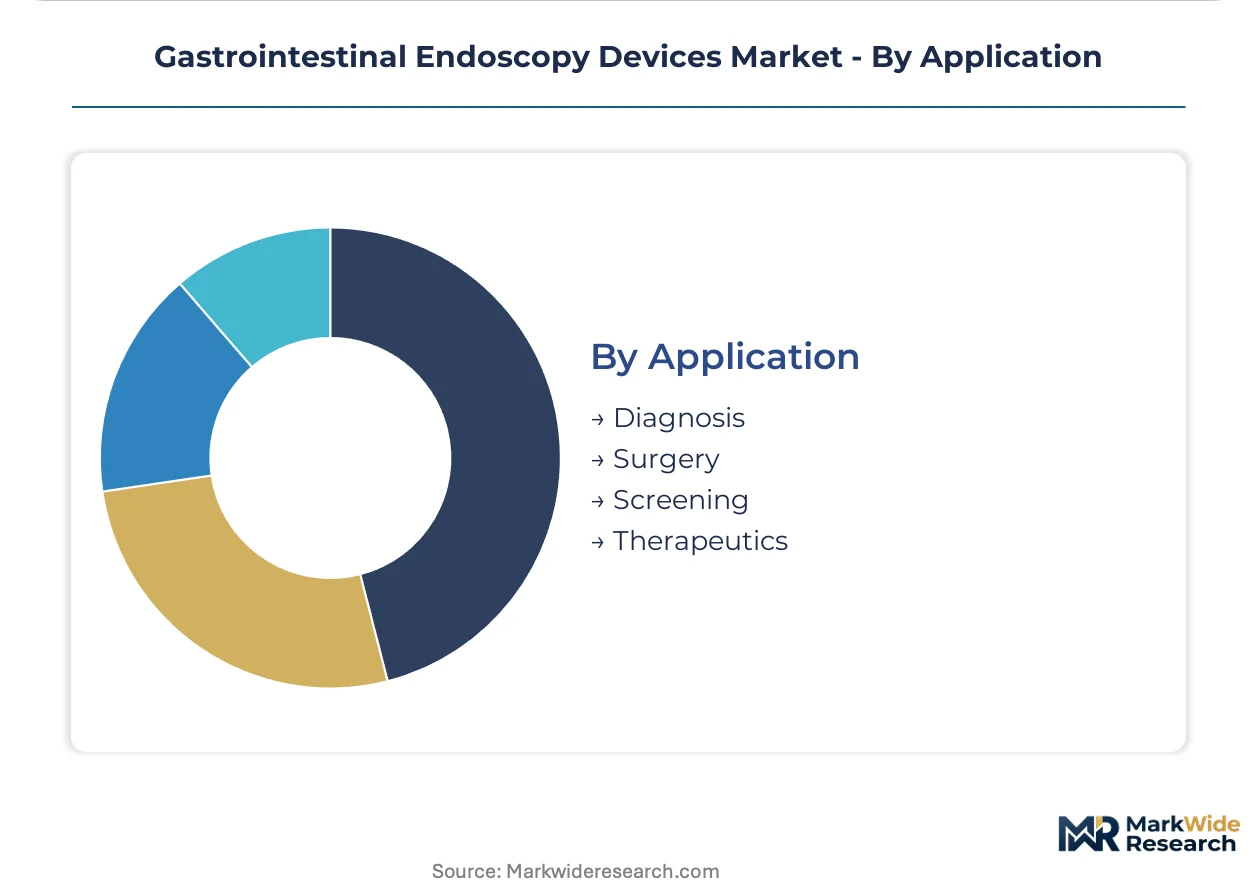
- Diagnosis:Visual examination and tissue sampling procedures generating the foundational revenue base for endoscopy service lines. Screening colonoscopy volumes in Germany sustain procedural growth among populations over sixty-five as national program expansion continues.
- Therapeutics:Interventional procedures including polypectomy, hemostasis, and stricture dilation command premium reimbursement. United States gastroenterology groups are adopting computer-aided detection systems at accelerating pace to reduce miss rates and manage malpractice exposure.
- Surgery:Minimally invasive operative interventions requiring advanced energy platforms.
- Screening:Preventive examination protocols with defined interval recommendations.
Diagnosis leads on scale; therapeutics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial endoscope manufacturing during the 1960s, establishing optical engineering clusters that shaped global quality standards. Japanese firms subsequently scaled CMOS sensor integration, while United States health systems drove demand for outpatient-compatible platforms. Today, national screening programs and reimbursement architectures determine where manufacturers prioritize product launches.
United States
Medicare site-of-service differentials accelerate procedure migration toward ambulatory surgical centers. FDA 510(k) clearance pathways enable faster product refreshes than European certification timelines. The Minneapolis-Saint Paul corridor hosts major service organizations capturing maintenance revenue from hospital procurement consortiums.
Germany
Statutory health insurance screening program expansion sustains procedural volume growth among populations over sixty-five. EU MDR compliance requirements extend certification timelines for novel endoscope designs. The Tuttlingen surgical instrument cluster maintains dense supplier networks for precision metalworking and optical component fabrication.
Japan
PMDA quality management expectations favor manufacturers with established local technical service networks. National colorectal cancer screening mandates drive replacement demand for digital imaging platforms. The Tokyo-Osaka corridor concentrates headquarters operations for integrated optics and video processor manufacturers.
India
Underpenetrated colorectal cancer detection infrastructure creates demand for cost-optimized video endoscopy systems. CDSCO medical device regulations are harmonizing with international standards to accelerate import approvals. The Mumbai-Pune pharmaceutical and device manufacturing belt is expanding cleanroom assembly capacity for disposable endoscopic accessories.
China
NMPA regulatory pathways are streamlining for domestically manufactured Class II and III endoscopic devices. Provincial health commissions are expanding early cancer screening pilots in urban centers. The Suzhou industrial park hosts foreign-invested joint ventures producing CMOS sensor modules and flexible endoscope insertion tubes.
Gastrointestinal Endoscopy Devices Market Vendor Landscape
Premium-margin players sit above commodity-margin players across imaging resolution and service integration capabilities. The vendor base clusters around three strategic archetypes: integrated optics manufacturers with captive sensor fabrication, interventional platform specialists bridging diagnostic and therapeutic workflows, and disposable-focused challengers attacking reprocessing cost structures. Consolidation pressure intensifies as hospitals prioritize multi-generational platform compatibility and subscription-based service flexibility over discrete capital purchases.
Among Japanese-headquartered integrated manufacturers, Olympus Corporation and Fujifilm Holdings Corporation exemplify the optics-captive archetype, while Boston Scientific Corporation represents the interventional platform specialist model. These three anchors occupy positions across the premium-tier spectrum, with Olympus and Fujifilm leveraging vertical control over component supply chains and Boston Scientific concentrating on therapeutic application breadth. Their collective presence shapes procurement negotiations in United States hospital systems and German procurement consortiums, where multi-vendor service aggregation agreements are unbundling traditional equipment-maintenance bundles.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Medtronic plc |
| Johnson & Johnson |
| KARL STORZ SE & Co. KG |
| Stryker Corporation |
| HOYA Corporation |
| Ambu A/S |
| Others |
Supply Flow & Price Mechanics
EU MDR sustainability and clinical evidence mandates gate qualified supply access and premium-tier pricing power, compressing margins for manufacturers lacking established notified body relationships while elevating certification-grade product premiums. Hospitals and ambulatory surgical centers now weight total cost of ownership calculations toward reprocessing efficiency and service contract flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared digital CMOS systems from PMDA-certified platforms and basic fiber-bundle alternatives. Price differentiation hinges on resolution specifications and after-sales service bundling, with Japanese and German procurement consortiums driving unbundling trends. Cost compression in the economy tier intensifies as Indian and Chinese domestic manufacturers scale cleanroom assembly capacity. Ambulatory surgical centers exhibit highest price sensitivity, while integrated hospital systems absorb premium tiers for multi-generational platform compatibility.
Supply Chain Analysis
China's NMPA domestic-content requirements and India's PLI scheme for medical devices are reshaping sourcing patterns for CMOS sensor modules and flexible insertion tubes. Manufacturing concentrates in Japan, Germany, and China, with optical component fabrication anchored in the Tuttlingen and Tokyo-Osaka corridors. Raw material dependencies span precision glass fibers, medical-grade polymers, and semiconductor-grade silicon substrates. Single-source vulnerability in East Asian CMOS foundries threatens input security. Distribution runs through hospital procurement consortiums in Germany, GPO contracts in the United States, and technical service networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastrointestinal endoscopy devices market represents a late-cycle quality story where screening program maturation in Germany and Japan shifts procurement toward premium digital platforms with native EMR connectivity and AI-embedded detection capabilities.
For Market Incumbents: To counter independent service organizations capturing maintenance revenue, Olympus Corporation and Fujifilm Holdings Corporation should deepen captive control over optical component supply chains and expand subscription-based software revenue streams. Backward integration into CMOS sensor fabrication reduces input vulnerability while accelerating FDA 510(k) refresh timelines relative to EU MDR certification queues.
For New Entrants and Emerging Players: Direct-to-ambulatory-surgical-center digital channels offer the most penetrable route for cost-optimized disposable forceps and capsule endoscopy systems. India's underpenetrated colorectal cancer detection infrastructure and CDSCO regulatory harmonization create white-space entry points. Targeting United States ASCs with modular, upgradeable platforms bypasses entrenched hospital procurement consortiums.
For Investors and Strategic Acquirers: Valuations sit cheapest among disposable-focused challengers with reprocessing-cost advantages and robotic platform specialists with single-operator navigation patents. Long-term viability over the next decade hinges on reimbursement parity between hospital and ambulatory settings. The signal to watch is CMS site-of-service payment differential adjustments that would accelerate ASC capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates iterative digital CMOS platform refreshes in United States ASCs. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines but secure premium-tier access for notified body-established manufacturers. |
| Hospital System Partnership | Multi-vendor service aggregation agreements with German procurement consortiums unbundle maintenance from capital purchases. |
| Software Companion Development | Computer-aided detection algorithms embedded in video processors reduce malpractice exposure for United States gastroenterology groups. |
| Reimbursement Strategy | Site-of-service parity advocacy shapes capital deployment priorities across hospital and ambulatory purchasers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement data, and EU MDR notified body certification records. Bottom-up procedure volume estimates and top-down capital expenditure triangulation anchored market sizing across the analysis window.
Segment-weighting approaches modeled product type, technology architecture, end-user site classification, and application purpose throughout the forecast period. CAGRs derived from procedure volume trajectories, replacement cycle compression, and ambulatory migration patterns. Forecast inputs incorporated screening program expansion timelines in Germany and Japan, reimbursement differential evolution in the United States, and CMOS sensor supply capacity utilization.
The model assumes a particular technology adoption path; alternative pathways for robotic single-operator platforms or disposable endoscope architectures would alter the outlook. Forecasts reflect documented assumptions around regulatory clearance timelines, reimbursement stability, and supply chain input availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Endorectal Balloon Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Endoscopic Submucosal Dissection Market