
 Emission Monitoring Systems Market | 2026-2036
Emission Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Monitoring Systems Market Intelligence
The shift towards equipment leasing and monitoring-as-a-service models is reshaping competitive positioning by reducing upfront capital expenditure for end-users. Siemens AG leverages its extensive industrial automation portfolio to offer integrated solutions for large-scale power plants. Meanwhile, Thermo Fisher Scientific Inc. specializes in high-precision analytical instruments for research and regulatory compliance. ABB Ltd. competes through its strong presence in process control systems across the oil and gas sector.
Emission monitoring systems are integrated hardware and software solutions used to measure, analyze, and report pollutants from industrial sources. Core components often include optical sensors or electrochemical cells to quantify specific gases like SOx, NOx, and CO2 in real-time. The Continuous Emission Monitoring segment leads in technology, mandated by regulations for power generation and oil & gas applications. Cloud-based deployment models are gaining traction, offering remote data access and analytics for industrial facilities.
Regulatory bodies such as the US EPA, Europe's ECHA under the EU Green Deal, and China's MEE set the primary compliance targets. These regulations mandate specific monitoring frequencies and accuracy standards, directly shaping product development and market access for system providers. Vendor selection will increasingly hinge on the ability to integrate monitoring data with broader enterprise resource planning and sustainability reporting platforms.
Market Dynamics
The central force shaping the market is the global regulatory clampdown on industrial pollutants. Frameworks from the US EPA, the EU Green Deal, and China's MEE are creating non-negotiable compliance requirements, compelling investment in advanced monitoring technologies across heavy industry.
Growth Catalysts
- Stringent National Mandates:Regulations such as China's "dual carbon goals" and India's emissions standards for thermal power plants are forcing widespread installation of continuous monitoring systems to meet national air quality targets.
- Power Generation Sector Compliance:The global power generation industry faces intense scrutiny over SOx, NOx, and mercury emissions, making real-time monitoring essential for operational permits and avoiding significant financial penalties.
- Sensor Technology Advancement:The development of more durable and sensitive optical and electrochemical sensors allows for the accurate detection of a wider range of pollutants at lower concentrations, expanding the addressable market.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for purchasing, installing, and commissioning a complete Continuous Emission Monitoring System (CEMS) remains a primary barrier, especially for smaller industrial operators.
- Operational Complexity:Systems require regular calibration and maintenance by skilled technicians to ensure data accuracy in harsh industrial environments with high temperatures, moisture, and corrosive gases, increasing total cost of ownership.
- Component Supply Concentration:A limited number of specialized manufacturers produce critical components like analytical gas sensors and optical detectors, creating potential supply chain vulnerabilities and pricing power for those suppliers.
Strategic Opportunities
- Emerging Market Industrialization:Rapidly industrializing economies in Southeast Asia and Africa represent significant growth areas as they begin to formulate and enforce their first comprehensive air quality and industrial emission regulations.
- Maritime and Aviation Sectors:New international regulations from bodies like the IMO targeting emissions from shipping and aviation are creating entirely new end-use segments for specialized mobile and onboard monitoring systems.
- Predictive Analytics Integration:Integrating monitoring data with AI and machine learning platforms offers a major opportunity for value-added services, including predictive maintenance alerts, process optimization, and automated compliance reporting.
Industry Challenges
- Legacy System Integration:A significant challenge lies in integrating modern, data-intensive monitoring systems with older, disparate plant control systems and IT infrastructure, which can lead to complex and costly implementation projects.
- Data Interoperability Standards:The lack of universal data formats and communication protocols between different vendor systems complicates enterprise-wide emissions management and benchmarking for multinational corporations operating across various regulatory jurisdictions.
- Shortage of Technical Expertise:A persistent shortage of technicians and engineers with the dual expertise in analytical instrumentation and environmental regulation hinders the effective operation and maintenance of advanced monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Monitoring Systems Market |
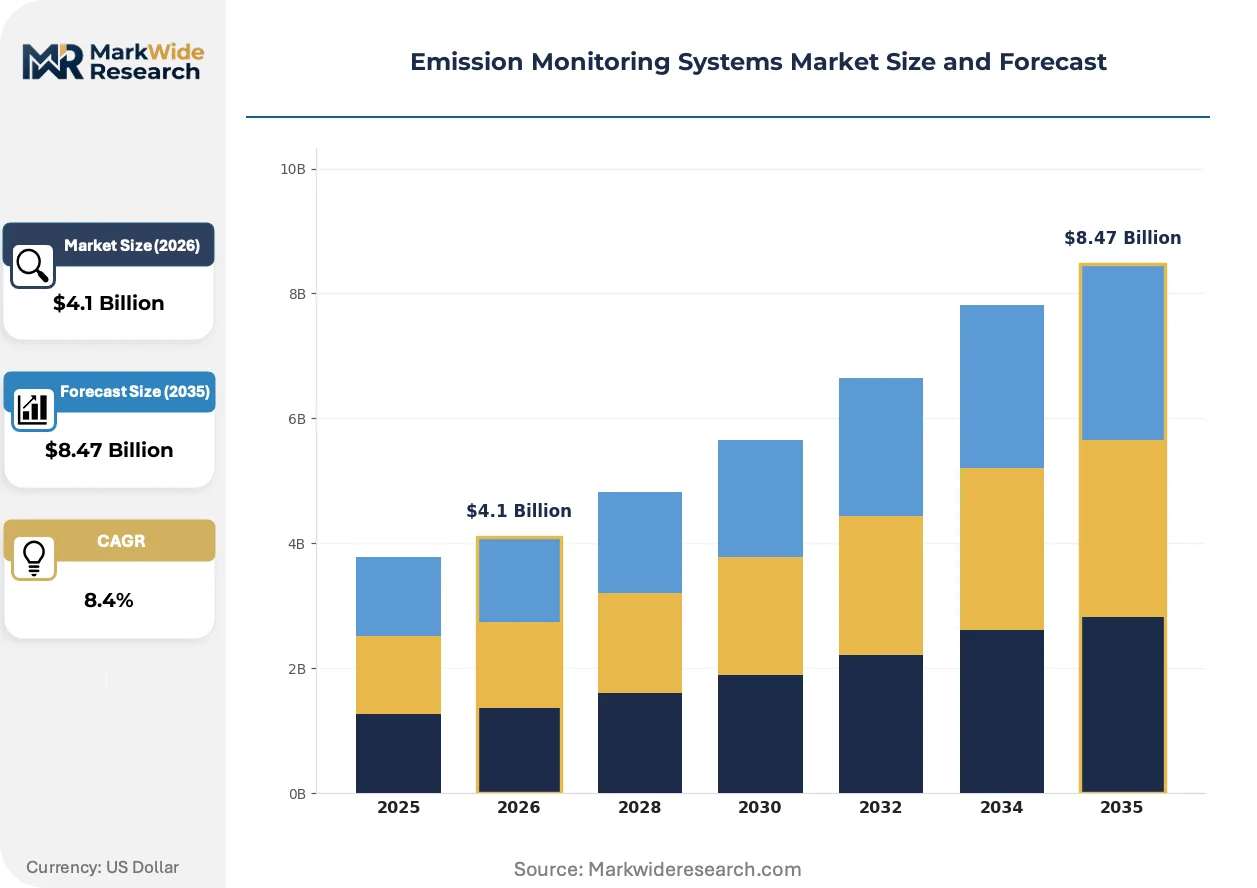
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Continuous Emission Monitoring, Extractive Monitoring, In-Situ Monitoring, Passive Sampling Application: Power Generation, Oil & Gas, Manufacturing, Waste Management End User: Industrial Facilities, Environmental Agencies, Utility Companies, Research Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Siemens AG, Horiba Ltd., ABB Ltd., General Electric Company, Fuji Electric Co., Ltd., AMETEK, Inc., Thermo Fisher Scientific Inc., Rockwell Automation, Inc., Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Monitoring Systems Market Strategic Shifts & Innovations
A fundamental shift is underway from using monitoring systems purely for regulatory compliance to leveraging their data for operational intelligence. This evolution transforms emissions data from a cost center into an asset for improving process efficiency and demonstrating sustainability commitments to stakeholders.
Non-dispersive infrared (NDIR) sensors provide a reliable method for quantifying greenhouse gases like carbon dioxide and methane. Heavy industries such as cement manufacturing and oil and gas are adopting NDIR technology for both regulatory reporting and process control. The trend toward miniaturized, solid-state sensor designs is collapsing the cost and complexity barrier between high-end compliance systems and distributed process monitoring networks.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory driver. It mandates that large companies provide detailed, audited reports on their environmental impact, including granular emissions data. This directly impacts chemical, manufacturing, and energy sectors, which now must invest in monitoring systems capable of producing verifiable, investment-grade data for their public disclosures.
A transition from one-time capital equipment sales to recurring revenue models is gaining traction. This involves "Monitoring-as-a-Service" (MaaS) or equipment leasing, which disrupts the traditional distributor-led sales channel for capital-intensive systems. This service-oriented model is most visible in North America and Europe, where it enables mid-sized industrial plants to access advanced technology by converting a large capital expense into a predictable operational one.
Emission Monitoring Systems Market Segmentation
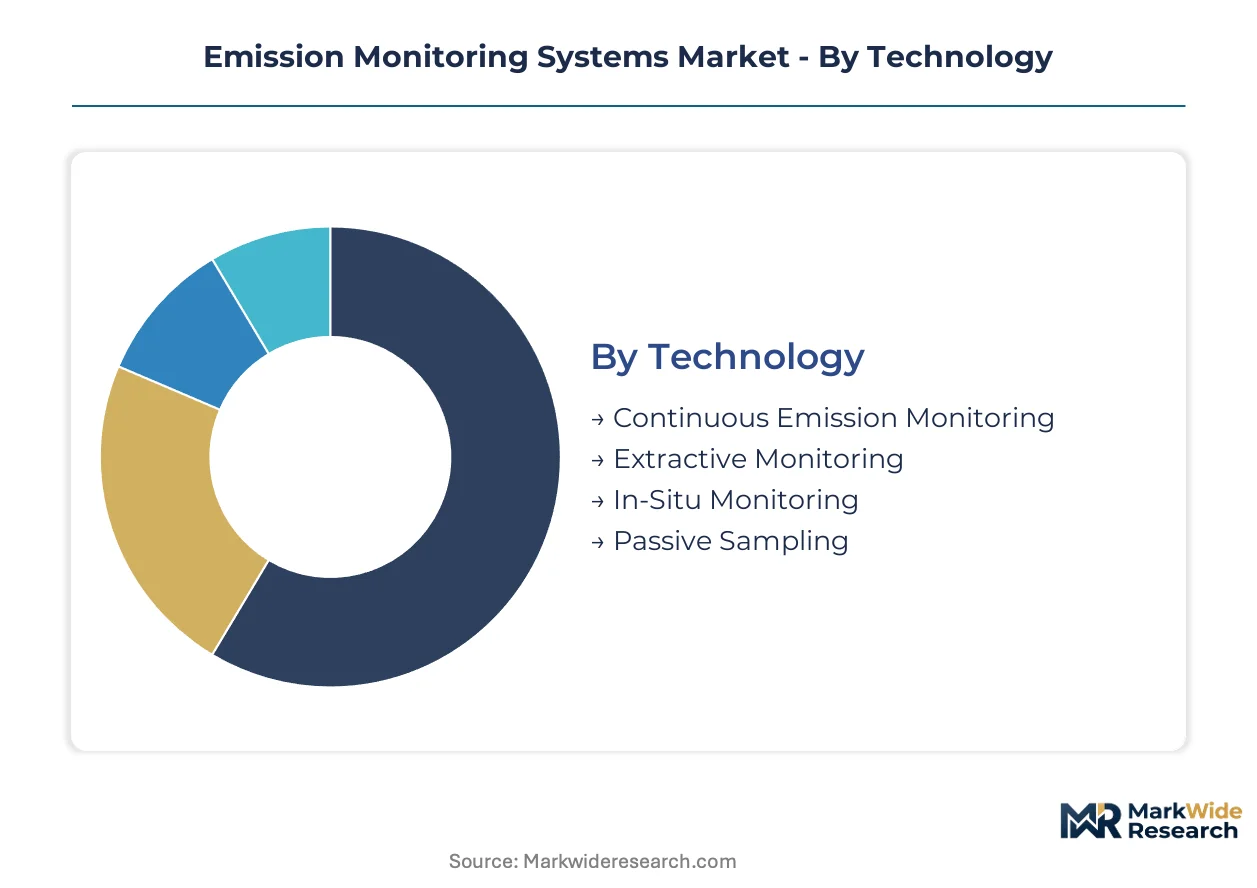
The Emission Monitoring Systems market segmentation provides a granular view of diverse technological approaches, application areas, and end-user requirements. Understanding these distinct segments is critical for manufacturers to tailor solutions that meet specific regulatory mandates and operational demands across various industrial sectors.
Technology:
The turnover rate for emission monitoring technologies varies significantly, with some systems offering rapid, real-time data while others provide periodic or integrated measurements. This influences both initial investment and ongoing operational costs for industrial operators seeking compliance and process optimization.
- Continuous Emission Monitoring:These systems provide real-time, uninterrupted measurement of pollutant concentrations directly from industrial stacks. Regulatory bodies like the US EPA and Europe's ECHA mandate CEMS for major industrial emitters, driving significant demand in the power generation sector.
- In-Situ Monitoring:This method involves placing sensors directly within the gas stream, offering immediate data without the need for gas extraction or conditioning. Demand for in-situ systems is expanding in applications requiring rapid response times and minimal sample interference, particularly in the oil and gas industry.
- Extractive Monitoring:Gas samples are drawn from the stack, conditioned, and then analyzed by instruments located remotely. This approach allows for detailed analysis of multiple gases and is widely used in complex industrial processes within chemical manufacturing facilities.
- Passive Sampling:This technique involves exposing a sorbent material to the ambient air or exhaust stream over a period to collect pollutants for later laboratory analysis. Passive sampling offers a cost-effective solution for long-term average concentration monitoring in less regulated or remote industrial sites.
Continuous Emission Monitoring anchors the volume base while In-Situ Monitoring gains share at the steepest rate.
Application:
Emission monitoring systems are deployed across various industrial applications, each presenting unique challenges related to gas composition, temperature, and regulatory frameworks. The specific application dictates the required sensor type, measurement range, and data reporting capabilities.
- Power Generation:This sector requires robust systems for monitoring SOx, NOx, CO2, and particulate matter to comply with stringent national mandates, such as those from China's MEE and India's Central Electricity Authority. Real-time data ensures operational permits are maintained and financial penalties are avoided.
- Oil & Gas:Continuous monitoring of methane, CO2, and other volatile organic compounds is essential for both environmental compliance and process efficiency in upstream and downstream operations. ABB Ltd. provides process control systems that integrate emission data for enhanced operational intelligence.
- Manufacturing:Diverse manufacturing processes, from cement to chemicals, require monitoring of various pollutants depending on their specific emissions profile. Systems help these facilities meet regional air quality standards and adhere to local environmental protection agency guidelines.
- Waste Management:Landfills and incineration plants utilize emission monitoring to track methane, dioxins, and furans, ensuring compliance with health and safety regulations. These applications often require specialized sensors capable of handling corrosive and high-moisture environments.
Power Generation represents the largest application segment, while Waste Management shows a strong expansion trajectory.
End User:
The end-user landscape for emission monitoring systems is diverse, ranging from large industrial operators to governmental bodies and research institutions. Each end-user type has distinct purchasing criteria, operational needs, and regulatory compliance obligations.
- Industrial Facilities:These entities, including power plants and manufacturing sites, are the primary purchasers, driven by strict environmental regulations and the need for operational intelligence. They seek integrated solutions that can report emissions data for sustainability reporting and process optimization.
- Utility Companies:Responsible for electricity generation and distribution, these companies invest in advanced monitoring systems to ensure continuous compliance with air quality permits. They face intense scrutiny over emissions of SOx, NOx, and mercury, making real-time data essential for avoiding penalties.
- Environmental Agencies:Governmental bodies like the US EPA and Europe's ECHA utilize monitoring systems for enforcement, policy development, and assessing regional air quality. Their demand focuses on high-accuracy, verifiable data for regulatory oversight.
- Research Institutions:Universities and private research organizations employ emission monitoring systems for scientific studies on atmospheric chemistry, climate change, and the development of new sensor technologies. They often require highly precise analytical instruments.
Industrial Facilities form the foundational demand, with Utility Companies exhibiting considerable investment in advanced systems.
Deployment:
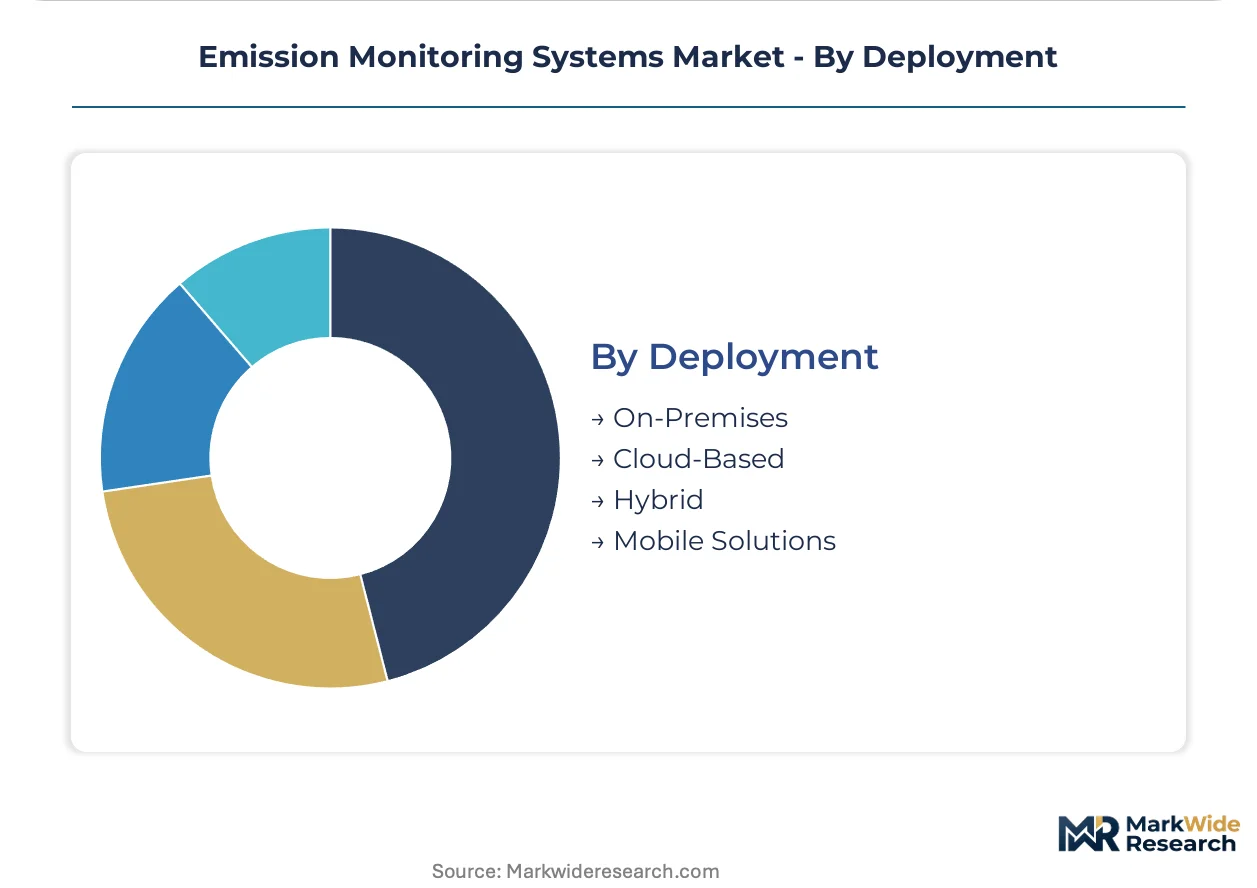
Deployment models for emission monitoring systems are evolving, offering varying degrees of flexibility, data accessibility, and infrastructure requirements. The choice of deployment depends on factors like data security needs, existing IT infrastructure, and the desire for remote management capabilities.
- Cloud-Based:This model offers remote data access, advanced analytics, and scalability by hosting monitoring software and data on cloud servers. Cloud-based deployments are gaining traction among industrial facilities seeking to leverage AI and machine learning for predictive maintenance and automated compliance reporting.
- Hybrid:Combining elements of both on-premises and cloud solutions, hybrid deployments allow sensitive data to remain local while leveraging cloud resources for analytics and scalability. This model provides a balance between data security, control, and remote accessibility, appealing to organizations with specific data governance requirements.
- On-Premises:Systems are installed and managed directly on the end-user's site, providing maximum control over data security and system customization. On-premises solutions are common in large industrial plants with established IT infrastructure and stringent data sovereignty policies.
- Mobile Solutions:These involve portable or vehicle-mounted monitoring systems used for temporary assessments, leak detection, or monitoring emissions from mobile sources. Mobile solutions are crucial for environmental agencies conducting field inspections and for specialized applications in the maritime and aviation sectors.
On-Premises deployment maintains a significant presence, while Cloud-Based solutions are rapidly transforming data management practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global emission monitoring systems market exhibits a dynamic interplay between regulatory drivers and technological supply across continents. Demand for advanced monitoring solutions is often driven by stringent national mandates, while manufacturing and innovation hubs provide critical system components. This global balance shapes investment and deployment patterns in key industrial regions.
United States
Demand for emission monitoring systems in the United States stems from strict environmental regulations across power generation and oil & gas sectors. The US EPA mandates continuous emission monitoring, compelling industrial facilities to invest in advanced technologies. Industrial clusters in Texas and Louisiana, particularly within the petrochemical and refining industries, are significant deployment sites.
Germany
Germany's market is propelled by robust industrial manufacturing and stringent European environmental policies. The EU Green Deal and ECHA regulations drive the adoption of sophisticated monitoring systems in chemical and energy sectors. Industrial regions like North Rhine-Westphalia, with its dense concentration of heavy industry, are key areas for system integration.
China
China's rapid industrialization and ambitious environmental targets create substantial demand for emission monitoring solutions. The Ministry of Ecology and Environment (MEE) enforces strict air quality standards, including "dual carbon goals," for thermal power plants and factories. Major industrial zones such as the Yangtze River Delta are implementing widespread continuous monitoring systems.
India
India's market expansion is driven by increasing industrial activity and evolving national emissions standards for thermal power plants. The Central Electricity Authority (CEA) mandates continuous monitoring to address air quality concerns. Industrial corridors in Gujarat and Maharashtra, home to numerous manufacturing and power facilities, are seeing significant deployments of advanced systems.
Brazil
Brazil presents a growing market for emission monitoring systems, particularly in its mining, oil & gas, and manufacturing sectors. National environmental protection agencies enforce specific emission limits, spurring investment in compliance technologies. Industrial hubs in São Paulo and Minas Gerais are adopting new monitoring systems to meet regulatory requirements.
Emission Monitoring Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing critical hardware. The market for emission monitoring systems is tiered, encompassing comprehensive solution providers and niche technology developers. Archetypes include large industrial automation conglomerates, specialized analytical instrument manufacturers, and emerging software-as-a-service firms. Competitive moves frequently involve strategic partnerships for integrated offerings and technology licensing to expand product portfolios.
Large industrial conglomerates, such as Germany-based Siemens AG and Switzerland-based ABB Ltd., exemplify the integrated solutions archetype, leveraging extensive automation portfolios across power generation and oil & gas. These entities often provide end-to-end monitoring and control systems, integrating hardware, software, and services for complex industrial facilities. Meanwhile, US-based Thermo Fisher Scientific Inc. represents the specialized analytical instrument segment, focusing on high-precision devices crucial for regulatory compliance and research applications. This differentiation allows for tailored offerings, from broad enterprise-level deployments to highly specific pollutant analysis.
| Leading Market Players |
|---|
| Siemens AG |
| Horiba Ltd. |
| ABB Ltd. |
| General Electric Company |
| Fuji Electric Co., Ltd. |
| AMETEK, Inc. |
| Thermo Fisher Scientific Inc. |
| Rockwell Automation, Inc. |
| Emerson Electric Co. |
Cost & Logistics Intelligence
Under-utilized manufacturing capacity for specialized sensors in Europe and Asia drives supplier behavior, influencing pricing power for critical components. This concentration impacts the overall cost structure for integrated emission monitoring systems.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure, combining project-based system sales with recurring revenue from Monitoring-as-a-Service subscriptions. Price differentiation stems from the level of system integration with enterprise platforms and the specific regulatory compliance certifications achieved. Cost compression in advanced systems is intensifying due to the shift towards service-oriented models, particularly for mid-sized industrial plants. Smaller industrial operators exhibit higher price sensitivity compared to large utility companies requiring continuous, verifiable data.
Supply Chain Analysis
Specialized analytical gas sensors and optical detectors form the upstream feedstock for emission monitoring systems. Supply concentrates in advanced manufacturing hubs such as Germany, Japan, and the United States, where a limited number of manufacturers produce these critical components. This concentration creates a single-source vulnerability, impacting system lead times and overall costs. Distribution runs through a mix of traditional distributor networks for capital equipment and direct channels for Monitoring-as-a-Service offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emission monitoring systems market presents a fragmentation opportunity, driven by new demand-side shifts such as specialized requirements from the maritime and aviation sectors. This creates distinct niches for tailored technological solutions.
For Market Incumbents: Insulate core market share by leveraging extensive industrial automation portfolios to offer integrated hardware and software solutions. Deepen vertical integration into specialized sensor manufacturing to mitigate supply chain vulnerabilities. Invest significantly in R&D for predictive analytics and AI integration, transforming emissions data into operational intelligence to counter emerging software-as-a-service threats. Control distribution channels by expanding "Monitoring-as-a-Service" offerings in North America and Europe.
For New Entrants and Emerging Players: Pursue underpenetrated segments by offering cloud-native, Monitoring-as-a-Service solutions that reduce upfront capital expenditure for mid-sized industrial plants. Target rapidly industrializing economies in Southeast Asia and Africa, which are formulating first-generation air quality regulations. A go-to-market angle focused on simplified deployment, remote data access, and automated compliance reporting can gain rapid traction. Specialize in mobile solutions for nascent maritime and aviation monitoring needs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-sized industrial plants, driven by the shift to service-oriented models, signaling a long-term shift in value capture. The market offers sustained viability due to non-negotiable global regulatory compliance requirements over the next decade. Identify acquisition targets among specialized analytical instrument manufacturers with strong IP in sensor technology or software firms excelling in predictive analytics. The signal to watch is the increasing proportion of recurring revenue in vendor financial statements.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Monitoring-as-a-Service Offerings | Reduces upfront capital barriers for end-users, accelerating advanced system adoption in mid-tier industries. |
| Acquire AI/ML Analytics Platform Provider | Integrates predictive maintenance and process optimization capabilities, enhancing data value for industrial facilities. |
| Invest in Miniaturized Sensor R&D | Lowers cost and complexity barriers, enabling broader deployment of distributed monitoring networks. |
| Certify Systems for Maritime Regulations | Unlocks new end-use segments by meeting specialized compliance requirements for mobile emission sources. |
| Form Partnerships in Emerging Economies | Facilitates market access and localized service delivery for industrializing regions like Southeast Asia. |
Research Approach
Operator-level perspectives from plant managers, environmental compliance officers, and R&D directors anchored the qualitative base, supplemented by in-depth interviews with technology specialists. This primary fieldwork was validated against extensive secondary research, including US EPA reports, EU ECHA documents, and China MEE publications. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all market segments.
Scenario-bracketing provided a robust framework for projecting market growth across the analysis window, considering various regulatory and technological adoption rates. The modeling incorporated segmentation dimensions including technology, application, end-user, deployment model, and specific pollutant types. Compound Annual Growth Rates were derived through a multi-variate regression analysis, integrating inputs such as evolving national emissions standards and the pace of sensor technology advancements.
Macroeconomic conditions sit as an overlay; deviation in global industrial production output or energy demand would shift the trajectory. Forecasts reflect documented assumptions, acknowledging specific risk factors such as geopolitical instability impacting critical component supply chains. Cross-checking against IEA reports and World Bank industrial output data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
Smart Water Monitoring Market