
 Water Quality Analyzer Market | 2026-2036
Water Quality Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Water Quality Analyzer Market Intelligence
Modular sensor bundling is repositioning how treatment plants configure monitoring suites, letting buyers swap analytical cartridges without replacing entire instruments. Danaher Corporation leverages its diagnostics platform breadth to anchor high-throughput municipal contracts. Xylem Inc. competes through vertical integration into telemetry and cloud-based data layers. Thermo Fisher Scientific Inc. differentiates by sustaining R&D intensity in portable mass spectrometry for field contaminant identification.
A water quality analyzer is an electrochemical or photometric instrument that measures parameters such as dissolved oxygen, turbidity, pH, and heavy metal concentration to verify compliance with safety and environmental thresholds. Online analyzers with automated sampling and digital protocol outputs now dominate capital expenditure among municipal water authorities, while handheld units with Bluetooth data logging represent the fastest-growing configuration for field audits and emergency response. Spectrophotometry-based systems command premium positioning due to multi-analyte capability, whereas electrochemical sensors retain volume leadership in process control loops where drift tolerance and electrode longevity determine total cost of ownership.
The EPA Safe Drinking Water Act and EU Drinking Water Directive enforce maximum contaminant levels that mandate continuous analyzer verification, while China's MEE discharge standards for industrial effluent create compliance-driven replacement cycles. ISO 15839 for online analyzers and WEF guidelines for wastewater monitoring further shape product certification requirements and procurement specifications. Stakeholders must weigh sensor interoperability standards against vendor lock-in risks as utilities consolidate data platforms.
Market Dynamics
Optical sensor miniaturization is compressing maintenance budgets for continuous monitoring networks while tightening EU Drinking Water Directive enforcement accelerates capital replacement cycles among municipal authorities.
Growth Catalysts
- EU Drinking Water Directive:Tightened maximum contaminant thresholds across Germany, France, and Netherlands are compelling municipal authorities to deploy online analyzers with automated sampling capabilities.
- China's MEE discharge standards:Real-time effluent verification mandates in industrial corridor cities are forcing manufacturing facilities to install spectrophotometry-based multi-analyte systems.
- Bluetooth-enabled handheld units:Field audit protocols for emergency response teams are standardizing around portable analyzers with wireless data logging for immediate compliance documentation.
Market Restraints
- Electrode longevity limitations:Electrochemical sensors in process control loops require frequent recalibration, elevating total cost of ownership above photometric alternatives.
- Specialized reagent supply concentration:High-purity chemical consumables for spectrophotometric analysis concentrate production in Germany and Switzerland, exposing buyers to currency and logistics volatility.
- ISO 15839 certification timelines:Extended validation periods for online analyzer compliance delay product launches and compress revenue recognition windows.
Strategic Opportunities
- India's Ganga rejuvenation infrastructure:Central Pollution Control Board mandates for river basin monitoring are opening tenders for telemetry-integrated analyzer networks.
- Cloud-based data layer convergence:Municipal utilities are unifying sensor outputs with SCADA platforms, creating subscription revenue streams for predictive maintenance analytics.
- Portable mass spectrometry field identification:Contaminant fingerprinting at industrial accident sites represents an emerging application beyond laboratory-bound instrumentation.
Industry Challenges
- Electrochemical drift calibration expertise:Utilities face acute shortages of technicians capable of maintaining electrode-based process control loops within tolerance bands.
- Legacy analog protocol integration:Municipal treatment plants with decades-old SCADA architectures struggle to interface digital-output analyzers without middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Quality Analyzer Market |
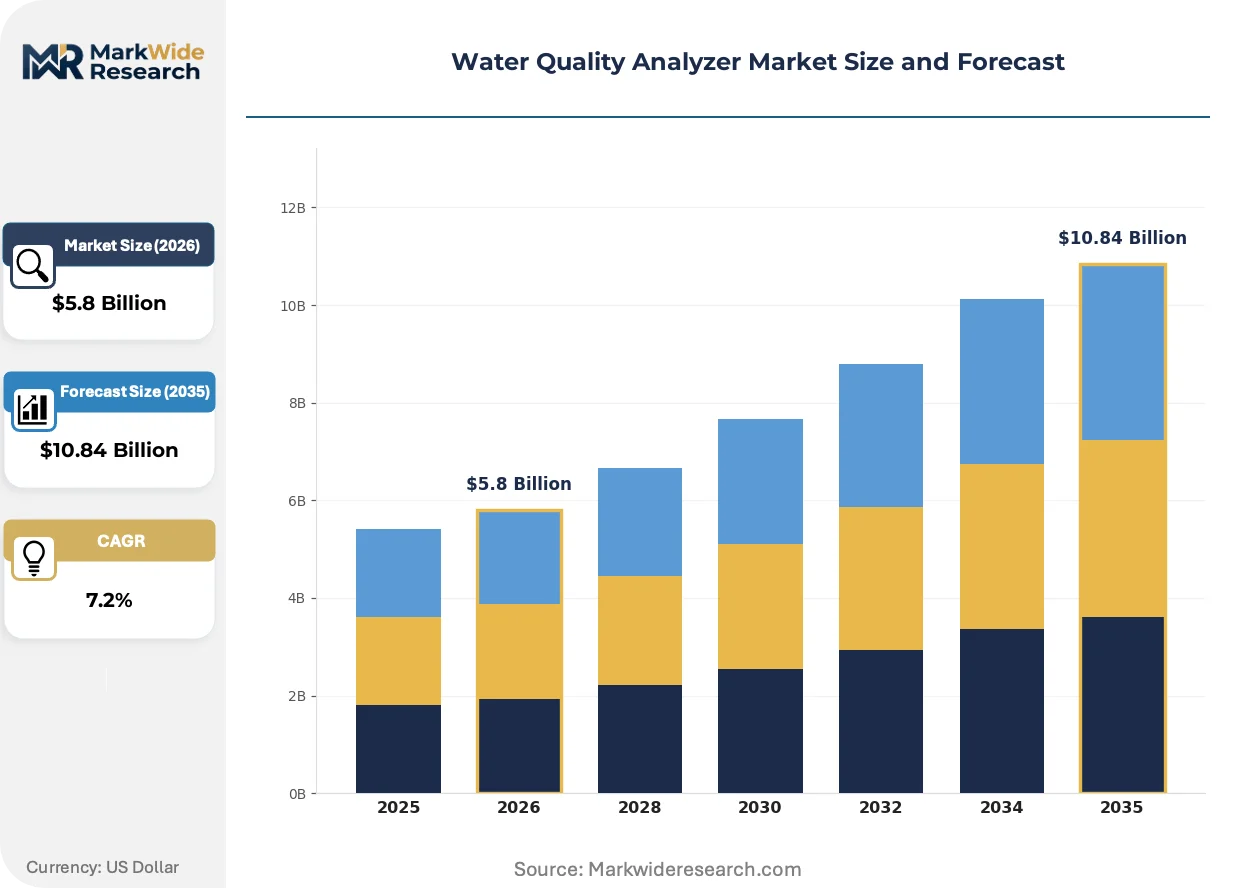
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.84 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Online, Handheld, Multiparameter Technology: Spectrophotometry, Electrochemical, Optical, Conductivity, Fluorometry Application: Drinking Water Testing, Wastewater Monitoring, Aquaculture, Environmental Research, Industrial Process Control End User: Municipal Water Authorities, Food & Beverage Plants, Research Institutions, Agriculture Facilities |
| Companies Covered | Danaher Corporation, Xylem Inc., Thermo Fisher Scientific Inc., ABB Ltd., Emerson Electric Co., Endress+Hauser Group, HORIBA Ltd., Siemens AG, Evoqua Water Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Quality Analyzer Market Strategic Shifts & Innovations
Spectrophotometric platforms are absorbing electrochemical functions while regulatory mandates harden around continuous verification rather than periodic sampling.
Multi-parameter optical sensors are unifying dissolved oxygen, turbidity, and heavy metal detection within single cartridge architectures. German municipal authorities are adopting these consolidated instruments at accelerated replacement cycles. This convergence is unifying vendor service contracts and compressing procurement decision timelines from multi-vendor evaluations to single-source negotiations.
REACH chemical registration requirements are restricting reagent formulations used in colorimetric analysis across European manufacturing facilities. Industrial laboratories must validate alternative indicator chemistries or absorb higher compliance documentation costs. Wastewater treatment operators in Belgium and Denmark are responding by pre-qualifying suppliers with established substance dossiers.
Analyzer-as-a-service contracting is displacing capital purchase models among mid-sized municipal utilities. Danish water authorities now specify outcome-based agreements where vendors retain ownership and guarantee uptime percentages. This restructuring concentrates most visibly in Scandinavia where public procurement rules favor operational expenditure frameworks over bonded capital projects.
Water Quality Analyzer Market Segmentation
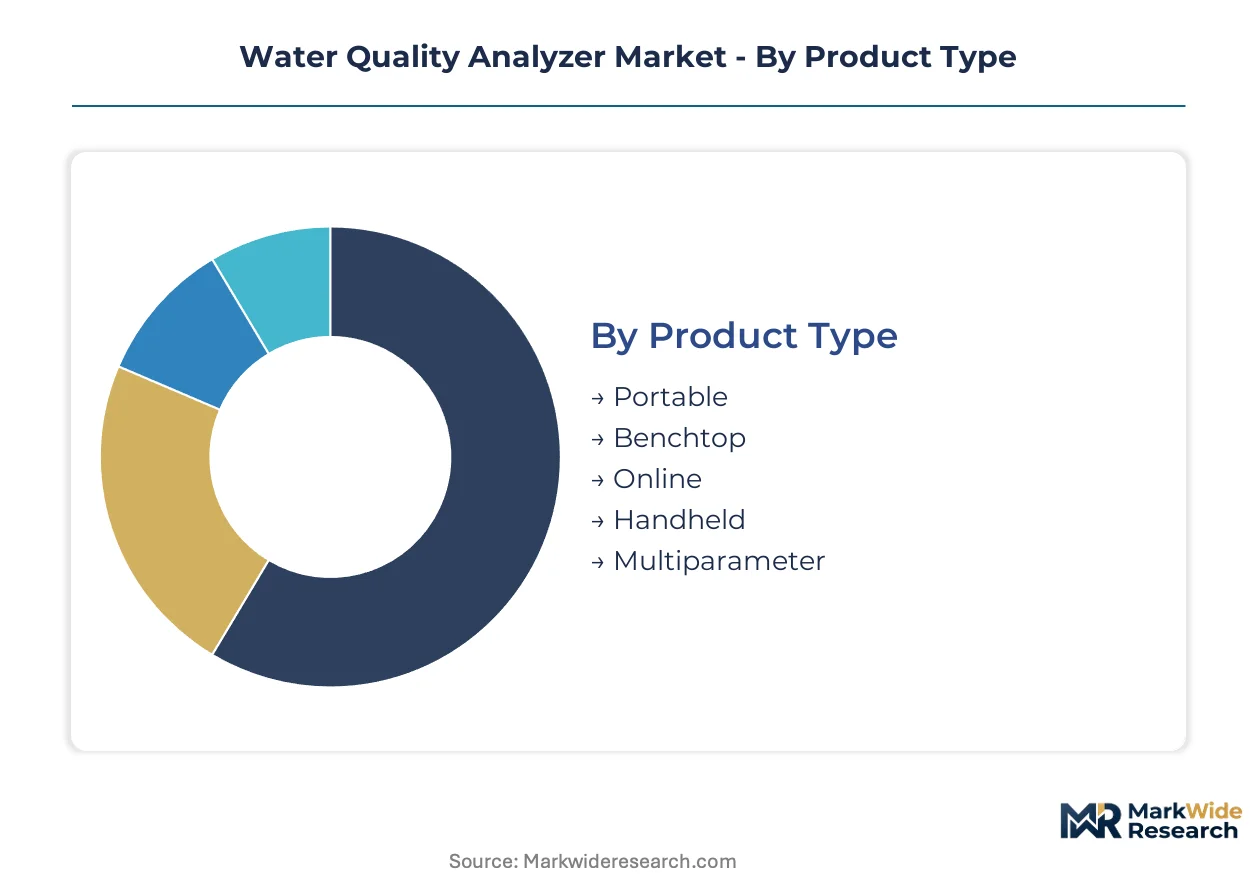
Water quality analyzer purchasing patterns diverge sharply between compliance-driven municipal buyers optimizing for uptime guarantees and industrial operators prioritizing multi-analyte throughput. Technology selection, form factor, and service contracting terms all pivot on these underlying buyer economics.
Product Type:
Form factor selection separates continuous process integration from episodic field deployment, with capital intensity and maintenance liability distributed differently across configurations.
- Portable:Battery-powered units with integrated data logging serve emergency response teams and remote site audits. Denmark's municipal authorities specify Bluetooth-enabled portables for field crews verifying distribution network integrity after main breaks.
- Benchtop:Laboratory-grade instruments with automated sample handling dominate certified testing laboratories. German environmental labs under EU Drinking Water Directive enforcement rely on benchtop spectrophotometry for official compliance documentation.
- Online:Permanently installed analyzers with digital protocol outputs anchor continuous monitoring networks. China's industrial corridor cities mandate online deployment for real-time effluent verification under MEE discharge standards.
- Handheld:Single-parameter probes with simplified interfaces target agricultural and small utility operators. India's Central Pollution Control Board tenders specify handheld units for river basin monitoring stations.
- Multiparameter:Consolidated cartridges measuring dissolved oxygen, turbidity, and pH within single housings reduce procurement complexity. Scandinavian water authorities favor multiparameter instruments for unified vendor service contracts.
Online analyzers lead volumes today; handheld units are gaining share fastest.
Technology:
Measurement principle determines reagent dependency, calibration frequency, and capital recovery timelines, creating distinct total cost of ownership profiles across buyer segments.
- Spectrophotometry:Multi-analyte systems using absorbance-based detection command premium positioning for complex contaminant matrices. Industrial facilities in Belgium and the Netherlands deploy spectrophotometry for heavy metal verification under REACH-aligned discharge permits.
- Electrochemical:Electrode-based sensors with drift tolerance limitations retain cost leadership in process control loops where electrode longevity determines maintenance budgets.
- Optical:Miniaturized photometric sensors with reduced moving parts compress maintenance intervals for continuous networks. German municipal authorities accelerate replacement cycles toward optical platforms.
- Conductivity:Ion-selective measurement for salinity and total dissolved solids monitoring serves aquaculture and desalination operators.
- Fluorometry:Fluorescence-based detection for organic compound tracing supports environmental research and pharmaceutical effluent monitoring.
Electrochemical technology anchors current installed base; optical platforms are expanding most quickly.
Application:
Regulatory enforcement intensity and penalty structures create divergent willingness-to-pay across compliance contexts, with drinking water mandates commanding premium pricing relative to industrial self-monitoring.
- Drinking Water Testing:Maximum contaminant level verification under EPA Safe Drinking Water Act and EU Drinking Water Directive mandates continuous analyzer deployment. Municipal authorities in France and Germany specify automated sampling capabilities for distribution network surveillance.
- Wastewater Monitoring:Effluent discharge permits drive spectrophotometry adoption for multi-parameter compliance documentation. China's MEE standards force manufacturing facilities toward real-time verification systems.
- Aquaculture:Dissolved oxygen and ammonia monitoring for intensive farming operations favors electrochemical sensor economics.
- Environmental Research:Portable mass spectrometry and fluorometry support field contaminant fingerprinting beyond laboratory boundaries.
- Industrial Process Control:Closed-loop chemical dosing applications prioritize electrode longevity and drift stability over multi-analyte breadth.
Drinking water testing commands revenue concentration; wastewater monitoring shows steepest expansion trajectory.
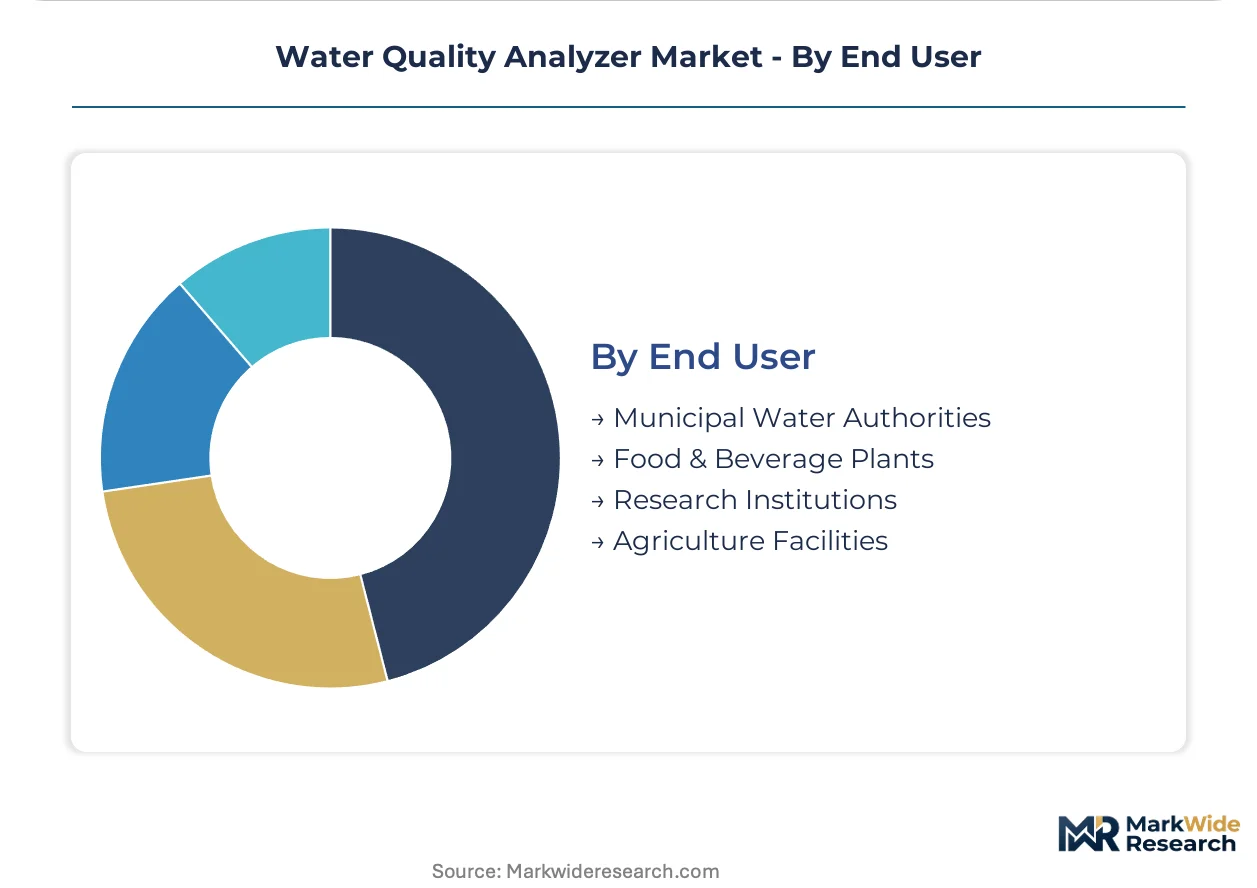
End User:
Procurement sophistication and service contracting preferences segment the customer base, with municipal authorities consolidating toward outcome-based agreements while industrial buyers retain capital purchase discipline.
- Municipal Water Authorities:Public utilities under tightening EU Drinking Water Directive enforcement dominate online analyzer demand. Danish authorities now specify analyzer-as-a-service contracts with guaranteed uptime percentages rather than capital purchases.
- Food & Beverage Plants:Process water and effluent monitoring requirements under ISO standards and national food safety regulations drive benchtop and online deployment.
- Research Institutions:Academic and government laboratories prioritize portable mass spectrometry and fluorometry for method development and field validation studies.
- Agriculture Facilities:Irrigation water quality and nutrient runoff monitoring for large-scale operations favors handheld and portable electrochemical platforms.
Municipal water authorities dominate current procurement volume; food and beverage plants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water quality analyzer manufacturing originated in German industrial centers during the 1970s environmental regulatory wave, with Ruhr Valley engineering firms pioneering continuous monitoring instrumentation for wastewater treatment compliance.
Germany
Municipal water authorities in North Rhine-Westphalia and Bavaria are accelerating online analyzer deployment under tightened EU Drinking Water Directive enforcement. The Federal Environment Agency mandates real-time distribution network surveillance. Ruhr Valley treatment plants now specify multi-parameter optical sensors with unified vendor service contracts.
China
Industrial corridor cities in the Yangtze River Delta and Pearl River Delta drive demand for spectrophotometry-based effluent verification systems. MEE discharge standards now require real-time monitoring for heavy metals and organic compounds. Manufacturing facilities in Suzhou and Shenzhen face compliance-driven replacement cycles for legacy sampling equipment.
United States
EPA Safe Drinking Water Act enforcement compels municipal utilities toward automated sampling capabilities with digital protocol outputs. Utilities in California and Texas consolidate procurement toward analyzer-as-a-service contracts with guaranteed uptime percentages. Flint and Newark legacy infrastructure crises accelerated capital replacement timelines for lead detection networks.
India
Central Pollution Control Board mandates for Ganga rejuvenation infrastructure are opening tenders for telemetry-integrated analyzer networks. The Namami Gange program requires dissolved oxygen and heavy metal monitoring at 164 priority drains. River basin stations in Uttar Pradesh and Bihar specify handheld units for field verification protocols.
Denmark
Danish water authorities pioneered outcome-based contracting where vendors retain instrument ownership and guarantee performance thresholds. Public procurement rules favor operational expenditure frameworks over bonded capital projects. Copenhagen and Aarhus municipal utilities now specify multiparameter instruments for consolidated maintenance liability.
Water Quality Analyzer Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology sophistication and service bundling depth. The vendor base clusters around three strategic archetypes: diversified instrumentation conglomerates with diagnostics platform breadth, vertically integrated water technology specialists with telemetry capabilities, and focused analytical instrument developers with R&D intensity in portable detection. Competitive positioning hardens through backward integration into sensor manufacturing and cloud-based data layer convergence.
Within the diversified conglomerate tier, Danaher Corporation and Thermo Fisher Scientific Inc. anchor high-throughput municipal and portable field identification segments respectively. Xylem Inc. occupies a distinct position through upstream control over telemetry infrastructure and subscription analytics. These three entities exemplify how capital depth and platform breadth determine contract capture in outcome-based procurement environments.
| Leading Market Players |
|---|
| Danaher Corporation |
| Xylem Inc. |
| Thermo Fisher Scientific Inc. |
| ABB Ltd. |
| Emerson Electric Co. |
| Endress+Hauser Group |
| HORIBA Ltd. |
| Siemens AG |
| Evoqua Water Technologies LLC |
| Others |
Cost & Logistics Intelligence
Municipal water authorities under tightening EU Drinking Water Directive enforcement anchor procurement volume and compress pricing negotiations toward outcome-based service contracts rather than capital purchases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates spectrophotometry-based multi-analyte systems from electrochemical sensors and handheld field units. Certification grade under ISO 15839 and EU Drinking Water Directive alignment command substantial premiums for online analyzers. Cost compression in electrochemical sensor tiers is intensifying because electrode longevity limitations elevate total cost of ownership and drive substitution toward optical platforms. Industrial operators in China's Yangtze River Delta corridor show least price sensitivity due to MEE discharge penalty structures, while small agricultural utilities in India exhibit highest sensitivity.
Supply Chain Analysis
High-purity reagent formulations for colorimetric analysis rest on German and Swiss specialty chemical producers, with optical sensor miniaturization components drawing from Japanese photonics manufacturers and Chinese electronics assemblers. Critical inputs span precision optical gratings, ion-selective electrode membranes, and certified reference standards. Single-source vulnerability concentrates in REACH-compliant indicator chemistries where alternative validation timelines extend procurement cycles. Distribution runs through authorized service integrators who bundle installation, calibration, and cloud telemetry subscriptions for municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical sensor miniaturization is compressing maintenance cost structures and enabling premium-tier positioning for continuous monitoring networks, expanding margin capture for vendors with captive sensor manufacturing.
For Market Incumbents: To counter modular sensor bundling from diversified instrumentation conglomerates, anchor municipal contracts through backward integration into optical cartridge production and secure exclusive telemetry-integrated service agreements with Scandinavian water authorities pursuing analyzer-as-a-service frameworks. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer low-friction entry for portable mass spectrometry field identification systems targeting India's Ganga rejuvenation infrastructure tenders, where Central Pollution Control Board mandates for river basin monitoring outstrip established vendor capacity. For Investors and Strategic Acquirers: Water technology specialists with telemetry capabilities are the most active acquirers in this space, consolidating cloud-based data layer providers to anchor subscription revenue streams. Acquisition targets with ISO 15839 certification pipelines and established substance dossiers under REACH offer defensive positioning. Watch MEE enforcement intensity in China's Pearl River Delta manufacturing clusters as inflection indicator for spectrophotometry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Sensor Manufacturing | Captive production of miniaturized photometric components compresses maintenance liability for German municipal contracts. |
| Analyzer-as-a-Service Contracting | Outcome-based agreements with Danish water authorities convert capital expenditure to recurring subscription revenue. |
| Cloud Telemetry Platform Integration | Unified SCADA convergence creates predictive maintenance analytics revenue streams for municipal utilities. |
| Portable Mass Spectrometry Field Launch | Contaminant fingerprinting capabilities beyond laboratory boundaries open emergency response procurement channels. |
| REACH-Compliant Reagent Diversification | Alternative indicator chemistry validation secures supply continuity for European industrial laboratory customers. |
Research Approach
Coverage spans Germany, China, the United States, India, and Denmark, with primary inputs from each combining structured interviews with municipal water authority procurement directors, industrial plant environmental compliance officers, optical sensor R&D leads, and aftermarket service operations managers. Secondary validation draws from EPA enforcement databases, EU Drinking Water Directive implementation reports, MEE discharge standard filings, and ISO 15839 certification registries. Bottom-up unit deployment estimates triangulate against top-down municipal capital expenditure budgets.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. Segmentation dimensions span product type, measurement technology, application context, and end-user procurement sophistication. CAGRs derive from regression against regulatory mandate implementation timelines and replacement cycle acceleration patterns. Forecast inputs incorporate EU Drinking Water Directive enforcement intensity curves and China's MEE real-time monitoring mandate rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for electrochemical-to-optical substitution would alter the outlook. Forecasts reflect assumptions around certification timeline stability and reagent supply chain continuity. Regulatory enforcement variance, currency volatility in Swiss-German chemical trade corridors, and technician shortage severity for electrode calibration expertise warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Canada Cloud Seeding Market