
 India Cloud Seeding Market | 2026-2036
India Cloud Seeding Market Size, Share, and Industry Trends Forecast 2026-2036
India Cloud Seeding Market Insights
Data-driven targeting is narrowing the operational gap between meteorological prediction and seeding execution in India. Weather Modification Inc. leverages its aircraft-based delivery systems to anchor government contracts in western states. Ice Crystal Engineering LLC sustains R&D intensity in hygroscopic flare chemistry, while RHS CONSULTING LTD. competes on ground-based generator networks across the Deccan plateau.
Cloud seeding involves atmospheric intervention using hygroscopic salts or silver iodide particles, typically 0.5–2.0 microns in diameter, to induce or enhance precipitation from suitable cloud formations. The technology serves primarily to augment water availability for rain-fed agriculture and reservoir replenishment in water-stressed regions. Static seeding technology dominates current deployment due to lower operational complexity, though drone-assisted delivery methods represent the fastest-growing segment as unmanned aerial systems reduce per-flight costs over manned aircraft. Government agencies command the largest end-user share, while private enterprise participation remains nascent but structurally expanding.
The Ministry of Earth Sciences and the India Meteorological Department shape operational standards through cloud seeding protocol guidelines, while the Directorate General of Civil Aviation regulates aerial dispersal altitudes and flight corridors. State-level water resource departments in Maharashtra, Karnataka, and Telangana drive procurement cycles tied to monsoon contingency budgets. Stakeholders must monitor evolving DGFA drone regulations and state drought declarations to anticipate procurement windows.
Market Dynamics
Drought declarations by Maharashtra, Karnataka, and Telangana are compressing procurement cycles for cloud seeding services, forcing state water resource departments to pre-position aircraft and ground generators before monsoon onset.
Growth Catalysts
- PLI scheme extension:The Production Linked Incentive scheme for drone manufacturing is reducing unit costs for unmanned aerial platforms used in hygroscopic flare delivery.
- Rain-fed agriculture dependency:Semi-arid Deccan plateau farming communities generate concentrated demand for reservoir replenishment during deficient monsoon years.
- DGCA altitude protocols:Revised flight corridor regulations for aerial dispersal above 15,000 feet are expanding operational windows for seeding aircraft.
Market Restraints
- Silver iodide cost volatility:Import dependency for crystalline nucleating agents exposes operators to raw material price swings and forex risk.
- Ground generator concentration:Deployment networks cluster around existing Maharashtra infrastructure, limiting coverage expansion into eastern states.
- Meteorological predictability limits:Cloud condensation nuclei variability reduces seeding efficacy in convective systems, constraining guaranteed outcome contracts.
Strategic Opportunities
- Telangana reservoir management:The state's Mission Kakatiya tank restoration program creates integrated demand for catchment-area precipitation enhancement.
- Drone-ground hybrid systems:Convergence of unmanned aerial platforms with automated ground generator networks enables precision targeting of orographic cloud formations.
- State drought contingency funds:Karnataka's annual disaster response allocations represent a recurring procurement channel with dedicated budget lines.
Industry Challenges
- Atmospheric physics expertise gap:Shortage of trained meteorologists capable of real-time cloud microphysics assessment limits operational scaling.
- Aircraft certification timelines:DGCA airworthiness approvals for modified seeding platforms extend lead times by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cloud Seeding Market |
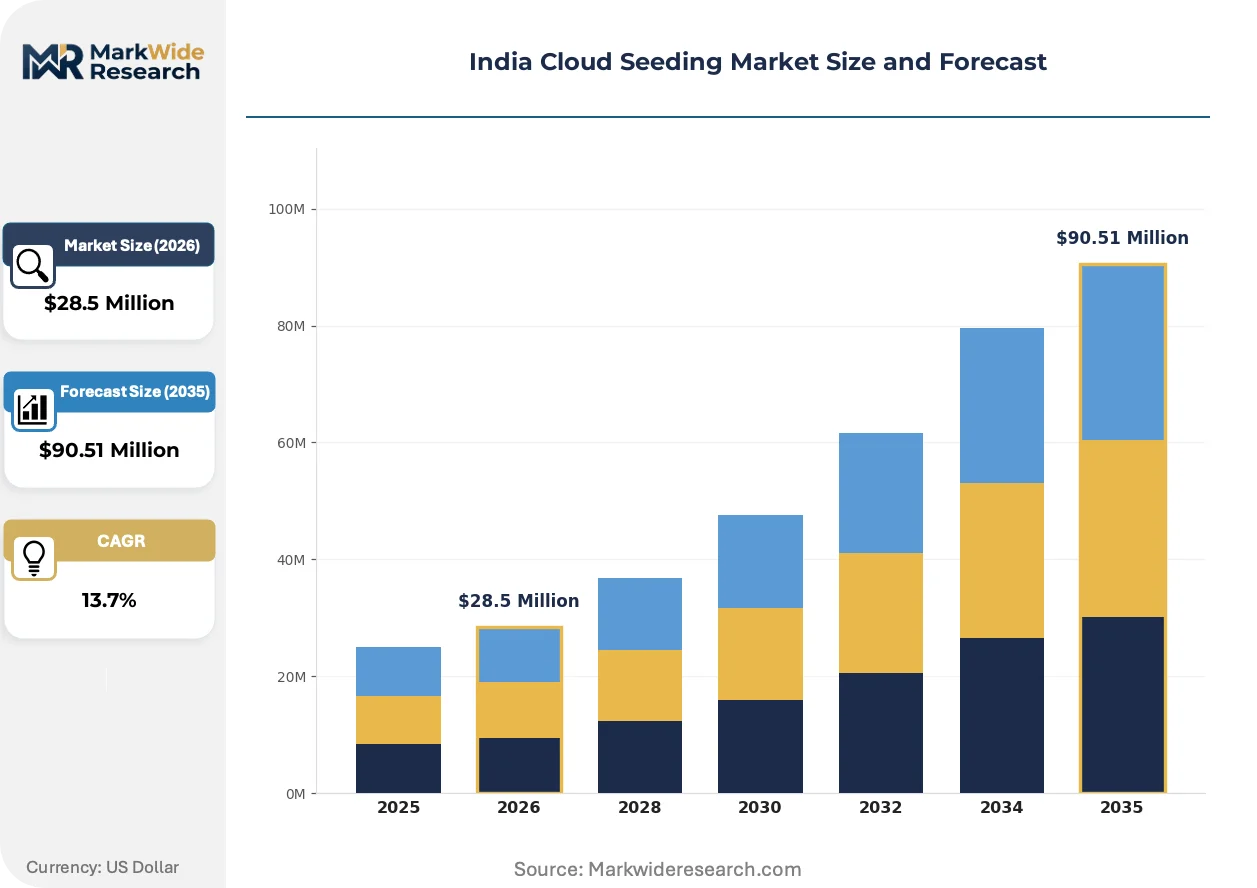
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $90.51 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Static, Dynamic, Hybrid, Data-Driven Application: Agriculture, Water Resource Management, Weather Modification, Urban Cooling End User: Government Agencies, Agriculture Sector, Research Institutions, Private Enterprises Delivery Method: Aerial, Ground-Based, Drone-Assisted, Automated |
| Companies Covered | American Elements Inc., ModClima, Weather Modification Inc., Cloud Technologies GmbH, 3D S.A., NAWC Inc, Northwest Mettech Corp., RHS CONSULTING LTD., Ice Crystal Engineering LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cloud Seeding Market Trends and Innovations
Operational models in Indian cloud seeding are pivoting from manned aircraft dominance toward autonomous systems integration, compressing cost structures while expanding geographic reach into previously inaccessible terrain.
Drone-assisted delivery platforms are collapsing the per-flight economics of hygroscopic particle dispersal. State agriculture departments in Maharashtra and Karnataka are piloting fixed-wing unmanned systems for orographic cloud targeting. This compression is enabling smaller state budgets to sustain multi-week seeding campaigns previously affordable only to national programs.
The Ministry of Earth Sciences' revised cloud seeding protocol guidelines are mandating dual-sensor validation for all operational flights. Aircraft operators must now integrate cloud condensation nuclei counters with standard hygroscopic flare systems. Western state water resource departments are responding by retendering contracts to include instrumentation compliance clauses.
Outcome-based service agreements are displacing flat-rate aircraft charter contracts across state procurement frameworks. Telangana's water resource department now ties vendor payments to verified precipitation metrics from IMD rain gauge networks. This shift is most visible in Deccan plateau districts where reservoir level data provides objective verification endpoints.
India Cloud Seeding Market Segmentation
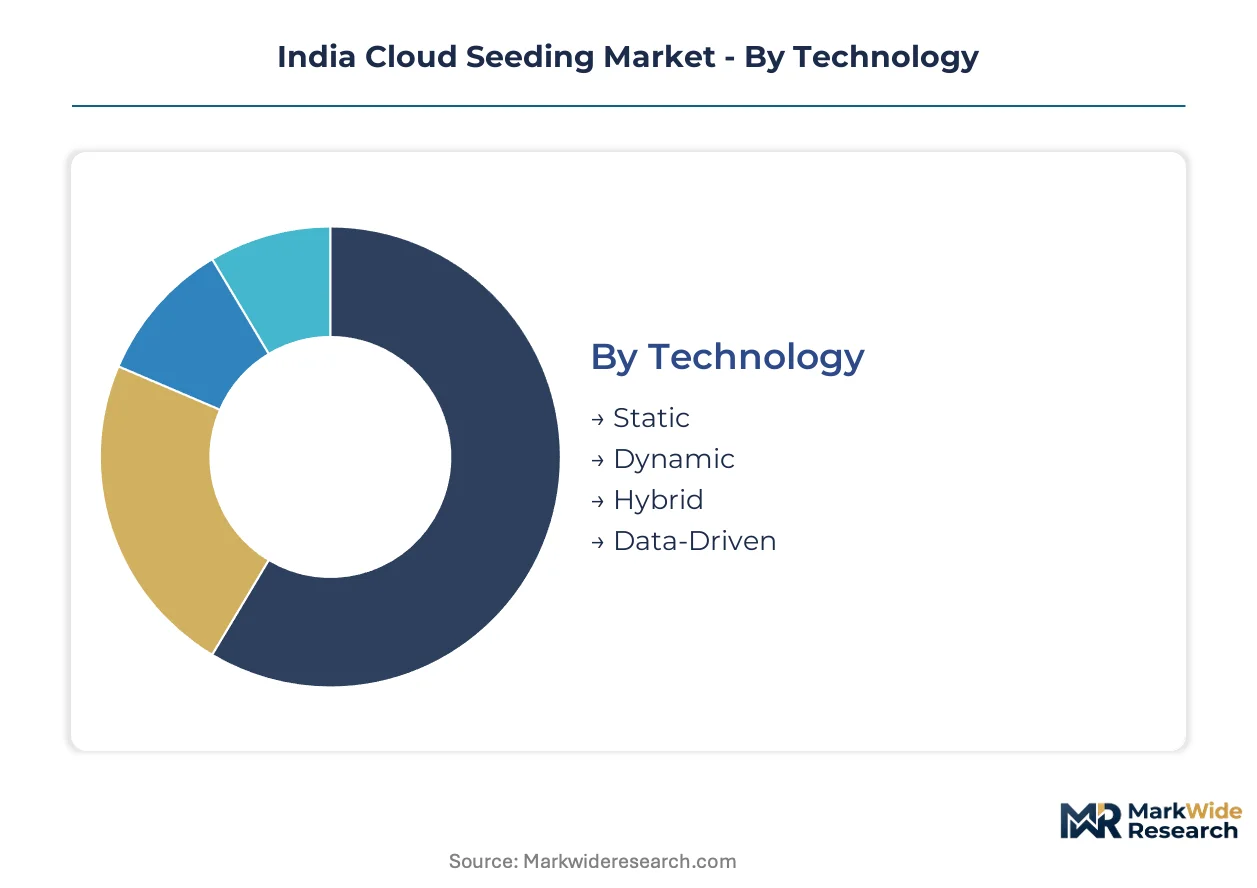
Cloud seeding procurement in India fragments across four operational dimensions, each governing distinct budget flows and regulatory touchpoints. Technology choices determine capital intensity, while delivery methods reshape per-campaign economics as state agencies weigh aircraft against autonomous platforms.
Technology:
Mature operational platforms dominate current deployment, though emerging methodologies are compressing execution timelines and expanding addressable weather windows.
- Static:Hygroscopic salt dispersal from ground generators or aircraft relies on passive nucleation within existing cloud moisture. Maharashtra's water resource departments anchor demand here, constrained by meteorological predictability limits that reduce guaranteed outcome contracts.
- Dynamic:Active ice nucleation using silver iodide burners operates at colder cloud temperatures, requiring specialized aircraft certification from DGCA. Karnataka's drought contingency procurement channels concentrate spending on this segment during deficient monsoon years.
- Hybrid:Combines static and dynamic mechanisms for layered atmospheric intervention. Telangana's Mission Kakatiya tank restoration program pilots integrated catchment-area applications.
- Data-Driven:Real-time cloud microphysics assessment with dual-sensor validation per Ministry of Earth Sciences protocols. The revised guidelines mandate this approach for all government-funded campaigns.
Static seeding retains volume leadership; data-driven methodologies hold the steepest expansion curve as regulatory compliance tightens.
Application:
Cost tier stratification separates reservoir-scale interventions from localized urban deployments, with agriculture commanding the dominant share of state budget allocations.
- Agriculture:Rain-fed farming across the Deccan plateau generates concentrated demand for monsoon augmentation. Semi-arid districts in Maharashtra and Karnataka sustain multi-week seeding campaigns tied to crop cycle water stress.
- Water Resource Management:Reservoir replenishment operations target catchment areas above major dams. Telangana's annual disaster response allocations channel dedicated funding here.
- Weather Modification:Hail suppression and fog dispersion for aviation corridors. The India Meteorological Department coordinates limited trials at select airports.
- Urban Cooling:Experimental heat island mitigation through increased cloud cover. Municipal corporations in Hyderabad and Bengaluru pilot small-scale programs.
Agriculture commands the dominant procurement volume; urban cooling exhibits the most rapid budget growth rate among municipal applications.
End User:
Customer type determines contracting structure, with government procurement cycles compressing as drought declarations trigger emergency response protocols.
- Government Agencies:State water resource departments and the Ministry of Earth Sciences anchor procurement through monsoon contingency budgets. Maharashtra, Karnataka, and Telangana drive recurring tender cycles.
- Agriculture Sector:Farmer producer organizations and cooperative societies fund localized ground generator networks. The Deccan plateau's rain-fed districts concentrate this demand.
- Research Institutions:Indian Institute of Tropical Meteorology and university atmospheric science departments operate validation campaigns. Funding flows through Ministry of Earth Sciences grants.
- Private Enterprises:Hydropower operators and mining companies commission bespoke precipitation enhancement. Participation remains nascent but structurally expanding as outcome-based pricing models mature.
Government agencies retain procurement leadership; private enterprises are climbing the fastest as commercial water risk management budgets expand.
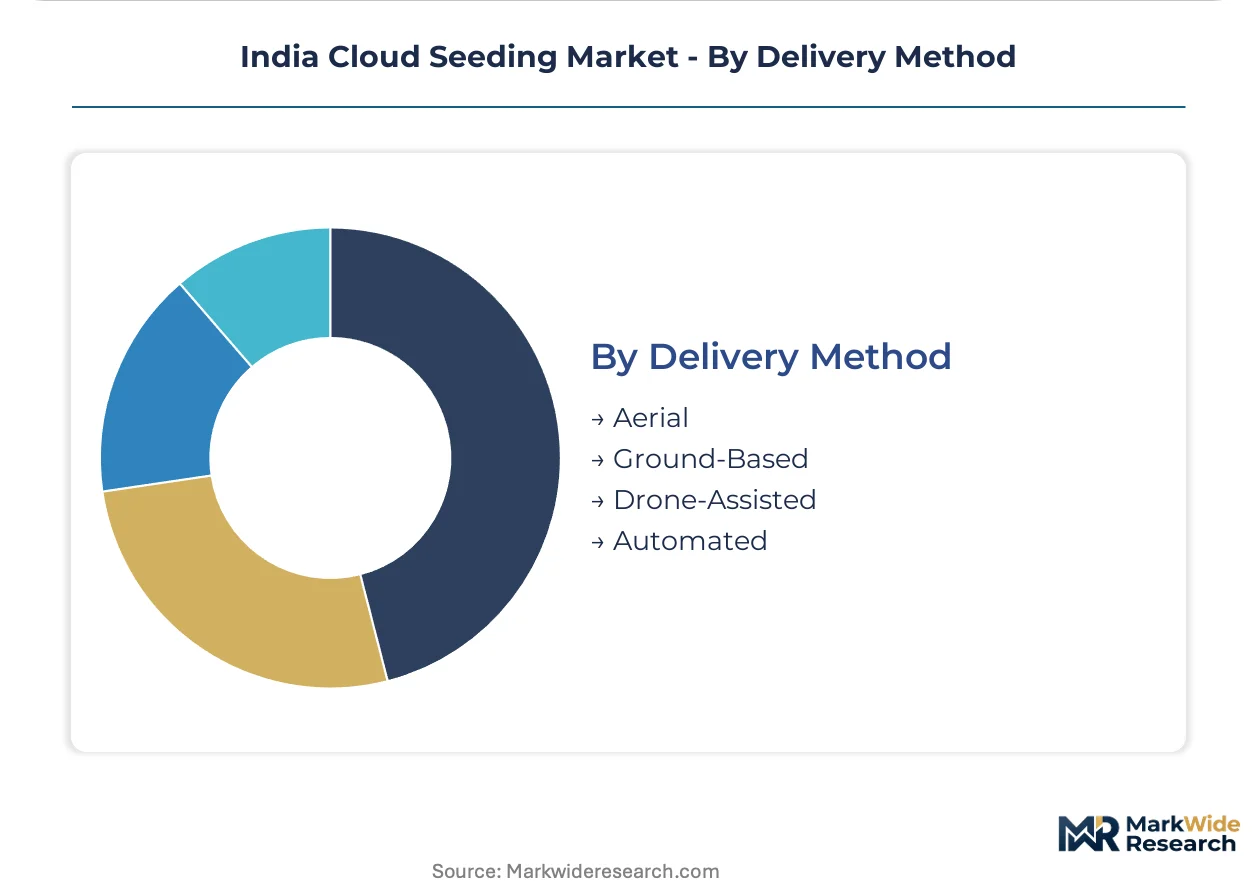
Delivery Method:
Supply concentration around Maharashtra's existing infrastructure limits coverage expansion, though drone regulations from DGCA are opening eastern state markets.
- Aerial:Manned aircraft with modified seeding platforms require 8-12 month DGCA airworthiness approvals. Western state contracts favor this method for orographic cloud targeting.
- Ground-Based:Automated generator networks cluster around existing Maharashtra infrastructure. Karnataka's water resource departments retender contracts to include instrumentation compliance clauses.
- Drone-Assisted:Fixed-wing unmanned systems reduce per-flight costs below manned aircraft economics. The PLI scheme for drone manufacturing is accelerating unit cost declines.
- Automated:Integrated ground generator networks with remote activation capabilities. Telangana pilots precision targeting of orographic formations through hybrid drone-ground coordination.
Aerial delivery maintains contract volume leadership; drone-assisted platforms are expanding most quickly as state agriculture departments pilot fixed-wing systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's cloud seeding market exhibits pronounced regional concentration, with import dependency for silver iodide nucleating agents and domestic manufacturing of ground generator infrastructure shaping sub-regional procurement patterns across state water resource departments.
Maharashtra
Drought-prone districts in Marathwada and Vidarbha sustain multi-week seeding campaigns tied to kharif crop cycles. The state's water resource department channels monsoon contingency budgets through DGCA-certified aerial dispersal contracts. Mumbai-Pune industrial corridor hosts ground generator fabrication clusters serving western India procurement networks.
Karnataka
Semi-arid districts across the Deccan plateau generate concentrated reservoir replenishment demand during deficient monsoon years. The state's annual disaster response allocations include dedicated budget lines for cloud seeding procurement. Bengaluru's aerospace supply base supports aircraft modification services for seeding platform certification.
Telangana
Mission Kakatiya tank restoration program integrates catchment-area precipitation enhancement into watershed management protocols. The state's water resource department pioneered outcome-based vendor payments tied to IMD rain gauge verification. Hyderabad anchors drone-assisted delivery pilot programs for orographic cloud targeting.
Andhra Pradesh
Rayalaseema region's chronic water stress drives emerging procurement demand from farmer producer organizations. The state's agriculture department evaluates ground generator network expansion under revised Ministry of Earth Sciences protocols. Vijayawada-Guntur corridor hosts emerging service provider clusters for Deccan plateau operations.
Gujarat
Saurashtra and Kutch regions deploy cloud seeding for cotton and groundnut irrigation security during erratic monsoon phases. The state's water resources department coordinates with the India Meteorological Department for pre-monsoon cloud assessment. Ahmedabad-based logistics networks support rapid equipment mobilization for drought-declared districts.
India Cloud Seeding Market Competitive Landscape
On the supply side, the industry is bifurcated between specialized atmospheric intervention service providers and diversified chemical/materials suppliers offering nucleating agents. The competitive terrain stratifies across three archetypes: aircraft-based aerial dispersal operators, ground generator network specialists, and hygroscopic flare chemistry developers. Capacity expansion through drone platform certification and strategic partnerships with state water resource departments constitute the dominant competitive moves reshaping procurement access.
Within the aircraft-based service tier, Weather Modification Inc. and Northwest Mettech Corp. occupy positions exemplifying North American-origin aerial dispersal expertise. Ice Crystal Engineering LLC represents the hygroscopic flare chemistry specialization segment, while RHS CONSULTING LTD. anchors the ground-based generator network archetype across Deccan plateau operations. These three entities collectively illustrate the geographic and technological diversification patterns within India-bound cloud seeding procurement.
| Leading Market Players |
|---|
| American Elements Inc. |
| ModClima |
| Weather Modification Inc. |
| Cloud Technologies GmbH |
| 3D S.A. |
| NAWC Inc |
| Northwest Mettech Corp. |
| RHS CONSULTING LTD. |
| Ice Crystal Engineering LLC |
| Others |
Pricing and Supply Chain Analysis
Silver iodide import dependency from North American and European chemical suppliers exposes Indian cloud seeding operators to forex volatility and crystalline nucleating agent price swings, compressing margins across both premium aerial dispersal tiers and economy ground-generator segments while forcing procurement teams toward multi-source qualification and domestic hygroscopic salt alternatives.
Pricing Analysis
State water resource departments anchor pricing structures around outcome-based service agreements that displace flat-rate aircraft charter contracts. Price differentiation hinges on DGCA certification tier for aerial platforms and real-time instrumentation compliance under Ministry of Earth Sciences protocols. Cost compression in the drone-assisted delivery tier is intensifying because PLI scheme subsidies collapse unmanned aerial system unit economics. Farmer producer organizations in the Deccan plateau exhibit the highest price sensitivity, while national program coordinators at the Ministry of Earth Sciences demonstrate the lowest.
Supply Chain Analysis
Contract manufacturing for hygroscopic flare chemistry concentrates with Ice Crystal Engineering LLC and specialized North American pyrotechnic suppliers, while ground generator fabrication clusters around Mumbai-Pune industrial corridor workshops. Raw material flows draw from imported silver iodide crystalline agents, domestically compounded hygroscopic salts, and Bengaluru-sourced aerospace modification components. Single-source vulnerability in nucleating agent supply creates exposure to international commodity price volatility. Distribution runs through state water resource department tender processes with emergency procurement windows triggered by drought declarations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
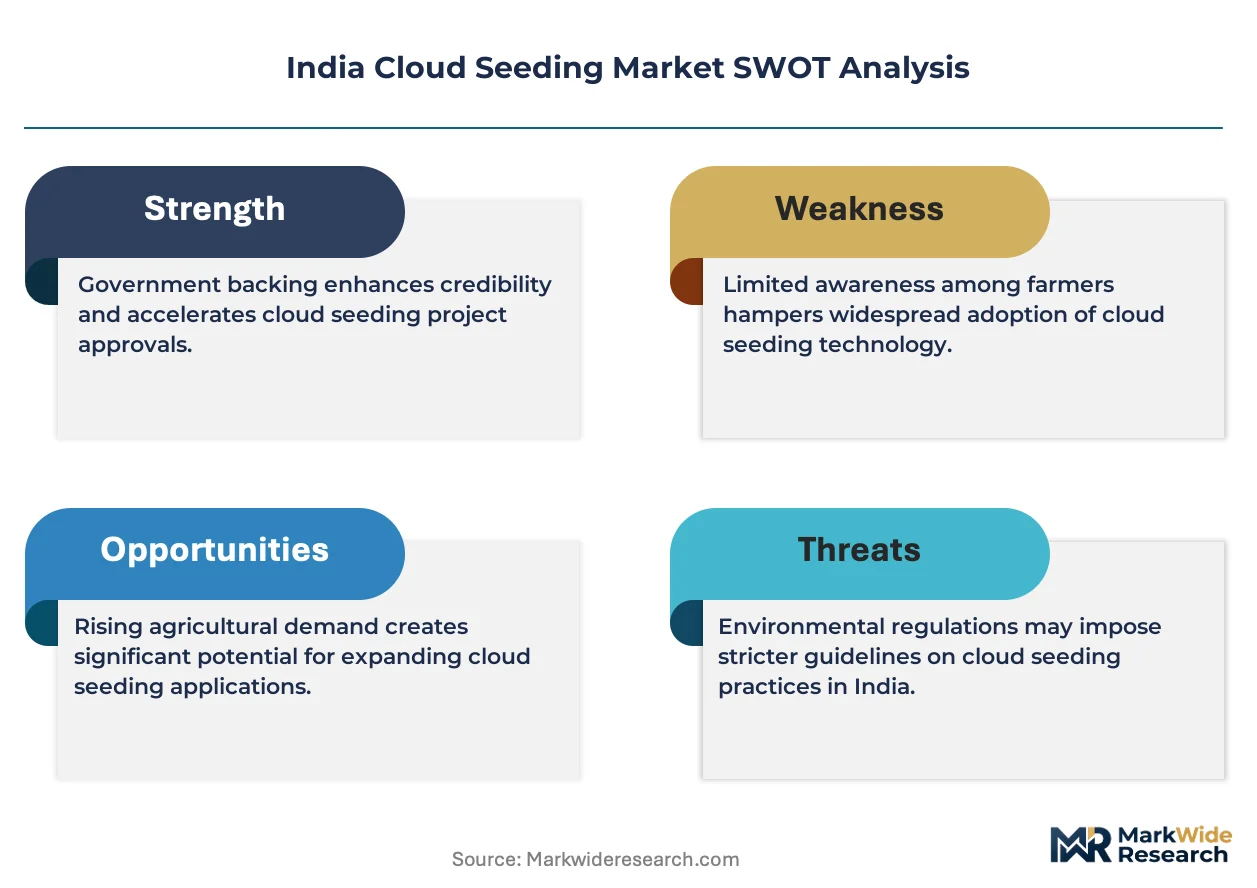
Cloud seeding procurement in India is approaching a platform-economics inflection as drone-ground hybrid systems enable precision targeting interoperability that collapses the traditional aircraft-or-ground binary into integrated catchment-area management ecosystems.
For Market Incumbents: Harden contract retention by embedding dual-sensor validation capabilities ahead of mandatory Ministry of Earth Sciences protocol compliance deadlines. Secure backward integration into hygroscopic flare chemistry through captive supply agreements with domestic pyrotechnic compounders to offset silver iodide import exposure. DGCA drone certification timelines represent the critical chokepoint threat.
For New Entrants and Emerging Players: Andhra Pradesh's Rayalaseema region offers concentrated white-space demand from farmer producer organizations underserved by Maharashtra-centric ground generator networks. Telangana's outcome-based vendor payment frameworks provide the most penetrable procurement entry point for performance-guaranteed service models. Lead with drone-assisted delivery pilots to bypass 8-12 month DGCA manned aircraft airworthiness barriers.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated service providers with captive drone platform and instrumentation capabilities. Long-term viability over the coming decade rests on positioning for post-PLI scheme subsidy environments where unit economics must self-sustain. Watch Karnataka's annual disaster response allocation cycles as the signal for procurement inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Drone Platform Certification | DGCA unmanned aerial system approvals unlock eastern state markets beyond Maharashtra infrastructure clusters. |
| Backward Integration into Flare Chemistry | Domestic hygroscopic compound manufacturing reduces silver iodide import dependency and forex exposure. |
| Outcome-Based Contract Structuring | IMD rain gauge verification ties vendor payments to objective precipitation metrics, transferring performance risk. |
| Hybrid Drone-Ground Generator Networks | Automated coordination enables precision orographic cloud targeting across Telangana's Mission Kakatiya catchments. |
| Dual-Sensor Validation Compliance | Cloud condensation nuclei counters integrated with standard flare systems satisfy revised Ministry of Earth Sciences protocols. |
Research Methodology
Operator-level perspectives from state water resource department procurement officers, DGCA certification specialists, Indian Institute of Tropical Meteorology research scientists, and farmer producer organization coordinators anchored the qualitative base. Secondary validation drew from Ministry of Earth Sciences cloud seeding protocol guidelines, India Meteorological Department precipitation databases, DGCA drone regulation circulars, and state drought contingency budget appropriations. Bottom-up campaign cost modeling and top-down monsoon contingency allocation analysis provided triangulation.
Scenario-bracketing around deficient, normal, and excess monsoon years shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application sector, end-user category, and delivery method. CAGRs were derived from state-level procurement cycle analysis and equipment replacement timelines. Forecast inputs incorporated PLI scheme drone manufacturing subsidy trajectories and evolving DGCA altitude protocol amendments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese unmanned aerial system manufacturers or domestic drone platform entrants would shift outcomes. Quarterly review of state drought declarations, DGCA certification queue lengths, and silver iodide import duty adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Smart Water Monitoring Market