
 Radon Gas Test Kits Market | 2026-2036
Radon Gas Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Radon Gas Test Kits Market Insights
North American activated charcoal sourcing is hardening as domestic suppliers face competition from importers facing stricter customs screening. First Alert leverages its retail shelf presence across home improvement chains to sustain volume leadership in passive test kits. Airthings competes through Bluetooth-enabled continuous monitors that anchor its position in the premium residential segment.
Radon gas test kits are measurement devices designed to quantify airborne radon-222 concentrations, typically employing charcoal adsorption, alpha track etching, or ion chamber detection with sensitivity thresholds measured in picocuries per liter. Their primary purpose is to identify hazardous indoor accumulation in enclosed structures, enabling mitigation decisions that reduce lung cancer risk. Short-term charcoal canister kits dominate residential real estate transactions due to low cost and rapid turnaround, while digital monitors capture the fastest expansion as homeowners seek continuous data logging. Distribution through online retail channels is concentrating margin pools away from specialty stores, reflecting consumer preference for comparison shopping and subscription-style monitor services.
EPA protocols and state radon disclosure laws in the United States shape product certification requirements, with laboratories requiring NRPP or NRSB credentials to process charcoal canister results. The EU F-Gas Regulation and national building codes in Germany and France are elevating awareness of indoor air quality standards, indirectly expanding addressable demand for detection equipment. Stakeholders must monitor evolving accreditation standards and the pace of smart home integration to determine whether hardware margins or data service subscriptions will define sustainable profitability.
Market Dynamics
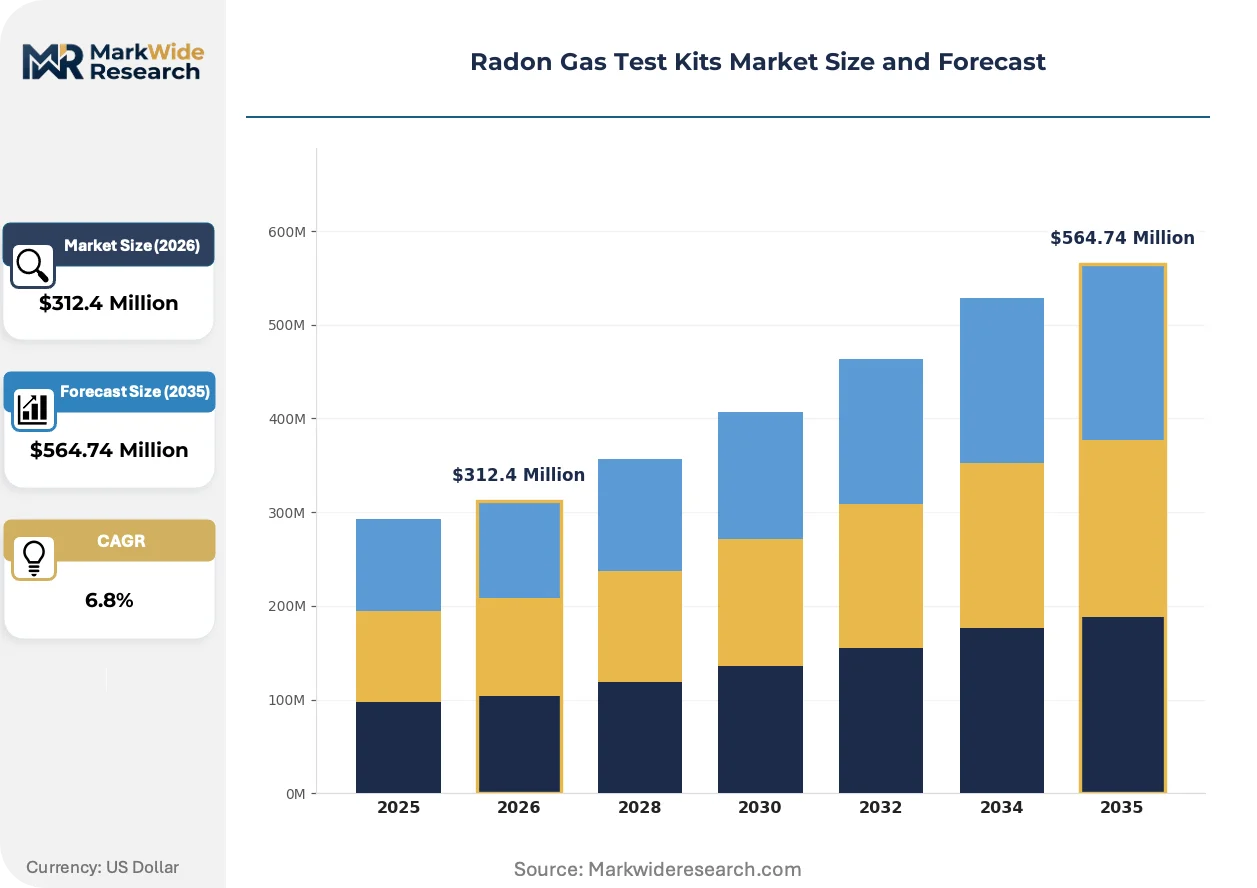
The EPA's radon disclosure mandates and state-level real estate transaction rules are compressing testing cycles, forcing kit manufacturers to align laboratory turnaround times with contract closing windows while digital monitor vendors exploit data subscription models.
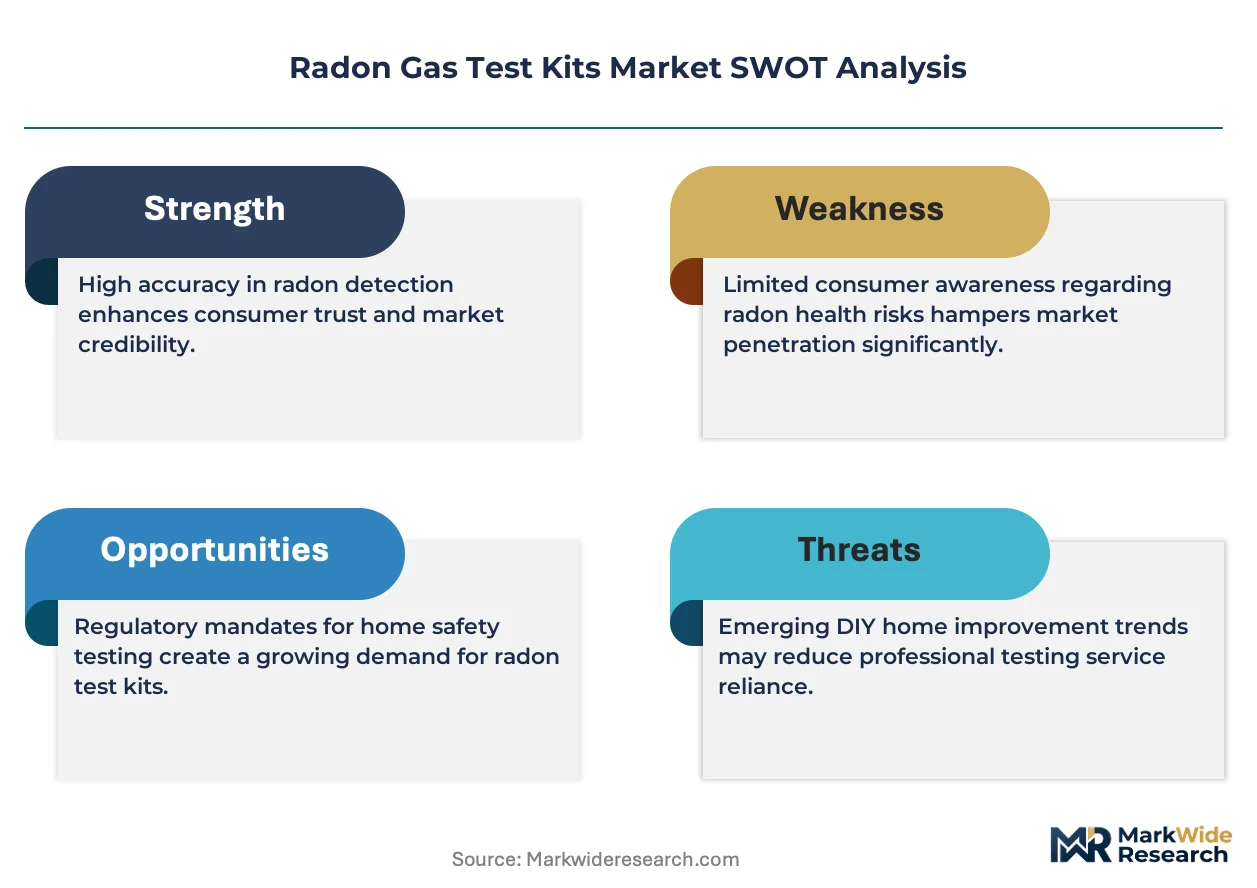
Growth Catalysts
- Real estate transaction velocity:Residential property transfers in basement-dense housing markets require pre-sale radon documentation, embedding test kits into mandatory inspection workflows.
- EPA mapping programs:Federal zone classification systems identify high-radon counties, triggering targeted outreach campaigns that normalize testing behavior among homeowners.
- Alpha track etching:This detection method enables long-term averaging accuracy that charcoal canisters cannot match, satisfying diagnostic requirements for mitigation system design.
Market Restraints
- Activated charcoal sourcing:Domestic carbon suppliers face import competition from producers facing enhanced customs screening, creating raw material availability bottlenecks.
- Laboratory accreditation concentration:NRPP and NRSB credentialing requirements limit the pool of qualified result processors, extending regional processing delays.
- Passive kit substitution:Digital continuous monitors with Bluetooth connectivity capture recurring revenue streams that one-time charcoal purchases cannot replicate.
Strategic Opportunities
- Smart home integration:API connectivity with HVAC control systems enables automated ventilation responses to radon spikes, creating recurring service revenue.
- EU F-Gas Regulation spillover:Indoor air quality awareness campaigns in Germany and France expand addressable demand beyond North American concentration.
- Subscription-based monitoring:Data logging services replace one-time test purchases, shifting margin pools toward software-enabled recurring revenue.
Industry Challenges
- NRPP certification timelines:New laboratory entrants face extended approval periods that delay market entry and compress competitive response windows.
- Cross-platform data standardization:Proprietary monitor protocols resist integration with unified home automation systems, fragmenting user experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radon Gas Test Kits Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short-Term Kits, Long-Term Kits, Digital Monitors, Passive Devices End User: Residential, Commercial, Government, Environmental Agencies Distribution Channel: Online Retail, Specialty Stores, Home Improvement Stores, Distribution Partners Testing Method: Charcoal Canisters, Alpha Track Detectors, Ion Chamber Detectors, Electronic Monitors |
| Companies Covered | First Alert, Airthings, RadonAway, Radonova, Air Chek, Alpha Energy Labs, PRO-LAB, AccuStar Labs, Sun Nuclear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radon Gas Test Kits Market Trends and Innovations
Bluetooth-enabled continuous monitors are restructuring competitive boundaries between passive charcoal kits and digital detection systems, while regulatory disclosure requirements embed testing deeper into property transaction infrastructure.
Continuous radon monitors with cloud-connected data logging are consolidating market share among health-conscious homeowners seeking real-time concentration tracking. Residential buyers in high-radon zones adopt these devices for ongoing validation of mitigation system performance. The technology is consolidating hardware margins toward vendors capable of delivering subscription analytics rather than single-transaction test kits.
EPA radon zone mapping combined with state disclosure statutes tightens compliance timelines for property sellers. Real estate professionals now bundle testing into standard listing preparation, compressing the window between detection and remediation. Residential transactions in Zone 1 counties face the most acute pressure to document pre-sale radon status.
Homebuyers increasingly demand laboratory-certified results rather than unverified DIY readings, concentrating purchase authority toward credentialed kit providers. Online retail channels capture this preference through transparent accreditation display and comparison tools. The United States exhibits the strongest channel shift as consumers prioritize documented chain-of-custody over immediate retail availability.
Radon Gas Test Kits Market Segmentation
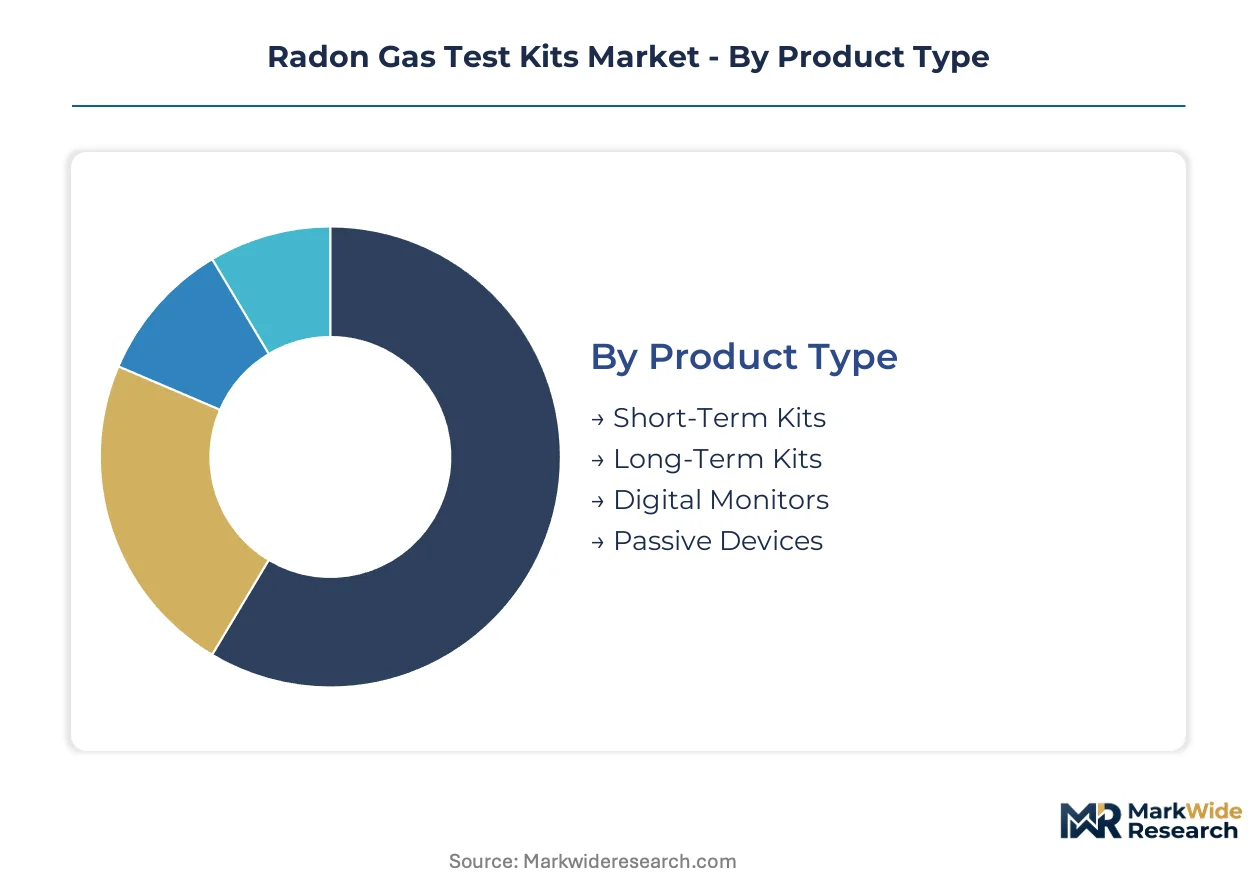
Product architecture in radon detection spans disposable consumables through connected hardware, creating divergent margin structures and customer lifetime value profiles. Segmentation choices determine whether vendors capture one-time transaction revenue or recurring data service income.
Product Type:
The customization-standardization spectrum runs from mass-produced charcoal canisters to firmware-configurable digital monitors with cloud analytics backends.
- Short-Term Kits:Charcoal adsorption devices designed for 2-7 day measurement windows dominate residential real estate transactions. Demand concentrates in basement-dense housing markets across the United States where EPA disclosure mandates compress testing timelines. First Alert and similar vendors leverage retail shelf presence to sustain volume leadership despite thin hardware margins.
- Digital Monitors:Bluetooth-enabled continuous detection systems with cloud data logging capture the steepest expansion trajectory. Residential buyers in high-radon zones adopt these for ongoing mitigation validation. Airthings anchors premium positioning through API connectivity and subscription analytics services that displace one-time kit purchases.
- Long-Term Kits:Alpha track etching devices enable 90-day averaging accuracy required for mitigation system design documentation.
- Passive Devices:Unpowered detection systems without electronic components serve cost-sensitive screening applications.
Most installed capacity flows through Short-Term Kits. Expansion is steepest in Digital Monitors.
End User:
Customer archetypes range from individual homeowners making discretionary purchases to institutional buyers with mandated compliance budgets.
- Residential:Individual property owners and homebuyers drive absolute volume. Transactions in Zone 1 counties face acute documentation pressure from state disclosure statutes. Online retail channels capture preference through transparent laboratory accreditation display.
- Commercial:Property management firms and employers with underground workspace obligations deploy continuous monitoring for liability protection.
- Government:Federal and state agencies purchase calibration equipment and reference standards for laboratory certification programs.
- Environmental Agencies:Public health departments conduct outreach testing in high-radon zones identified by EPA mapping programs.
Residential captures the dominant revenue share. Commercial applications are gaining share fastest as employer liability frameworks tighten.
Distribution Channel:
Channel strategy determines margin retention versus volume velocity, with digital platforms consolidating information-rich purchase decisions.
- Online Retail:E-commerce platforms capture growing preference for comparison shopping and subscription-style monitor services. The United States exhibits the strongest channel shift as consumers prioritize documented chain-of-custody over immediate retail availability.
- Home Improvement Stores:Big-box retail maintains relevance for emergency purchases and contractor bulk procurement.
- Specialty Stores:Localized HVAC and environmental equipment dealers serve professional installer networks.
- Distribution Partners:Wholesale intermediaries supply institutional buyers with volume pricing and consolidated logistics.
Online Retail concentrates margin pools fastest. Home Improvement Stores retain position in passive kit categories.
Testing Method:
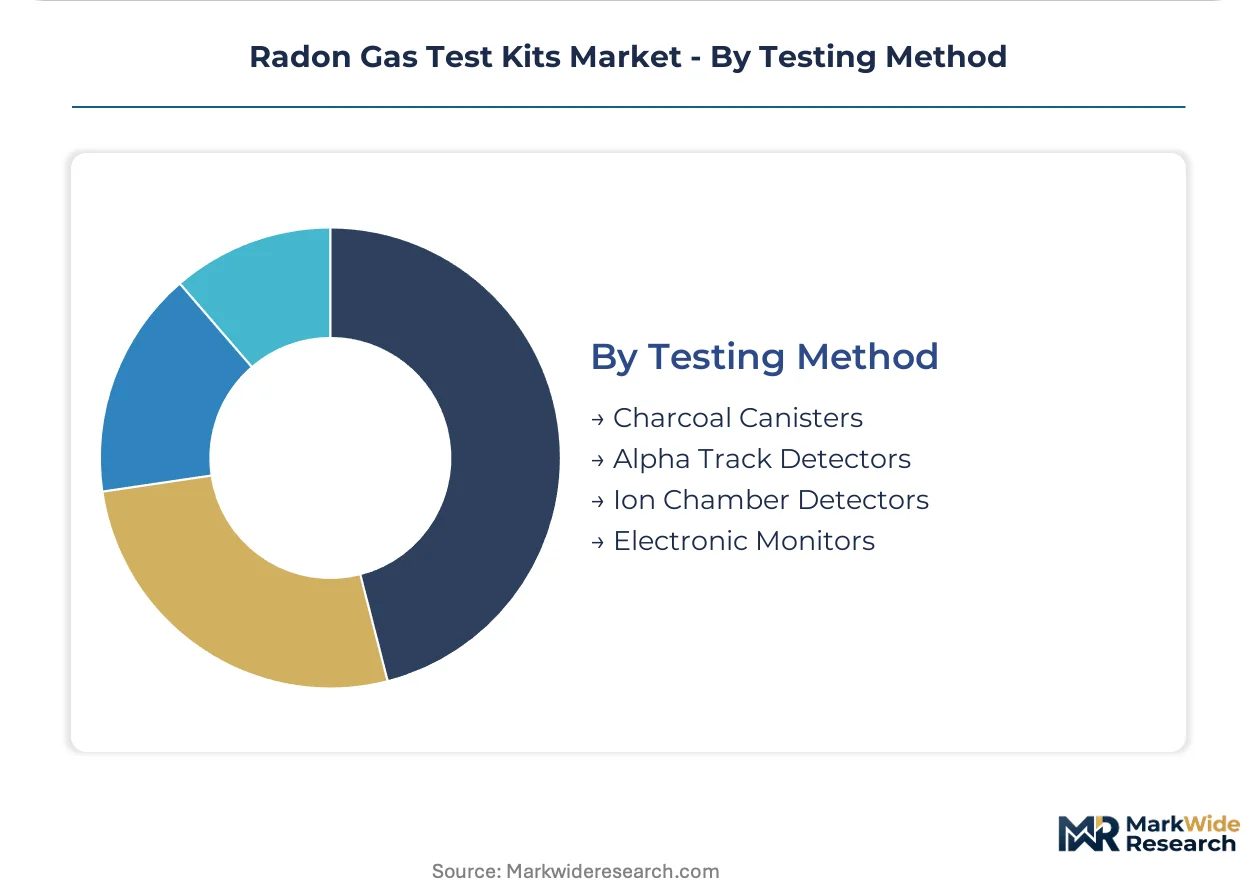
Detection chemistry versus electronic sensing creates divergent accuracy-cost tradeoffs and laboratory dependency profiles.
- Charcoal Canisters:Activated carbon adsorption systems require laboratory analysis for picocurie-per-liter quantification. NRPP and NRSB credentialing requirements limit qualified processors, extending regional turnaround times. Raw material sourcing faces import competition from producers facing enhanced customs screening.
- Alpha Track Detectors:Polymer film etching technology enables long-term averaging without power consumption. Environmental Agencies in Germany and France deploy these for building code compliance documentation under elevated indoor air quality standards.
- Ion Chamber Detectors:Electret-based measurement provides immediate results without laboratory processing.
- Electronic Monitors:Solid-state sensors with digital readouts support continuous logging and HVAC integration.
Charcoal Canisters retain the largest installed base. Electronic Monitors are climbing the fastest as smart home integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are migrating laboratory processing capacity toward jurisdictions with streamlined EPA-equivalent accreditation pathways, exploiting cost-of-compliance gaps between established and emerging certification regimes. This arbitrage reshapes regional supply patterns as vendors chase faster NRPP and NRSB credentialing timelines.
United States
Basement-dense housing stock across the Midwest and Northeast drives residential transaction volume, with Zone 1 counties mandating pre-sale documentation under state disclosure statutes. EPA radon mapping programs target outreach to high-risk postal codes, normalizing testing behavior among homeowners. Laboratory clusters in Colorado and Ohio process charcoal canister results for real estate closing windows.
Germany
Federal building codes referencing indoor air quality standards elevate detection equipment procurement by property developers and environmental consultancies. The EU F-Gas Regulation spillover amplifies awareness of radon as a lung carcinogen, expanding addressable demand beyond traditional North American concentration. Alpha track detector deployment concentrates in Bavaria and Baden-Württemberg for long-term residential monitoring.
Canada
Health Canada guidelines for radon action levels trigger mandatory testing in federal buildings and subsidized housing stock, creating institutional procurement pipelines. Cross-border laboratory accreditation mutual recognition with US NRPP standards accelerates kit import velocity from American suppliers. Greater Toronto and Vancouver housing markets exhibit basement construction patterns that elevate residential testing frequency.
France
ANSM public health campaigns on domestic radon exposure drive demand for certified measurement devices in Auvergne-Rhône-Alpes and Massif Central granite zones. National building renovation subsidies now incorporate radon mitigation prerequisites, embedding detection into construction workflows. Paris-region environmental laboratories expand processing capacity to serve cross-border EU demand.
United Kingdom
Public Health England radon maps identify Cornwall, Devon, and Derbyshire as priority intervention zones, concentrating kit distribution through regional environmental health partnerships. Building control approval processes in high-risk areas increasingly require mitigation-ready documentation at planning stage. London-based laboratory networks process alpha track etching for long-term averaging compliance.
Radon Gas Test Kits Market Competitive Landscape
North American producers anchor the high-volume charcoal canister tier; European specialists hold premium positioning in continuous monitoring hardware. The vendor base splits between retail-shelf passive kit suppliers and direct-to-consumer digital monitor platforms, with laboratory credentialing requirements acting as a structural barrier to new entrants. Three archetypes dominate: home improvement retail brands, Bluetooth-enabled hardware specialists, and accredited laboratory service providers. Consolidation pressures concentrate around laboratory acquisition and API licensing for smart home integration.
Within the retail-brand archetype, First Alert exemplifies shelf-presence dominance across big-box channels. Airthings occupies a position in the premium connected-device segment through subscription analytics anchoring. Radonova represents the laboratory-service tier with European accreditation breadth.
| Leading Market Players |
|---|
| First Alert |
| Airthings |
| RadonAway |
| Radonova |
| Air Chek |
| Alpha Energy Labs |
| PRO-LAB |
| AccuStar Labs |
| Sun Nuclear Corporation |
| Others |
Pricing and Supply Chain Analysis
Laboratory technician clusters in Colorado and Ohio anchor the pricing-tier spread across charcoal canister processing, with wage differentials between credentialed NRPP analysts and entry-level lab staff creating a three-tier pricing structure across premium, standard, and economy levels. Cost compression in the economy tier intensifies because import competition from activated carbon producers facing enhanced customs screening squeezes raw material margins, forcing domestic suppliers to absorb freight volatility or surrender shelf position.
Pricing Analysis
Distributor margin layers in home improvement retail sustain First Alert's volume leadership despite thin hardware economics, while direct-to-consumer digital monitor vendors capture subscription recurring revenue that transactional charcoal kit sellers cannot replicate. Price differentiation rests on NRPP certification grade and laboratory chain-of-custody documentation, with Zone 1 county homebuyers exhibiting lowest price sensitivity due to state disclosure statute urgency. Cost compression in economy charcoal canisters is accelerating as online retail comparison tools transparently expose accreditation gaps, pressuring uncredentialed kit providers toward margin elimination.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Canada feed hub-and-spoke patterns that concentrate activated charcoal inventory near EPA Zone 1 postal codes and EU F-Gas Regulation compliance zones. Raw material flows draw from coconut shell carbon producers in Southeast Asia, domestic coal-based activated carbon facilities, and synthetic polymer substrate suppliers for alpha track detectors. Single-source vulnerability in NRPP-accredited laboratory processing creates bottleneck risk during real estate closing windows. Distribution runs through online retail platforms capturing comparison-shopping preference, with home improvement stores retaining emergency procurement relevance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radon gas test kits constitute a late-cycle quality story as residential buyers migrate from unverified DIY readings toward laboratory-certified results with documented chain-of-custody, elevating premium positioning for credentialed kit providers.
For Market Incumbents: Cement laboratory acquisition strategies to lock NRPP processing capacity ahead of disclosure mandate expansion, while deepening API licensing partnerships with HVAC control system vendors to anchor smart home integration. Digital monitor substitution threatens charcoal canister incumbents with recurring revenue displacement; vertical integration into cloud analytics services represents the priority defensive lever. For New Entrants and Emerging Players: Enter via EU F-Gas Regulation spillover markets in Germany and France where indoor air quality awareness campaigns outrun established vendor presence, targeting environmental consultancies and property developers with alpha track etching documentation services. The most penetrable white space sits in commercial employer liability applications, with Bluetooth-enabled continuous monitors offering the strongest go-to-market angle against passive kit inertia. For Investors and Strategic Acquirers: Home improvement retail chains are the most active acquirer in this space, seeking private-label kit capabilities to defend shelf margin against direct-to-consumer digital entrants. Long-term viability favors laboratory-service platforms with multi-jurisdiction accreditation breadth over hardware-only vendors facing subscription model displacement. The signal to watch is EPA disclosure statute adoption velocity in currently unmandated states, which would inflect addressable transaction volume.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Acquisition | NRPP-accredited processing capacity locks compliance revenue streams against disclosure mandate expansion. |
| API Licensing Partnership | HVAC control integration enables automated ventilation responses that differentiate subscription monitor services. |
| EU Market Entry | F-Gas Regulation spillover in Germany and France expands addressable demand beyond North American concentration. |
| Subscription Analytics Launch | Data logging services displace one-time kit purchases and consolidate recurring revenue pools. |
| Commercial Channel Development | Employer liability frameworks in underground workspace applications accelerate continuous monitor adoption. |
Research Methodology
Bottom-up residential transaction modeling reconciled against top-down laboratory processing capacity tracking forms the analytical core of this study. Primary interviews with EPA radon program officers, NRPP-accredited laboratory directors, home improvement retail category managers, real estate transaction attorneys, and HVAC mitigation contractors combined with secondary validation from EPA zone mapping databases, state disclosure statute compilations, Health Canada guideline publications, and EU F-Gas Regulation implementation reports. Triangulation across stakeholder inputs and documentary sources anchored volume estimates against accredited laboratory throughput constraints.
Input-output matrix framing connects charcoal canister production volumes, digital monitor shipment data, and laboratory turnaround metrics to end-use adoption rates across residential real estate, commercial property management, and environmental agency segments. Segmentation dimensions modeled include product architecture, end-user archetype, distribution channel, and testing method chemistry, with CAGRs derived from regression analysis against housing transaction velocity and regulatory mandate adoption curves. Forecast inputs incorporated EPA disclosure statute expansion timelines and smart home integration penetration assumptions.
Inputs from EPA program publications and EU regulatory filings were available through the study window; gaps in real-time laboratory capacity utilization data introduce uncertainty bands around processing bottleneck scenarios. Forecasts reflect documented assumptions regarding disclosure mandate adoption velocity and digital monitor price elasticity; unforeseen regulatory delays or faster-than-projected smart home integration could materially revise trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
Environmental Testing Market