
 Pollution Monitoring Equipment Market | 2026-2036
Pollution Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pollution Monitoring Equipment Market Analytics
EPA National Ambient Air Quality Standards revision is restructuring capital allocation across the pollution monitoring value chain. Thermo Fisher Scientific leverages its mass spectrometry depth to sustain premium positioning in regulatory-grade instrumentation. Honeywell International anchors North American industrial compliance through its distributed sensor networks and control systems integration.
Pollution monitoring equipment comprises calibrated sensor arrays, analyzers, and telemetry systems designed to detect particulate matter, gaseous contaminants, heavy metals, and acoustic emissions across air, water, and soil matrices. Optical sensors with detection thresholds below one part per billion now dominate precision environmental assessment applications where laboratory-grade accuracy matters. Electrochemical sensors compete on unit economics in industrial compliance deployments where high node density offsets moderate per-sensor precision. Smart city initiatives represent the fastest-growing application vector as municipalities embed networked monitors into traffic infrastructure and public building envelopes.
EPA enforcement shapes United States product certification requirements while China's MEE mandates real-time data transparency from stack monitors and wastewater outfalls. REACH compliance in Europe adds substance-level traceability obligations that filter into equipment design specifications. Stakeholders must weigh calibration protocol standardization against the fragmentation emerging from jurisdiction-specific data formats and reporting cadences.
Market Dynamics
Real-time emissions disclosure mandates from China's MEE and the EPA's tightened National Ambient Air Quality Standards are forcing wholesale replacement of legacy stack monitoring infrastructure across industrial corridors and municipal networks.
Growth Catalysts
- Smart city sensor deployment:Municipal governments in Asia-Pacific are embedding networked air quality monitors into traffic infrastructure and public building envelopes, creating sustained procurement pipelines.
- EPA National Ambient Air Quality Standards revision:Industrial facilities across the United States face mandatory upgrades to legacy monitoring stacks, compressing replacement cycles.
- Optical sensor precision thresholds:Detection capabilities below one part per billion now enable laboratory-grade accuracy in field-deployable units, expanding addressable applications.
Market Restraints
- Calibration protocol fragmentation:Jurisdiction-specific data formats and reporting cadences between EPA, MEE, and REACH compliance regimes force redundant engineering investments.
- Electrochemical sensor precision ceiling:Moderate per-sensor accuracy limits deployment in regulatory-grade applications despite favorable unit economics.
- Specialized component supply concentration:Mass spectrometry subsystems and precision optical arrays depend on concentrated supplier bases in Germany and Japan.
Strategic Opportunities
- India's industrial corridor expansion:Central Pollution Control Board enforcement intensification in Gujarat and Maharashtra creates first-mover advantage for certified equipment vendors.
- Acoustic emissions monitoring:Mining operations and port authorities represent underpenetrated verticals requiring integrated particulate and noise monitoring arrays.
- Edge computing convergence:On-device analytics reducing telemetry bandwidth requirements opens municipal budgets previously constrained by recurring data transmission costs.
Industry Challenges
- Cross-trained field technician scarcity:Simultaneous competence in electrochemical calibration, optical alignment, and telemetry troubleshooting commands premium compensation.
- Legacy system integration complexity:Brownfield industrial sites require custom protocol bridges between 1990s-era SCADA architectures and modern IoT-native monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pollution Monitoring Equipment Market |
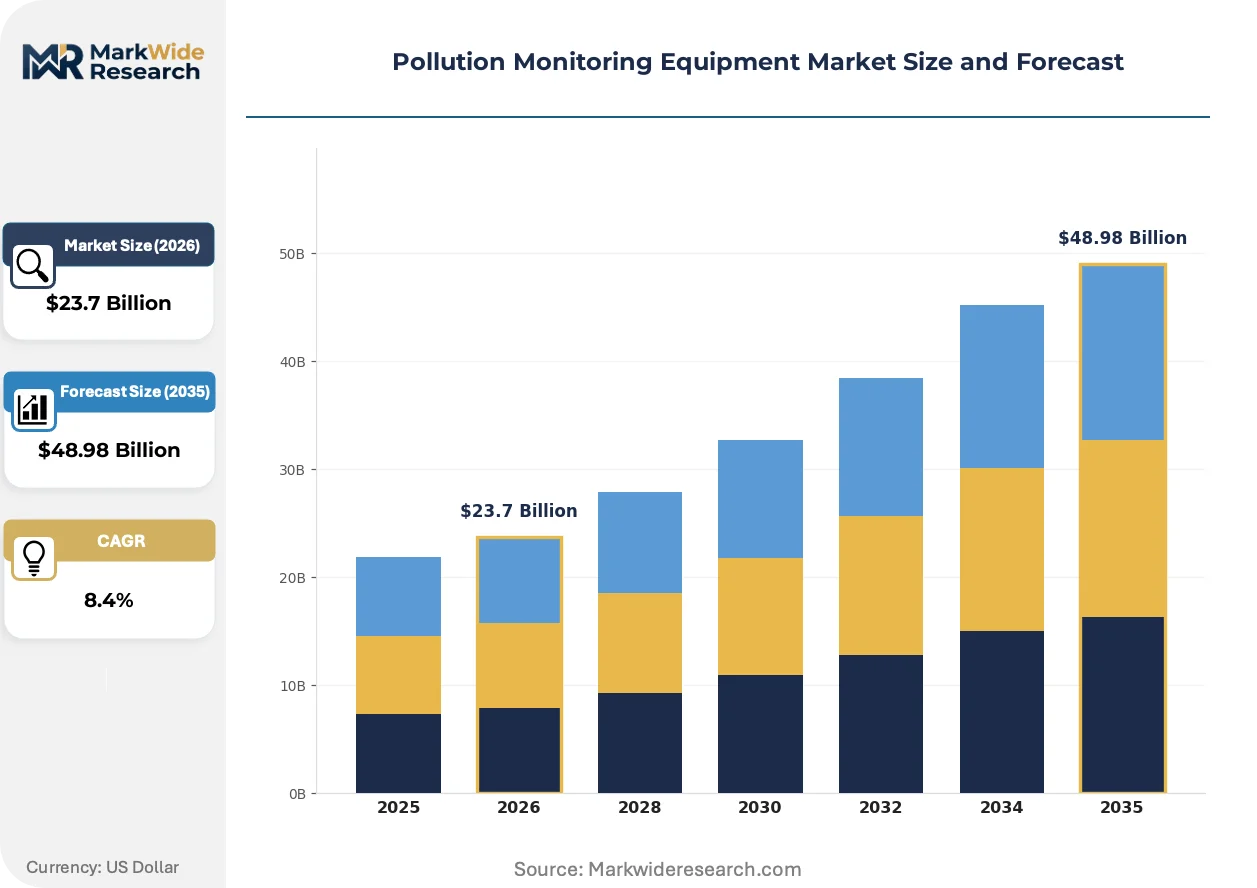
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Quality Sensors, Water Quality Monitors, Soil Sensors, Noise Monitoring Devices Application: Environmental Assessment, Industrial Compliance, Research Studies, Smart City Initiatives End User: Government Agencies, Environmental Organizations, Industries, Research Institutions Technology: Optical Sensors, Electrochemical Sensors, Gas Chromatography, Remote Sensing |
| Companies Covered | Thermo Fisher Scientific, Teledyne Technologies, Siemens AG, Honeywell International, 3M Company, Aeroqual Limited, HORIBA, PerkinElmer, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pollution Monitoring Equipment Market Evolving Landscape
Sensor miniaturization and edge intelligence are compressing the cost-performance frontier, enabling dense monitoring networks that were economically unviable with earlier generation equipment.
Optical sensors with sub-ppb detection thresholds are overtaking electrochemical alternatives in precision environmental assessment applications. Municipal air quality networks and industrial fence-line monitoring programs are adopting these units despite 3-4x unit cost premiums. The shift is compressing addressable market share for mid-tier electrochemical vendors while expanding total serviceable market for integrated optical-telemetry platforms.
REACH substance-level traceability obligations are filtering into equipment design specifications across European manufacturing. Component suppliers must now document full material declarations for sensors, housings, and cable assemblies. Industrial buyers in Germany and the Netherlands are prioritizing vendors with pre-certified supply chains, creating procurement friction for non-EU equipment manufacturers.
Service contract unbundling is disrupting traditional equipment-plus-maintenance bundles. Large industrial operators in China's Yangtze River Delta are separating hardware procurement from calibration and data analytics services, awarding multi-year telemetry contracts to specialized software vendors. This bifurcation pressures integrated equipment manufacturers to defend margin through certified consumables and proprietary data formats.
Pollution Monitoring Equipment Market Segmentation
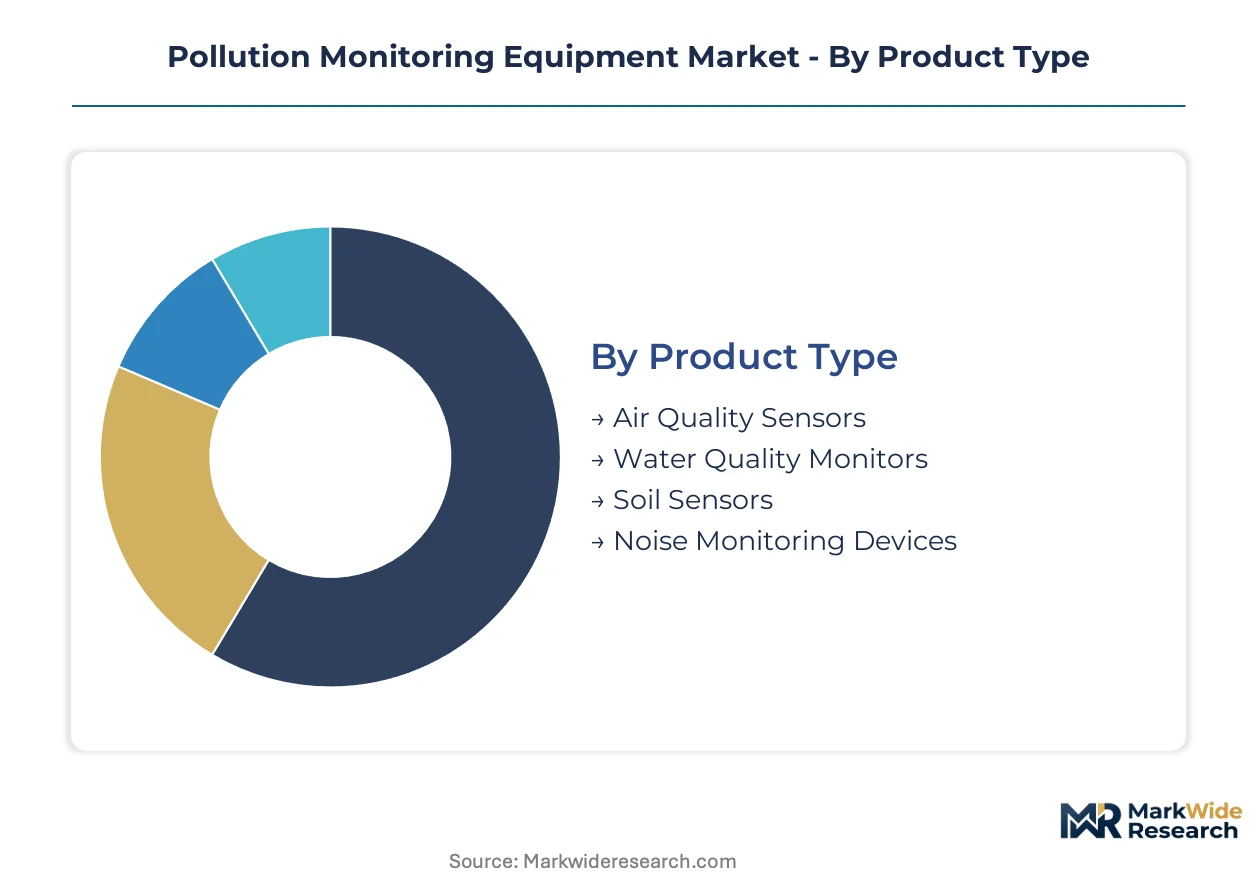
Segmentation in pollution monitoring equipment reveals how technology choices, regulatory exposure, and procurement authority fragment addressable value across divergent customer workflows. Vendors must calibrate R&D investment and channel strategy to the specific compliance regimes and performance thresholds governing each category.
Product Type:
Supply concentration in precision optical components and specialized sensor substrates creates tiered availability across product categories, with laboratory-grade units dependent on concentrated German and Japanese supplier bases.
- Air Quality Sensors:Calibrated arrays detecting particulate matter, nitrogen oxides, sulfur dioxide, and volatile organic compounds through optical scattering or electrochemical reaction. Municipal procurement in China's industrial corridor cities concentrates demand as MEE enforcement mandates real-time emissions disclosure from stack monitors and urban monitoring networks.
- Water Quality Monitors:Multi-parameter probes measuring dissolved oxygen, pH, conductivity, turbidity, and specific ion concentrations through ion-selective electrodes and optical absorption. Industrial facilities along the Yangtze River Delta and Gujarat's chemical belt drive replacement cycles as wastewater discharge permits tighten.
- Soil Sensors:In-situ probes and portable extractive systems assessing heavy metal contamination, moisture content, and nutrient profiles. Remediation contractors and agricultural regulators in contaminated land programs constitute the primary demand pool.
- Noise Monitoring Devices:Calibrated acoustic sensors with frequency-weighted decibel measurement for construction, mining, and transportation compliance. Port authorities and urban planning departments represent underpenetrated verticals requiring integration with air quality networks.
Today's leader: Air Quality Sensors. Tomorrow's challenger: Noise Monitoring Devices.
Application:
Cost tier differentiation separates capital-intensive regulatory-grade deployments from volume-driven municipal sensor networks, with software and service attach rates varying dramatically across application types.
- Environmental Assessment:Precision field studies and baseline characterization requiring laboratory-grade accuracy and defensible chain-of-custody protocols. Consulting firms and government laboratories in Germany and the Netherlands prioritize vendors with REACH-certified supply chains and full material declarations.
- Industrial Compliance:Continuous emissions monitoring and fence-line surveillance to satisfy permit conditions and avoid enforcement penalties. EPA's tightened National Ambient Air Quality Standards compress replacement cycles across United States manufacturing facilities.
- Research Studies:Academic and institutional investigations demanding configurable sensor platforms and raw data access. Funding agency requirements for open data publication shape procurement specifications.
- Smart City Initiatives:Dense urban sensor networks embedded in traffic infrastructure and public building envelopes. Asia-Pacific municipal governments represent the steepest expansion trajectory as networked air quality monitors become standard smart city infrastructure.
Industrial Compliance commands current procurement volume. Smart City Initiatives are climbing the fastest as municipal budgets shift from capital expenditure to sensor-as-a-service models.
End User:
Customer type determines pricing tolerance, contract structure, and service expectations, with government procurement cycles and industrial maintenance schedules creating divergent revenue recognition patterns.
- Government Agencies:National environmental regulators and municipal departments operating certified monitoring networks with mandated calibration protocols. India's Central Pollution Control Board enforcement intensification in Maharashtra and Gujarat creates first-mover certification requirements.
- Environmental Organizations:Non-governmental monitoring programs and advocacy-driven sensor deployments prioritizing cost efficiency and community accessibility. Crowdsourced data platforms and open-source hardware compatibility influence vendor selection.
- Industries:Chemical, power generation, mining, and manufacturing operators managing permit compliance and risk mitigation. Large operators in China's Yangtze River Delta are unbundling hardware procurement from calibration and telemetry services.
- Research Institutions:Universities and national laboratories requiring customizable platforms and publication-grade data quality. Grant funding cycles and peer-review publication timelines shape purchasing decisions.
Industries dominate current equipment revenue. Government Agencies are gaining share fastest as EPA and MEE enforcement intensifies.
Technology:
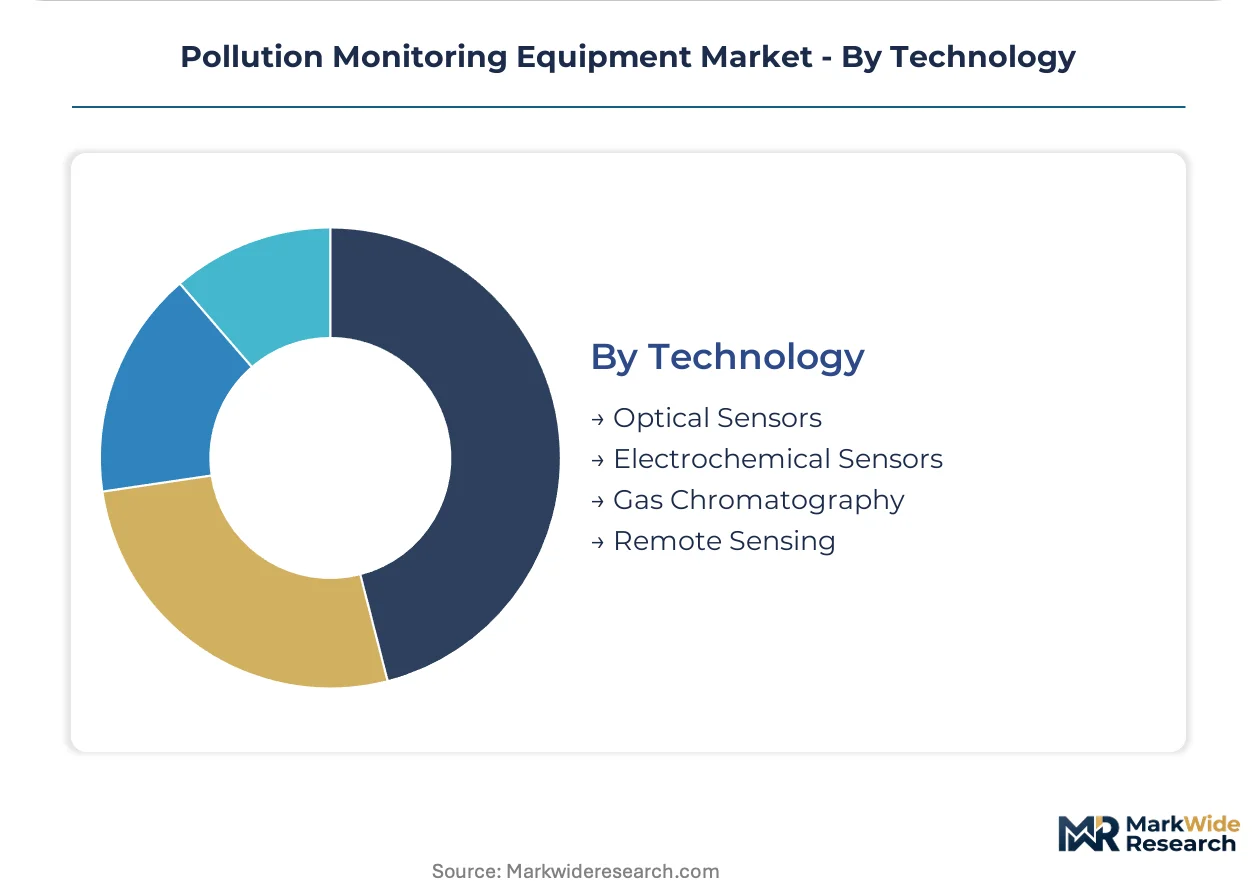
Technology maturity curves separate established electrochemical platforms from emerging optical and remote sensing modalities, with precision thresholds and total cost of ownership driving substitution patterns.
- Optical Sensors:Laser absorption spectroscopy, cavity ring-down spectroscopy, and light-scattering systems achieving detection thresholds below one part per billion. Field-deployable laboratory-grade accuracy expands addressable applications in fence-line monitoring and precision environmental assessment.
- Electrochemical Sensors:Amperometric and potentiometric cells competing on unit economics and deployment density. Moderate per-sensor precision limits regulatory-grade applications despite favorable capital costs for high-node networks.
- Gas Chromatography:Separative analytical systems for complex mixture characterization and speciated organic compound identification. Stack testing laboratories and research facilities maintain demand for reference-grade measurements.
- Remote Sensing:Satellite-based hyperspectral imaging and ground-based lidar systems for regional-scale pollution mapping. Atmospheric research programs and regulatory trend analysis constitute primary use cases.
Optical Sensors anchor premium positioning. Remote Sensing represents the most speculative expansion path dependent on data fusion algorithm advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration technicians and field service engineers cluster in Germany's precision instrumentation belt, China's industrial corridor cities, and the United States' Gulf Coast petrochemical corridor. These talent concentrations anchor regional equipment procurement patterns and aftermarket service capabilities.
United States
Stack monitoring replacement cycles dominate demand as EPA enforcement compresses capital expenditure timelines. The National Ambient Air Quality Standards revision forces upgrades across Texas, Louisiana, and Ohio River Valley chemical complexes. Houston's petrochemical corridor generates concentrated procurement of continuous emissions monitoring systems.
Germany
REACH substance-level traceability obligations filter into equipment design specifications for precision optical components. ECHA compliance documentation requirements favor vendors with pre-certified supply chains and full material declarations. Bavaria's instrumentation manufacturing belt anchors European production of laboratory-grade analyzers.
China
MEE real-time disclosure mandates drive networked sensor deployment across Yangtze River Delta manufacturing zones. Municipal smart city programs in Beijing, Shanghai, and Shenzhen embed air quality monitors into traffic infrastructure. Guangdong's electronics manufacturing clusters demand fence-line monitoring arrays for volatile organic compound surveillance.
India
Central Pollution Control Board enforcement intensification in Gujarat and Maharashtra creates certification urgency for industrial operators. Chemical belt facilities along the western coast face compressed compliance timelines for wastewater discharge monitoring. Ahmedabad and Mumbai industrial corridors represent first-mover procurement opportunities for certified equipment vendors.
Japan
Precision optical component supply concentrates in Nagoya and Osaka manufacturing zones, creating tiered availability for field-deployable analyzers. METI industrial decarbonization programs accelerate stack monitoring upgrades across Kansai steel and chemical complexes. Japanese sensor substrate suppliers maintain critical positions in mass spectrometry subsystem value chains.
Pollution Monitoring Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Thermo Fisher Scientific and Honeywell International anchor premium regulatory-grade instrumentation through mass spectrometry depth and distributed sensor network integration. Mid-tier electrochemical vendors compete on unit economics for high-node municipal deployments. Strategic moves concentrate on unbundling service contracts from hardware procurement and defending margin through proprietary data formats.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Honeywell International exemplify contrasting geographic anchoring—Waltham-based mass spectrometry depth versus Charlotte-rooted industrial control systems integration. HORIBA represents the specialized Japanese precision optical archetype. These three occupy positions spanning regulatory-grade laboratory equipment through field-deployable fence-line monitoring platforms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Teledyne Technologies |
| Siemens AG |
| Honeywell International |
| 3M Company |
| Aeroqual Limited |
| HORIBA |
| PerkinElmer |
| Agilent Technologies |
| Others |
Value Network & Pricing Analysis
Municipal procurement offices in Asia-Pacific smart city programs anchor pricing power for volume-tier electrochemical sensors, compressing margins for mid-tier vendors while optical instrumentation commands certification-linked premiums in regulatory-grade deployments.
Pricing Analysis
Bundled hardware-plus-service contracts still dominate industrial compliance sales, though unbundling accelerates in China's Yangtze River Delta where operators separate equipment procurement from telemetry and analytics subscriptions. Pricing stratifies across regulatory-grade optical systems, mid-tier electrochemical networks, and economy-grade portable units, with EPA and MEE certification tiers driving differentiation. Cost compression in electrochemical nodes intensifies as Chinese municipal buyers consolidate purchase volumes. Environmental organizations and crowdsourced monitoring programs exhibit highest price sensitivity, while German industrial buyers prioritize REACH-certified supply chains over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's Central Pollution Control Board certification requirements and China's MEE procurement guidelines are reshaping sourcing patterns for stack monitoring assemblies. Precision optical subsystems and mass spectrometry components concentrate in Germany and Japan, while electrochemical cell manufacturing clusters in South Korea and Taiwan feed high-volume sensor networks. The supply chain rests on specialized laser sources, ion-selective electrode substrates, and telemetry chipsets. Single-source vulnerability in precision optical arrays from Nagoya and Osaka suppliers creates geographic concentration risk. Distribution runs through authorized service networks for regulatory-grade equipment and direct OEM channels for municipal volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
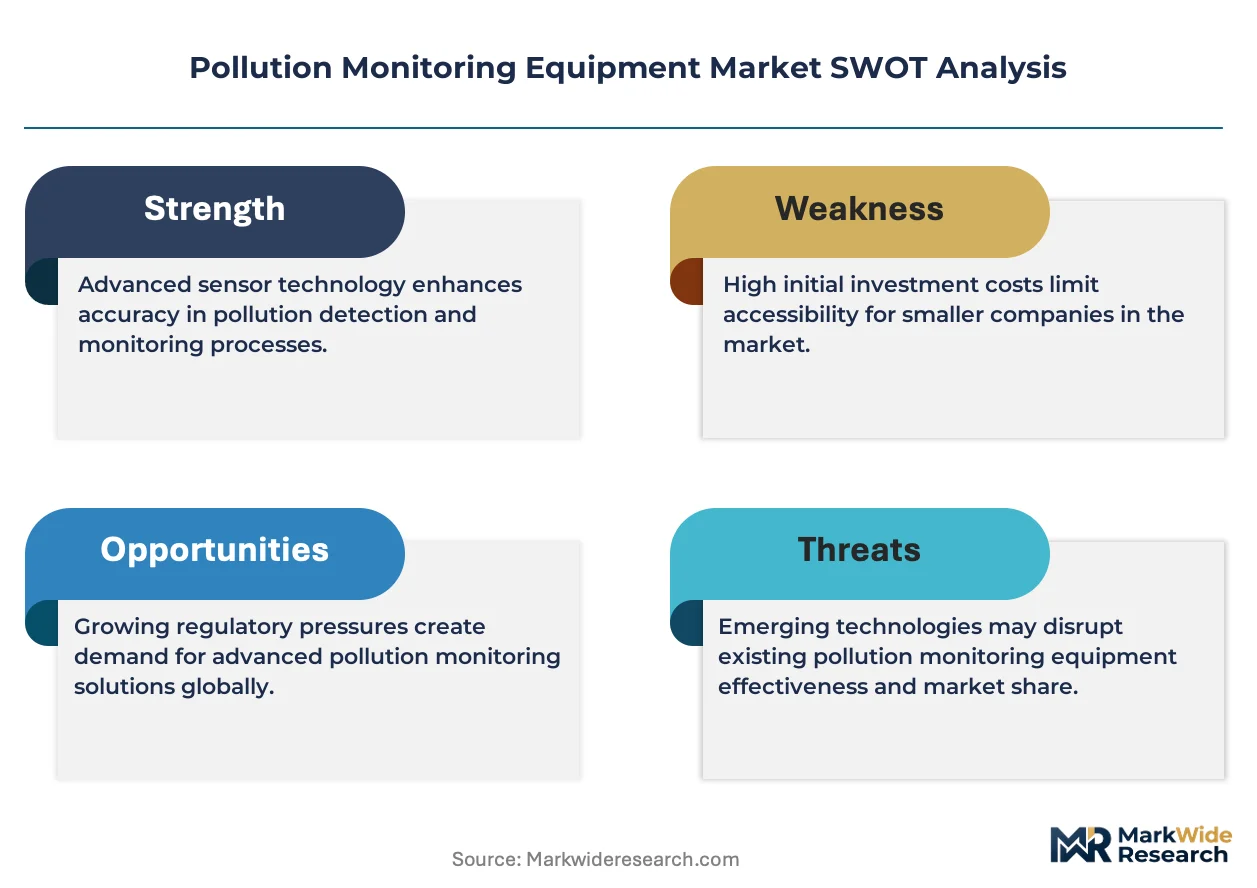
Pollution monitoring equipment has entered a late-cycle quality phase where optical precision and certified data chains displace price-driven electrochemical volume plays, with EPA and MEE enforcement tightening specification floors across industrial and municipal procurement.
For Market Incumbents: Lock in calibration protocol standardization to defend against software-native entrants unbundling telemetry services. Deepen backward integration into precision optical component supply from Japanese substrate suppliers. Certification moats around EPA and MEE compliance documentation create switching costs that proprietary data formats reinforce. For New Entrants and Emerging Players: India's Central Pollution Control Board enforcement intensification in Gujarat and Maharashtra opens a window for certified equipment vendors lacking legacy SCADA integration burdens. Noise monitoring devices for port authorities and mining operations represent the most penetrable vertical, with integrated acoustic-particulate arrays commanding limited incumbent attention. Pursue sensor-as-a-service municipal contracts to bypass capital-budget procurement cycles. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking fence-line monitoring capabilities to complement distributed control systems. Five-to-ten year viability favors vendors with mass spectrometry depth or edge-computing telemetry platforms over pure electrochemical assemblers. Watch for MEE disclosure mandate expansion beyond Yangtze River Delta as inflection signal for certified equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Protocol Standardization | EPA and MEE certification requirements lock in recurring service revenue and raise rival switching costs. |
| Edge Computing Integration | On-device analytics reduce telemetry bandwidth costs for municipal buyers in Asia-Pacific smart city deployments. |
| REACH Supply Chain Certification | Full material declarations from German and Dutch vendors capture procurement preference in European industrial compliance. |
| Acoustic Emissions Platform Launch | Integrated noise-particulate arrays address underpenetrated mining and port authority verticals with limited incumbent presence. |
| Sensor-as-a-Service Model | Subscription pricing bypasses municipal capital budget constraints and creates multi-year revenue visibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at chemical and power generation facilities, procurement leads at municipal environmental departments, aftermarket service heads at instrumentation distributors, and regulatory affairs specialists at EPA and MEE offices with secondary validation from EPA enforcement data, MEE disclosure filings, REACH substance databases, and customs records for precision optical component trade flows. Bottom-up equipment shipment tracking and top-down industrial compliance spending estimates triangulated market sizing.
Segment-weighting across product type, application, end user, and technology dimensions informed the analytical framework, with optical sensor, electrochemical sensor, gas chromatography, and remote sensing categories modeled separately across the projection horizon. CAGRs derived from replacement cycle analysis, regulatory enforcement intensity scoring, and municipal smart city budget allocation trends. Industry-specific forecast inputs included MEE real-time disclosure mandate rollout timelines and EPA National Ambient Air Quality Standards revision implementation phases.
Revisions become necessary when regulatory enforcement intensity shifts, precision optical component supply disruptions materialize, or municipal procurement models accelerate toward unbundled service contracts. Forecasts reflect documented assumptions about certification timeline adherence and sensor network deployment cadence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
North America Emission Monitoring System Market