
 Smart Water Monitoring Market | 2026-2036
Smart Water Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Monitoring Market Analytics
EPA Lead and Copper Rule revisions is shifting compliance costs toward continuous monitoring infrastructure for municipal distributors. Xylem leverages its vertical integration across sensor hardware and analytics platforms to capture utility upgrade cycles. Badger Meter anchors its position through specialized ultrasonic flow measurement technology for residential and commercial endpoints. IBM Corporation competes via cloud-based data architecture that integrates disparate utility legacy systems.
Smart water monitoring encompasses networked sensor arrays, telemetry systems, and software platforms that collect, transmit, and analyze hydraulic and water quality parameters in distribution networks, treatment facilities, and consumption points. These systems typically operate through IoT-enabled devices sampling pH, turbidity, pressure, and flow at intervals ranging from seconds to minutes, with edge computing preprocessing reducing transmission loads before cloud analytics generate actionable alerts for utility operators. IoT Devices and Sensors dominate current hardware procurement volumes, though Data Analytics represents the fastest-expanding margin pool as utilities prioritize predictive maintenance over reactive response. Water Quality Sensors command premium pricing due to calibration complexity and regulatory certification requirements, while Flow Meters constitute the most mature segment with established vendor relationships and replacement-driven demand cycles.
EPA regulations in the United States, the EU Drinking Water Directive enforced by member state environmental agencies, and ISO 24500 series standards collectively shape product certification requirements and procurement specifications across developed markets. Compliance deadlines force utilities to budget for certified monitoring equipment, effectively filtering uncertified vendors from municipal tenders. Stakeholders must weigh capital deployment timing against regulatory phase-in schedules and infrastructure bond issuance windows.
Market Dynamics
EPA Lead and Copper Rule revisions are compressing utility procurement cycles toward continuous monitoring infrastructure, forcing capital allocation decisions ahead of bond issuance windows and infrastructure replacement schedules.
Growth Catalysts
- EU Drinking Water Directive compliance deadlines:German utilities face binding infrastructure replacement mandates that accelerate certified sensor procurement timelines.
- Non-revenue water loss reduction targets:Municipal distributors deploy real-time network visibility systems to identify leaks and pressure anomalies before physical inspection.
- Ultrasonic flow measurement:Residential and commercial endpoints adopt solid-state metering to eliminate mechanical wear and enable remote telemetry.
Market Restraints
- Water quality sensor calibration complexity:Regulatory certification requirements for pH and turbidity devices extend vendor qualification periods and inflate service costs.
- Legacy system integration friction:Disparate SCADA architectures in established utilities resist cloud-native platform connectivity without middleware investment.
- Edge computing hardware costs:Distributed preprocessing units for telemetry systems strain capital budgets relative to centralized data lake alternatives.
Strategic Opportunities
- Predictive maintenance service models:Data analytics platforms monetize subscription revenue streams beyond hardware installation cycles.
- IoT-enabled pressure monitoring:Convergence of low-power wide-area networks with MEMS sensors opens greenfield deployment in aging distribution networks.
- ISO 24500 series certification pathways:Standardized procurement specifications enable vendor qualification across multiple municipal tender processes.
Industry Challenges
- Cross-functional talent scarcity:Utilities struggle to recruit personnel combining hydraulic engineering expertise with cloud architecture skills.
- Multi-vendor interoperability testing:Sensor arrays from disparate manufacturers require extensive field validation before network deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Monitoring Market |
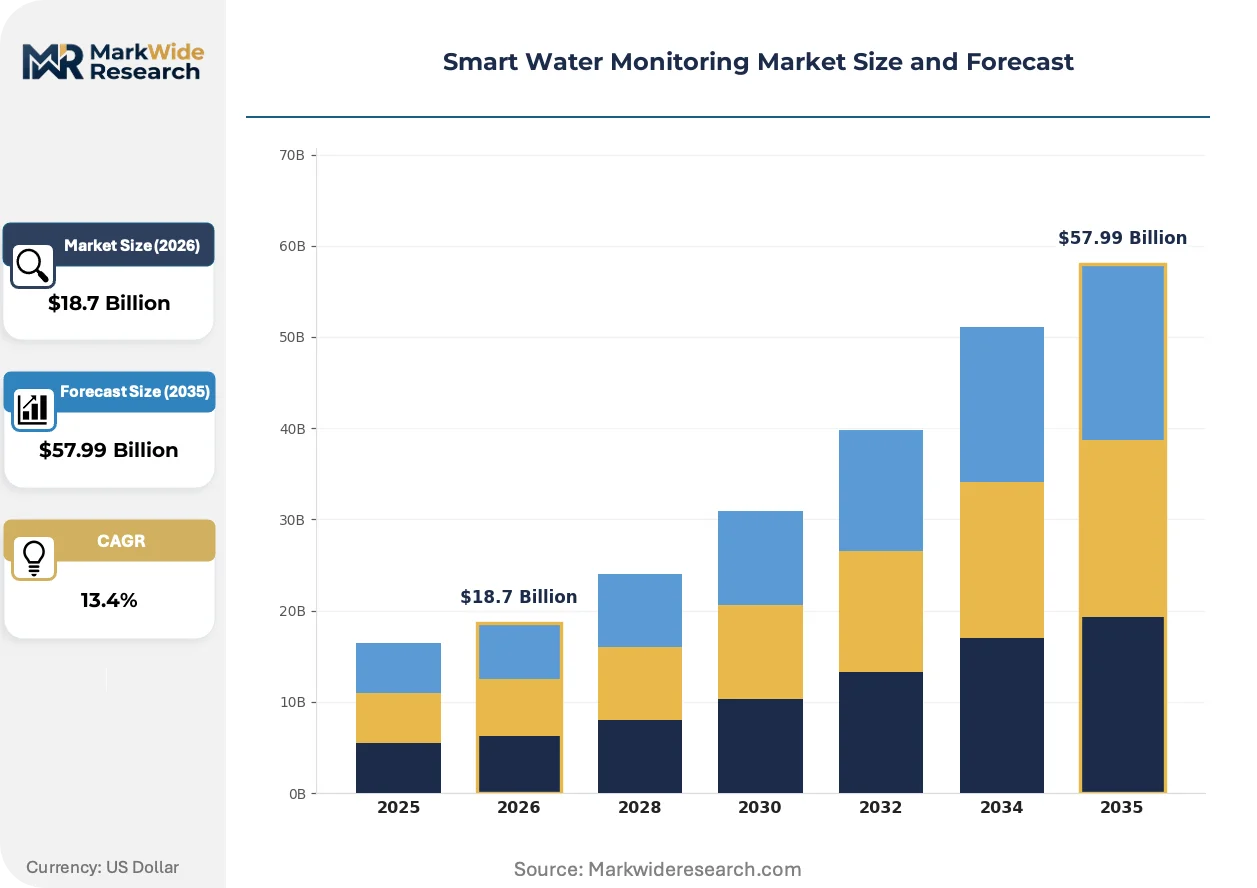
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, Sensors, Data Analytics, Cloud Computing Product Type: Flow Meters, Water Quality Sensors, Pressure Sensors, Level Sensors End User: Municipalities, Industrial, Agricultural, Residential Application: Leak Detection, Water Quality Monitoring, Smart Irrigation, Consumption Tracking |
| Companies Covered | General Electric, Itron, IBM Corporation, Schneider Electric, ABB, Siemens, Badger Meter, Xylem, SUEZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Monitoring Market Evolving Landscape
Digital twin architecture is reshaping how utilities simulate hydraulic behavior, compressing design validation timelines and enabling scenario modeling without physical network disruption.
Edge AI inference at telemetry nodes is electrifying real-time anomaly detection capabilities. Municipal distributors in water-stressed regions deploy these units to filter false positives before cloud transmission. The technology is electrifying demand for on-device processing silicon and specialized firmware stacks.
EPA enforcement discretion letters under revised Lead and Copper Rule provisions are tightening data transparency requirements. Utilities must submit continuous monitoring records rather than periodic sampling results. Large municipal distributors in the Great Lakes region are accelerating procurement of certified lead sensors to meet disclosure timelines.
Performance-based service contracts are displacing capital purchase agreements for monitoring infrastructure. Water utilities in California and Texas now contract for guaranteed leak detection rates rather than sensor ownership. This procurement shift concentrates vendor selection on analytics accuracy metrics rather than hardware specifications alone.
Smart Water Monitoring Market Segmentation
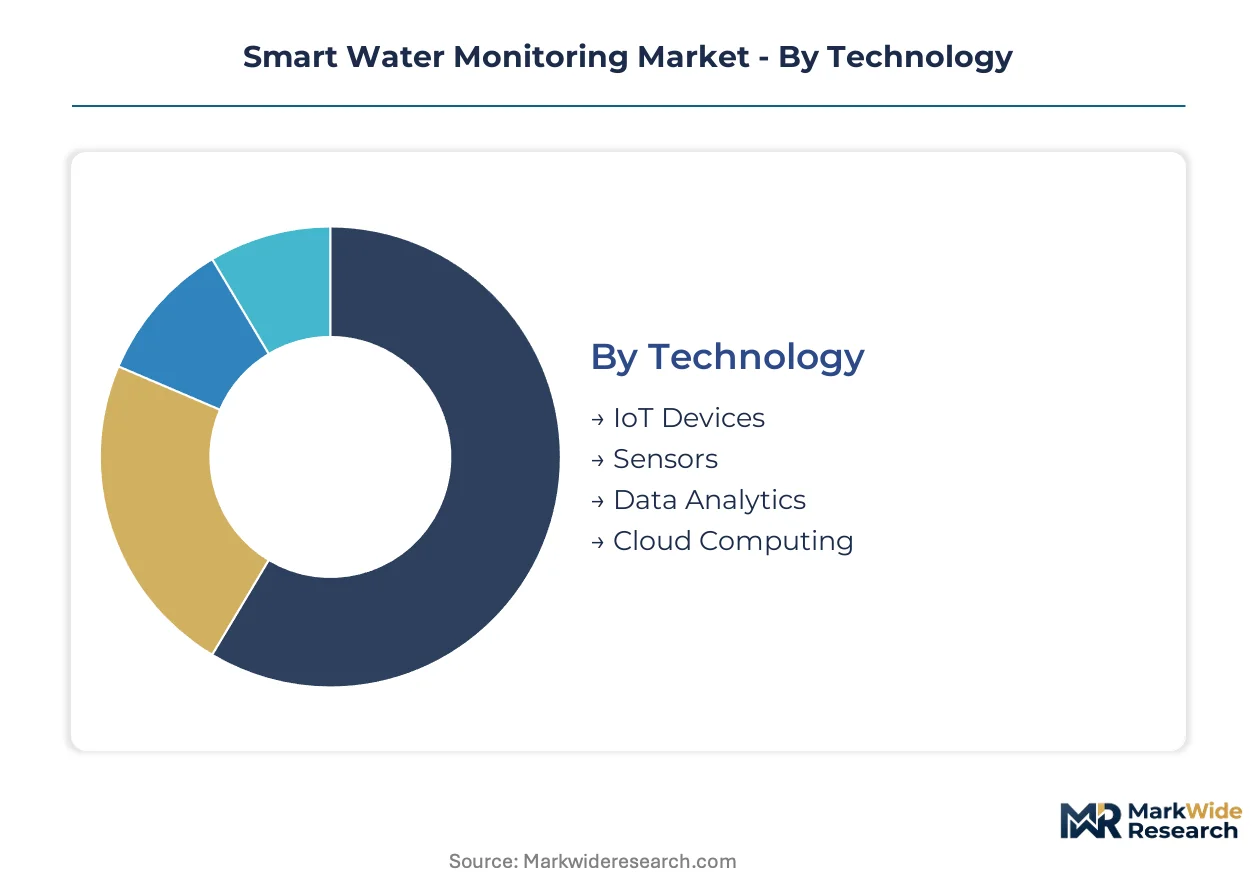
Smart water monitoring procurement splits across hardware specifications, software architectures, and operational use cases. Utility capital allocation patterns differ sharply between compliance-driven sensor replacement and greenfield IoT network deployment. Understanding these segment boundaries clarifies where vendor margins concentrate versus where price competition erodes returns.
Technology:
Technology selection hinges on data latency requirements and capital deployment sequencing across utility infrastructure cycles.
- IoT Devices:Networked telemetry hardware with LPWAN or cellular connectivity enables minute-interval sampling across distribution networks. Municipal utilities in Germany deploy these units to meet EU Drinking Water Directive continuous monitoring mandates ahead of compliance deadlines.
- Data Analytics:Cloud-based algorithmic platforms process hydraulic and quality parameters to generate predictive maintenance alerts. This segment gains share fastest as utilities shift from reactive repair schedules toward subscription-based outcome guarantees.
- Sensors:Solid-state and electrochemical detection elements measuring pH, turbidity, and residual chlorine. EPA certification requirements for lead and copper monitoring extend vendor qualification timelines.
- Cloud Computing:Centralized data architecture integrating disparate SCADA systems through API middleware. Procurement concentrates among large municipal distributors with legacy infrastructure fragmentation.
IoT Devices leads on scale; Data Analytics leads on momentum.
Product Type:
Product differentiation tracks measurement precision requirements and mechanical durability specifications across installation environments.
- Flow Meters:Ultrasonic and electromagnetic devices measuring volumetric throughput without mechanical wear. Residential and commercial endpoints in the United States adopt solid-state designs to eliminate maintenance cycles and enable remote telemetry.
- Water Quality Sensors:Multi-parameter probes requiring calibration protocols and regulatory certification. These command premium pricing due to EPA and ISO 24500 compliance documentation burdens.
- Pressure Sensors:MEMS-based transducers detecting network anomalies and leak precursors through hydraulic signature analysis. Aging infrastructure replacement cycles drive procurement in German distribution networks.
- Level Sensors:Ultrasonic and radar instruments monitoring reservoir and tank volumes. Industrial end-users deploy these for inventory management and overflow prevention.
Flow Meters dominates procurement volume; Water Quality Sensors captures the steepest expansion trajectory.
End User:
End user segmentation reflects divergent procurement authority structures and regulatory exposure across public and private water management.
- Municipalities:Public water utilities managing distribution networks under EPA and EU Drinking Water Directive compliance frameworks. Bond issuance windows and infrastructure replacement schedules shape capital deployment timing.
- Industrial:Manufacturing and processing facilities with process water quality requirements and discharge permit obligations. These buyers prioritize integration with existing SCADA architectures.
- Agricultural:Irrigation districts and farm operations deploying soil moisture and flow monitoring for water rights compliance and yield optimization.
- Residential:Individual property owners and homeowner associations adopting smart metering for consumption visibility and leak detection.
Municipalities anchor procurement value; Industrial segments expand most quickly through performance-based service contracting.
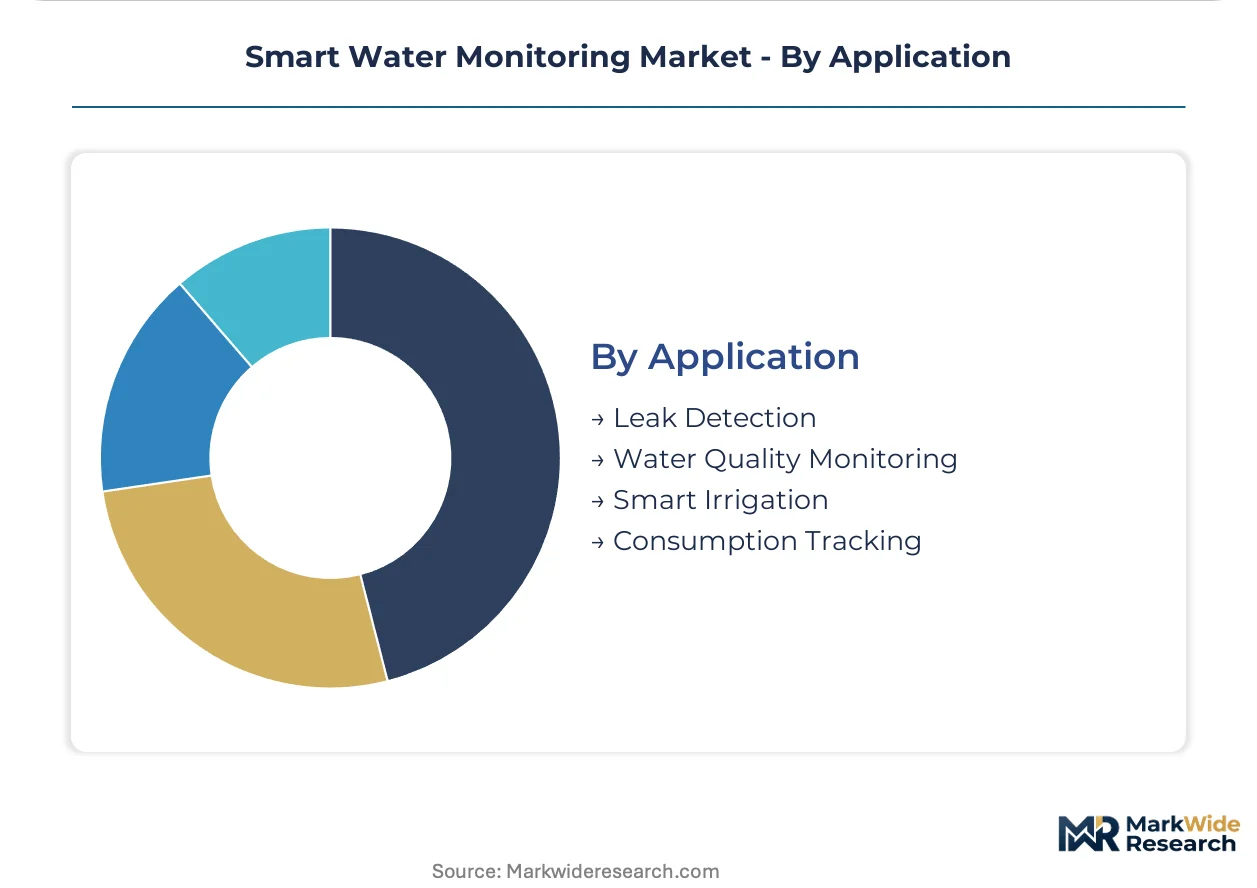
Application:
Application focus determines sensor array configuration and analytics platform specification during system design.
- Leak Detection:Pressure transient analysis and acoustic monitoring to identify pipe failures before surface manifestation. Non-revenue water reduction targets in California and Texas utilities concentrate demand here.
- Water Quality Monitoring:Continuous sampling for regulatory compliance and public health protection. EPA Lead and Copper Rule revisions mandate enhanced data transparency for municipal distributors.
- Smart Irrigation:Soil moisture integration with weather data to optimize agricultural water application. These systems reduce consumption in water-stressed regions.
- Consumption Tracking:Residential and commercial metering for billing accuracy and demand management. Ultrasonic endpoint adoption displaces mechanical meter replacement cycles.
Leak Detection commands the largest project scale; Water Quality Monitoring faces the most stringent certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers with combined hydraulic and cloud architecture expertise concentrate procurement authority in German municipal utilities and American Great Lakes distributors, compressing vendor qualification timelines across both markets.
United States
EPA Lead and Copper Rule revisions mandate continuous monitoring disclosure for municipal distributors. Large utilities in the Great Lakes region accelerate certified lead sensor procurement ahead of enforcement discretion deadlines. Chicago and Detroit metropolitan water authorities bond-finance infrastructure replacement cycles.
Germany
EU Drinking Water Directive compliance deadlines force binding infrastructure replacement mandates on aging distribution networks. Federal environmental agencies enforce stringent certification requirements for pH and turbidity devices. Utilities in North Rhine-Westphalia deploy real-time pressure monitoring across corroded pipe segments.
China
Provincial water authorities under MEE oversight expand smart metering deployment in water-stressed northern regions. National standards for IoT-enabled quality monitoring tighten data transparency obligations. Yangtze River Delta municipalities pilot edge-computing telemetry nodes in Shanghai and Hangzhou distribution networks.
Japan
METI efficiency targets drive ultrasonic flow meter adoption in Tokyo and Osaka metropolitan utilities. JIS certification requirements extend vendor qualification periods for multi-parameter water quality probes. Kansai region distributors integrate predictive maintenance platforms with existing SCADA architectures.
United Kingdom
Environment Agency discharge permits tighten real-time monitoring requirements for industrial water users. Ofwat regulatory pressure on non-revenue water losses accelerates leak detection procurement. Thames Water and United Utilities deploy acoustic monitoring arrays across London and Manchester distribution zones.
Smart Water Monitoring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated system tiers. The vendor base stratifies between industrial automation conglomerates with captive sensor divisions and telemetry-focused specialists with cloud-native architectures. Three archetypes dominate: diversified industrial technology groups, water-dedicated equipment manufacturers, and enterprise software platforms with utility verticals. Capacity expansion concentrates in ultrasonic metering and edge AI inference hardware, while strategic partnerships bridge legacy SCADA integration gaps.
Among diversified industrial technology groups, General Electric, Siemens, and ABB exemplify the integrated automation-to-analytics archetype. These conglomerates occupy positions spanning sensor hardware through cloud platforms, leveraging established utility relationships across municipal and industrial segments. Xylem and Badger Meter represent the water-dedicated specialist tier, with geographic naming anchoring their heritage in fluid technology domains. IBM Corporation sits within the enterprise software vector, offering data architecture that absorbs disparate utility legacy systems without hardware manufacturing exposure.
| Leading Market Players |
|---|
| General Electric |
| Itron |
| IBM Corporation |
| Schneider Electric |
| ABB |
| Siemens |
| Badger Meter |
| Xylem |
| SUEZ |
| Others |
Value Network & Pricing Analysis
Family-owned German sensor specialists and private-equity-rolled-up telemetry providers anchor supply-side discipline, translating concentrated component sourcing into pricing power over municipal utilities facing EPA and EU Drinking Water Directive compliance deadlines.
Pricing Analysis
Bundled hardware-software service contracts now dominate municipal procurement, displacing capital purchase agreements across water utilities in California and Texas. Price differentiation rests on EPA certification tier and analytics accuracy guarantees rather than sensor specifications alone. Cost compression in mid-tier ultrasonic metering intensifies as Asian manufacturers expand LPWAN-enabled endpoint production. Industrial end-users exhibit lowest price sensitivity due to SCADA integration requirements and discharge permit liability exposure.
Supply Chain Analysis
Reverse-logistics flows for pH and turbidity sensor refurbishment concentrate in Germany and the United States, extending asset lifecycles for utilities under budget constraints. Manufacturing draws from semiconductor fabrication in Taiwan, MEMS sensor production in Japan, and electrochemical probe assembly in Germany. Single-source vulnerability in edge-computing silicon creates procurement risk for telemetry node deployments. Distribution runs through authorized utility channel partners with EPA certification training capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
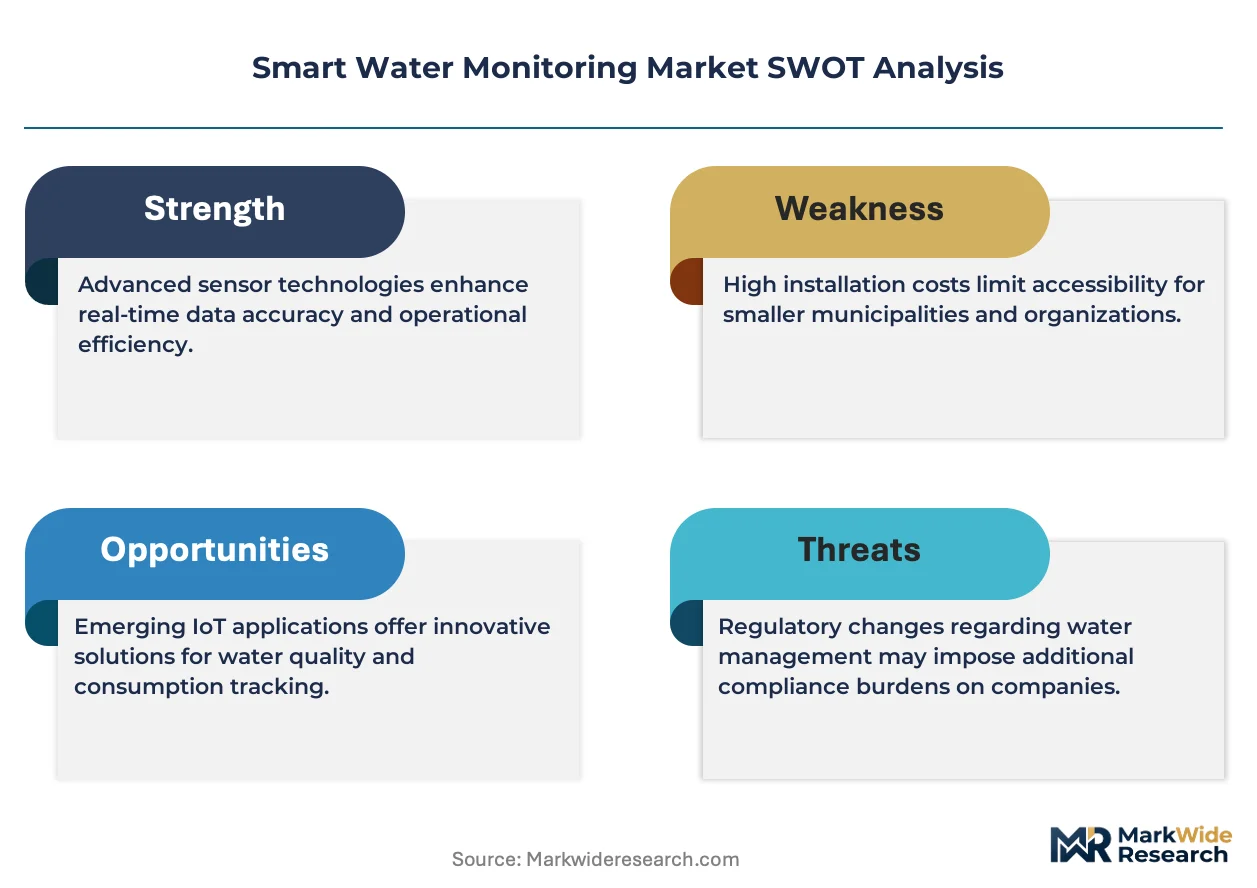
The Smart Water Monitoring Market reads as a late-cycle quality story where utilities prioritize predictive maintenance subscriptions over reactive hardware replacement, elevating vendors with ISO 24500-certified analytics platforms.
For Market Incumbents: To counter cloud-native platform entrants, Xylem and Badger Meter should deepen backward integration into MEMS sensor fabrication and secure exclusive distribution agreements with Great Lakes municipal utilities ahead of EPA Lead and Copper Rule enforcement discretion deadlines. For New Entrants and Emerging Players: Enter via agricultural irrigation districts in water-stressed Texas and California regions where leak detection procurement lags municipal sophistication. Target outcome-based service contracting with guaranteed consumption reduction metrics to bypass incumbent hardware relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap telemetry specialists with captive LPWAN connectivity stacks and pending EPA lead sensor certifications. Long-term viability hinges on recurring analytics revenue exceeding 40% of total mix. Monitor EPA enforcement discretion letter issuance rates as inflection indicator for certified sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Shifts municipal utilities from capital expenditure to subscription revenue models. |
| EPA Lead Sensor Certification Investment | Unlocks procurement eligibility for Great Lakes region infrastructure replacement cycles. |
| Edge AI Telemetry Node Development | Enables real-time anomaly filtering before cloud transmission in water-stressed regions. |
| SCADA Middleware Partnership | Bridges legacy system fragmentation for industrial end-users with disparate architectures. |
| Ultrasonic Metering Capacity Expansion | Captures residential and commercial endpoint replacement demand eliminating mechanical wear. |
Research Methodology
Direct dialogue with utility planning officers, SCADA integration specialists, EPA regulatory affairs leads, and municipal bond issuance advisors grounded qualitative findings, cross-referenced against EPA enforcement discretion letters, EU Drinking Water Directive compliance databases, utility capital expenditure disclosures, and ISO 24500 certification registries. Bottom-up sensor shipment tallies and top-down infrastructure replacement budget aggregation provided triangulation anchors.
Bottom-up modeling tracked IoT device deployments, analytics platform subscriptions, and sensor replacement cycles across technology, product type, end user, and application dimensions. CAGRs were derived from utility capital allocation patterns and regulatory phase-in schedules. Forecast inputs incorporated LPWAN network coverage expansion, edge-computing hardware cost trajectories, and predictive maintenance contract penetration rates.
Inputs from EPA enforcement discretion letter archives and German federal environmental agency procurement databases were available through the study window; gaps in real-time Chinese provincial water authority expenditure disclosures introduce uncertainty bands around Asia-Pacific volume estimates. Forecasts reflect modeled assumptions regarding regulatory timeline adherence and infrastructure bond issuance windows. Practitioners should monitor EPA Lead and Copper Rule revision implementation pace and EU Drinking Water Directive deadline extensions for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Green Mining Market