
 Climate Tech Market | 2026-2036
Climate Tech Market Size, Share, and Industry Trends Forecast 2026-2036
Climate Tech Market Analysis
China is tilting its manufacturing base toward electrolyzer and photovoltaic component output at scale. Helion Energy leverages its fusion prototype program to anchor long-term baseload power ambitions. Redwood Materials controls a closed-loop battery materials recovery network that sustains cathode supply for domestic cell producers. Commonwealth Fusion Systems competes on magnet technology intensity to differentiate its reactor architecture from conventional tokamak approaches.
Climate tech encompasses engineered systems, digital platforms, and process innovations that measure, reduce, or remove greenhouse gas emissions across industrial, commercial, and residential activity. Carbon capture systems operate at atmospheric or point-source concentration levels, typically employing solid sorbent or liquid amine contactors to achieve separation thresholds required for geological sequestration or synthetic fuel synthesis. Renewable Energy leads technology deployment by installed capacity, while Energy Storage captures the fastest expansion trajectory as lithium-ion and emerging iron-air chemistries scale for multi-hour grid applications. Smart Grids occupy a mature infrastructure replacement cycle where margin pools concentrate in software-defined control layers rather than hardware substitution alone.
The EPA enforces power sector emissions standards that shape demand for carbon capture retrofits at existing fossil facilities. The EU AI Act and CSRD impose disclosure and algorithmic accountability requirements on climate software vendors operating across European markets. China's MIIT issues GB standards that dictate product certification thresholds for domestic and export-bound clean technology equipment. Stakeholders must monitor how divergent certification timelines across these jurisdictions fragment go-to-market sequencing for integrated climate technology platforms.
Market Dynamics
Grid-scale battery procurement under the EU Green Deal is forcing synchronous generation retirements faster than transmission operators can reconfigure stability services. This mismatch between renewable capacity additions and grid inertia management sits at the center of current market tension.
Growth Catalysts
- Production Tax Credits:The Inflation Reduction Act's manufacturing incentives anchor solar, hydrogen, and carbon removal facility investments across the United States.
- Electrolyzer Scale-Up:China's MIIT-directed capacity expansion in electrolyzer and photovoltaic component output compresses clean hydrogen production costs.
- Carbon Removal Mandates:Corporate net-zero commitments are pulling engineered carbon dioxide removal into offtake contracting at prices that sustain project finance.
Market Restraints
- Lithium Supply Concentration:Spodumene and brine processing capacity clusters in Chile, Australia, and China expose cell manufacturers to geopolitical supply interruptions.
- Interconnection Queues:US FERC Order 2023 implementation lags leave renewable projects stranded in multi-year transmission access delays.
- Amine Degradation:Liquid solvent carbon capture systems face energy penalty floors that limit retrofit economics at existing gas-fired plants.
Strategic Opportunities
- Iron-Air Long-Duration Storage:Multi-day discharge chemistries open grid services beyond lithium-ion's four-hour economics, targeting Midwest ISO markets.
- India PLI Scheme:Production-linked incentives for solar module and advanced chemistry cell manufacturing attract supply chain relocation from China.
- EU AI Act Alignment:Climate software vendors embedding algorithmic accountability into carbon accounting platforms capture CSRD-mandated disclosure demand.
Industry Challenges
- Magnet Engineering Scarcity:High-temperature superconductor fabrication and plasma physics specialization shortages constrain fusion reactor development timelines.
- Certification Fragmentation:Divergent GB standard, CE marking, and UL certification timelines force redundant testing spend for integrated platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Climate Tech Market |
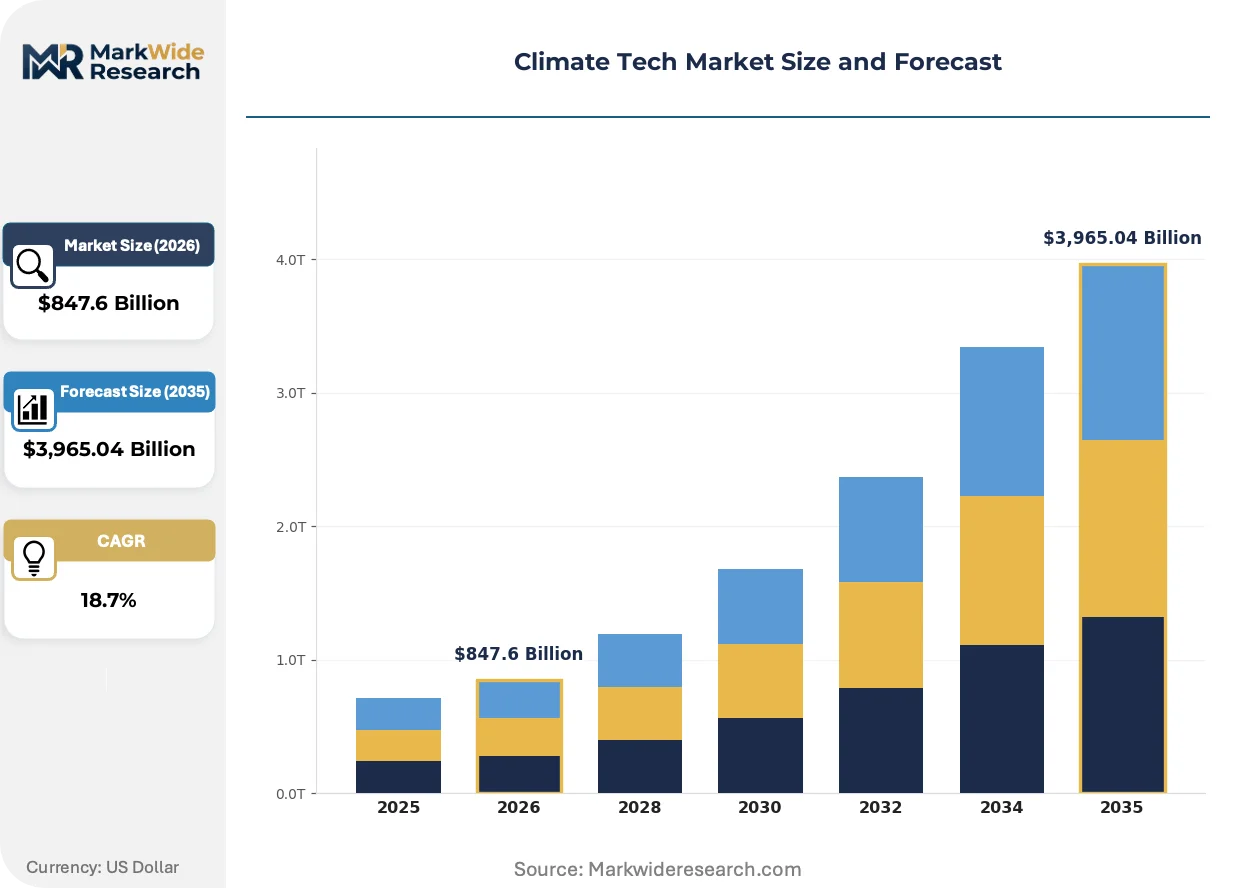
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $3,965.04 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Carbon Capture, Renewable Energy, Smart Grids, Energy Storage Application: Energy Efficiency, Waste Management, Water Treatment, Sustainable Agriculture End User: Government, Corporations, NGOs, Residential Users Service Type: Consulting, Software Solutions, Installation, Maintenance |
| Companies Covered | Helion Energy, Dandelion Energy, Fervo Energy, Pachama, 247Solar, Commonwealth Fusion Systems, Factorial, Green Project, Redwood Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Climate Tech Market Emerging Trajectories
Artificial intelligence is compressing the design-test-deploy cycle across climate hardware, from materials discovery to grid dispatch optimization. This acceleration is collapsing traditional stage-gate development timelines.
Solid-state battery architectures are collapsing the thermal management footprint and fire suppression requirements that constrain lithium-ion pack density. Automotive OEMs in South Korea and Japan are qualifying sulfide and oxide electrolyte cells for 2026 platform integration. The structural consequence is collapsing the gap between cell-level energy density and system-level pack efficiency.
The EU F-Gas Regulation phase-down is forcing refrigerant transitions in heat pump and stationary cooling equipment. Manufacturers are redesigning compressors and heat exchangers for propane and CO2 working fluids. Cold climate heat pump deployments in Nordic markets are absorbing the first wave of certified equipment.
Corporate renewable energy buyers are consolidating procurement through virtual power purchase agreements rather than on-site installations. This channel shift concentrates offtake negotiation leverage with large technology and data center operators. The trend is most visible in Texas ERCOT and MISO markets where merchant solar and storage stacks compete on wholesale capture rates.
Climate Tech Market Segmentation
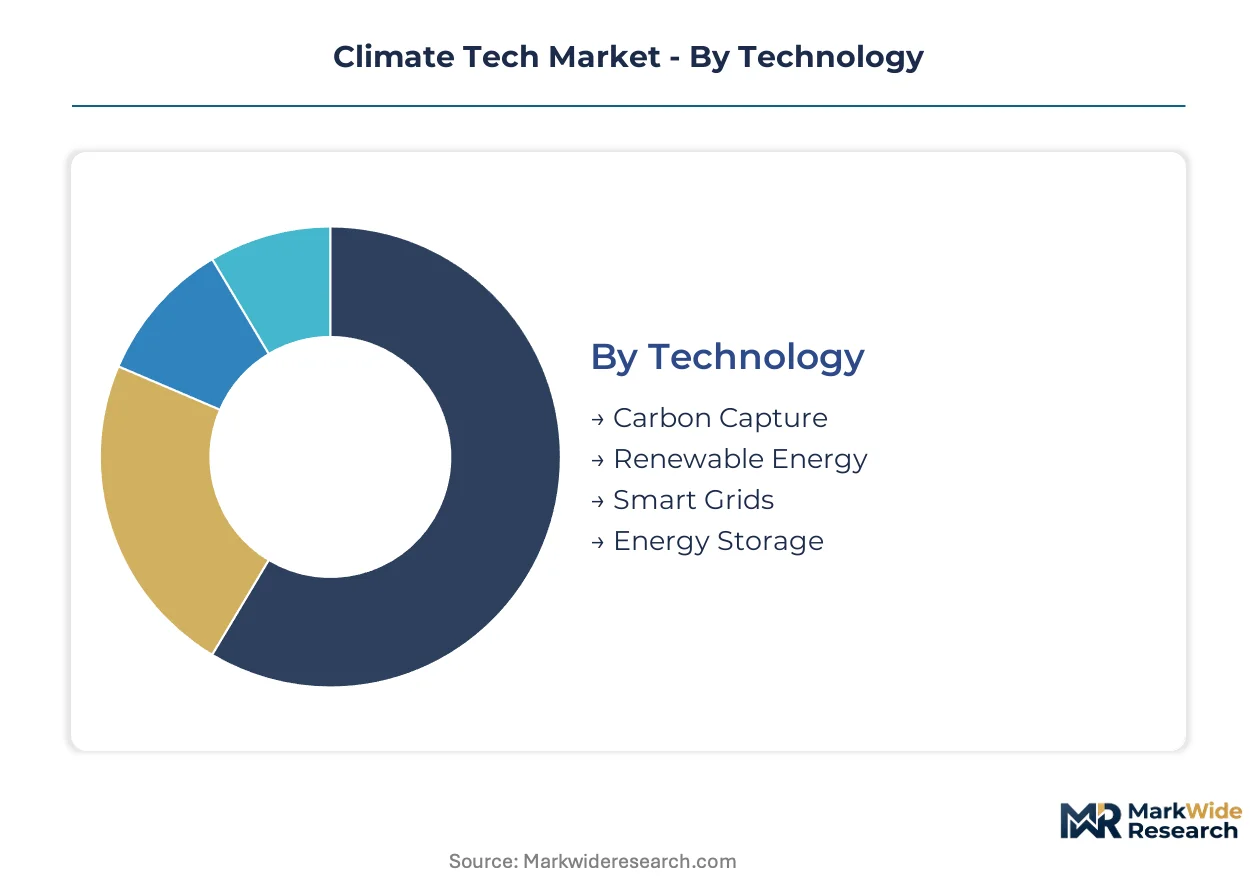
Climate tech vendors configure product portfolios around distinct technology cycles and procurement authority structures. Segment boundaries determine pricing architecture, sales cycle duration, and partnership requirements across hardware and software offerings.
Technology:
Renewable Energy assets turn over on 25-year power purchase agreements while Energy Storage contracts cycle every 5-7 years as battery chemistries improve.
- Carbon Capture:Point-source and direct air capture systems employ solid sorbent or liquid amine contactors to achieve CO2 separation thresholds. Industrial facility retrofits in Germany and the Netherlands concentrate demand as EU ETS pricing strengthens project economics.
- Renewable Energy:Photovoltaic and wind generation systems dominate installed capacity metrics across utility-scale and distributed configurations. China's MIIT-directed manufacturing expansion compresses module pricing, pulling procurement decisions toward solar-dominated portfolios.
- Smart Grids:Software-defined control layers overlay legacy transmission hardware.
- Energy Storage:Lithium-ion and emerging iron-air chemistries target multi-hour grid applications.
Renewable Energy dominates installed base. Energy Storage is where expansion concentrates.
Application:
Municipal procurement concentrates in Water Treatment while corporate sustainability budgets flow toward Energy Efficiency retrofits.
- Energy Efficiency:Building automation, industrial process optimization, and HVAC upgrades reduce operational emissions intensity. Data center operators in Virginia and Texas anchor demand as power density requirements clash with renewable procurement timelines.
- Waste Management:Anaerobic digestion, plasma gasification, and materials recovery facilities process organic and construction waste streams. European landfill diversion mandates concentrate project development in France and Italy.
- Water Treatment:Desalination and wastewater energy recovery systems address scarcity constraints.
- Sustainable Agriculture:Precision irrigation, soil carbon monitoring, and alternative protein production reduce agricultural emissions.
Water Treatment commands longest asset lifecycles. Energy Efficiency is climbing the fastest as corporate net-zero deadlines approach.
End User:
Government procurement runs on 18-36 month appropriation cycles while Residential Users convert on 30-day retail decisions.
- Government:Federal, state, and municipal agencies deploy climate tech through public works programs and procurement mandates. The Inflation Reduction Act's production tax credits anchor utility-scale project development across Texas, California, and Arizona.
- Corporations:Industrial and technology sector buyers contract virtual power purchase agreements and carbon removal offtake. Scope 3 disclosure requirements under the EU CSRD pull engineered carbon dioxide removal into long-term contracting.
- NGOs:Philanthropic and development finance institutions anchor early-stage technology demonstration.
- Residential Users:Rooftop solar, heat pump, and battery storage adoption follows net metering policy.
Corporations concentrate revenue per account. Residential Users represent volume scaling potential.
Service Type:
Software Solutions command recurring revenue multiples while Installation services absorb commodity labor pricing pressure.
- Consulting:Carbon accounting, net-zero pathway design, and regulatory compliance advisory services structure enterprise climate strategy. EU AI Act disclosure requirements pull algorithmic accountability expertise into CSRD-mandated reporting.
- Software Solutions:Grid dispatch optimization, emissions monitoring platforms, and predictive maintenance systems compress operational decision cycles. ERCOT and MISO market participants anchor demand for wholesale price forecasting tools.
- Installation:EPC contractors execute utility-scale renewable and storage deployments.
- Maintenance:Asset performance guarantees and predictive service contracts extend equipment lifecycles.
Installation captures upfront capital deployment. Software Solutions is gaining share fastest through recurring revenue conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA power sector emissions standards and the Inflation Reduction Act's production tax credits anchor United States demand for carbon capture retrofits and clean hydrogen facilities. China's MIIT-directed manufacturing expansion compresses electrolyzer and photovoltaic component costs. Germany's EU Green Deal implementation accelerates grid-scale battery procurement.
United States
Data center operators in Virginia and Texas anchor demand for renewable procurement and energy efficiency retrofits as power density requirements clash with net-zero timelines. FERC Order 2023 implementation lags leave renewable projects stranded in multi-year interconnection queues. The Inflation Reduction Act's manufacturing incentives concentrate solar, hydrogen, and carbon removal investments across Arizona and California.
China
MIIT-directed capacity expansion in electrolyzer and photovoltaic component output pulls procurement decisions toward solar-dominated portfolios. GB standards dictate product certification thresholds for domestic and export-bound clean technology equipment. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta scale iron-air battery chemistries for multi-hour grid applications.
Germany
Utilities expand procurement of grid-scale battery systems under EU Green Deal decarbonization mandates. The EU F-Gas Regulation phase-down forces refrigerant transitions in heat pump equipment redesigns. Industrial facility retrofits in the Ruhr Valley and Bavaria concentrate carbon capture demand as EU ETS pricing strengthens project economics.
India
Production-linked incentives for solar module and advanced chemistry cell manufacturing attract supply chain relocation from China. The country's national renewable energy regulator accelerates transmission access for utility-scale solar parks. Manufacturing investments cluster in Gujarat and Tamil Nadu as corporate renewable energy buyers consolidate procurement through virtual power purchase agreements.
Japan
Automotive OEMs qualify sulfide and oxide electrolyte solid-state battery cells for platform integration timelines. METI directs cold climate heat pump deployments absorbing certified propane and CO2 working fluid equipment. Industrial concentration in the Kansai region anchors plasma physics specialization for fusion reactor magnet engineering.
Climate Tech Market Vendor Landscape
Technology licensors and integrated project developers split the market between intellectual property monetization and full-stack deployment ownership. The vendor base organizes around three strategic archetypes: fusion energy hardware specialists, closed-loop materials recovery operators, and grid-scale storage integrators. Competitive moves concentrate on strategic partnerships for offtake contracting and backward integration into critical mineral supply.
Among fusion energy hardware specialists, Helion Energy and Commonwealth Fusion Systems exemplify magnet technology intensity differentiation from conventional reactor architectures. Within the closed-loop materials recovery tier, Redwood Materials occupies a position sustaining cathode supply networks for domestic cell producers. These three companies represent divergent bets on baseload power, materials circularity, and reactor engineering scalability.
| Leading Market Players |
|---|
| Helion Energy |
| Dandelion Energy |
| Fervo Energy |
| Pachama |
| 247Solar |
| Commonwealth Fusion Systems |
| Factorial |
| Green Project |
| Redwood Materials |
| Others |
Supply Flow & Price Mechanics
Lithium supply concentration in Chile, Australia, and China exposes cell manufacturers to geopolitical interruptions that compress pricing tiers for battery storage systems while forcing procurement diversification across alternative chemistries. This single-source dependency widens spreads between premium UL-certified domestic packs and economy-grade imports while reshaping inventory strategies toward regional buffer stock.
Pricing Analysis
Geographic price spreads between EU Green Deal-compliant battery systems and non-certified alternatives exceed factor ranges as GB standards and CE marking timelines fragment certification costs. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed-performance utility contracts from merchant solar-plus-storage stacks. Cost compression in lithium-ion modules is intensifying because China's MIIT-directed manufacturing expansion floods spot markets. Corporate renewable energy buyers show least price sensitivity due to net-zero deadline rigidity, while municipal utilities face procurement freezes when federal appropriations lapse.
Supply Chain Analysis
Export-control regimes limiting high-temperature superconductor and rare-earth magnet flows constrain fusion reactor component sourcing from Japan and South Korea. Spodumene concentrates in Western Australia, brine processing clusters in Chile's Atacama, and cathode active material production is anchored in China's Yangtze River Delta. Single-source vulnerability runs through graphite anode supply as synthetic alternatives face energy-intensity penalties. Distribution runs through EPC contractor networks that bundle installation with long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among data center operators and hyperscalers consolidating virtual power purchase agreement volumes, fragmenting negotiation leverage for smaller offtakers.
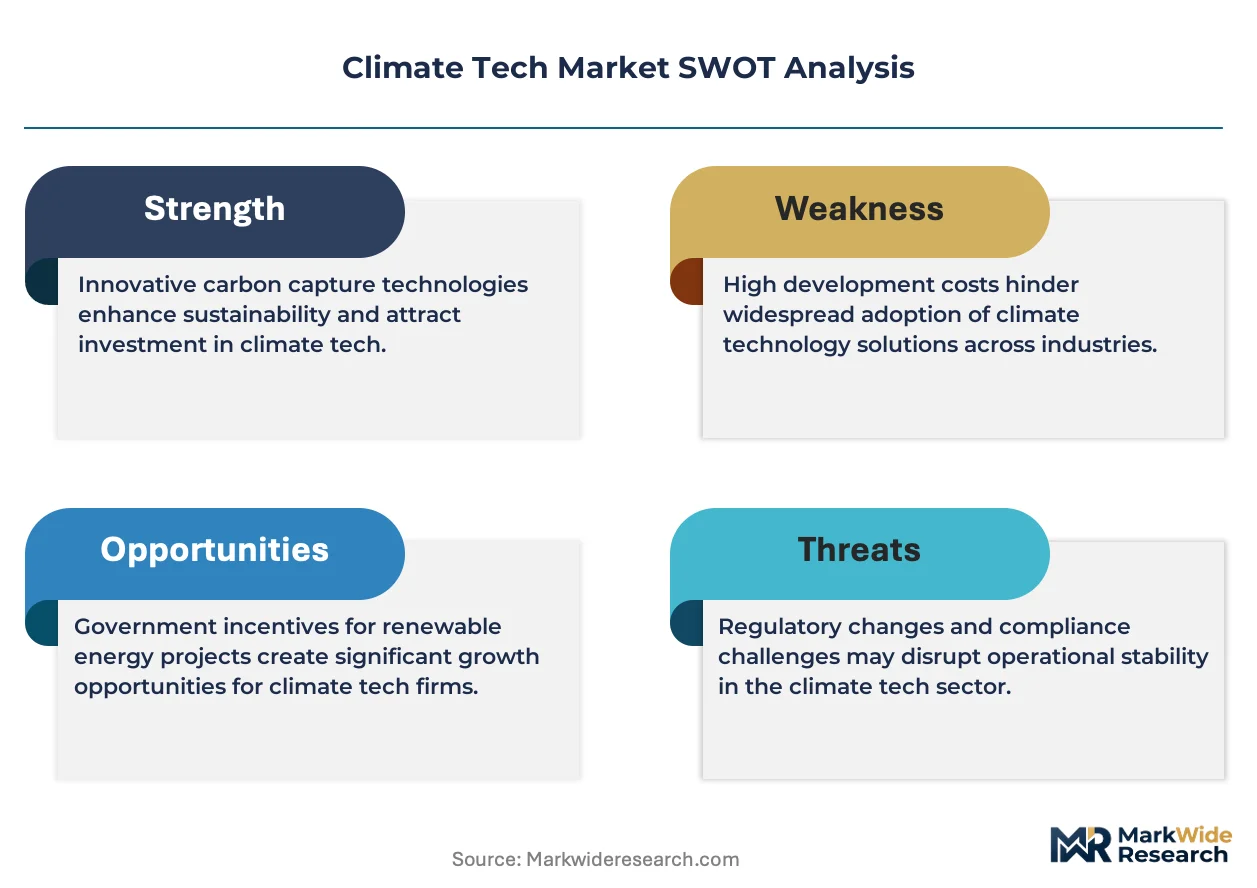
For Market Incumbents: Harden cathode supply networks through backward integration into lithium hydroxide conversion capacity in North America. Secure FERC Order 2023-compliant interconnection positions before queue reform accelerates. Magnet engineering scarcity threatens fusion reactor timelines; captive plasma physics recruitment programs defend development velocity against Commonwealth Fusion Systems and Helion Energy. For New Entrants and Emerging Players: Build out iron-air long-duration storage demonstration capacity targeting Midwest ISO markets where multi-day discharge economics outcompete lithium-ion. India's PLI scheme for advanced chemistry cells offers the most penetrable manufacturing relocation pathway from China. Go-to-market positioning should anchor on virtual power purchase agreement aggregation platforms serving mid-market corporate buyers excluded from direct utility negotiations. For Investors and Strategic Acquirers: The market sits at a manufacturing-capacity-expansion phase that favors materials recovery operators with closed-loop feedstock agreements. Long-term viability across the projection horizon rests on cathode supply security rather than cell assembly scale. Acquisition target archetype: electrolyzer stack specialists with MIIT export certification and European offtake pipelines. Signal to watch is EU ETS price corridor stability sustaining carbon capture retrofit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Scale-Up | MIIT-directed capacity expansion in China compresses clean hydrogen production costs for EU importers. |
| Grid-Scale Battery Procurement | German utilities under EU Green Deal mandates force synchronous generation retirements faster than stability services reconfigure. |
| Closed-Loop Materials Recovery | Redwood Materials' cathode supply networks sustain domestic cell producers against lithium concentration risk. |
| Fusion Reactor Magnet Development | Commonwealth Fusion Systems competes on high-temperature superconductor intensity to differentiate tokamak architectures. |
| Carbon Removal Offtake Contracting | Corporate net-zero commitments pull engineered CO2 removal into project finance at prices sustaining direct air capture. |
Methodological Framework
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration against operating reality. Primary interview data combined with secondary validation from EIA electricity statistics, IEA technology roadmaps, FERC interconnection queue filings, and EU ETS price registries. Bottom-up project pipeline aggregation and top-down policy impact modeling triangulated volume and value estimates.
Scenario-bracketing around IRA production tax credit permanence and EU Green Deal implementation velocity bounded CAGR derivation across the analysis window. Segmentation dimensions modeled include technology cycle maturity, procurement authority structure, and regional regulatory framework. Forecast inputs incorporated electrolyzer cost curves, lithium carbonate spot price volatility, and interconnection queue clearance rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese manufacturers or fusion energy demonstrators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Global Environmental Sensor Market
Environment & Sustainability
Household Composters Market
Environment & Sustainability
Asia-Pacific Industrial Waste Management Market
Environment & Sustainability
Solar Waste Recycling Market
Environment & Sustainability
Commercial Atmospheric Water Generator Market
Environment & Sustainability
Sludge Management Equipment Market
Environment & Sustainability
E-Scrap Recycling Market
Environment & Sustainability
Environmental Technology Market
Environment & Sustainability
Chile Water Consumption Market
Environment & Sustainability
Paper Recycling Market
Environment & Sustainability
Saudi Arabia Waste Management Market
Environment & Sustainability
Global RO Water Purifier Market
Environment & Sustainability
Solid Waste Management Market
Environment & Sustainability
Wastewater Recovery Systems Market
Environment & Sustainability
Environmental Software Market
Environment & Sustainability
Smart Water Network Market