
 Environmental Radiation Monitor Market | 2026-2036
Environmental Radiation Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Radiation Monitor Market Insights
Semiconductor sensor integration with IoT telemetry is rewriting how environmental radiation data is collected, transmitted, and acted upon in distributed monitoring networks. Thermo Fisher Scientific leverages its vertical integration across scintillation crystal production and detector assembly to sustain cost advantages in high-precision installations. Mirion Technologies anchors its position through deep specialization in nuclear facility safety systems, while HORIBA competes by extending its optical sensing expertise into semiconductor-based radiation detection platforms.
Environmental radiation monitors are instruments that detect, quantify, and record ionizing radiation levels in ambient air, water, soil, and biological samples, typically achieving detection thresholds from picocuries to millirems per hour depending on sensor architecture and shielding design. These systems serve critical functions in regulatory compliance, public health protection, and operational safety at facilities handling radioactive materials. Fixed monitors dominate capital deployment in nuclear power plant perimeter networks where continuous automated surveillance is mandatory, while portable detectors represent the fastest-expanding category as emergency management organizations prioritize rapid-deploy kits for radiological incident response. Semiconductor sensors command premium positioning due to superior energy resolution and miniaturization potential, though Geiger-Muller counters retain volume leadership in cost-sensitive environmental test lab applications.
The U.S. Nuclear Regulatory Commission enforces 10 CFR Part 20 standards that mandate continuous area monitoring in restricted zones, while the European Union's Basic Safety Standards Directive and EURATOM treaty obligations shape cross-border environmental surveillance protocols. China's Ministry of Ecology and Environment implements GB standards for nuclear facility discharge monitoring that increasingly align with IAEA safety series recommendations. Stakeholders must weigh semiconductor sensor migration timelines against legacy Geiger-Muller installed bases when allocating R&D budgets and field service infrastructure.
Market Dynamics
Semiconductor sensor architectures are collapsing the cost floor for distributed radiation detection networks, forcing legacy Geiger-Muller supply chains to defend installed bases through service bundling rather than hardware margins.
Growth Catalysts
- IAEA Safety Standards:The International Atomic Energy Agency's updated safety series recommendations are mandating redundant monitoring layers at civilian nuclear facilities, expanding procurement volumes for dual-sensor configurations.
- China's reactor construction pipeline:The national nuclear regulator's enforcement of GB standards for environmental release monitoring at new reactor sites is generating concentrated demand for fixed perimeter installations.
- Emergency response modernization:National civil defense agencies across multiple jurisdictions are standardizing rapid-deploy portable kits, accelerating replacement cycles for aging field detection equipment.
Market Restraints
- Scintillation crystal supply concentration:High-purity sodium iodide and cesium iodide production clusters in limited geographic zones, exposing detector manufacturers to raw material availability shocks.
- Calibration infrastructure scarcity:Certified reference source facilities capable of traceable gamma and neutron calibration remain sparse outside major nuclear science centers, lengthening commissioning timelines.
- Geiger-Muller tube legacy lock-in:Decades of deployed tube-based networks in environmental test labs create switching friction against semiconductor migration due to familiarity bias and spare parts inventories.
Strategic Opportunities
- Sub-Saharan Africa mining corridors:Uranium and rare earth extraction projects in Namibia and Niger lack established environmental baseline monitoring, creating first-mover positioning for turnkey monitoring networks.
- IoT telemetry convergence:Integration of LoRaWAN and satellite backhaul with solid-state sensors enables real-time data streaming to centralized regulatory dashboards, opening subscription revenue models.
- EU CSRD alignment:The Corporate Sustainability Reporting Directive's environmental disclosure requirements are pressuring industrial radiography users to document ambient radiation baselines for ESG filings.
Industry Challenges
- Radiation metrology expertise gap:Qualified personnel capable of spectral analysis, shielding design, and regulatory interpretation are concentrating at national laboratories and major operators, constraining field service scaling.
- Multi-jurisdiction certification complexity:Achieving simultaneous NRC recognition, EURATOM compliance, and Chinese MEE approval for a single detector platform demands parallel testing tracks that extend product launch timelines.
- Legacy analog integration friction:Semiconductor sensor outputs require digital signal processing architectures incompatible with existing chart recorder and SCADA interfaces at aging nuclear facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Radiation Monitor Market |
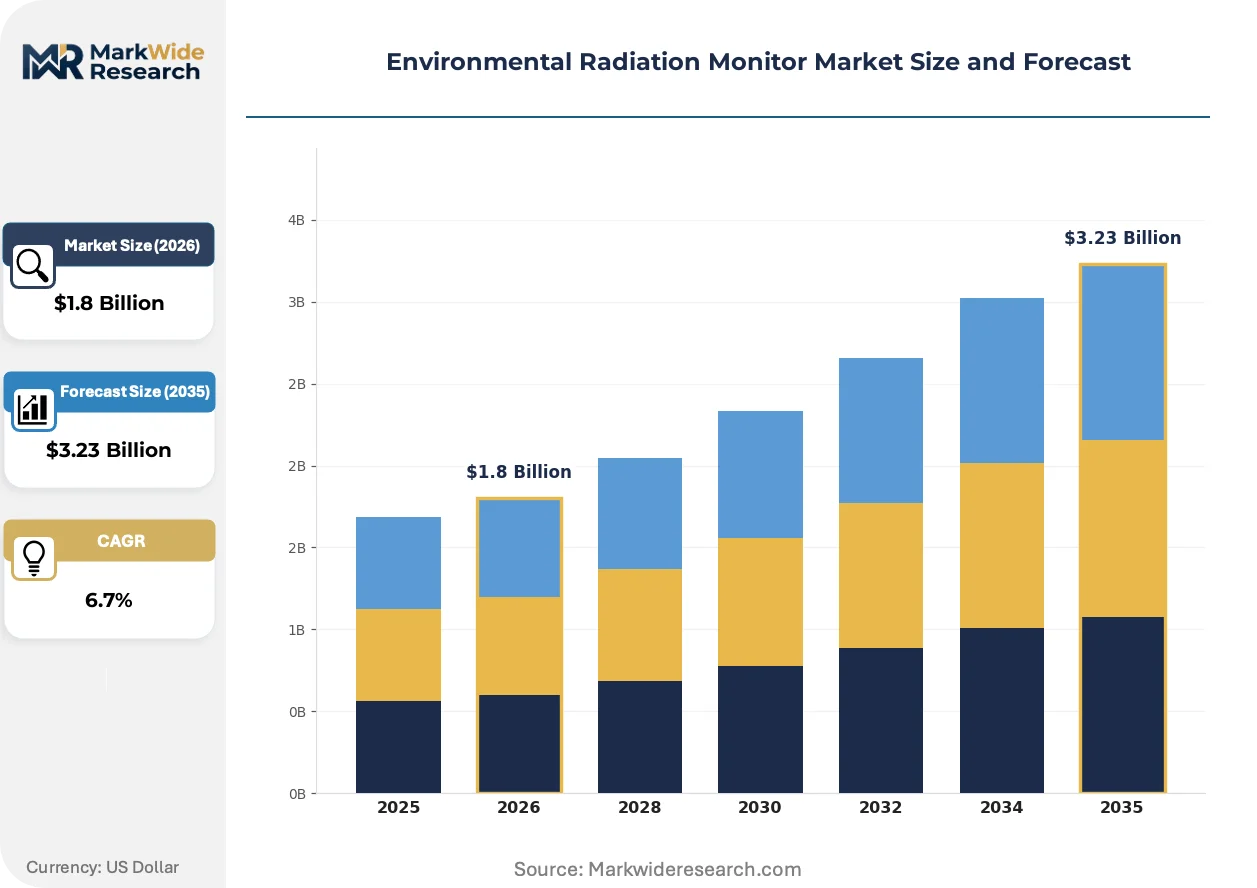
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Monitors, Portable Detectors, Airborne Rad Monitors, Waterborne Rad Monitors, Soil Rad Sensors Technology: Geiger-Muller Counters, Scintillation Detectors, Semiconductor Sensors, Ionization Chambers, Proportional Counters Application: Nuclear Facility Safety, Environmental Surveillance, Emergency Response, Industrial Hygiene, Research Laboratory Monitoring End User: Nuclear Power Plants, Research Institutes, Government Agencies, Environmental Test Labs, Emergency Management Organizations |
| Companies Covered | Thermo Fisher Scientific, HORIBA, Mirion Technologies, Bertin Instruments, Comecer, NUVIATech Instruments, ALOKA, Senstate, Shanghai Renji Instrument, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Radiation Monitor Market Trends and Innovations
Three intersecting developments are restructuring how radiation detection hardware is specified, procured, and operated across civilian nuclear, industrial, and environmental monitoring contexts.
Silicon photomultiplier arrays paired with cerium-doped lanthanum bromide crystals are collapsing the performance gap between portable field units and laboratory-grade spectrometers. Nuclear power plant health physics departments are piloting these configurations for perimeter monitoring, displacing traditional photomultiplier tube architectures that require high voltage supplies and temperature stabilization. The structural consequence is collapsing price-performance boundaries between fixed and mobile detection categories, enabling spectral-capable deployments in locations previously restricted to simple gross-gamma alarming.
REACH restrictions on lead and cadmium in electronic components are forcing detector manufacturers to redesign shielding assemblies and internal soldering processes. The European Chemicals Agency's substance restrictions are compressing available material options for radiation-hardened enclosures, pushing engineering teams toward tungsten-composite and bismuth-alloy alternatives. German and French nuclear operators are responding by tightening supplier qualification protocols to verify full material disclosure across subcomponent tiers.
Utility procurement departments are unbundling hardware acquisition from multi-year calibration and data management contracts that previously shipped as integrated packages. This disaggregation is fragmenting vendor relationships, with specialized service firms capturing recurring revenue streams that equipment manufacturers once retained. The shift is most visible in North American nuclear generation fleets, where independent environmental data management platforms are winning regulatory reporting contracts previously held by detector OEMs.
Environmental Radiation Monitor Market Segmentation
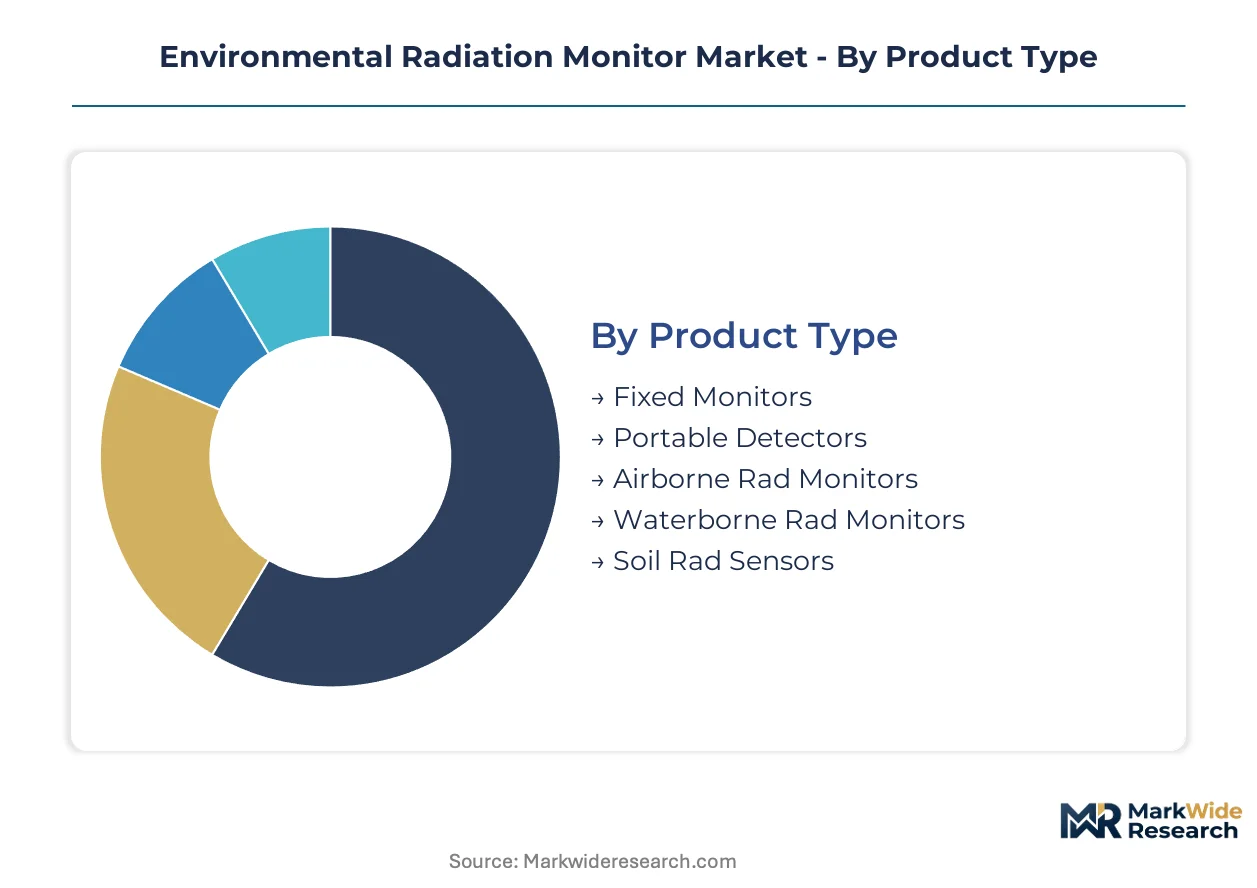
Environmental radiation monitor segmentation reflects divergent technical requirements across continuous perimeter surveillance, rapid-deploy field operations, and precision laboratory measurement. Procurement patterns differ sharply between capital-intensive fixed installations with decade-long service lifecycles and portable equipment subject to shorter replacement cycles driven by sensor technology advances.
Product Type:
Fixed monitors anchor reactor perimeter networks where regulatory mandates demand uninterrupted data streams, while portable configurations serve mobile emergency response teams requiring rapid deployment capabilities.
- Fixed Monitors:These systems integrate multi-sensor arrays with automated data telemetry for continuous perimeter surveillance at nuclear facilities. China's Ministry of Ecology and Environment is enforcing GB standards that mandate redundant fixed installations at new reactor sites, concentrating procurement among domestic and international suppliers capable of dual-sensor configurations.
- Portable Detectors:Battery-powered units with semiconductor or scintillation sensors enable rapid field assessment during radiological incidents. National civil defense agencies across multiple jurisdictions are standardizing rapid-deploy kits, accelerating replacement cycles for aging field detection equipment and expanding volumes for lightweight spectral-capable designs.
- Airborne Rad Monitors:Stack and vent sampling systems measure particulate and noble gas releases from nuclear facility exhaust streams.
- Waterborne Rad Monitors:Continuous flow-through detectors track liquid effluent discharge concentrations at reactor cooling water outfalls.
- Soil Rad Sensors:Buried probe networks monitor groundwater migration and subsurface contamination plumes at waste storage facilities.
The dominant share belongs to Fixed Monitors, while Portable Detectors are gaining share fastest as emergency response modernization accelerates replacement investments.
Technology:
Sensor architecture selection trades energy resolution, size constraints, and cost floors against specific detection requirements for gamma, neutron, or mixed radiation fields.
- Geiger-Muller Counters:Gas-filled tubes operating in avalanche mode provide robust gross-count detection with minimal electronic complexity. Environmental test labs retain substantial installed bases of tube-based instruments due to familiarity bias and extensive spare parts inventories, though semiconductor alternatives are eroding this position.
- Scintillation Detectors:Crystals such as sodium iodide or cesium iodide convert gamma photon energy to light pulses with moderate spectral resolution. High-purity crystal production concentrates in limited geographic zones, exposing detector manufacturers to raw material availability shocks and supply chain vulnerabilities.
- Semiconductor Sensors:Silicon and cadmium-zinc-telluride devices achieve superior energy resolution in compact packages suitable for distributed networks.
- Ionization Chambers:Gas-filled cavities with applied electric fields measure absorbed dose rate in high-radiation environments.
- Proportional Counters:Operated below Geiger threshold, these discriminate particle types through pulse height analysis for neutron detection applications.
Geiger-Muller Counters retain volume leadership in cost-sensitive applications, though Semiconductor Sensors are climbing the fastest as IoT telemetry integration drives distributed network deployment.
Application:
Regulatory frameworks and operational risk profiles shape specification requirements across civilian nuclear, public health, and industrial hygiene contexts.
- Nuclear Facility Safety:Perimeter and stack monitoring systems enforce license conditions for radioactive material handling operations. The U.S. Nuclear Regulatory Commission's 10 CFR Part 20 standards mandate continuous area monitoring in restricted zones, sustaining procurement for redundant sensor configurations.
- Environmental Surveillance:Ambient air, water, and soil monitoring networks establish baseline radiation levels and detect anomalous releases. The European Union's Basic Safety Standards Directive and EURATOM treaty obligations shape cross-border environmental surveillance protocols, harmonizing data formats and alarm thresholds.
- Emergency Response:Rapid-deploy kits enable field assessment during transportation accidents or radiological dispersal events.
- Industrial Hygiene:Personnel and area monitors protect workers in radiography, nuclear medicine, and materials processing operations.
- Research Laboratory Monitoring:High-resolution spectrometers support isotopic identification and quantitative analysis for scientific applications.
Nuclear Facility Safety commands the largest procurement volumes, while Emergency Response is expanding most quickly as civil defense agencies modernize field capabilities.
End User:
Customer technical sophistication and procurement authority vary from centralized utility engineering departments to distributed emergency management jurisdictions.
- Nuclear Power Plants:Utility health physics departments specify integrated monitoring networks with centralized data management platforms. Procurement departments are unbundling hardware acquisition from multi-year calibration contracts, fragmenting vendor relationships and opening service revenue to specialized firms.
- Research Institutes:National laboratories and university facilities demand high-resolution spectrometers for isotopic analysis and method development. Qualified personnel capable of spectral analysis and shielding design are concentrating at these institutions, constraining field service scaling for commercial deployments.
- Government Agencies:Environmental regulators and public health authorities operate surveillance networks and set compliance standards.
- Environmental Test Labs:Commercial analytical laboratories perform contract monitoring for industrial clients and regulatory compliance verification.
- Emergency Management Organizations:Civil defense and fire services maintain rapid-deploy capabilities for radiological incident response.
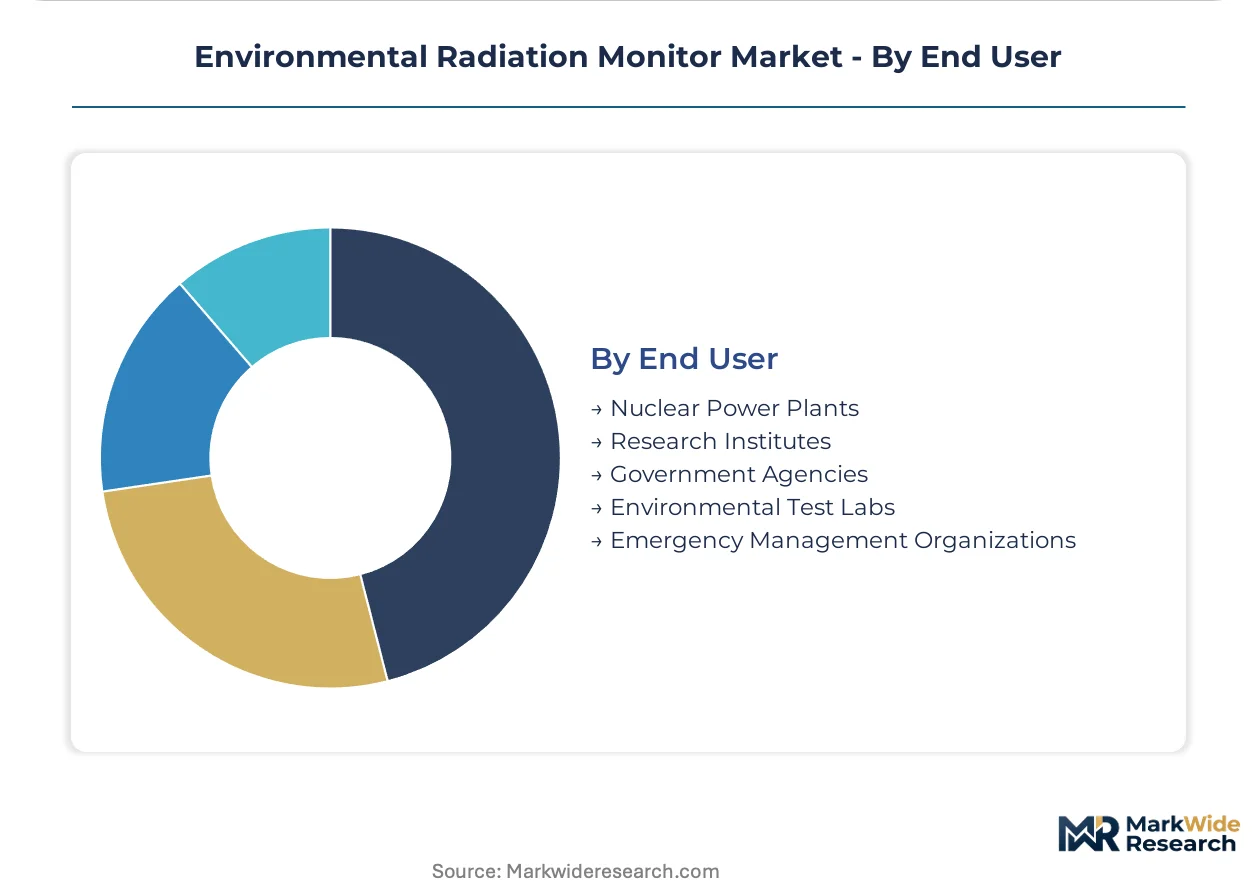
Nuclear Power Plants dominate capital deployment, though Emergency Management Organizations are driving the steepest volume expansion as rapid-deploy kit standardization accelerates replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German detector manufacturers export precision scintillation assemblies to reactor operators across Eastern Europe and the Middle East, while Chinese component suppliers feed semiconductor sensor substrates into assembly plants in South Korea and Japan.
United States
Utility procurement departments at Exelon and Duke Energy are unbundling hardware from service contracts, fragmenting vendor relationships. The NRC enforces 10 CFR Part 20 standards mandating continuous area monitoring in restricted zones. Oak Ridge National Laboratory and Idaho National Laboratory anchor spectral analysis capability development in the Tennessee-Idaho corridor.
China
State Power Investment Corporation and China General Nuclear Power Group are expanding fixed monitor deployments across 24 new reactor sites. The Ministry of Ecology and Environment implements GB standards for environmental release monitoring that align with IAEA safety series recommendations. The Yangtze River Delta cluster around Shanghai hosts domestic detector assembly operations scaling to meet indigenous content requirements.
Germany
Decommissioning projects at Gundremmingen and Brokdorf are sustaining replacement demand for perimeter monitoring systems despite the nuclear phase-out. The European Chemicals Agency's REACH restrictions on lead and cadmium are forcing shielding redesigns toward tungsten-composite alternatives. The Karlsruhe technology region concentrates high-purity scintillation crystal production and calibration reference source facilities.
Japan
Tokyo Electric Power Company and Kansai Electric Power Company are upgrading Fukushima perimeter networks and western plant installations with redundant sensor configurations. METI oversees national standards for environmental radiation monitoring that incorporate post-2011 enhanced surveillance protocols. The Chubu region around Nagoya maintains specialized manufacturing for photomultiplier tube alternatives and silicon photomultiplier arrays.
France
Électricité de France is standardizing monitor specifications across its 56-reactor fleet to reduce spare parts complexity. ANSM and IRSN coordinate environmental surveillance protocols under EURATOM treaty obligations and EU Basic Safety Standards Directive requirements. The Provence-Alpes-Côte d'Azur region around Cadarache hosts ITER and research reactor monitoring technology validation programs.
Environmental Radiation Monitor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation pressures are mounting as procurement departments unbundle hardware from multi-year service contracts, fragmenting traditional vendor relationships. The competitive terrain separates vertically integrated instrument conglomerates, specialized nuclear safety system providers, and component-focused sensor technology developers. Dominant competitive moves include backward integration into scintillation crystal production and strategic partnerships for IoT telemetry platform integration.
Among vertically integrated instrument conglomerates, Thermo Fisher Scientific exemplifies the archetype combining captive scintillation crystal production with detector assembly operations. HORIBA occupies a position representing optical sensing specialists extending expertise into semiconductor-based radiation detection platforms. Mirion Technologies anchors the specialized nuclear safety system tier through deep domain focus on facility-specific monitoring configurations. These three players represent divergent strategic postures: upstream supply control, cross-technology migration, and end-use specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| HORIBA |
| Mirion Technologies |
| Bertin Instruments |
| Comecer |
| NUVIATech Instruments |
| ALOKA |
| Senstate |
| Shanghai Renji Instrument |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on high-purity sodium iodide and cesium iodide crystal production determines both the premium-to-economy pricing spreads in detector assemblies and the geographic clustering of scintillation supply chains. Buyers face procurement premiums when sourcing from non-dominant production zones, while manufacturers absorb margin compression during raw material availability shocks.
Pricing Analysis
The semiconductor-to-Geiger-Muller pricing gap spans roughly an order of magnitude, with silicon photomultiplier arrays and cadmium-zinc-telluride sensors commanding project-based premiums for spectral-capable deployments while gas-filled tubes retain per-unit transactional dominance in cost-sensitive environmental test labs. Three-tier pricing structure across premium, standard, and economy levels separates IAEA-certified redundant installations from single-sensor perimeter units and basic gross-gamma alarming devices. Pricing pressure stems from utility procurement departments unbundling hardware from calibration contracts, forcing detector OEMs to compete on equipment margins alone. Emergency management organizations exhibit highest price sensitivity due to budget-constrained rapid-deploy kit standardization, while nuclear power plant health physics departments prioritize certification grade over unit cost.
Supply Chain Analysis
Tariff exposure between China and Western detector assembly markets dominates supply chain risk planning for semiconductor sensor substrates and finished monitor exports. High-purity scintillation crystal production concentrates in Germany, Japan, and the United States, while semiconductor sensor substrate fabrication clusters in China, South Korea, and Taiwan. Raw material dependencies include cerium-doped lanthanum bromide crystals, silicon photomultiplier dies, and tungsten-composite shielding alloys replacing lead under REACH restrictions. Distribution runs through nuclear engineering procurement departments, specialized radiation safety distributors, and direct OEM relationships with utility fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The environmental radiation monitor market rewards organizations that control scarce radiation metrology expertise and certified calibration infrastructure. Qualified personnel capable of spectral analysis, shielding design, and multi-jurisdiction regulatory interpretation are concentrating at national laboratories and major operators, constraining scaling for commercial service expansion.
For Market Incumbents: Harden installed base defenses through captive scintillation crystal supply and multi-year data management contract retention as utility procurement departments fragment traditional vendor relationships. Deepen backward integration into sodium iodide and cesium iodide production to offset raw material availability shocks from geographic supply concentration. Prioritize certification investment for simultaneous NRC, EURATOM, and Chinese MEE approval to compress product launch timelines against emerging competitors. For New Entrants and Emerging Players: Establish a beachhead in Sub-Saharan African uranium and rare earth mining corridors where environmental baseline monitoring infrastructure remains underdeveloped. Target rapid-deploy portable detector segments for emergency response modernization programs, as civil defense agencies accelerate replacement cycles for aging field equipment. Pursue IoT telemetry platform partnerships to capture recurring subscription revenue streams that incumbent OEMs are losing through procurement unbundling. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component-specialist acquisition targets with semiconductor sensor architectures and LoRaWAN integration capabilities. Long-term viability hinges on positioning for distributed network deployment as fixed installations mature and portable spectral-capable units expand. Monitor IAEA safety series revision cycles as the primary inflection signal for procurement volume acceleration in dual-sensor redundant configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scintillation Crystal Production | Thermo Fisher Scientific's captive sodium iodide supply secures margin protection against German and Japanese crystal shortages. |
| IoT Telemetry Platform Partnership | LoRaWAN and satellite backhaul integration enables real-time data streaming to Chinese Ministry of Ecology and Environment dashboards. |
| Multi-Jurisdiction Certification Investment | Simultaneous NRC 10 CFR Part 20, EURATOM, and GB standards approval compresses product launch timelines for reactor perimeter deployments. |
| Sub-Saharan Africa Market Entry | Turnkey monitoring network first-mover positioning in Namibian and Nigerien uranium extraction corridors captures environmental baseline establishment demand. |
| Service Contract Retention Strategy | Independent environmental data management platforms are winning regulatory reporting contracts from detector OEMs in North American nuclear fleets. |
Research Methodology
The analysis maps fixed monitor, portable detector, airborne, waterborne, and soil sensor sub-sectors, each validated through health physics directors, utility procurement officers, emergency management coordinators, and environmental test lab managers. Primary interviews with nuclear facility safety officers, radiation metrology specialists, and regulatory compliance consultants combined with secondary validation against IAEA safety series documentation, NRC reactor oversight process filings, and Chinese GB standards enforcement records. Bottom-up unit deployment estimates triangulated with top-down procurement budget analysis across civilian nuclear, environmental surveillance, and emergency response application segments.
Assumption sets held regulatory enforcement timelines and reactor construction pipelines fixed while varying semiconductor sensor cost decline curves and IoT telemetry adoption rates across the projection horizon. The analytical framework modeled product type, technology architecture, application context, and end-user sophistication dimensions throughout the forecast period. CAGRs derived from installed base replacement cycles, new reactor site monitoring mandates, and rapid-deploy kit standardization trends. Industry-specific inputs included scintillation crystal supply availability, certified reference source facility capacity, and multi-jurisdiction certification timeline data.
Sensitivities concentrate around IAEA safety series revision timing, REACH restriction enforcement on lead and cadmium alternatives, and Chinese indigenous content requirements for reactor site equipment. Forecasts reflect documented assumptions regarding semiconductor sensor migration rates against legacy Geiger-Muller installed bases. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Weather Modification Equipment Market