
 Environment Monitoring Devices Market | 2026-2036
Environment Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Environment Monitoring Devices Market Foresight
Modular sensor bundling is hardening as the dominant procurement pattern for industrial buyers seeking scalable air and water monitoring networks. Danaher Corporation leverages its life sciences instrumentation portfolio to anchor integrated water quality platforms across municipal utilities. Thermo Fisher Scientific Inc. sustains technology leadership in mass spectrometry detection for trace contaminant analysis. Siemens AG competes through its industrial automation channel, embedding environment sensors directly into process control architectures for manufacturing clients.
Environment monitoring devices encompass electrochemical, optical, and semiconductor-based instruments engineered to detect particulate matter, dissolved oxygen, volatile organic compounds, and meteorological variables within specified detection limits. These systems transmit calibrated data through wireless protocols to centralized analytics platforms, enabling regulatory compliance and operational decision-making. Air quality monitors occupy the largest installed base among product types, though IoT-enabled wireless sensors represent the fastest-expanding technology category as edge computing reduces latency for critical alerts. Data analytics applications command premium pricing by transforming raw sensor outputs into predictive maintenance schedules and emission forecasting models.
The United States EPA enforces National Ambient Air Quality Standards that mandate continuous monitoring at major emission sources, directly stimulating equipment replacement cycles. The EU Green Deal and associated F-Gas Regulation impose progressively tighter limits on fluorinated greenhouse gases, requiring upgraded leak detection infrastructure across chemical processing and refrigeration sectors. China's MEE administers dual carbon goals that expand mandatory monitoring coverage to provincial industrial clusters. Stakeholders must weigh capital deployment toward sensor-as-a-service models against traditional hardware ownership as regulatory granularity intensifies across jurisdictions.
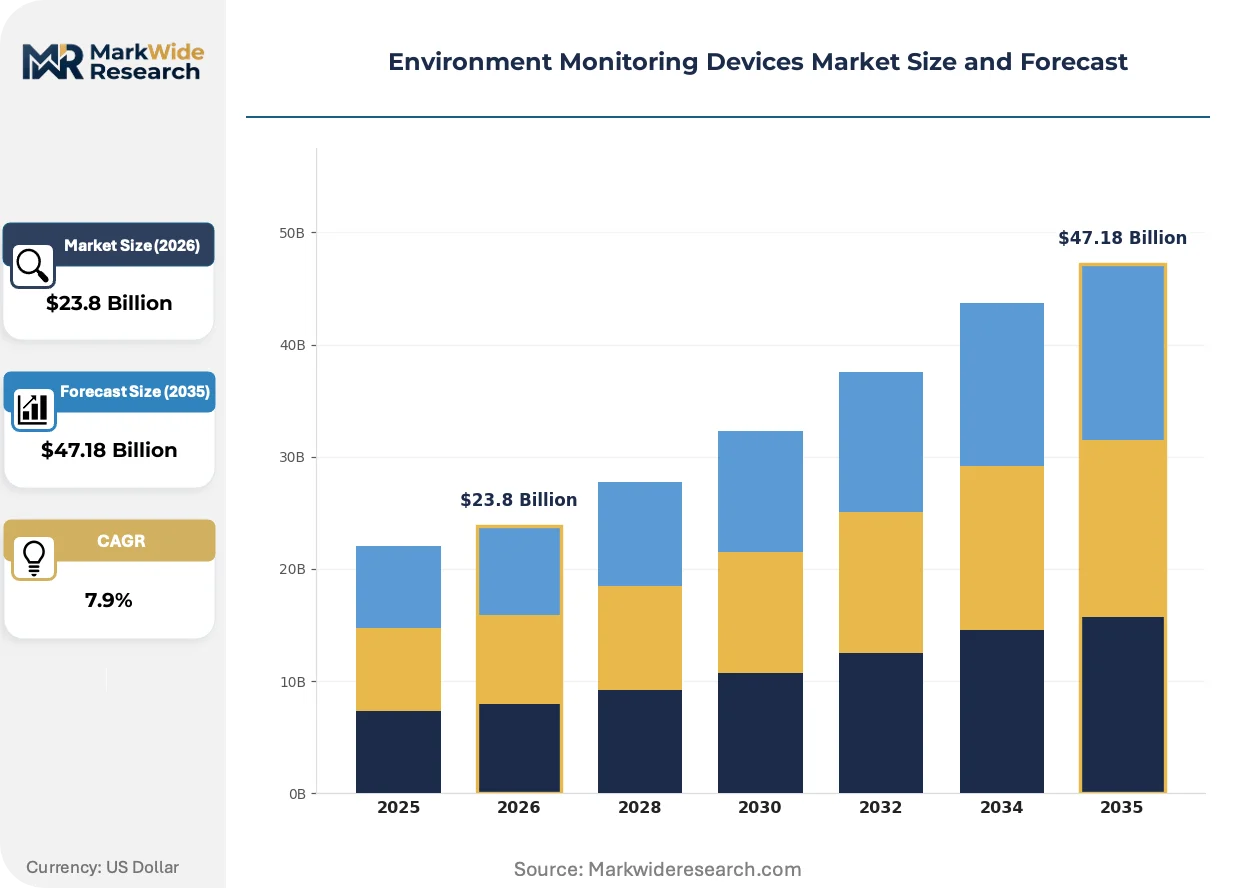
Market Dynamics
Wireless sensor networks are compressing deployment timelines for industrial emissions tracking while tightening ambient air quality mandates across the United States, Europe, and China force synchronized equipment upgrade cycles.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Continuous monitoring mandates at major emission sources trigger replacement demand for legacy analyzer systems across American manufacturing zones.
- Semiconductor fabrication expansion:Fab construction in Taiwan, South Korea, and the United States requires ultra-trace contamination detection for cleanroom environments and process gas purity.
- EU F-Gas Regulation phase-down:Leak detection infrastructure upgrades accelerate across European chemical processing and commercial refrigeration installations.
Market Restraints
- Optical sensor component concentration:Laser diode and photodetector supply chains cluster in East Asian foundries, exposing lead time volatility for Western instrument manufacturers.
- Calibration gas scarcity:Certified reference material shortages for trace-level VOC standards extend commissioning timelines for ambient air monitoring stations.
- Interference from low-cost electrochemical substitutes:Budget-grade sensors without temperature compensation degrade data quality in municipal procurement decisions.
Strategic Opportunities
- India's Central Pollution Control Board expansion:National Air Quality Monitoring Network densification creates first-mover positioning for continuous emissions monitoring system vendors.
- Edge-AI convergence with MEMS sensors:On-device inference for anomaly detection reduces cloud transmission costs and enables sub-second alert generation.
- Sensor-as-a-service channel development:Subscription pricing for water quality monitoring hardware penetrates small municipal utilities with constrained capital budgets.
Industry Challenges
- Cross-disciplinary talent scarcity:Field engineers must simultaneously command electrochemistry, RF protocols, and cloud architecture for distributed sensor network deployment.
- Multi-jurisdiction certification backlog:Separate EPA equivalency, EU MCERTS, and China MEE approvals extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environment Monitoring Devices Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $47.18 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Quality Monitors, Water Quality Analyzers, Soil Sensors, Weather Stations Technology: Wireless Sensors, IoT Solutions, Remote Sensing, Data Analytics End User: Government Agencies, Research Institutions, Industrial Facilities, Agriculture Application: Pollution Monitoring, Climate Research, Agricultural Monitoring, Urban Planning |
| Companies Covered | Danaher Corporation, Agilent Technologies Inc., Thermo Fisher Scientific Inc., Honeywell International Inc., Emerson Electric Co., Siemens AG, PerkinElmer Inc., Shimadzu Corporation, Teledyne Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environment Monitoring Devices Market Shifts & Advancements
Sensor miniaturization and embedded intelligence are collapsing the boundary between field instrumentation and consumer-grade devices, opening new deployment vectors beyond traditional regulatory compliance.
Photonic integrated circuits are integrating silicon photonics for multi-species gas detection onto single chips. Oil refineries and petrochemical complexes in the US Gulf Coast and Rotterdam harbor adopt these platforms for fence-line monitoring. The technology is integrating laboratory-grade sensitivity into weatherproof enclosures that slash per-point installation costs.
China's Ministry of Ecology and Environment is tightening real-time data transparency requirements for provincial industrial clusters. Manufacturing facilities must now transmit calibrated readings directly to government servers without intermediary processing. Heavy industry in the Yangtze River Delta and Pearl River Delta is responding by hardening network security and redundant connectivity into monitoring system specifications.
Municipal water utilities are unbundling analytical service contracts from hardware ownership. Third-party operators now maintain sensor fleets and guarantee data validity under performance-based agreements. This reconfiguration concentrates most rapidly in German and Dutch drinking water networks where asset-light operating models align with municipal austerity pressures.
Environment Monitoring Devices Market Segmentation
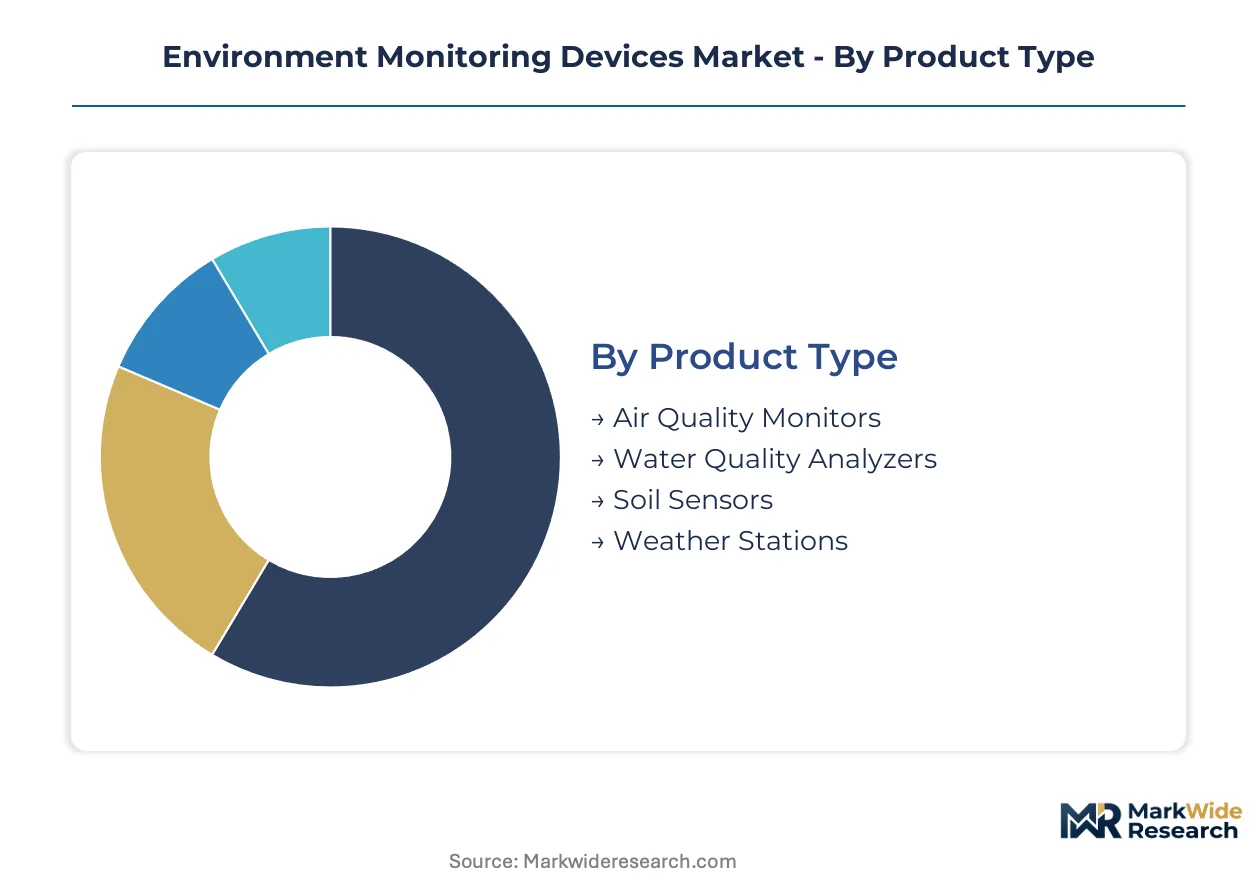
Segmentation in environment monitoring devices reflects divergent technical requirements across regulatory compliance, scientific research, and operational intelligence applications. Procurement patterns vary sharply between capital-intensive permanent installations and flexible subscription-based sensor networks.
Product Type:
Detection physics and calibration protocols differentiate hardware categories, with optical and electrochemical methods dominating distinct use cases.
- Air Quality Monitors:Optical particle counters and chemiluminescence analyzers detect PM2.5, NOx, and ozone at ppb thresholds. Municipal networks in the United States and China deploy these for EPA and MEE compliance, with continuous replacement cycles triggered by tightening ambient standards.
- Water Quality Analyzers:Multi-parameter sondes integrate dissolved oxygen, pH, conductivity, and turbidity sensors for riverine and wastewater monitoring. German and Dutch utilities are unbundling analytical service contracts from hardware ownership, accelerating sensor-as-a-service adoption.
- Soil Sensors:Capacitance-based moisture probes and ion-selective nutrient detectors support precision agriculture irrigation scheduling.
- Weather Stations:Ultrasonic anemometers and solid-state barometric sensors feed meteorological models for climate research and renewable energy forecasting.
Mature deployment sits with Air Quality Monitors. Newer deployment is concentrated in Soil Sensors.
Technology:
Connectivity architectures determine data latency, transmission costs, and edge processing capabilities for distributed monitoring networks.
- Wireless Sensors:LoRaWAN and NB-IoT protocols enable battery-operated nodes with 5-10 year lifespans for fence-line emissions tracking. Semiconductor fabrication facilities in Taiwan and South Korea deploy mesh networks for cleanroom contamination detection.
- IoT Solutions:Cloud-integrated platforms bundle hardware, connectivity, and software analytics under unified dashboards. Small municipal utilities with constrained capital budgets are penetrating this segment fastest through subscription pricing models.
- Remote Sensing:Satellite-mounted hyperspectral imagers and LIDAR systems track regional-scale pollution plumes and land-use changes.
- Data Analytics:Machine learning pipelines transform raw sensor streams into predictive maintenance schedules and emission forecasting models, commanding premium pricing.
Established infrastructure dominates Remote Sensing. IoT Solutions are climbing the fastest among technology categories.
End User:
Procurement authority and technical sophistication shape vendor engagement strategies across public and private sector buyers.
- Government Agencies:National environmental regulators mandate continuous monitoring at major emission sources, directly stimulating equipment replacement cycles through enforcement actions.
- Research Institutions:Universities and national laboratories require laboratory-grade sensitivity for atmospheric chemistry and hydrological studies.
- Industrial Facilities:Oil refineries and petrochemical complexes in the US Gulf Coast adopt photonic integrated circuits for fence-line monitoring, integrating silicon photonics into weatherproof enclosures.
- Agriculture:Large-scale farming operations deploy soil sensors and micro-weather stations for irrigation optimization and crop protection.
Volume concentration rests with Government Agencies. Agriculture represents the fastest-expanding end-user category.
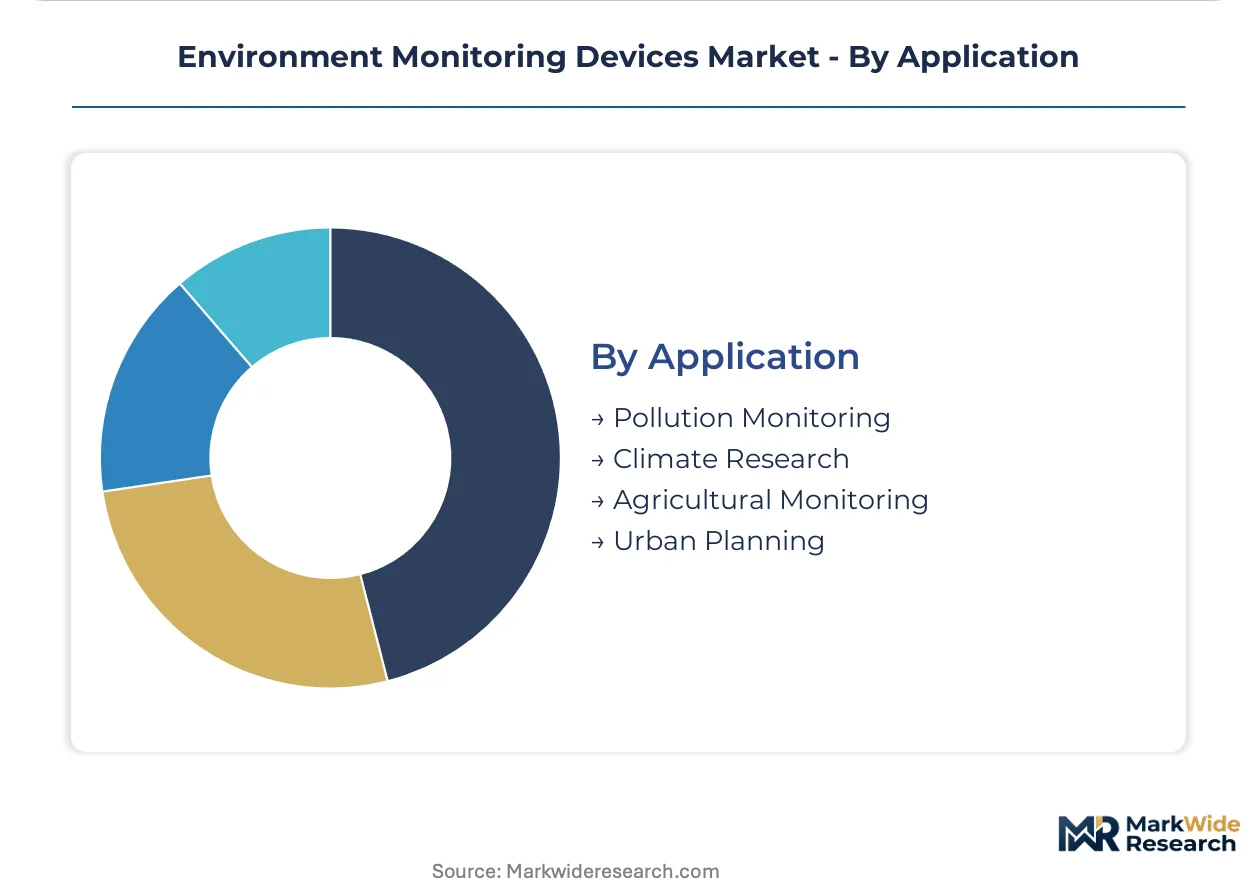
Application:
Use-case specificity drives sensor specification, with regulatory compliance demanding stricter calibration protocols than operational optimization.
- Pollution Monitoring:Continuous emissions monitoring systems track stack releases and ambient concentrations for EPA, EU, and MEE compliance. India's Central Pollution Control Board network densification creates first-mover positioning for vendors.
- Climate Research:Long-term atmospheric composition records require drift-corrected instruments with traceable calibration chains.
- Agricultural Monitoring:Soil moisture, nutrient, and microclimate sensors enable variable-rate input application and yield forecasting.
- Urban Planning:Dense sensor grids inform heat island mitigation, traffic emissions management, and green infrastructure design.
Regulatory mandates anchor Pollution Monitoring. Urban Planning is gaining share fastest as smart city investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of optical sensor components concentrates in East Asian foundries, while consumption patterns diverge across regulatory enforcement zones. Equipment deployment accelerates where ambient air quality mandates tighten fastest.
United States
Semiconductor fabrication expansion in Arizona and Texas drives ultra-trace contamination detection procurement. EPA National Ambient Air Quality Standards mandate continuous monitoring at major emission sources, triggering replacement cycles for legacy analyzer systems. Oil refineries along the US Gulf Coast adopt photonic integrated circuits for fence-line monitoring.
China
Heavy industry in the Yangtze River Delta and Pearl River Delta responds to MEE real-time data transparency requirements. The Ministry of Ecology and Environment enforces dual carbon goals that expand mandatory monitoring coverage to provincial industrial clusters. Manufacturing facilities harden network security and redundant connectivity into monitoring specifications.
Germany
Municipal water utilities unbundle analytical service contracts from hardware ownership under performance-based agreements. EU F-Gas Regulation phase-down accelerates leak detection infrastructure upgrades across chemical processing installations. The Ruhr industrial region and Bavarian manufacturing belt lead sensor-as-a-service adoption.
India
Central Pollution Control Board network densification creates first-mover positioning for continuous emissions monitoring system vendors. National Air Quality Monitoring Network expansion concentrates procurement in Delhi-NCR, Maharashtra, and Gujarat industrial corridors. Small municipal utilities with constrained capital budgets penetrate subscription pricing models fastest.
Japan
Precision instrumentation demand from METI-supported environmental technology programs sustains domestic manufacturing. Semiconductor fabrication facilities deploy mesh networks for cleanroom contamination detection in Kyushu and Chubu regions. Drift-corrected instruments with traceable calibration chains serve long-term atmospheric composition records.
Environment Monitoring Devices Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with life sciences and industrial automation portfolios. Market concentration remains moderate, with instrumentation specialists competing against integrated platform providers. Two strategic archetypes dominate: precision analytical instrument manufacturers and industrial automation-embedded sensor providers. Competitive moves center on strategic partnerships for cloud analytics integration and geographic licensing arrangements for multi-jurisdiction certification.
Among diversified technology conglomerates, Danaher Corporation and Thermo Fisher Scientific Inc. exemplify the precision analytical instrument archetype through their life sciences instrumentation portfolios. Siemens AG occupies a position within the industrial automation-embedded tier, competing through process control architecture integration. These three entities anchor the competitive landscape by representing divergent paths to market access: laboratory-grade sensitivity platforms versus manufacturing-embedded distributed networks.
| Leading Market Players |
|---|
| Danaher Corporation |
| Agilent Technologies Inc. |
| Thermo Fisher Scientific Inc. |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Siemens AG |
| PerkinElmer Inc. |
| Shimadzu Corporation |
| Teledyne Technologies Incorporated |
| Others |
Supply & Pricing Matrix
Photodetector wafer pricing indices from East Asian foundries cascade through three distinct equipment tiers, compressing margins on mid-range electrochemical sensors while laboratory-grade mass spectrometry systems retain pricing power through EPA equivalency certification requirements.
Pricing Analysis
Margin tightening in mid-tier ambient air monitors traces to laser diode supply constraints and calibration gas scarcity extending commissioning timelines. Three-tier pricing structure across premium, standard, and economy levels separates MCERTS-certified optical analyzers from municipal-grade electrochemical nodes and unbranded imports without temperature compensation. Pricing pressure accelerates in wireless sensor networks as subscription models displace capital purchases among small utilities. Government procurement offices exhibit highest price sensitivity; semiconductor fabs demonstrate lowest sensitivity due to cleanroom contamination detection mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for finished instruments. Laser diode and photodetector production concentrates in Taiwan, South Korea, and Japan. Silicon photonics wafers, electrochemical sensor membranes, and certified reference gases constitute critical input dependencies. Single-source vulnerability in East Asian photonics foundries exposes Western manufacturers to lead time volatility. Distribution runs through authorized technical distributors with field calibration capabilities rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
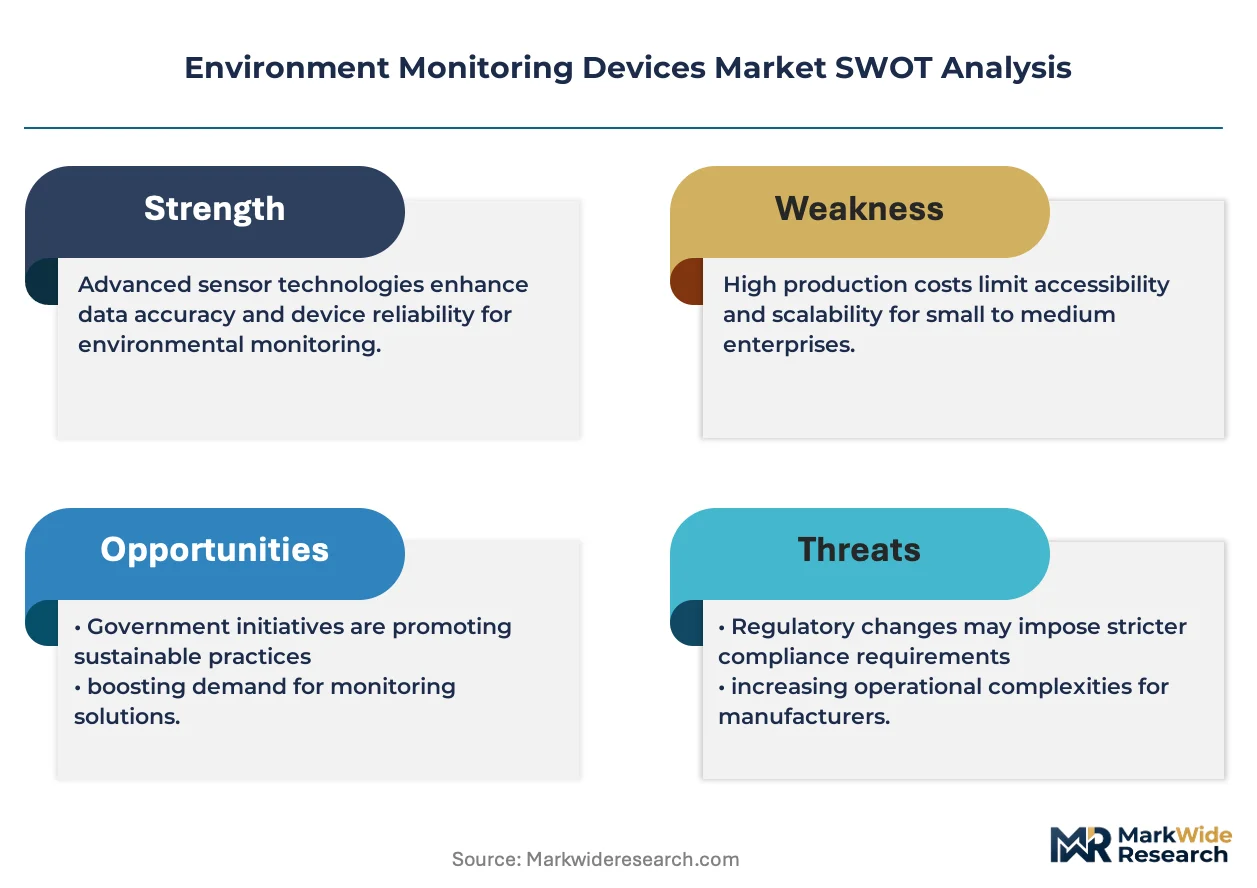
Optical component foundry capacity constraints prop pricing across all tiers, creating durable margin pools for vendors with captive supply arrangements or long-term offtake contracts.
For Market Incumbents: Cement technology leadership in photonic integrated circuits through backward integration into silicon photonics wafer supply or exclusive partnerships with Taiwan-based foundries. Defend against MEMS-based substitutes by embedding edge-AI inference capabilities that low-cost competitors cannot replicate without cross-disciplinary engineering teams. Prioritize MCERTS and EPA equivalency certification investments to maintain procurement eligibility as regulatory granularity intensifies.
For New Entrants and Emerging Players: Edge-AI sensor fusion offers the most penetrable wedge for bypassing incumbent instrument lock-in. Target India's Central Pollution Control Board network densification before established vendors complete distribution infrastructure. Pursue sensor-as-a-service channel partnerships with municipal utilities in Germany and the Netherlands where asset-light operating models align with austerity pressures.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive photonics manufacturing and existing multi-jurisdiction certification portfolios. Monitor EPA National Ambient Air Quality Standards tightening velocity and EU F-Gas Regulation phase-down implementation as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Integration | Laboratory-grade sensitivity in weatherproof enclosures slashes per-point installation costs for fence-line monitoring. |
| Sensor-as-a-Service Channel Development | Subscription pricing penetrates small municipal utilities with constrained capital budgets in German and Dutch networks. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA equivalency, EU MCERTS, and China MEE approvals compress product launch timelines by 12-18 months. |
| Edge-AI Convergence with MEMS Sensors | On-device inference reduces cloud transmission costs and enables sub-second alert generation for critical emissions events. |
| Backward Integration into Optical Components | Captive laser diode supply insulates margins from East Asian foundry lead time volatility and tariff exposure. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and equipment procurement contracts underwrites the qualitative findings. Primary interviews with environmental compliance officers at industrial facilities, municipal utility procurement managers, and field service engineers at technical distributors combined with secondary validation from EPA enforcement actions, EU ETS emissions data, and China MEE transparency disclosures. Bottom-up unit economics triangulate against top-down market sizing across the analysis window.
Comparable-period anchoring to historical replacement cycles and regulatory enforcement intensities shapes the projection horizon. Segmentation dimensions include detection physics, connectivity architecture, end-user procurement authority, and application-specific calibration requirements. CAGRs derive from equipment deployment velocity tied to ambient air quality mandate tightening schedules. Forecast inputs incorporate semiconductor fabrication capacity expansion timelines and F-Gas Regulation phase-down compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden tariff escalations on East Asian optical components or accelerated EPA standard revisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market