
 Propionic Acid Market | 2026-2036
Propionic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Propionic Acid Market Intelligence
The bundling of propionic acid with other feed additives like formic acid is restructuring buyer procurement strategies, favoring suppliers with diverse chemical portfolios. BASF SE leverages its extensive production capacity to offer these combined solutions globally. Dow Inc. differentiates with high-purity grades for specialized industrial applications like polymer production. Eastman Chemical Company sustains its market position through a robust distribution network across North America and Europe.
Propionic acid is a naturally occurring carboxylic acid, chemically designated as CH3CH2CO2H. Industrial production predominantly involves the carbonylation of ethylene, yielding a liquid with a characteristic pungent odor. Its primary function is as a powerful mold inhibitor and preservative, crucial for livestock grain and certain human foods. The feed additives application for animal feed manufacturers represents the largest and most mature segment, while use in polymer production and herbicides shows notable growth.
Frameworks from the U.S. FDA and the European Food Safety Authority (EFSA) define purity standards and maximum residue limits in food and feed. China's State Administration for Market Regulation (SAMR) enforces strict GB standards for its use as a preservative. These regulations directly influence market access and grade-specific demand. Navigating the choice between bio-based alternatives and petrochemical-derived products remains the central strategic decision for producers.
Market Dynamics
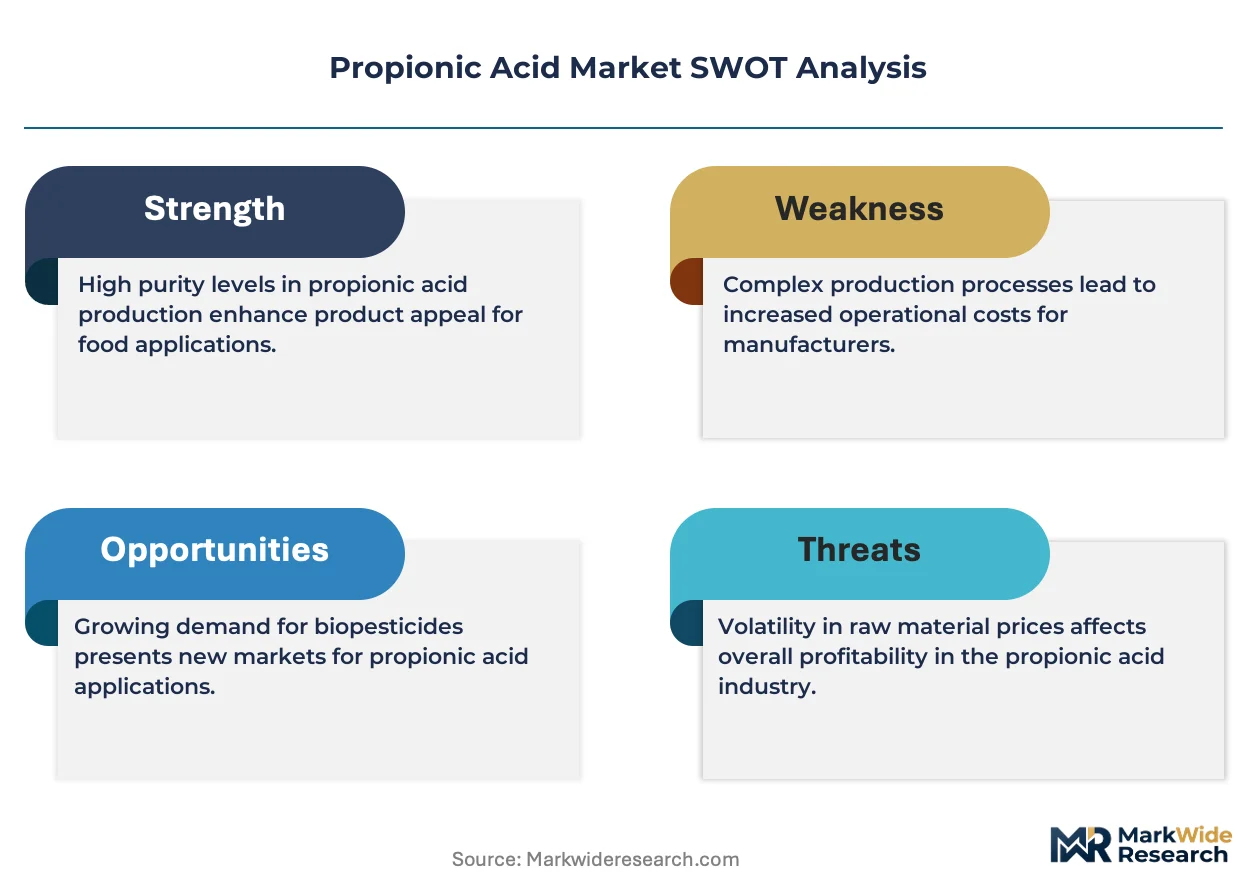
The central strategic decision for producers and buyers revolves around the choice between conventional petrochemical-derived propionic acid and emerging bio-based alternatives. This tension is driven by both input cost volatility and sustainability mandates from regulators like the EFSA.
Growth Catalysts
- Stringent Feed Regulations:The EU Green Deal and similar frameworks promote efficient livestock feed utilization and reduced spoilage, directly supporting the use of propionic acid as a proven grain preservative to minimize waste.
- Food Safety Initiatives:China's national focus on food safety, enforced through its GB standards, increases demand for high-quality preservatives in its massive animal feed and food processing industries to prevent mold contamination.
- Bio-based Production Advances:Improvements in microbial fermentation technology are making bio-based propionic acid more economically viable, appealing to buyers with corporate sustainability goals and demand for "green" ingredients.
Market Restraints
- Input Price Volatility:The market's cost structure is tied to petrochemical feedstocks like ethylene and carbon monoxide, making producer margins susceptible to fluctuations in global energy and chemical markets.
- Substitution Threats:In certain food preservation applications, propionic acid faces competition from other preservatives like sorbic acid and benzoic acid, which can offer different efficacy or cost profiles.
- Supply Chain Risk:Heavy concentration of industrial production capacity within a few key chemical hubs in North America, Europe, and China creates potential for logistical bottlenecks and regional supply disruptions.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in the rapidly growing and professionalizing animal feed markets of Southeast Asia, where adoption of advanced feed preservation techniques is still developing.
- Emerging Polymer Applications:The use of propionic acid as a chemical intermediate for producing cellulose acetate propionate (CAP) and other specialized polymers for coatings and plastics represents a high-value growth vector.
- Green Chemistry Incentives:Producers of bio-based propionic acid can capitalize on government incentives and green procurement policies aimed at promoting sustainable chemicals and reducing reliance on fossil-fuel-based feedstocks.
Industry Challenges
- High Capital Intensity:Constructing new world-scale production facilities, whether through ethylene carbonylation or large-scale fermentation, requires substantial capital investment and long lead times, limiting new market entrants.
- Divergent Regulatory Compliance:Manufacturers must navigate and comply with a complex web of differing maximum residue limits (MRLs) and purity standards set by the FDA, EFSA, and SAMR for food and feed uses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propionic Acid Market |
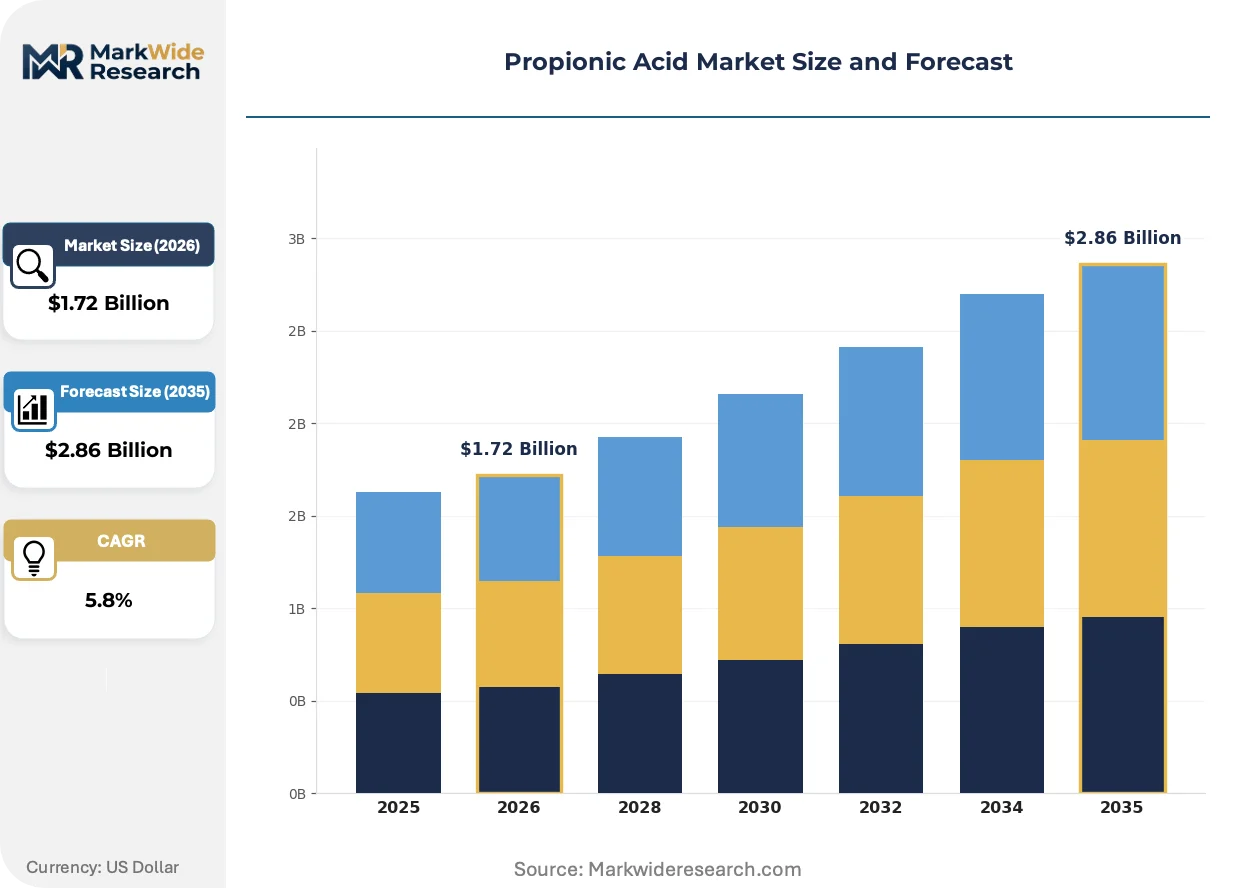
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Preservatives, Herbicides, Feed Additives, Polymer Production End User: Animal Feed Manufacturers, Chemical Manufacturers, Pharmaceutical Companies, Cosmetic Producers Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Carboys |
| Companies Covered | Celanese Corporation, Oxea GmbH, BASF SE, Merck KGaA, Corbion N.V., Dow Inc., Perstorp Holding AB, Hawkins Inc., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propionic Acid Market Strategic Shifts & Innovations
A fundamental transition from a bulk commodity to a performance-differentiated ingredient defines the market's evolution. This change is propelled by demand for specific purity grades for new applications and a growing preference for sustainable production pathways.
Bio-based production using advanced microbial fermentation offers a renewable alternative to petrochemical synthesis. Food and feed manufacturers are increasingly adopting these grades to meet sustainability targets and consumer demand for green labels. This potential for a circular, non-fossil-fuel-based supply chain is electrifying the industry’s long-term capital investment strategy, challenging the dominance of traditional carbonylation.
China’s stringent GB standards, enforced by the State Administration for Market Regulation (SAMR), impose strict purity requirements on propionic acid in food and feed. This framework elevates quality control to a competitive factor, barring low-grade imports. The animal feed preservative segment is most impacted, forcing suppliers to certify products to these specific national standards to gain market access.
Consolidated purchasing for bundled additive packages is displacing single-ingredient transactions. This model disrupts specialist producers by favoring suppliers who offer a portfolio including formic acid and other preservatives. The shift is most pronounced within the integrated livestock systems of North America and Europe, where supply chain simplification is a key procurement objective.
Propionic Acid Market Segmentation
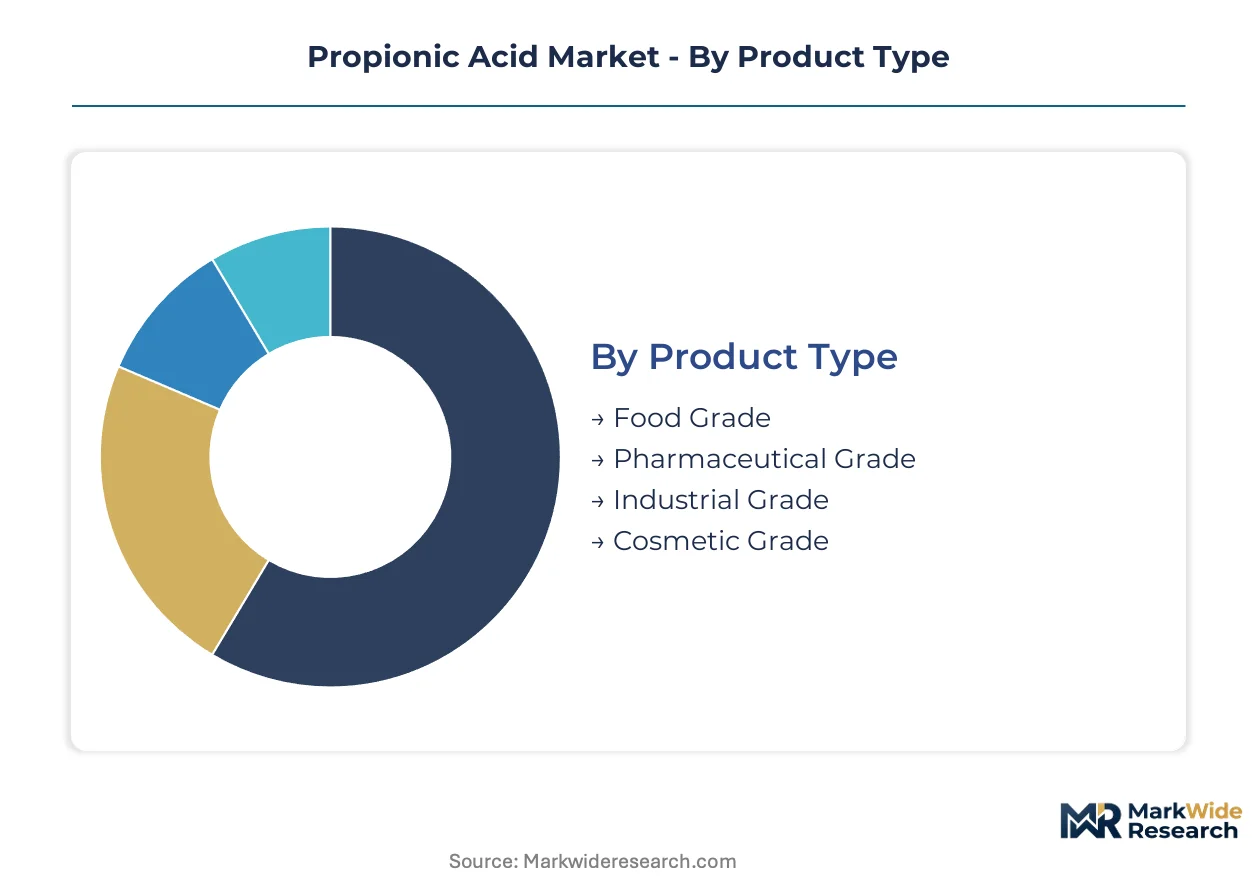
The propionic acid market segments based on product type, application, end user, and packaging reflect distinct demand drivers and supply chain requirements. Understanding these differentiations allows producers to align their offerings with specific industry needs and regulatory mandates.
Product Type:
Propionic acid product types differentiate based on purity and intended integration into specific manufacturing processes or direct consumption.
- Food Grade:This product type maintains high purity with minimal impurities, adhering to strict food safety standards. Demand concentrates in China, driven by national food safety initiatives that mandate high-quality preservatives for grain and food products.
- Industrial Grade:This grade represents standard purity propionic acid, suitable for a wide array of chemical synthesis and manufacturing processes. Demand is strong in North America for polymer production, tied directly to the region's robust chemical manufacturing output.
- Pharmaceutical Grade:This ultra-high purity grade meets stringent specifications for use in medical and drug formulations. Pharmaceutical companies require this precise quality for active pharmaceutical ingredients or excipients.
- Cosmetic Grade:This controlled purity grade is specifically formulated for personal care products. Cosmetic producers utilize it as a preservative to ensure product stability and consumer safety.
Volume placements concentrate in Industrial Grade; the faster expansion belongs to Food Grade.
Application:
Propionic acid applications span from broad-spectrum preservation to highly specialized chemical synthesis.
- Feed Additives:This application segment uses propionic acid as a critical grain preservative to inhibit mold and bacterial growth in animal feed. Demand from the European Union is substantial, driven by the EU Green Deal's emphasis on efficient feed utilization and reduced spoilage.
- Polymer Production:Propionic acid serves as a chemical intermediate for creating specialized polymers, including cellulose acetate propionate (CAP), used in coatings and plastics. Demand in North America stems from the expanding specialty chemicals sector, seeking high-performance material components.
- Preservatives:This broad application encompasses the use of propionic acid in various food and feed products to prevent spoilage. It is utilized in human food products like baked goods and cheese.
- Herbicides:Propionic acid acts as a component in certain agricultural chemical formulations. Farmers use it for effective weed control in specific crop applications.
The largest volume segment remains Feed Additives, with Polymer Production showing significant potential.
End User:
End-user segments for propionic acid reflect distinct industrial purchasing behaviors and regulatory environments.
- Animal Feed Manufacturers:This segment represents the largest consumer of propionic acid, primarily for preserving grains and silage. Demand in China is particularly high, driven by the country's extensive livestock production and national food safety initiatives.
- Chemical Manufacturers:These entities utilize propionic acid as a foundational building block for synthesizing various derivatives and polymers. Demand in Europe is propelled by the region's advanced chemical industry, focusing on specialized product development.
- Pharmaceutical Companies:These companies integrate high-purity propionic acid into drug formulations and excipients. They require strict quality control for all incoming raw materials.
- Cosmetic Producers:This segment employs propionic acid as a preservative within personal care and beauty products. Their focus remains on ensuring product stability and consumer safety.
Demand concentration is highest among Animal Feed Manufacturers, while Chemical Manufacturers exhibits a steeper expansion curve for new applications.
Packaging Type:
Propionic acid packaging types are primarily determined by shipment volume, logistical efficiency, and end-user handling requirements.
- Bulk Containers:These large-scale transport solutions cater to industrial users requiring significant volumes of propionic acid. Demand from major chemical manufacturers in North America is high, optimizing supply chain costs for continuous production.
- Drums:This standard packaging format serves medium-volume industrial and commercial users, offering a balance of capacity and manageability. Demand from smaller feed mills in Europe is consistent, requiring flexible delivery options.
- Intermediate Bulk Containers:These reusable containers offer efficient handling for moderate volumes, bridging the gap between drums and bulk shipments. They are preferred by specialized chemical processors for batch production.
- Carboys:These smaller, robust containers are designed for laboratory use or low-volume specialized applications. Pharmaceutical companies often use carboys for handling specific high-purity ingredients.
The dominant format for high-volume delivery is Bulk Containers, with Intermediate Bulk Containers serving specialized logistical needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propionic acid production primarily concentrates in established chemical manufacturing hubs, while consumption patterns shift with expanding livestock industries and evolving food safety regulations. Global demand for propionic acid is driven by its essential role as a preservative in animal feed and polymer production. This creates a dynamic interplay between regions focused on synthesis and those with large agricultural sectors.
China
Demand for propionic acid in China is substantial, propelled by its extensive livestock production and national food safety initiatives. The State Administration for Market Regulation (SAMR) enforces strict GB standards, influencing purity requirements across food and feed. Chemical manufacturing clusters in the Yangtze River Delta actively produce and consume propionic acid derivatives.
United States
The United States exhibits strong demand for propionic acid, particularly as a chemical intermediate in polymer production. U.S. FDA frameworks define purity standards and maximum residue limits for food and feed uses. The Gulf Coast region, with its robust chemical industry, is a significant hub for production and consumption.
Germany
Germany's advanced chemical industry drives significant propionic acid consumption for specialized product development and polymer applications. The European Food Safety Authority (EFSA) sets stringent standards for its use in food and feed. The Rhine-Ruhr chemical corridor represents a key industrial concentration for propionic acid synthesis and downstream processing.
Brazil
Brazil's expanding animal feed market creates substantial demand for propionic acid as a grain preservative to support its large agricultural sector. The country's national food safety agencies establish guidelines for feed additives, ensuring product quality. Industrial zones in São Paulo state are witnessing increased investment in feed additive production and distribution.
India
India's developing animal feed and food processing sectors present a growing market for propionic acid, particularly for mold inhibition. The Food Safety and Standards Authority of India (FSSAI) regulates its use as a food and feed additive, influencing purity requirements. The Gujarat chemical belt is emerging as a production and distribution center for various chemical intermediates.
Propionic Acid Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the propionic acid market, creating a tiered competitive structure. Large chemical manufacturers often integrate propionic acid into broader portfolios, leveraging existing feedstock supply chains and distribution networks. Mid-sized players specialize in specific grades like bio-based or high-purity, targeting niche applications. Dominant competitive moves include strategic partnerships for bio-based technology and geographic expansion into emerging agricultural markets.
At the scale-driven end, BASF SE exemplifies large-scale petrochemical production and global distribution capabilities, often bundling propionic acid with other feed additives in its diverse chemical portfolio. Dow Inc. occupies a position focusing on high-purity grades for specialized industrial applications such as polymer production. Eastman Chemical Company represents another significant player, leveraging a robust distribution network across North America and Europe to maintain its market presence. These entities anchor the market through extensive production capacities and broad customer reach, influencing supply dynamics across various end-use sectors and grades.
| Leading Market Players |
|---|
| Celanese Corporation |
| Oxea GmbH |
| BASF SE |
| Merck KGaA |
| Corbion N.V. |
| Dow Inc. |
| Perstorp Holding AB |
| Hawkins Inc. |
| Eastman Chemical Company |
Cost & Logistics Intelligence
Diversified chemical conglomerates, with their extensive production capacities, exert significant influence over propionic acid supply and pricing discipline. Their global distribution networks manage feedstock volatility and ensure market access.
Pricing Analysis
Margin tightening in industrial-grade propionic acid reflects petrochemical feedstock volatility. The dominant pricing structure combines commodity spot rates for bulk volumes with contract-based long-term agreements for bundled additive packages. Price differentiation stems from quality grades, such as food-grade meeting China's GB standards, and volume scale. Animal feed manufacturers exhibit higher price sensitivity compared to pharmaceutical companies requiring ultra-high purity.
Supply Chain Analysis
Propionic acid supply rests on petrochemical feedstocks like ethylene and carbon monoxide, exposing producers to market fluctuations. Production capacity concentrates heavily in the United States, Germany, and China, leading to potential logistical bottlenecks. This geographic concentration creates single-source vulnerability for some buyers. Distribution runs through established global networks for bulk containers and specialized regional channels for drums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The propionic acid market increasingly functions as a cost-of-compliance story, where stringent regulatory frameworks define market access. China's GB standards, enforced by SAMR, establish a significant barrier-to-entry moat for high-quality, compliant producers.
For Market Incumbents:Extend existing global distribution networks into professionalizing animal feed markets in Southeast Asia to counter regional competition. Incumbents should invest in advanced microbial fermentation technologies to diversify from petrochemical feedstocks, mitigating input price volatility. Consolidate market share by offering bundled feed additive packages, leveraging established customer relationships against single-ingredient specialists. Secure critical regulatory certifications like China's GB standards to defend market access.
For New Entrants and Emerging Players:Advanced microbial fermentation technologies offer a potent technology-first wedge for new entrants targeting the bio-based segment. Focus on developing high-purity grades for emerging polymer applications, which represent a high-value growth vector. The most penetrable segment lies within food and feed manufacturers seeking "green" ingredients to meet sustainability goals. A direct-to-customer go-to-market angle, emphasizing environmental credentials and specific certifications, can secure early adopters.
For Investors and Strategic Acquirers:Distressed-cycle entries favor strategic acquirers seeking specialized bio-based producers in Europe, driven by sustainability mandates. The long-term viability of propionic acid remains strong, underpinned by its essential role as a preservative and chemical intermediate. Target acquisition archetypes include mid-sized players with proprietary fermentation technology or established distribution in high-growth regions like Southeast Asia. A significant signal to watch is the economic viability of new bio-based production facilities reaching commercial scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | This move supports the professionalizing animal feed markets in a high-growth region. |
| Green Manufacturing Transition | Capitalizing on bio-based production aligns with corporate sustainability goals and government incentives. |
| Long-term Offtake Agreements | Securing stable demand from large animal feed manufacturers mitigates market volatility for producers. |
| Joint Venture for Bio-based Technology | Partnerships accelerate the development and commercialization of advanced microbial fermentation processes. |
| Investment in Regulatory Certifications | Meeting China's stringent GB standards ensures market access and competitive advantage for compliant products. |
Research Approach
Trade association data, regulatory filings from EFSA and FDA, and customs records anchored secondary inputs for this study. Primary interviews included plant managers, procurement leads at animal feed manufacturers, and R&D directors focused on polymer applications. This approach combined bottom-up market sizing with top-down validation, incorporating insights from regulatory affairs specialists.
Data-stream reconciliation integrated historical trends with future projections across the analysis window. The model segmented propionic acid by product type, application, end user, and packaging format, alongside regional adoption patterns. Compound annual growth rates derived from market drivers, expert projections, and historical performance. Key forecast inputs included ethylene prices, global livestock production volumes, and bio-based technology adoption rates.
Several conditions sit outside the modeled scope, including micro-level pricing fluctuations and specific R&D pipeline details. Forecasts reflect assumptions documented regarding geopolitical stability and feedstock availability. Unforeseen regulatory shifts or rapid substitute technology adoption could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market