
 Isobutyraldehyde Market | 2026-2036
Isobutyraldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Isobutyraldehyde Market Foresight
A capital-intensity divergence between integrated petrochemical giants and specialty chemical operators is reorganizing competitive dynamics in isobutyraldehyde supply. BASF SE leverages its Ludwigshafen Verbund site to sustain captive propylene feedstock integration, while Celanese Corporation anchors North American production through its Texas Gulf Coast infrastructure. Mitsubishi Chemical Corporation competes via technology leadership in high-purity grades for pharmaceutical applications.
Isobutyraldehyde (2-methylpropanal) is a colorless, highly flammable liquid with a pungent odor, produced primarily through hydroformylation of propylene with synthesis gas; it functions as a versatile building block for synthesizing isobutanol, neopentyl glycol, and various pharmaceutical intermediates. Liquid product type dominates commercial volumes due to handling efficiency and established storage infrastructure, while intermediates application captures the deepest margin pools through long-term supply contracts to agrochemical and pharmaceutical manufacturers. Flavoring agents application occupies a premium niche with stringent purity requirements and shorter qualification cycles.
EPA regulations under the Toxic Substances Control Act and OSHA process safety management standards govern U.S. production facility design and emission thresholds, while REACH registration obligations in Europe mandate comprehensive substance dossiers for market access. China's MEE enforces increasingly stringent volatile organic compound discharge limits around Yangtze River Delta chemical parks. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional feedstock cost differentials to optimize capacity placement and contractual structures.
Market Dynamics
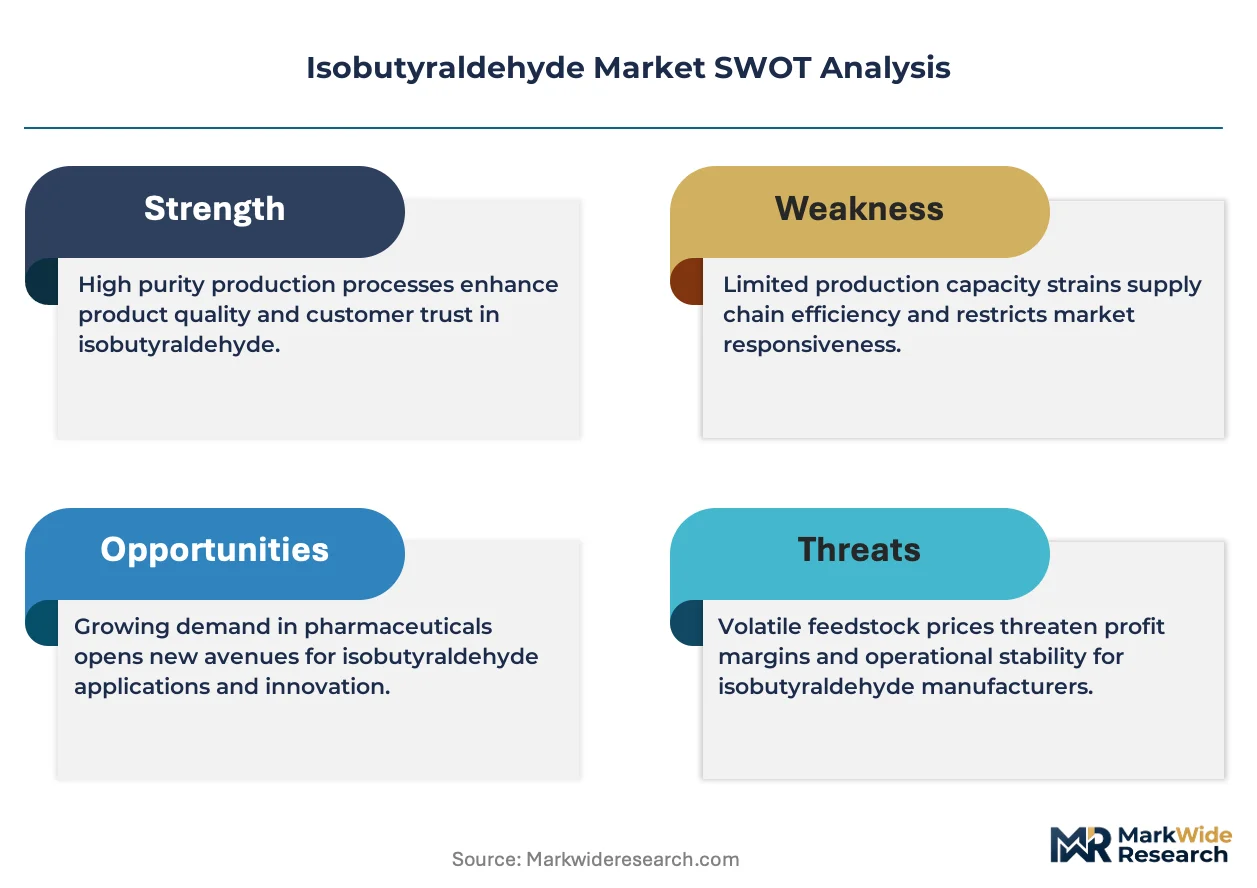
Feedstock cost volatility and propylene supply concentration in the US Gulf Coast and Middle Eastern corridors are compressing margin structures for non-integrated isobutyraldehyde producers, forcing asset-light operators toward tolling arrangements or long-term offtake contracts with integrated refiners.
Growth Catalysts
- Pharmaceutical intermediate demand:Synthesis of ACE inhibitors and other cardiovascular APIs requires high-purity isobutyraldehyde grades, with CDSCO and FDA inspections driving qualification standards upward.
- REACH registration completion:Full dossier submission by major EU suppliers eliminated market access barriers for pharmaceutical-grade material, streamlining cross-border trade within the European Economic Area.
- China's Yangtze River Delta chemical park consolidation:Centralized wastewater treatment and VOC recovery infrastructure at Taixing and Nantong clusters lowered environmental compliance costs for compliant producers.
Market Restraints
- Propylene feedstock volatility:Steam cracker operating rates and PDH unit economics in the US and Middle East transmit directly to isobutyraldehyde production costs, squeezing non-integrated operators.
- Supply concentration risk:Ludwigshafen Verbund and Texas Gulf Coast complexes control disproportionate captive supply, limiting spot market liquidity and alternative sourcing options.
- Neopentyl glycol substitution pressure:Alternative routes using formaldehyde and isobutyraldehyde compete with glycerol-based processes in certain coating applications.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:PLI scheme incentives for API production create qualified demand for pharmaceutical-grade isobutyraldehyde at Dahej and Visakhapatnam chemical parks.
- Bio-based propylene pathways:Renewable naphtha and bio-PDH technologies converging with conventional hydroformylation enable carbon-intensity reduction for brand-owner specifications.
- Direct e-commerce channels:Alibaba 1688 and specialty chemical platforms are compressing distributor layers for standard-grade material in East Asian spot transactions.
Industry Challenges
- Process safety engineering talent scarcity:OSHA PSM and Seveso III compliance requires specialized expertise in hydroformylation unit operations that outpaces vocational training pipeline output.
- Pharmaceutical qualification timeline compression:FDA and EMA change notification protocols extend re-qualification cycles to 18-24 months for specification modifications.
- Legacy DCS integration complexity:Older hydroformylation plants face control system modernization costs when connecting to enterprise carbon accounting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isobutyraldehyde Market |
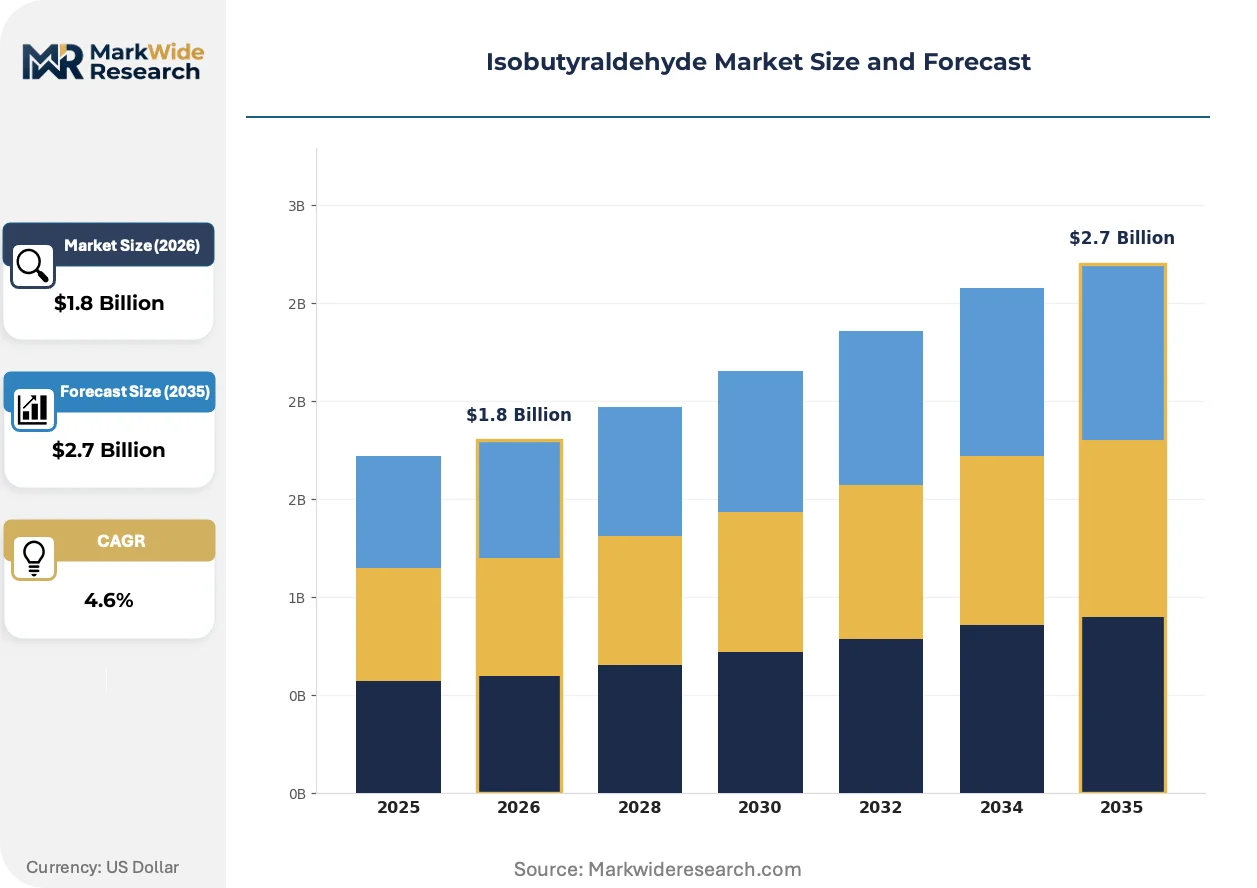
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gas, Solid, Crystalline Application: Solvents, Intermediates, Chemical Synthesis, Flavoring Agents End User: Chemical Industry, Paints & Coatings, Food & Beverage, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Mitsubishi Chemical Corporation, Celanese Corporation, BASF SE, Evonik Industries AG, Sumitomo Chemical Co. Ltd., Dow Inc., Arkema S.A., Perstorp Holding AB, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isobutyraldehyde Market Shifts & Advancements
Hydroformylation catalyst evolution and downstream process intensification are restructuring production economics, while regulatory carbon accounting and buyer consolidation reshape commercial relationships across the value chain.
Low-pressure rhodium-phosphine catalysis is decomposing the traditional cobalt-based hydroformylation cost structure in new capacity installations. Pharmaceutical manufacturers in Switzerland and Japan are specifying rhodium-catalyzed material for impurity profile consistency. This technology is decomposing the historical premium commanded by high-pressure process veterans in merchant markets.
EU Green Deal carbon border adjustment mechanisms are forcing embedded emissions documentation for imported isobutyraldehyde and derivatives. ETS benchmark calculations now include Scope 3 upstream emissions, compelling non-EU suppliers to deploy certified carbon accounting. Pharmaceutical and coating formulators in Germany and the Netherlands are prioritizing low-carbon intensity certificates in supplier scorecards.
Consolidated procurement by multinational agrochemical formulators is compressing supplier panels from regional distributors to direct mill relationships. BASF and Celanese now manage tier-one supply through multi-year framework agreements with volume commitments and indexed pricing. This concentration is most visible in Brazilian and Australian glyphosate precursor supply chains where three buyers control majority volume.
Isobutyraldehyde Market Segmentation
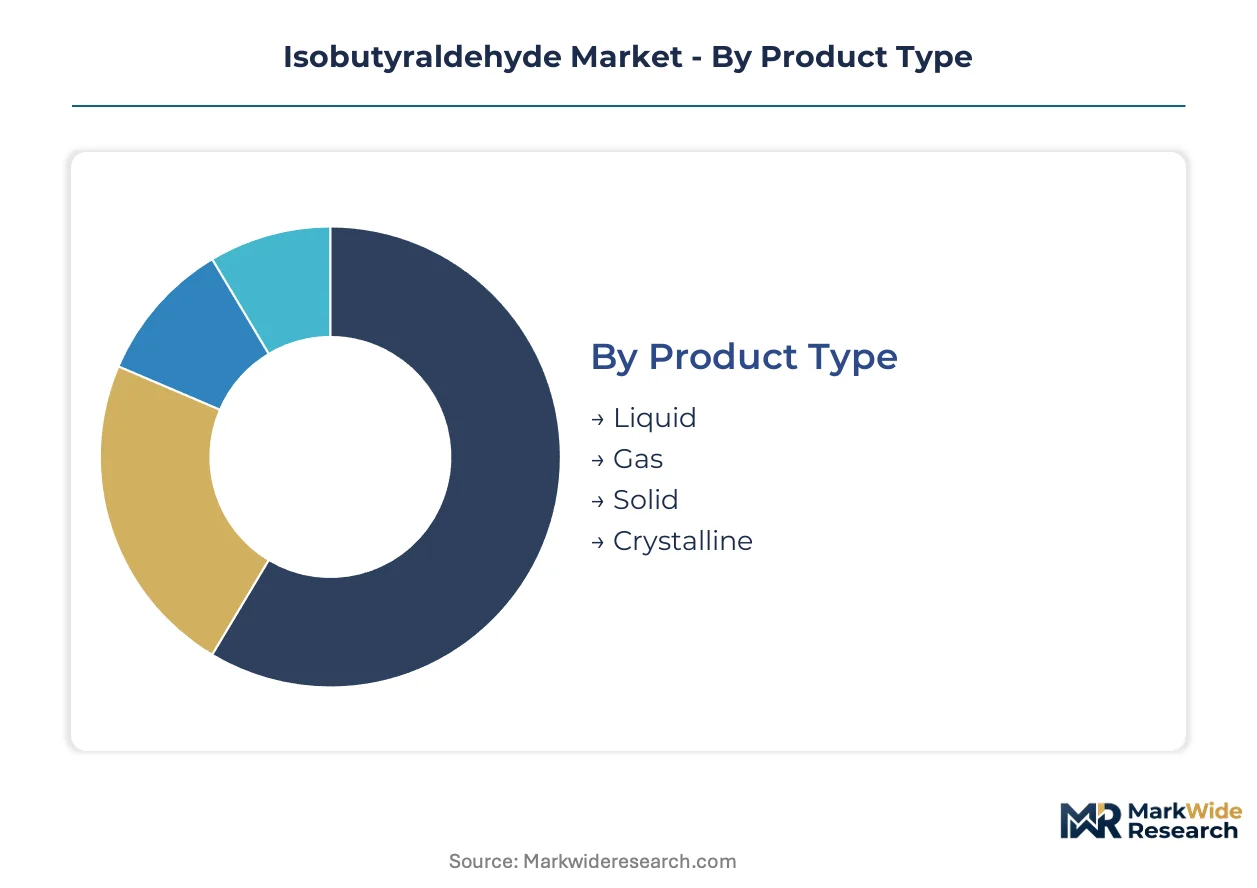
Isobutyraldehyde's diverse industrial roles create distinct channel economics across product grades. Pharmaceutical and food-grade specifications command dedicated distribution infrastructure, while standard industrial volumes flow through consolidated chemical distribution networks.
Product Type:
Liquid product dominates bulk chemical logistics, with gas and solid forms serving specialized synthesis requirements where handling protocols diverge sharply.
- Liquid:Colorless, highly flammable liquid with pungent odor, stored and transported in stainless steel tankers and lined drums. Chemical processing corridors in China's Yangtze River Delta and Germany's Ludwigshafen cluster concentrate demand for this form, driven by hydroformylation unit proximity and established tank farm infrastructure.
- Gas:Vapor-phase isobutyraldehyde serves specialized pharmaceutical synthesis and analytical applications requiring precise stoichiometric control. Swiss and Japanese pharmaceutical manufacturers specify gas-phase material for impurity profile consistency in ACE inhibitor production.
- Solid:Polymer-encapsulated or complexed solid forms enable controlled-release applications in agrochemical formulations.
- Crystalline:High-purity crystalline grades meet stringent food and pharmaceutical specifications with extended shelf stability.
Liquid dominates installed base. Crystalline is where expansion concentrates.
Application:
Margin structures diverge sharply between long-term contract intermediates and spot-market flavoring agents, with solvents occupying a cost-competitive middle tier.
- Intermediates:Serves as building block for neopentyl glycol, isobutanol, and pharmaceutical precursors with multi-year supply agreements. Agrochemical formulators in Brazil and Australia lock in volume commitments through framework contracts with indexed pricing.
- Flavoring Agents:High-purity grades for food and beverage applications with stringent FDA and EFSA purity requirements. Shorter qualification cycles and premium pricing attract specialty chemical operators seeking margin protection.
- Solvents:Industrial cleaning and extraction applications with price-sensitive procurement patterns.
- Chemical Synthesis:General-purpose reagent use across research and specialty manufacturing with fragmented demand.
Intermediates capture the deepest margin pools. Flavoring agents are climbing the fastest.
End User:
Customer consolidation patterns favor direct mill relationships with integrated producers, while fragmented segments rely on distributor intermediaries.
- Pharmaceuticals:ACE inhibitor and cardiovascular API synthesis demands pharmaceutical-grade material with CDSCO and FDA inspection protocols. India's PLI scheme incentives at Dahej and Visakhapatnam chemical parks are qualifying new demand sources.
- Chemical Industry:Broad intermediate consumption across agrochemical and specialty chemical value chains with consolidated procurement panels.
- Paints & Coatings:Neopentyl glycol precursor demand tied to coating formulation cycles and construction activity.
- Food & Beverage:Flavoring agent applications with FSSAI and FDA compliance requirements and shorter product lifecycles.
Chemical Industry anchors volume throughput. Pharmaceuticals is where specification premiums expand.
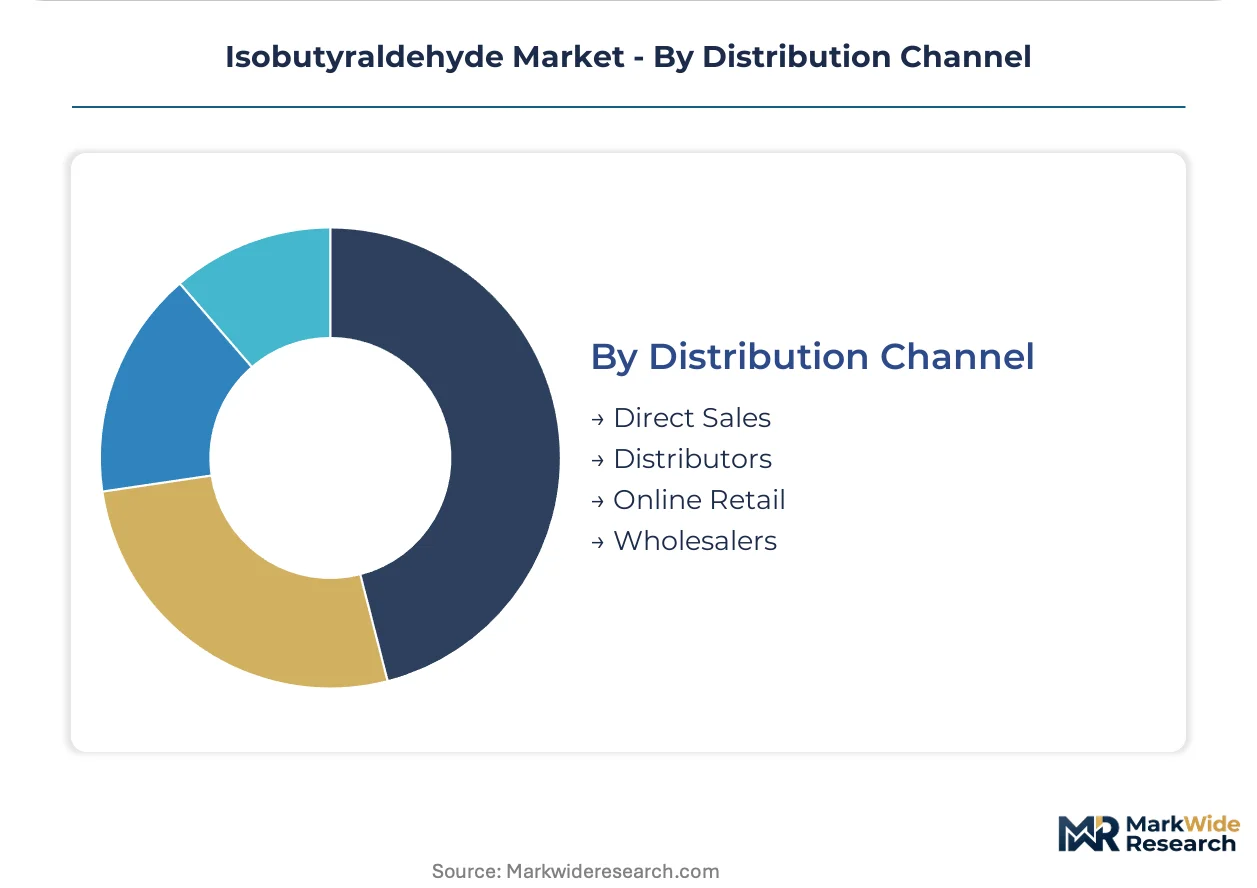
Distribution Channel:
Channel selection correlates with buyer scale and specification complexity, with digital platforms compressing layers for standard-grade spot transactions.
- Direct Sales:Multi-year framework agreements with volume commitments link BASF and Celanese to multinational agrochemical formulators. Indexed pricing mechanisms and technical service support justify the relationship investment.
- Distributors:Regional chemical distributors manage inventory and qualification documentation for mid-tier pharmaceutical and coating manufacturers.
- Online Retail:Alibaba 1688 and specialty chemical platforms enable spot procurement for standard-grade material in East Asian markets.
- Wholesalers:Bulk aggregation for smaller industrial consumers with limited technical specification requirements.
Direct Sales commands the largest contract value. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers in Switzerland and Japan exhibit the least price elasticity, absorbing premium grades for impurity consistency, while coating formulators in Brazil and Australia drive hard volume negotiations. Chemical processors in China's Yangtze River Delta cluster occupy the middle ground, balancing specification requirements against feedstock cost exposure.
China
Neopentyl glycol precursor demand and pharmaceutical intermediate synthesis dominate consumption. MEE enforcement of VOC discharge limits around Taixing and Nantong chemical parks is consolidating production into compliant zones. The Yangtze River Delta corridor concentrates hydroformylation capacity with centralized wastewater infrastructure lowering per-unit compliance costs.
Germany
High-purity pharmaceutical grades for ACE inhibitor APIs command sustained premiums. ECHA REACH registration completion eliminated cross-border trade friction within the European Economic Area. The Ludwigshafen Verbund cluster anchors captive propylene integration with rhodium-catalyzed production serving Swiss and domestic pharmaceutical formulators.
United States
Agrochemical intermediate offtake and coating precursor demand drive volume. EPA Toxic Substances Control Act and OSHA process safety management standards govern facility design and emission thresholds. The Texas Gulf Coast infrastructure concentrates production with indexed pricing mechanisms linking propylene feedstock costs to multinational offtake contracts.
India
API manufacturing expansion under the PLI scheme is qualifying new pharmaceutical-grade demand. CDSCO inspection protocols align with FDA standards for cardiovascular drug precursor qualification. Dahej and Visakhapatnam chemical parks are emerging as import substitution hubs with dedicated storage for high-purity material.
Japan
Specialized pharmaceutical synthesis and analytical applications require gas-phase material for stoichiometric precision. METI industrial standards and PMDA pharmaceutical regulations enforce stringent impurity profiling. Osaka and Tokyo pharmaceutical manufacturing clusters source rhodium-catalyzed grades for consistency in ACE inhibitor production.
Isobutyraldehyde Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical giants commanding feedstock economics and specialty operators capturing specification premiums. The market structure concentrates around three tiers: captive producers with backward integration into propylene supply, merchant specialists with pharmaceutical qualification expertise, and regional tolling operators serving spot industrial demand. Strategic moves center on multi-year framework agreements with volume commitments and carbon intensity certification to meet EU Green Deal procurement criteria.
Within the integrated petrochemical tier, BASF SE and Celanese Corporation exemplify divergent geographic anchoring strategies. Mitsubishi Chemical Corporation occupies a position in the high-purity pharmaceutical specialist segment. These three entities represent the dominant competitive archetypes: European Verbund-site integration, North American Gulf Coast feedstock access, and Asian technology leadership in pharmaceutical-grade production.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Celanese Corporation |
| BASF SE |
| Evonik Industries AG |
| Sumitomo Chemical Co. Ltd. |
| Dow Inc. |
| Arkema S.A. |
| Perstorp Holding AB |
| Eastman Chemical Company |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with indexed pricing mechanisms lock in both supply access and price visibility for agrochemical formulators sourcing from Ludwigshafen and Texas Gulf Coast producers, insulating qualified buyers from propylene volatility while cementing supplier dominance.
Pricing Analysis
After-sales technical service and re-qualification support drive lifetime value in pharmaceutical-grade supply relationships. Three-tier pricing structure across pharmaceutical, food-grade, and industrial specifications separates specification premiums from commodity spot levels. Cost compression in standard industrial grades is intensifying because bio-based propylene pathways and tolling arrangements erode fixed-cost advantages. Agrochemical formulators in Brazil and Australia exhibit the highest price sensitivity through consolidated procurement panels, while Swiss and Japanese pharmaceutical manufacturers absorb premiums for impurity profile consistency.
Supply Chain Analysis
Inventory cycles stretch 6-12 weeks for pharmaceutical-grade material due to CDSCO and FDA qualification documentation requirements. Geographic supply concentrates in Germany, the United States, and China, with captive propylene integration at Ludwigshafen and Texas Gulf Coast complexes anchoring merchant availability. Production draws from propylene feedstock, rhodium-phosphine catalysts, and synthesis gas inputs. Single-source vulnerability runs through concentrated hydroformylation capacity at Verbund sites. Distribution runs through direct mill relationships for multinational formulators and regional chemical distributors for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and re-qualification support represent the fastest-expanding revenue layer in pharmaceutical-grade supply, outpacing base chemical offtake as qualification timelines extend and regulatory documentation burdens intensify.
For Market Incumbents: Shield pharmaceutical-grade margin pools by deepening captive propylene integration and preemptively securing REACH-compliant carbon accounting documentation ahead of EU Green Deal procurement criteria. Bio-based propylene entrants and tolling operators threaten integrated cost structures. Certification investment in low-carbon intensity grades offers defensive positioning. For New Entrants and Emerging Players: CDSCO fast-track qualification for pharmaceutical-grade material unlocks white-space access at India's Dahej and Visakhapatnam chemical parks under PLI scheme incentives. Specialty gas-phase production for Japanese analytical applications offers penetrable premium tier. Direct e-commerce channels via Alibaba 1688 enable spot-market entry without distributor infrastructure. For Investors and Strategic Acquirers: Merchant specialists with pharmaceutical qualification expertise and established FDA inspection protocols present acquisition targets with durable moats. Long-term viability hinges on carbon intensity certification alignment with EU procurement scorecards. Watch for EU carbon border adjustment mechanism implementation timing as inflection signal for import-competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Ludwigshafen Verbund sites secure captive feedstock economics against merchant volatility. |
| Pharmaceutical-Grade Certification Investment | Rhodium-catalyzed production meets Swiss and Japanese impurity profile specifications. |
| Long-term Supply Agreement with Indexed Pricing | BASF and Celanese framework contracts lock volume commitments from Brazilian agrochemical formulators. |
| Green Manufacturing Transition | Bio-PDH pathways enable carbon-intensity reduction for EU Green Deal supplier scorecards. |
| Joint Venture in India Chemical Parks | Dahej and Visakhapatnam partnerships capture PLI scheme API manufacturing incentives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hydroformylation plant managers, procurement leads at agrochemical formulators, pharmaceutical technical directors, and distribution channel partners. Secondary validation drew from customs and trade data, ECHA REACH registration dossiers, SEC 10-K chemical segment disclosures, and MEE environmental compliance filings. Bottom-up capacity modeling and top-down consumption estimates were triangulated across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value by grade tier, end-use industry, regional production hub, and catalyst technology type. CAGRs were derived from trend extrapolation of feedstock cost differentials, regulatory compliance cost trajectories, and downstream demand elasticity patterns. Forecast inputs incorporated propylene supply concentration indices and pharmaceutical qualification timeline compression effects.
The analysis sits within stated boundaries; outcomes outside sustained propylene supply integration or accelerated carbon border adjustment implementation would require recalibration. Forecasts reflect documented assumptions regarding hydroformylation capacity utilization and REACH registration maintenance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Cobalt (II) Sulfate Market