
 Tributyl Phosphate Market | 2026-2036
Tributyl Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Tributyl Phosphate Market Outlook
High-purity solvent-grade specifications are redrawing competitive boundaries in the Tributyl Phosphate Market. LANXESS leverages backward integration into phosphate feedstocks to secure margin control across European supply chains. Eastman Chemical Company anchors North American demand through specialized distribution networks serving coatings and pharmaceutical end users. Guizhou Zerophos Chemical dominates cost-sensitive volume segments with integrated manufacturing bases in Guizhou province.
Tributyl Phosphate functions as a tri-n-butyl ester of phosphoric acid with the molecular formula C12H27O4P, operating across a boiling range of 289°C and serving primarily as an extraction solvent for rare earth elements and nuclear fuel reprocessing. The extractant segment leads value capture due to stringent purity requirements in nuclear and rare earth applications, while the plasticizer segment sustains volume throughput in PVC compounding despite regulatory pressure on organophosphate alternatives. Direct sales channels concentrate margin pools with large chemical processors, whereas distributor networks fragment pricing power across smaller agricultural and coatings formulators.
EPA oversight under the Toxic Substances Control Act and REACH registration through ECHA impose purity and handling standards that filter subscale suppliers from Western markets. China's MEE enforces wastewater discharge limits on phosphate ester manufacturers, elevating environmental compliance costs for domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent hazard classifications threaten to bifurcate product specifications and complicate cross-border trade in solvent and extractant grades.
Market Dynamics
REACH registration through ECHA and EPA oversight under the Toxic Substances Control Act are tightening purity thresholds for solvent-grade specifications, filtering subscale suppliers from Western markets while concentrating procurement among qualified chemical processors.
Growth Catalysts
- Rare earth extraction demand:Nuclear fuel reprocessing facilities and rare earth separation plants require high-purity extractant grades, pulling volume through specialized procurement channels.
- China's MEE wastewater standards:Environmental compliance elevation is consolidating domestic phosphate ester manufacturing, reducing supplier fragmentation and stabilizing feedstock availability for downstream chemical processors.
- PVC compounding resilience:Plasticizer-grade specifications sustain baseline volume despite regulatory pressure on organophosphate alternatives, anchoring throughput in construction and automotive end uses.
Market Restraints
- Phosphoric acid feedstock volatility:Input cost swings from phosphate rock mining concentration in Morocco and China compress margin predictability for non-integrated manufacturers.
- Substitution threat from bio-based plasticizers:Epoxidized soybean oil and citrate esters are displacing organophosphate alternatives in flexible PVC applications sensitive to regulatory hazard classification.
- REACH registration cost barriers:ECHA data requirements and substance evaluation timelines filter subscale European suppliers from solvent-grade segments, concentrating supply among backward-integrated multinationals.
Strategic Opportunities
- Battery electrolyte additive applications:Lithium-ion cell manufacturers are testing phosphate ester flame retardants and wetting agents, opening specification development contracts with specialty chemical suppliers.
- India's PLI scheme for specialty chemicals:Production-linked incentives for downstream chemical manufacturing are attracting greenfield investment in phosphates processing capacity.
- Direct sales channel expansion:Large chemical processors are consolidating procurement through long-term offtake agreements, bypassing distributor markups and capturing volume commitments.
Industry Challenges
- Phosphate process engineering talent scarcity:Specialized expertise in organophosphate synthesis and purification is concentrating among legacy manufacturers, constraining new entrant scale-up.
- Multi-jurisdiction hazard classification divergence:EPA, ECHA, and China's MEE maintain inconsistent toxicity endpoints, complicating product specification harmonization for cross-border solvent-grade trade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tributyl Phosphate Market |
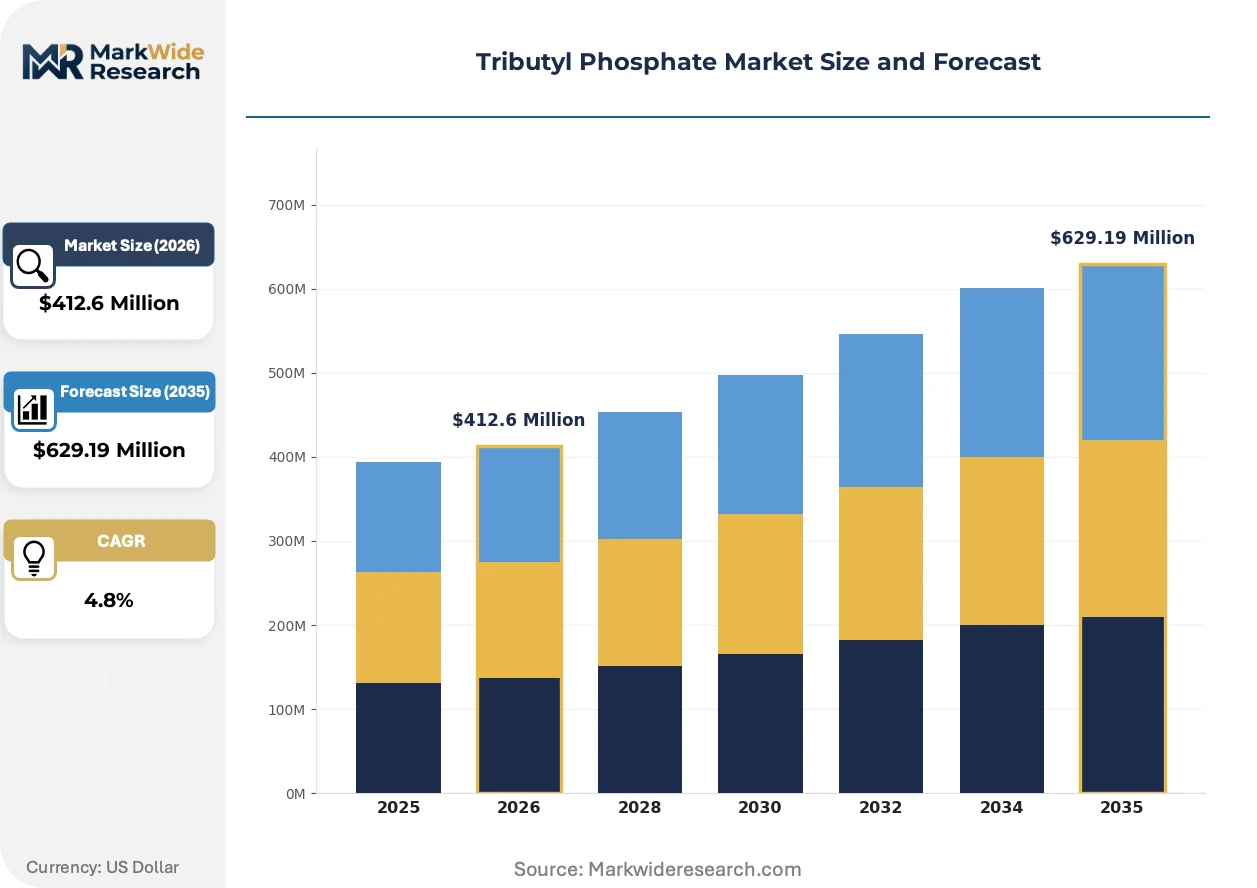
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Extractant, Plasticizer, Intermediate Application: Agriculture, Chemical Processing, Pharmaceuticals, Coatings End User: Agricultural Sector, Chemical Industry, Healthcare, Manufacturing Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | LANXESS, Eastman Chemical Company, Tokyo Chemical Industry, Solvay, Merck KGaA, Connect Chemicals GmbH, Guizhou Zerophos Chemical, Neostar United Industrial, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tributyl Phosphate Market Strategic Shifts
Continuous purification technologies and modular extraction unit designs are compressing capital requirements for rare earth separation facilities, while regulatory hazard reclassifications are forcing reformulation roadmaps across plasticizer applications.
Membrane-based solvent recovery systems are miniaturizing extraction loop footprints in rare earth processing facilities. Chinese nuclear fuel reprocessing plants are piloting these units to reduce tributyl phosphate inventory holding. The technology is miniaturizing on-site solvent regeneration capacity, displacing centralized recovery infrastructure and enabling distributed extraction architectures.
EPA's updated organophosphate hazard assessment under the Toxic Substances Control Act is triggering downstream notification requirements for plasticizer formulations. Coatings and adhesive manufacturers are accelerating substitution testing to preempt supply disruption. The regulatory pressure is compressing formulation development cycles and elevating certification costs for retained organophosphate applications.
Long-term offtake contracting is displacing spot procurement in rare earth extraction chemical supply. Large separation facilities in China and emerging projects in Australia are locking in multi-year solvent-grade supply commitments. This behavioral shift is concentrating pricing power among qualified manufacturers and fragmenting spot market liquidity for uncommitted volumes.
Tributyl Phosphate Market Segmentation
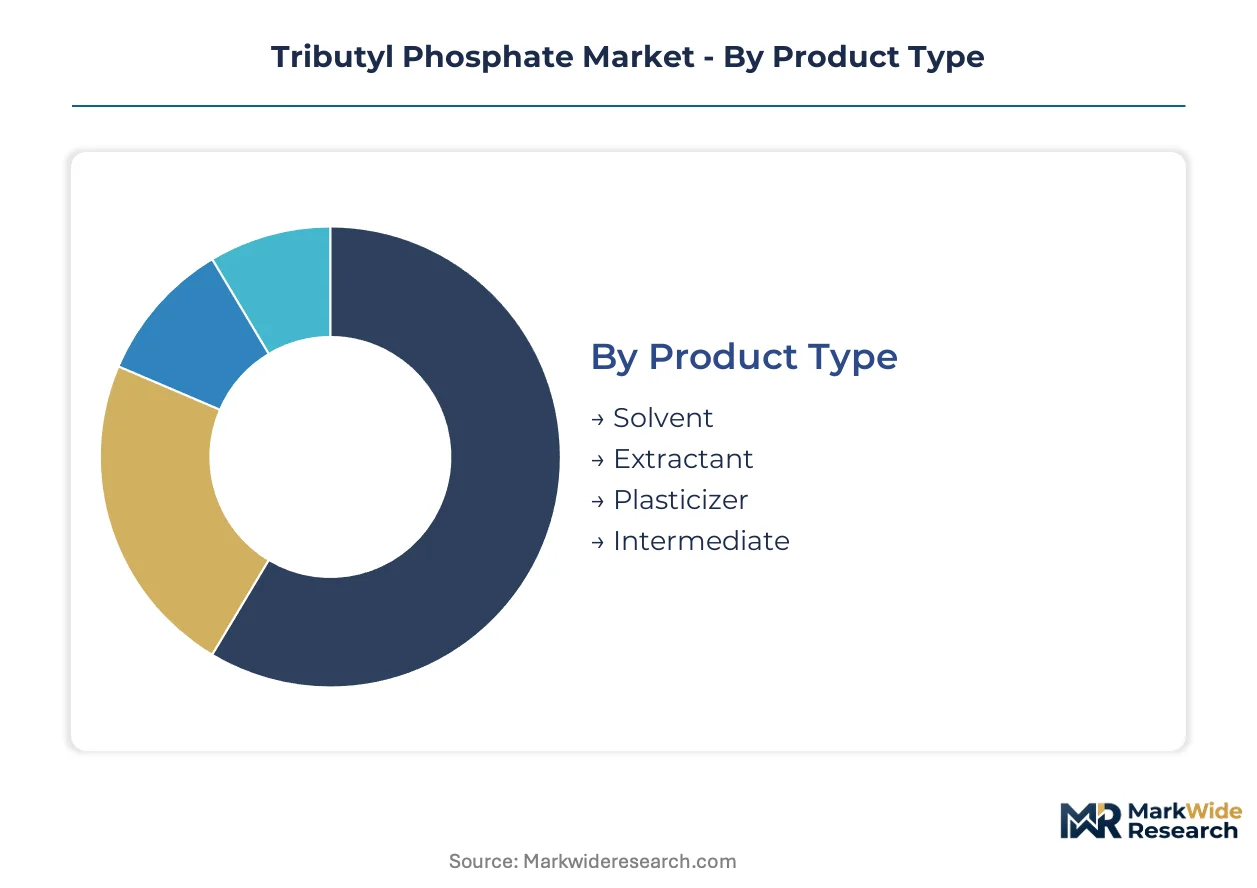
Tributyl phosphate applications diverge sharply in their vulnerability to substitution and regulatory reclassification. Segment boundaries are hardening around purity thresholds that separate qualified suppliers from commodity competitors.
Product Type:
Substitution pressure from bio-based alternatives and flame-retardant regulations hits plasticizer and intermediate grades hardest, while solvent and extractant specifications defend position through technical moats.
- Extractant:Nuclear fuel reprocessing and rare earth separation facilities demand ultra-high purity grades with sub-ppm contaminant limits. China's expanding reprocessing infrastructure and Australian rare earth projects pull volume through specialized procurement channels that filter unqualified suppliers.
- Solvent:Chemical processing applications require solvent-grade specifications with tight boiling range control around 289°C. REACH and EPA purity thresholds concentrate supply among backward-integrated manufacturers with captive phosphate feedstock security.
- Plasticizer:PVC compounding faces displacement from epoxidized soybean oil and citrate esters in hazard-sensitive applications.
- Intermediate:Downstream phosphate ester synthesis absorbs volume in agrochemical and flame-retardant manufacturing.
Plasticizer retains volume leadership; extractant holds the steepest expansion curve.
Application:
Margin capture stratifies across application tiers, with chemical processing commanding premium positioning while agricultural and coatings segments fragment pricing power.
- Chemical Processing:Rare earth extraction and nuclear reprocessing operations require certified solvent-grade supply with full regulatory documentation. Chinese separation plants and European reprocessing facilities anchor demand concentration.
- Pharmaceuticals:Drug manufacturing uses high-purity grades as extraction solvents and process aids. FDA and EMA quality standards elevate supplier qualification barriers.
- Agriculture:Pesticide formulation and fertilizer processing absorb standard-grade volumes through distributor networks.
- Coatings:Paint and adhesive manufacturers face EPA notification requirements under updated organophosphate hazard assessments.
Chemical processing commands the highest purity premiums; pharmaceuticals is climbing fastest on regulatory compliance spending.
End User:
Procurement consolidation patterns separate large chemical processors with direct sales relationships from fragmented smaller buyers dependent on distributor intermediaries.
- Chemical Industry:Integrated processors and specialty chemical manufacturers lock in multi-year offtake agreements for solvent and extractant grades. Chinese state-owned enterprises and Western multinationals dominate contract volumes.
- Healthcare:Pharmaceutical manufacturers and medical device producers require GMP-compliant supply chains with full batch traceability.
- Agricultural Sector:Crop protection formulators and fertilizer processors purchase through regional distributor networks with price-sensitive specifications.
- Manufacturing:Automotive and construction material producers consume plasticizer grades in flexible PVC applications.
Chemical industry dominates contract value; healthcare is expanding most quickly on quality certification requirements.
Distribution Channel:
Channel economics bifurcate between margin-rich direct relationships and high-volume distributor routes serving price-sensitive segments.
- Direct Sales:Large chemical processors and nuclear facilities negotiate long-term supply agreements bypassing intermediaries. Chinese rare earth separation plants and European reprocessing operators concentrate procurement through qualified manufacturer relationships.
- Distributors:Regional chemical distributors fragment pricing across agricultural and coatings formulators with smaller volume requirements.
- Online Retail:Specialty chemical marketplaces serve research laboratories and small-scale processors with catalog-grade specifications.
- Wholesalers:Bulk traders handle commodity-grade volumes for standard industrial applications with minimal technical support.
Direct sales captures the steepest margin expansion; online retail is gaining share fastest on e-procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate ester manufacturing clusters in Guizhou province and phosphate rock mining concentration in Morocco feed downstream Tributyl Phosphate production across three continents. Regulatory divergence between EPA, ECHA, and China's MEE is fragmenting product specifications and reshaping cross-border trade patterns.
China
Rare earth separation plants in Jiangxi and Inner Mongolia pull high-purity extractant grades through specialized procurement channels. The Ministry of Ecology and Environment enforces wastewater discharge limits that elevate environmental compliance costs for domestic phosphate ester manufacturers. Guizhou province hosts integrated manufacturing bases where captive phosphate feedstock supply secures cost positioning for volume-grade production.
United States
Nuclear fuel reprocessing facilities and specialty chemical processors anchor solvent-grade demand through qualified supplier relationships. EPA oversight under the Toxic Substances Control Act imposes purity thresholds that filter subscale suppliers from Western markets. The Gulf Coast chemical corridor concentrates downstream formulation capacity serving coatings and pharmaceutical end users.
Germany
REACH registration through ECHA and backward-integrated phosphate feedstock security position domestic manufacturers for premium solvent-grade segments. The country's national chemical regulator maintains stringent substance evaluation timelines that concentrate supply among qualified multinationals. The Rhine-Ruhr industrial region hosts specialized distribution networks serving European coatings and pharmaceutical formulators.
Japan
Electronics-grade phosphate ester demand from semiconductor and lithium-ion battery manufacturers pulls high-specification volumes through direct sales channels. METI industrial policy supports domestic specialty chemical manufacturing through supply chain resilience programs. The Kanto region around Tokyo concentrates pharmaceutical and electronic chemical processing facilities with GMP-compliant supply requirements.
Australia
Emerging rare earth separation projects in Western Australia and Queensland are locking in multi-year solvent-grade supply commitments with qualified manufacturers. The country's national environmental regulator imposes purity standards on extractant chemicals used in mining and mineral processing applications. Perth and Brisbane host project development offices for separation facilities targeting downstream integration into battery material supply chains.
Tributyl Phosphate Market Competitive Environment
Concentration sits with backward-integrated multinationals and regional phosphate specialists. The vendor base stratifies across three tiers: qualified suppliers with captive feedstock security, distributor-dependent regional formulators, and research-grade catalog providers. Dominant competitive moves include long-term offtake contracting with rare earth separation facilities and modular extraction unit technology licensing.
Within the integrated multinational tier, LANXESS and Eastman Chemical Company exemplify archetypes with phosphate feedstock control and specialized distribution networks. Among Asia-Pacific specialists, Guizhou Zerophos Chemical occupies a position representing cost-optimized volume production from integrated Guizhou province manufacturing bases. These three anchors illustrate the competitive divergence between premium solvent-grade qualification and commodity-scale positioning.
| Leading Market Players |
|---|
| LANXESS |
| Eastman Chemical Company |
| Tokyo Chemical Industry |
| Solvay |
| Merck KGaA |
| Connect Chemicals GmbH |
| Guizhou Zerophos Chemical |
| Neostar United Industrial |
| Tosoh Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at phosphate ester manufacturing clusters in Guizhou province anchors both supply concentration and price floors for solvent-grade specifications. REACH registration costs and EPA compliance thresholds erect barriers that filter subscale producers, concentrating procurement leverage among backward-integrated multinationals with captive feedstock security.
Pricing Analysis
REACH and EPA purity thresholds dictate the pricing tier structure across extractant, solvent, and plasticizer grades. Three-tier pricing structure across premium, standard, and economy levels separates nuclear-certified extractant supply from commodity plasticizer volumes. Price differentiation rests on certification grade and volume scale, with long-term offtake agreements commanding discounts against spot procurement. Cost compression in plasticizer tiers is intensifying because bio-based alternatives displace organophosphate formulations in hazard-sensitive PVC applications. Agricultural formulators through distributor networks exhibit highest price sensitivity, while nuclear reprocessing facilities prioritize qualification over cost.
Supply Chain Analysis
Strait of Malacca transit underwrites phosphate rock feedstock flows from Moroccan mining concentrations to Asian manufacturing hubs. Supply concentrates in China, Morocco, and Germany for phosphate rock mining, ester synthesis, and specialty distribution respectively. Raw material dependencies center on phosphoric acid, n-butanol, and catalyst chemicals for esterification processes. Single-source vulnerability from Moroccan phosphate rock concentration threatens margin predictability for non-integrated manufacturers. Distribution runs through direct sales channels for qualified chemical processors and regional distributor networks for fragmented agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for solvent regeneration and purification system maintenance expand faster than commodity chemical sales, creating recurring revenue attachment opportunities for qualified suppliers.
For Market Incumbents: Compound backward integration into phosphate feedstocks to secure margin control against phosphoric acid price volatility from Moroccan supply concentration. Expand certification maintenance services for nuclear reprocessing facilities to deepen switching costs. Bio-based plasticizer substitution in flexible PVC applications threatens volume retention in construction end uses. For New Entrants and Emerging Players: Aftermarket solvent recovery system servicing represents a service-layer gap where incumbents under-serve rare earth separation facilities in Australia and emerging markets. Target online retail channels for research-grade catalog specifications with minimal qualification barriers. Pursue modular extraction unit technology licensing as the go-to-market angle to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical manufacturers with REACH-qualified solvent-grade capabilities and established nuclear facility relationships. Long-term viability hinges on regulatory compliance moats widening as ECHA substance evaluation timelines extend. Watch for MEE wastewater enforcement intensity in Guizhou province as inflection indicator for Chinese domestic supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Feedstocks | Captive phosphoric acid supply from Moroccan or Guizhou sources insulates margin from input volatility. |
| Long-term Supply Agreement | Multi-year offtake contracts with Chinese rare earth separation plants lock in volume commitments and pricing power. |
| Green Manufacturing Transition | Membrane-based solvent recovery systems reduce wastewater discharge and satisfy MEE compliance thresholds. |
| Capacity Expansion | Modular extraction unit production for Australian rare earth projects captures emerging demand concentration. |
| Joint Venture | Technology licensing partnerships with battery electrolyte developers open specification development contracts. |
Study Parameters
Two parallel data streams informed the analysis: primary engagement with plant managers at phosphate ester manufacturing facilities, procurement leads at downstream chemical processors, distribution channel partners, and technical R&D directors; and secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical companies, and regulatory submissions to ECHA and EPA. Bottom-up volume triangulation from application-level consumption patterns cross-checked against top-down phosphate rock feedstock flow analysis.
Across the projection horizon, the analytical framework modeled grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs were derived from trend extrapolation of rare earth separation capacity buildouts, nuclear reprocessing infrastructure investment cycles, and PVC compounding demand patterns. Forecast inputs incorporated MEE wastewater enforcement trajectories and REACH registration renewal timelines.
Forecasts assume regulatory continuity in REACH, EPA TSCA, and MEE wastewater regimes; material policy shifts would require re-modeling purity threshold adjustments or hazard reclassifications. Practitioners should keep alternative scenarios live as bio-based plasticizer substitution rates and battery electrolyte additive qualification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Paint Stripper Market
Chemicals
5 Dinitroaniline Market
Chemicals
Global Thiophene Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
De-Icing Agents Market
Chemicals
Benzhydrol Market
Chemicals
Coagulant Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Malonic Acid Market
Chemicals
Sulfuric Acid Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Fluoroboric Acid Market
Chemicals
Calcium Carbide Market