
 Global Hexamethylenediamine Market | 2026-2036
Global Hexamethylenediamine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hexamethylenediamine Market Foresight
China's integrated chemical corridor is narrowing the historical supply deficit that previously defined Asian hexamethylenediamine procurement. BASF SE leverages its Ludwigshafen Verbund site to sustain captive adiponitrile conversion into polymer-grade material. Evonik Industries AG anchors its European position through specialized industrial-grade formulations for engineering resin customers. Ascend Performance Materials dominates the Americas supply base with backward integration into adiponitrile feedstock production.
Hexamethylenediamine is a linear aliphatic diamine with the formula H2N(CH2)6NH2, typically produced via catalytic hydrogenation of adiponitrile and serving as the essential co-monomer with adipic acid in nylon 6,6 polymerization. The liquid product type occupies the highest volume share due to its direct pipeline integration into continuous nylon polymerization reactors. Pharmaceutical-grade material commands premium positioning relative to industrial and technical grades, reflecting stringent impurity thresholds demanded by regulated medical applications. Nylon production as an application dimension absorbs the dominant share of global offtake, while coatings and surfactants represent specialized outlets with differentiated margin structures.
EPA industrial chemical oversight in the United States and REACH registration requirements under ECHA govern facility permitting, emissions thresholds, and substance characterization for hexamethylenediamine commerce across transatlantic corridors. China's MEE enforces wastewater and air emission standards at adiponitrile hydrogenation complexes along the eastern seaboard. Stakeholders must monitor regulatory divergence between jurisdictions as carbon-border adjustment mechanisms and chemical hazard reclassifications reshape cost structures for integrated producers.
Market Dynamics
Integrated adiponitrile-to-HMDA production corridors are compressing historical supply premiums by eliminating merchant market dependency for nylon 6,6 polymerization feedstock. Captive hydrogenation complexes now dictate regional pricing power across three continents.
Growth Catalysts
- Automotive lightweighting mandates:Under-hood nylon resin consumption accelerates in Germany and Japan as OEMs substitute metal with polymer-grade material for thermal management components.
- REACH purity escalation:ECHA registration requirements tighten industrial-grade specifications, forcing quality upgrades that favor integrated producers with in-house refining capabilities.
- Yangtze River Delta clustering:China's chemical corridor concentrates adiponitrile hydrogenation capacity adjacent to domestic nylon polymerization, reducing logistics exposure for regional offtake.
Market Restraints
- Adiponitrile feedstock volatility:Butadiene and acrylonitrile price swings transmit directly to HMDA cost structures, squeezing margin predictability for non-integrated converters.
- Americas supply concentration:Single-source dominance in North American adiponitrile creates vulnerability for polymer producers lacking alternative hydrogenation feedstock arrangements.
- Biobased diamine substitution:Sebacic acid-derived alternatives from castor oil feedstocks threaten technical-grade applications in coatings and surfactants.
Strategic Opportunities
- Pharmaceutical-grade white space:Medical device polymerization demands impurity thresholds below 50 ppm, commanding 3-4x industrial-grade pricing for qualified suppliers.
- India engineering resin buildout:PLI scheme incentives for domestic nylon capacity create first-mover advantage for adiponitrile hydrogenation joint ventures.
- Carbon-border adjustment positioning:EU CBAM implementation favors low-carbon hydrogenation routes, rewarding producers with renewable energy-integrated steam crackers.
Industry Challenges
- Specialized catalyst procurement:Raney nickel and noble metal hydrogenation catalysts face extended lead times from limited qualified suppliers, constraining capacity ramp schedules.
- Polymer-grade certification timelines:Automotive OEM qualification cycles for under-hood nylon components extend 18-24 months, freezing supplier switches regardless of cost competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hexamethylenediamine Market |
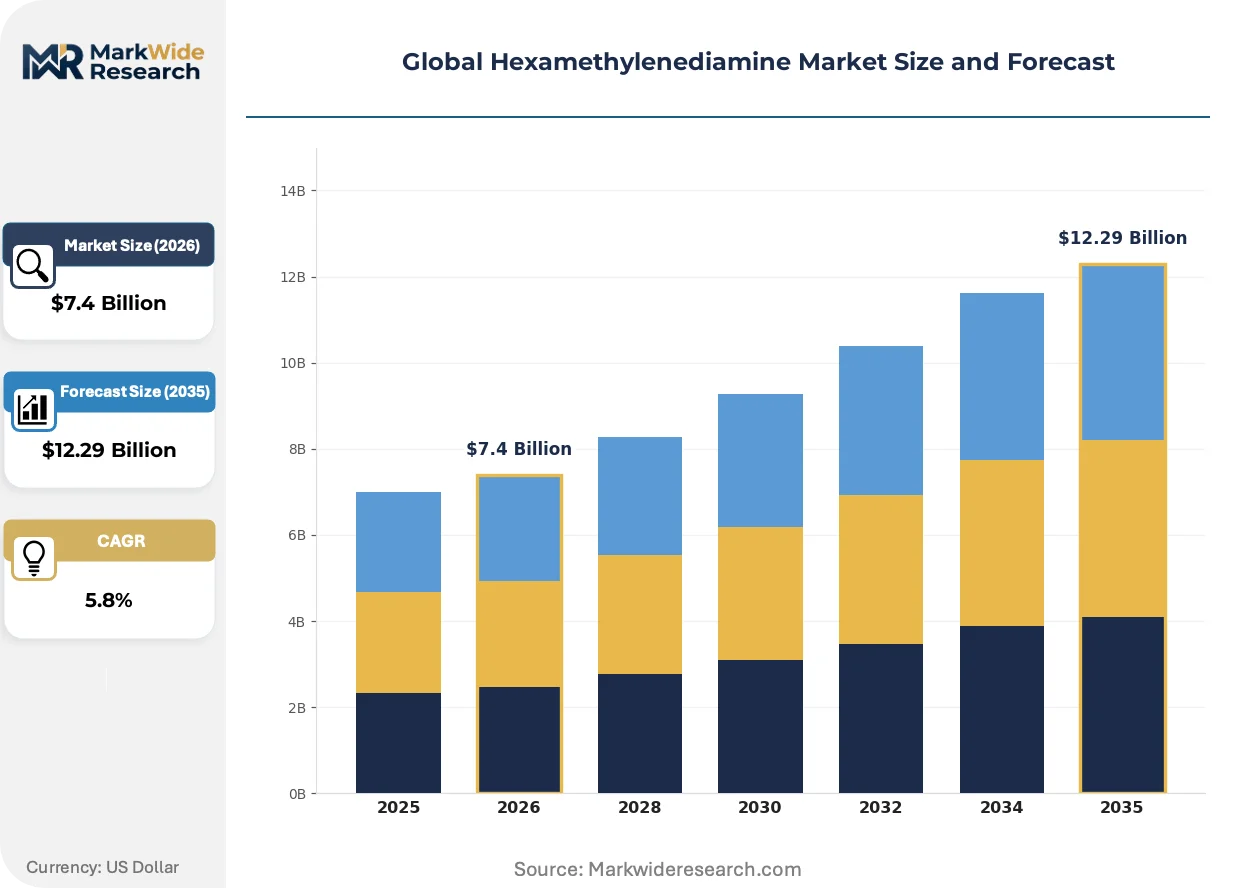
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Crystalline, Powder Grade: Industrial, Technical, Reagent, Pharmaceutical Application: ADS, Nylon Production, Agrochemicals, Surfactants, Coatings End User Industry: Textile Manufacturers, Chemical Producers, Polymer Fabricators, Plastic Molders |
| Companies Covered | BASF SE, Evonik Industries AG, Asahi Kasei Corporation, Merck KGaA, TORAY INDUSTRIES, INC., Ascend Performance Materials, DuPont de Nemours, Inc., INVISTA, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hexamethylenediamine Market Shifts & Advancements
Process intensification and regulatory chemistry are compressing the traditional merchant-market model for hexamethylenediamine, while end-use specifications fragment into application-specific purity tiers.
Membrane-based adiponitrile purification is hybridizing with conventional distillation sequences at integrated sites. European polymer producers adopt these hybrid trains to meet REACH-mandated impurity ceilings without yield sacrifice. The technology is hybridizing capital efficiency with regulatory compliance, collapsing the historical trade-off between throughput and specification attainment.
EU F-Gas Regulation phase-down schedules are accelerating ammonia-based cooling system retrofits at hydrogenation complexes. Industrial refrigeration dependent on high-GWP refrigerants faces compliance cliffs by 2030, forcing capex reallocations toward process-integrated heat recovery. German and Belgian facilities lead this transition, exploiting district heating infrastructure for energy export.
Specification-driven contracting now dominates pharmaceutical-grade procurement, displacing spot-market purchasing for regulated medical applications. Buyers consolidate qualified supplier lists to two or three sources, accepting premium pricing for audit-traceable batch documentation. Japan's PMDA and the US FDA drive this consolidation through polymer biocompatibility filing requirements.
Global Hexamethylenediamine Market Segmentation
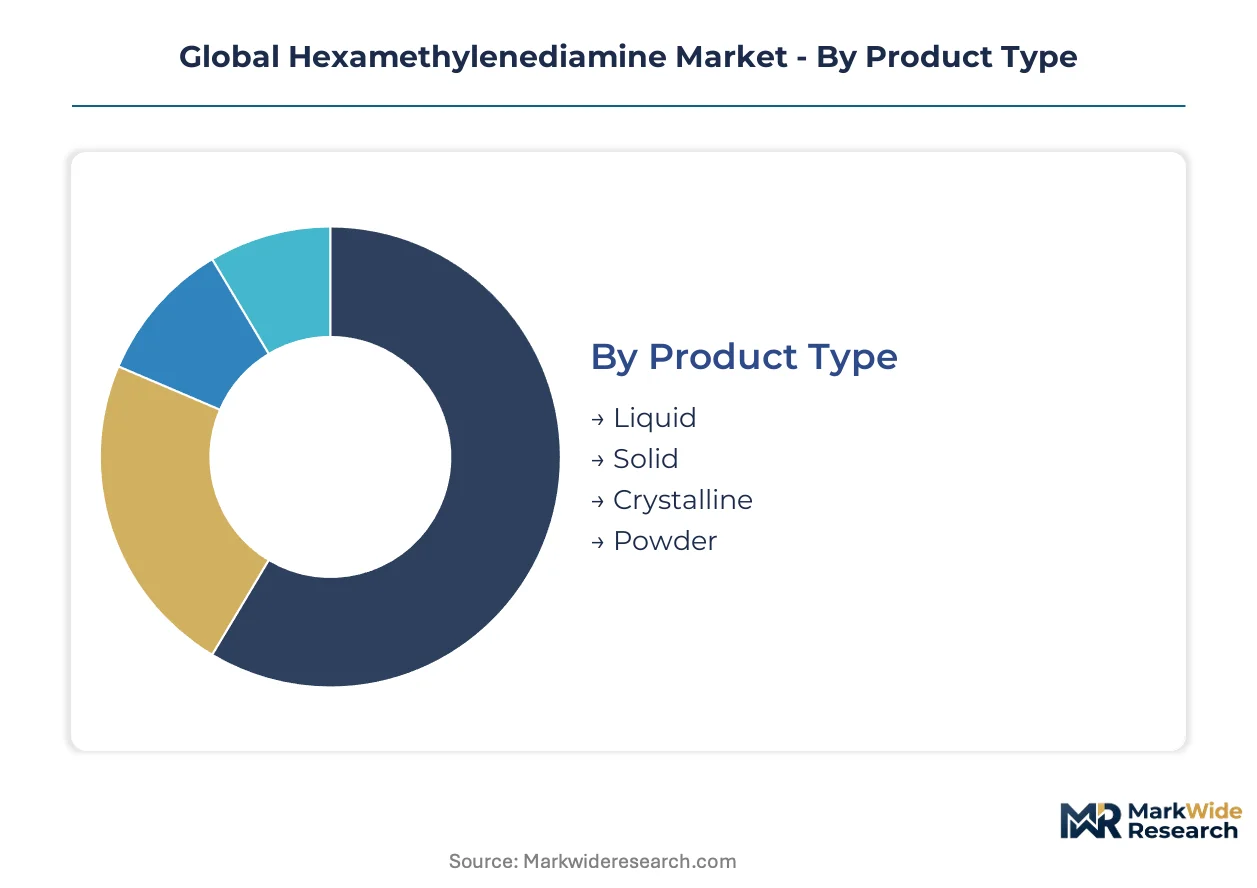
Hexamethylenediamine segmentation reflects the tension between commodity-scale nylon polymerization and specialized pharmaceutical-grade certification. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning across end-use verticals.
Product Type:
After-sales service intensity varies sharply across physical forms, with liquid handling demanding continuous technical support while solid variants shift liability to downstream processors.
- Liquid:Pipeline-delivered material dominates continuous nylon polymerization with direct reactor injection. Demand concentrates in China's Yangtze River Delta cluster, where integrated adiponitrile-to-HMDA plants eliminate intermediate storage and handling risks for domestic nylon producers.
- Solid:Flaked or pelletized product serves batch polymerization and specialty chemical synthesis requiring precise dosing control. German automotive compounders favor solid form for just-in-time delivery to dispersed compounding lines, accepting premium logistics costs for inventory flexibility.
- Crystalline:High-purity crystal structure supports pharmaceutical-grade applications with defined melting point specifications.
- Powder:Micronized material enables uniform dispersion in coatings and surfactant formulations.
Liquid holds the largest share; momentum sits with solid as regional polymerization diversifies beyond pipeline corridors.
Grade:
Cost tier stratification separates mass-market industrial material from certified pharmaceutical supply, with technical and reagent grades occupying intermediate price bands.
- Industrial:Standard purity material serves nylon 6,6 polymerization and general chemical synthesis with ppm-level impurity allowances. REACH registration requirements under ECHA tighten specifications progressively, forcing quality upgrades that favor integrated producers with in-house refining capabilities.
- Pharmaceutical:Impurity thresholds below 50 ppm command 3-4x industrial-grade pricing for medical device polymerization. Japan's PMDA and the US FDA drive supplier consolidation through biocompatibility filing requirements, limiting qualified sources to two or three per buyer.
- Technical:Mid-tier purity serves coatings and adhesives with performance specifications below pharmaceutical but above industrial baselines.
- Reagent:Laboratory-grade material supports analytical chemistry and research applications with batch-traceable documentation.
Industrial-grade volume dominates; pharmaceutical-grade expands most quickly as medical device polymerization accelerates.
Application:
Volume concentration in nylon polymerization creates margin pressure, while specialty applications retain pricing power through technical differentiation.
- Nylon Production:Co-monomer supply for polyamide 6,6 resin absorbs the dominant share of global offtake. Automotive lightweighting mandates in Germany and Japan accelerate under-hood component substitution, transmitting demand growth directly to polymer-grade HMDA procurement.
- ADS (Adipic Dihydrazide Synthesis):Cross-linking agent production for powder coatings and epoxy curing commands specialized logistics. European coating formulators prioritize ADS-grade material for low-VOC architectural finishes, aligning with EU Green Deal decarbonization targets.
- Agrochemicals:Intermediate for herbicide and fungicide synthesis with seasonal demand patterns.
- Surfactants:Cationic surfactant production for industrial cleaning and personal care applications.
- Coatings:Polyamide resin synthesis for corrosion-resistant industrial finishes.
Nylon production retains volume leadership; ADS climbs the fastest as powder coating substitution accelerates.
End User Industry:
Customer type fragmentation splits procurement between integrated chemical majors and specialized fabricators with divergent supply security requirements.
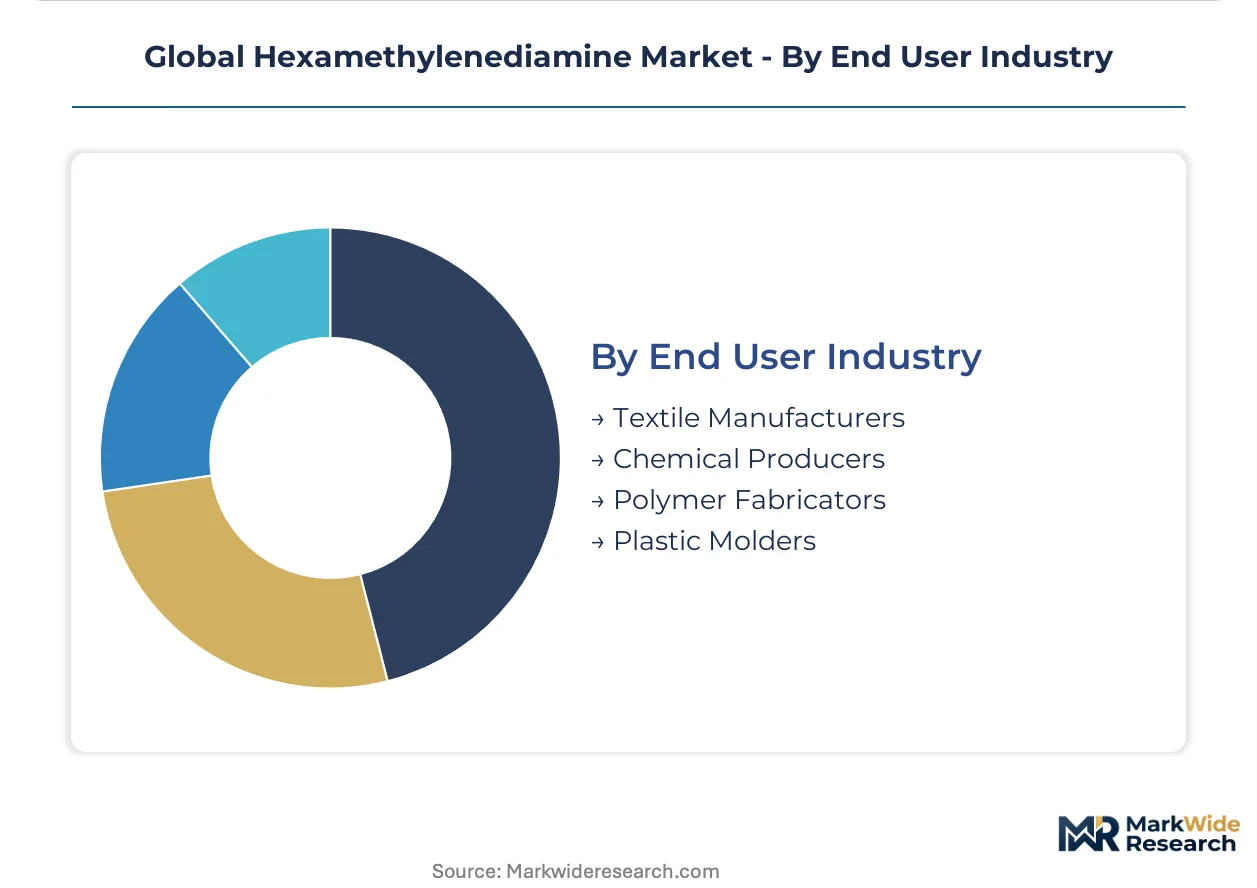
- Polymer Fabricators:Nylon resin producers with captive or toll-based polymerization capacity drive bulk procurement. India's PLI scheme incentives for domestic nylon capacity create first-mover advantage for adiponitrile hydrogenation joint ventures targeting this customer segment.
- Chemical Producers:Diversified intermediates manufacturers serving agrochemical and coating value chains. China's MEE wastewater enforcement at eastern seaboard hydrogenation complexes shapes supplier qualification criteria for this risk-sensitive buyer group.
- Textile Manufacturers:Fiber producers integrating polymerization with spinning operations.
- Plastic Molders:Injection molders of engineering resin components for automotive and electrical applications.
Polymer fabricators command the largest share; chemical producers gain share fastest as specialty application diversification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main pipeline corridor underwrites Germany's role as Europe's adiponitrile conversion hub, while China's Yangtze River Delta chemical cluster anchors Asia-Pacific hydrogenation capacity.
Germany
Automotive lightweighting programs at BMW and Mercedes-Benz accelerate polymer-grade consumption for under-hood thermal management components. ECHA REACH registration protocols tighten industrial-grade purity specifications progressively, favoring integrated producers with captive refining. BASF SE's Ludwigshafen Verbund site sustains adiponitrile-to-HMDA conversion adjacent to polymerization customers.
China
Domestic nylon 6,6 resin expansion by Invista and local polymer fabricators concentrates demand in the Yangtze River Delta. MEE wastewater enforcement at eastern seaboard hydrogenation complexes shapes supplier qualification criteria for chemical producers. Shanghai and Ningbo host integrated adiponitrile hydrogenation plants serving captive polymerization capacity.
United States
EPA industrial chemical oversight governs facility permitting and emissions thresholds for hydrogenation complexes along the Gulf Coast. Ascend Performance Materials dominates regional supply through backward integration into adiponitrile feedstock. Texas and Louisiana host the majority of North American hydrogenation capacity.
Japan
PMDA biocompatibility filing requirements drive supplier consolidation for pharmaceutical-grade procurement in medical device polymerization. Asahi Kasei Corporation and Toray Industries anchor domestic nylon resin production for automotive and electronics applications. The Kansai industrial corridor around Osaka concentrates specialty chemical synthesis.
India
PLI scheme incentives for domestic nylon capacity create first-mover advantage for adiponitrile hydrogenation joint ventures targeting engineering resin buildout. CDSCO pharmaceutical regulations govern medical-grade material import and qualification. Gujarat and Maharashtra host emerging polymer fabricator clusters seeking localized feedstock security.
Global Hexamethylenediamine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with differentiated margin structures. The vendor base organizes around three archetypes: integrated chemical majors with captive adiponitrile supply, specialized hydrogenation tollers serving merchant markets, and pharmaceutical-grade refiners targeting medical device polymerization. Consolidation pressures favor backward integration into feedstock production and geographic expansion through joint ventures in high-growth corridors.
Among European-based integrated producers, BASF SE and Evonik Industries AG exemplify the chemical major archetype with Verbund site economics and specialized industrial-grade formulations respectively. Ascend Performance Materials represents the Americas-anchored integrated model with upstream control over adiponitrile feedstock. These three companies occupy positions that span the value chain from raw material through polymer-grade certification.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Asahi Kasei Corporation |
| Merck KGaA |
| TORAY INDUSTRIES, INC. |
| Ascend Performance Materials |
| DuPont de Nemours, Inc. |
| INVISTA |
| Solvay |
| Others |
Supply & Pricing Matrix
Adiponitrile feedstock concentration in the United States Gulf Coast and China's Yangtze River Delta funnels pricing power toward integrated producers with captive hydrogenation capacity, squeezing merchant-market converters into thinner margin bands. Liquid product pipeline deliveries to continuous nylon polymerization reactors command stability premiums, while solid and crystalline grades absorb logistics volatility through inventory carrying costs.
Pricing Analysis
REACH registration protocols under ECHA dictate the pricing tier structure across European corridors, stratifying material into industrial, technical, and pharmaceutical grades with widening purity premiums. Certification-driven procurement for medical device polymerization under PMDA and FDA filings separates qualified suppliers from commodity converters, with audit-traceable batch documentation justifying substantial markups. Cost compression in industrial-grade material intensifies as China's integrated chemical corridor eliminates historical supply deficits, forcing non-integrated European tollers toward specialty formulations. Polymer fabricators with captive hydrogenation capacity exhibit lowest price sensitivity, while coating formulators and surfactant producers negotiate aggressively on volume scale.
Supply Chain Analysis
Export-control restrictions on advanced hydrogenation catalyst technology limit equipment flows to qualified suppliers in Germany, Japan, and the United States, constraining capacity expansion timelines for emerging producers. Geographic supply concentration centers on China, the United States, and Germany, with adiponitrile production anchored in Texas, Louisiana, and Ludwigshafen feeding downstream hydrogenation complexes. Raw material dependencies rest on butadiene and acrylonitrile feedstocks, plus Raney nickel and noble metal catalysts from limited qualified sources. Single-source vulnerability in North American adiponitrile supply creates structural exposure for polymer producers lacking alternative arrangements. Distribution runs through pipeline corridors to integrated polymerization sites, supplemented by bulk tanker and flaked solid logistics for batch processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern anchored to automotive production schedules, with OEM lightweighting programs in Germany and Japan transmitting demand pulses directly through nylon resin procurement channels.
For Market Incumbents: Pre-empt biobased diamine substitution threats by securing pharmaceutical-grade certification pathways before sebacic acid-derived alternatives capture technical-grade coating applications. Deepen backward integration into adiponitrile feedstock through joint ventures in India's PLI-subsidized corridor, locking in regional pricing power before merchant-market competitors establish tolling arrangements. For New Entrants and Emerging Players: India's underpenetrated engineering resin buildout offers the most accessible white-space target, with Gujarat and Maharashtra polymer fabricator clusters seeking localized feedstock security absent domestic hydrogenation capacity. Pharmaceutical-grade refining for medical device polymerization presents a second entry vector, exploiting supplier consolidation under PMDA and FDA biocompatibility requirements to capture 3-4x industrial-grade pricing. A go-to-market strategy anchored to CDSCO import qualification and domestic joint venture structuring accelerates market access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hydrogenation tollers in European merchant markets, where REACH compliance investments have strained balance sheets ahead of carbon-border adjustment implementation. Long-term viability over a multi-year window favors platforms with renewable energy-integrated steam crackers positioned for EU CBAM advantage. The signal to watch is automotive OEM qualification cycle completion, which unfreezes supplier switches and triggers consolidation windows regardless of underlying cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Captive feedstock supply eliminates merchant-market dependency and secures margin predictability for integrated producers. |
| Pharmaceutical-Grade Certification Investment | FDA and PMDA biocompatibility filings open medical device polymerization segments with 3-4x pricing premiums. |
| Joint Venture in India PLI Corridor | Domestic nylon capacity incentives create first-mover positioning for hydrogenation complexes serving Gujarat fabricators. |
| Renewable Energy-Integrated Steam Cracker | EU CBAM compliance favors low-carbon hydrogenation routes, rewarding producers with green power sourcing. |
| Long-Term Supply Agreement with Automotive OEM | 18-24 month qualification cycles freeze supplier relationships, making early contractual anchoring defensible. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at adiponitrile hydrogenation complexes, procurement leads at downstream nylon polymer fabricators, and technical R&D directors at coating formulators; plus secondary validation against customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical majors. Bottom-up capacity and utilization estimates triangulated with top-down demand segmentation across grade tiers, end-use industries, and regional production hubs.
Forecast inputs incorporated automotive lightweighting program timelines, REACH registration protocol phase-ins, and PLI scheme incentive structures without anchoring to specific calendar milestones. Segmentation dimensions spanned product form, purity grade, application vertical, and customer type, with CAGRs derived from elasticity modeling against feedstock price scenarios and capacity expansion announcements. Industry-specific inputs included butadiene and acrylonitrile price volatility patterns, catalyst lead time distributions, and OEM qualification cycle durations.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, energy price shocks, or trade policy shifts would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Material shifts in biobased diamine cost curves or carbon-border adjustment scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Global Cyclopentane Market