
 Electrolytic Etching Machine Market | 2026-2036
Electrolytic Etching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolytic Etching Machine Market Foresight
The price-performance gap between premium automated etching systems and entry-level manual units is hardening. Applied Materials leverages its semiconductor equipment heritage to dominate high-throughput pulse etching configurations for wafer-level packaging. Tokyo Electron Limited anchors its position through R&D intensity in high-frequency etching modules that address sub-micron precision requirements. NAURA Technology Group competes on manufacturing scale, sustaining cost advantages in continuous etching platforms for mid-tier PCB producers.
An electrolytic etching machine uses controlled electrochemical dissolution to selectively remove material from conductive substrates, typically operating with DC or pulse current densities between 5 and 50 A/dm² in acid or salt-based electrolyte baths. The equipment serves precision manufacturing by enabling burr-free patterning on metals and semiconductors without mechanical stress or thermal distortion. Automated etching systems command the largest installed base, while pulse etching technology captures the fastest expansion as miniaturization demands tighter sidewall control. Desktop etchers occupy a mature niche serving educational institutions and hobbyists, where margin pools remain thin due to standardized specifications and limited customization requirements.
The US EPA regulates wastewater discharge from etching operations under Clean Water Act permits, while the EU's REACH framework restricts hexavalent chromium and other electrolyte additives, forcing chemistry reformulation across the supply chain. China's MEE enforces dual carbon goals that raise energy efficiency standards for industrial etching equipment, particularly in the Yangtze River Delta manufacturing cluster. Stakeholders must monitor how evolving chemical compliance regimes in multiple jurisdictions reshape total cost of ownership and equipment replacement cycles.
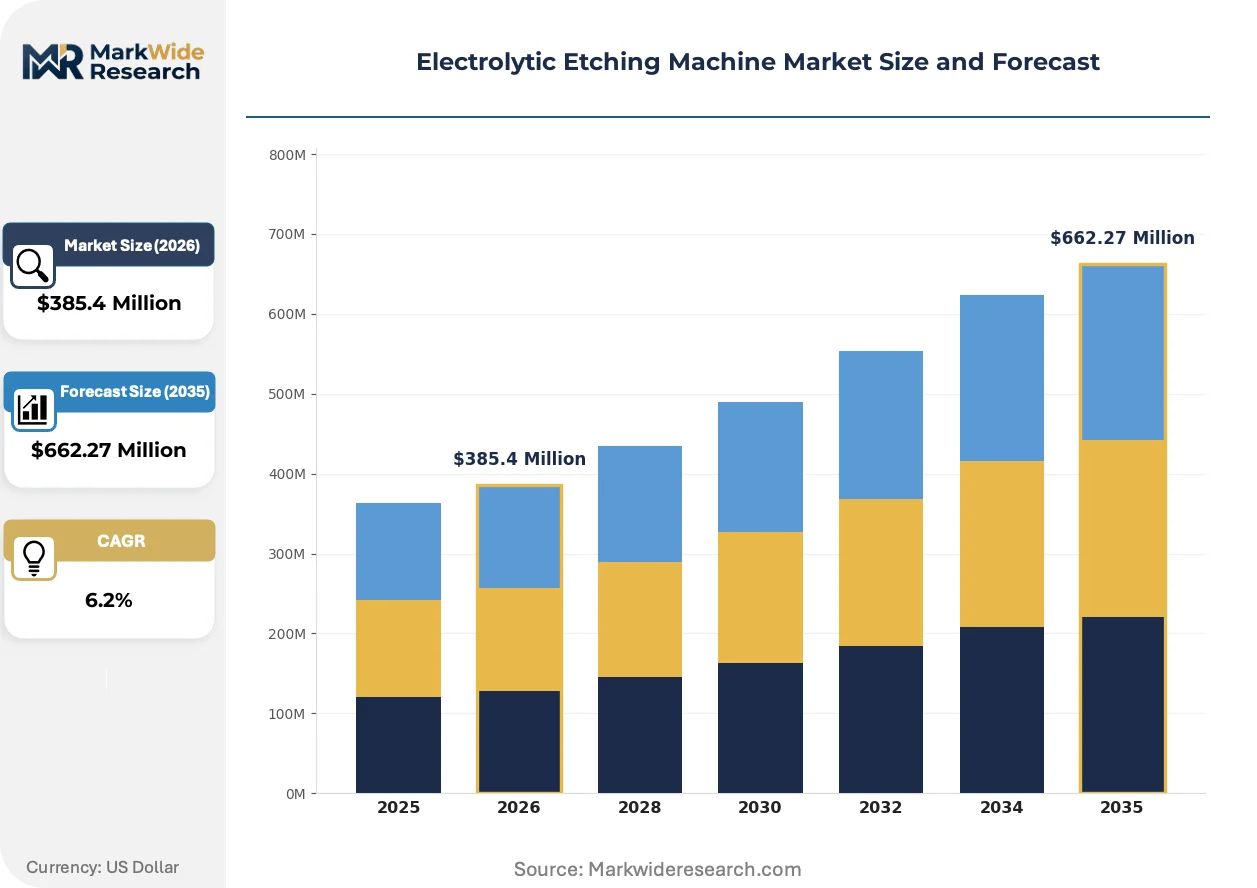
Market Dynamics
Pulse etching technology is compressing replacement cycles as semiconductor packaging demands sub-micron sidewall precision that legacy DC systems cannot deliver, forcing capital redeployment across East Asian fabrication clusters.
Growth Catalysts
- High-density interconnect PCB expansion:South Korea's semiconductor packaging corridor requires precision electrolytic processing for advanced substrate fabrication, pulling capacity investments from domestic equipment suppliers.
- EU RoHS compliance mandates:Hazardous substance limits on etching chemistry are accelerating wastewater system upgrades among European PCB producers seeking market access.
- China's dual carbon goals:Energy efficiency standards enforced by MEE in the Yangtze River Delta manufacturing cluster are stimulating demand for next-generation etching equipment with reduced power consumption profiles.
Market Restraints
- Electrolyte chemistry volatility:Hexavalent chromium substitution under REACH frameworks forces continuous reformulation, raising input costs and technical validation timelines for European manufacturers.
- Supply concentration in precision components:High-frequency etching module production clusters in Japanese and German industrial zones, creating vulnerability to regional disruption.
- Technical ceiling in pulse control:Current power electronics limit pulse frequency bandwidth, constraining etch uniformity below 0.5-micron feature sizes in high-volume production.
Strategic Opportunities
- Underpenetrated Indian PCB fabrication:PLI scheme incentives for electronics manufacturing are creating first-mover advantage for etching equipment suppliers establishing local service infrastructure.
- AI-driven process optimization:Machine learning integration with etching parameter control is enabling real-time chemistry adjustment, reducing waste and improving yield consistency.
- Vietnam electronics assembly migration:Contract manufacturers relocating from China are importing etching capacity requirements, opening greenfield installation opportunities outside established supply networks.
Industry Challenges
- Electrochemical process engineering talent scarcity:Specialized expertise in pulse waveform design and electrolyte bath chemistry is concentrated among aging workforces in Japan and Germany, constraining expansion timelines.
- Legacy DC system integration complexity:Retrofitting existing continuous etching lines with pulse modules requires custom mechanical redesign, extending commissioning periods and disrupting production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolytic Etching Machine Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Etching Machines, Automated Etching Systems, Manual Etching Devices, Desktop Etchers Technology: Pulse Etching, Continuous Etching, DC Etching, High-Frequency Etching Application: PCB Manufacturing, Metal Fabrication, Decorative Etching, Lab Use End User: Manufacturers, Hobbyists, Educational Institutions, Research Labs |
| Companies Covered | Applied Materials, Lam Research Corporation, Tokyo Electron Limited, Hitachi High-Tech Corporation, SAMCO Inc., ULVAC, NAURA Technology Group, Veeco Instruments, Advanced Micro-Fabrication Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolytic Etching Machine Market Shifts & Advancements
Electrolytic etching equipment is converging with digital process control and closed-loop chemistry management, transforming capital equipment into precision manufacturing platforms rather than standalone dissolution tools.
High-frequency pulse etching modules are integrating adaptive impedance matching to maintain constant current density across varying substrate geometries. Advanced packaging facilities in South Korea and Taiwan are deploying these systems for wafer-level redistribution layer fabrication. The technology is integrating machine vision feedback loops that adjust pulse parameters in real-time, compressing process development cycles from weeks to days.
REACH restrictions on hexavalent chromium and PFAS-containing wetting agents are forcing electrolyte formulation shifts across European etching operations. ECHA substance evaluation timelines are accelerating substitution mandates, pushing equipment manufacturers to validate alternative chemistry sets. PCB producers in Germany and the Netherlands are responding by qualifying acid-salt hybrid electrolytes that demand modified anode materials and tank linings.
Buyer consolidation among tier-one PCB and semiconductor packaging houses is concentrating procurement leverage, displacing fragmented distributor networks with direct OEM relationships. Large-scale manufacturers in China's Pearl River Delta are negotiating multi-site service agreements that bundle equipment, consumables, and predictive maintenance. This pattern is most visible in substrate fabrication, where single buyers account for substantial annual etching capacity additions.
Electrolytic Etching Machine Market Segmentation
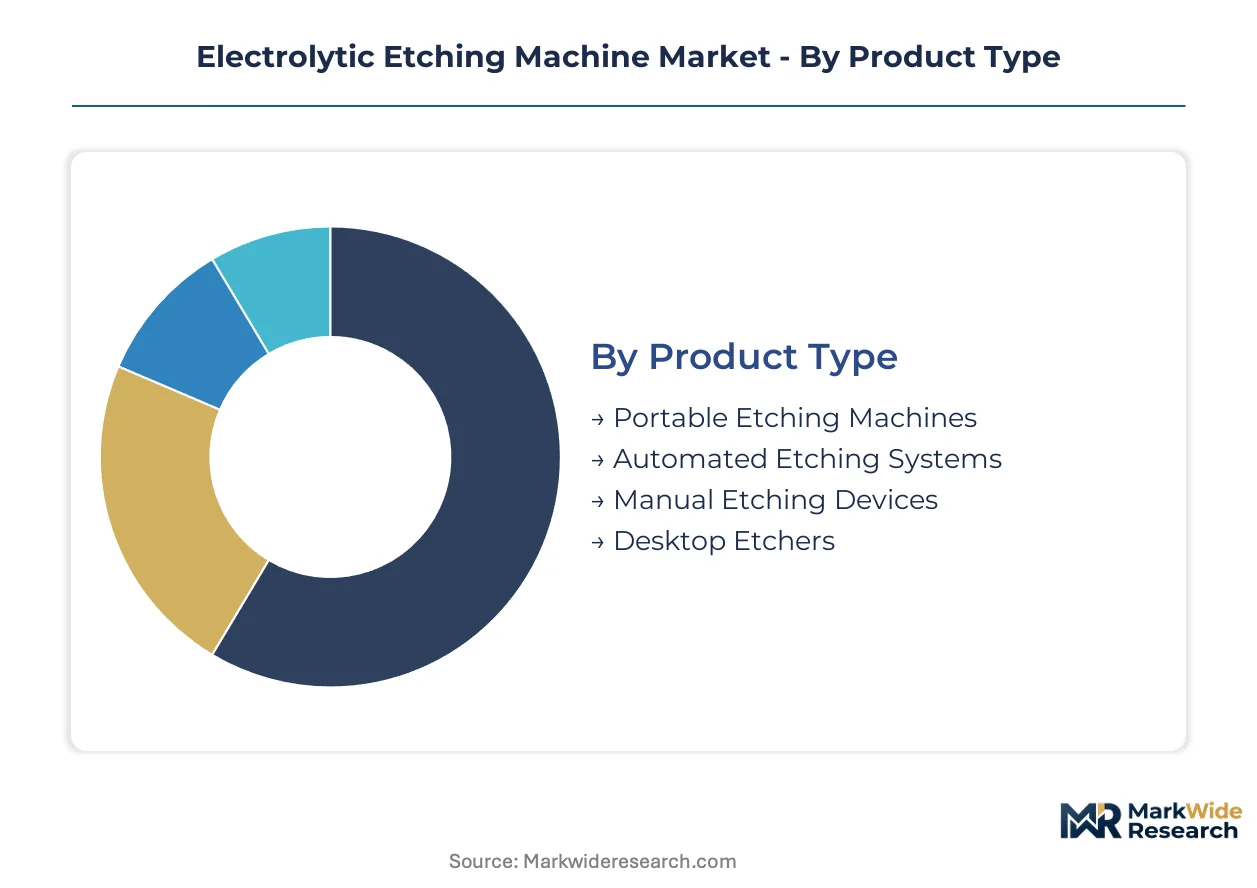
Electrolytic etching equipment segments diverge sharply by capital intensity, precision requirements, and regulatory exposure. Buyers select across these dimensions based on substrate complexity, throughput needs, and chemistry compliance obligations in their operating jurisdictions.
Product Type:
Capital deployment scale and operator skill requirements separate buyers across this category.
- Automated Etching Systems:These units integrate conveyor mechanics with closed-loop chemistry management for high-throughput PCB fabrication. Demand concentrates among South Korean semiconductor packaging houses where MEE carbon efficiency mandates favor reduced manual handling and optimized power profiles.
- Portable Etching Machines:Mobile units with compact electrolyte reservoirs enable on-site metal marking and repair operations. Field service contractors in Germany's industrial maintenance sector deploy these for REACH-compliant hexavalent chromium-free etching at customer facilities.
- Manual Etching Devices:Hand-operated systems with basic DC power supplies serve low-volume patterning needs.
- Desktop Etchers:Benchtop units with standardized 5-10 liter tanks occupy educational and hobbyist applications.
Volume sits with Automated Etching Systems; growth tilts toward Portable Etching Machines.
Technology:
Pulse frequency capabilities and current control architectures define performance tiers in this category.
- Pulse Etching:Modulated current delivery with microsecond waveform control achieves sub-micron sidewall precision for advanced packaging substrates. Taiwan's wafer-level redistribution layer fabricators drive capacity expansion as legacy DC systems fail to meet miniaturization tolerances.
- High-Frequency Etching:Adaptive impedance matching maintains constant current density across varying substrate geometries. Japanese equipment suppliers concentrate production of these modules, creating supply vulnerability for European PCB producers.
- Continuous Etching:Steady-state DC operation with conveyor-fed substrates dominates mid-tier PCB volume production.
- DC Etching:Basic direct current dissolution remains entrenched in metal fabrication and decorative applications.
Continuous Etching carries the largest installed base; Pulse Etching expands most quickly.
Application:
Substrate material and pattern complexity determine equipment specification requirements.
- PCB Manufacturing:Multi-layer high-density interconnect fabrication demands precision sidewall control and chemistry consistency. China's Yangtze River Delta cluster drives capacity additions as GB industrial equipment safety standards tighten wastewater system requirements.
- Metal Fabrication:Structural steel and aluminum etching for aerospace and automotive components prioritizes throughput over micron-scale precision. German automotive suppliers qualify acid-salt hybrid electrolytes under ECHA substitution timelines.
- Decorative Etching:Artistic surface patterning on jewelry and architectural metals employs lower-current systems.
- Lab Use:Research prototyping requires flexible parameter adjustment for experimental chemistry validation.
Metal Fabrication holds steady volume; PCB Manufacturing climbs the fastest.
End User:
Technical expertise depth and procurement scale separate demand profiles in this category.
- Manufacturers:Tier-one PCB and semiconductor packaging houses negotiate multi-site service agreements bundling equipment, consumables, and predictive maintenance. China's Pearl River Delta substrate fabricators account for substantial annual capacity additions through direct OEM relationships.
- Research Labs:Academic and corporate R&D facilities require pulse waveform programmability for process development. South Korean national laboratories deploy high-frequency modules for next-generation substrate technology evaluation.
- Educational Institutions:Technical training programs utilize standardized desktop units with limited customization.
- Hobbyists:Individual makers pursue decorative and small-scale fabrication with entry-level manual systems.
Manufacturers dominate procurement volume; Research Labs show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing cluster anchors electrolytic etching equipment demand, with Shanghai and Suzhou hosting the densest concentration of PCB substrate fabrication facilities.
China
MEE dual carbon goals are accelerating equipment replacement in Jiangsu and Zhejiang provinces. GB industrial equipment safety standards now mandate closed-loop wastewater systems for new etching line installations. The Pearl River Delta substrate fabricators in Shenzhen and Dongguan negotiate multi-site service agreements bundling equipment and predictive maintenance.
South Korea
Semiconductor packaging corridors in Gyeonggi Province require pulse etching systems for wafer-level redistribution layer fabrication. The country's national laboratories deploy high-frequency modules for next-generation substrate technology evaluation. Busan-Ulsan manufacturing clusters are expanding electrolytic capacity for advanced memory packaging substrates.
United States
EPA Clean Water Act permits regulate wastewater discharge from etching operations in California and Arizona semiconductor packaging facilities. Arizona's Phoenix metro area attracts substrate fabricators relocating from East Asian supply chains. Texas Instruments and Intel expansion in the Southwest is pulling capital equipment procurement toward pulse etching configurations.
Germany
ECHA REACH restrictions on hexavalent chromium are forcing electrolyte reformulation across Bavarian and North Rhine-Westphalia PCB producers. Acid-salt hybrid electrolytes now require modified anode materials and tank linings. Stuttgart automotive suppliers qualify these alternative chemistries under accelerated substitution timelines.
Japan
METI energy efficiency standards concentrate high-frequency etching module production in Nagoya and Osaka industrial zones. Japanese equipment suppliers anchor supply for sub-micron precision requirements. Chubu region fabricators face supply vulnerability as module production clusters tightly in these historic manufacturing centers.
Electrolytic Etching Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and precision capability. The market structures into three tiers: semiconductor heritage equipment suppliers commanding pulse etching configurations, industrial-scale continuous etching platform manufacturers, and regional specialists serving mid-tier PCB producers. Consolidation pressure concentrates among East Asian fabrication clusters where buyer procurement leverage is tightening. Competitive moves center on R&D intensity in high-frequency module development and multi-site service agreement bundling.
Within the semiconductor heritage tier, Applied Materials and Tokyo Electron Limited exemplify premium-positioned archetypes with deep process technology integration. Lam Research Corporation occupies a position bridging semiconductor and advanced packaging applications. Among China-based scale manufacturers, NAURA Technology Group represents the cost-optimized continuous etching platform segment. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across precision versus throughput market segments.
| Leading Market Players |
|---|
| Applied Materials |
| Lam Research Corporation |
| Tokyo Electron Limited |
| Hitachi High-Tech Corporation |
| SAMCO Inc. |
| ULVAC |
| NAURA Technology Group |
| Veeco Instruments |
| Advanced Micro-Fabrication Equipment |
| Others |
Supply & Pricing Matrix
Multi-site service agreements bundling equipment, consumables, and predictive maintenance are compressing margins for standalone equipment vendors and forcing supply chain consolidation around integrated service platforms capable of delivering chemistry management alongside hardware.
Pricing Analysis
Yield guarantees and uptime commitments anchor value-based pricing for pulse etching configurations serving advanced packaging substrates. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor heritage suppliers from mid-tier continuous etching manufacturers and entry-level manual equipment producers. Cost compression in the standard tier intensifies because NAURA Technology Group leverages manufacturing scale advantages. Hobbyists and educational institutions exhibit highest price sensitivity, while tier-one semiconductor packaging houses prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
High-frequency etching module production rests on Japanese and German industrial zones, creating geographic concentration risk for European and East Asian PCB producers. Precision power electronics, specialty anode materials, and acid-salt hybrid electrolytes draw from concentrated specialty chemical suppliers. Single-source vulnerability in adaptive impedance matching components threatens fabrication timelines. Distribution runs through direct OEM relationships displacing fragmented distributor networks among large-scale substrate manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrolytic etching machine market operates as a cost-of-compliance story where ECHA REACH restrictions on hexavalent chromium create barrier-to-entry moats for equipment suppliers with validated alternative chemistry sets and modified tank lining capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into electrolyte formulation capabilities and captive supply of high-frequency module components. Applied Materials and Tokyo Electron Limited should deepen R&D intensity in adaptive impedance matching to defend against emerging Chinese scale manufacturers. Certification investment for acid-salt hybrid chemistry validation represents the critical lever for sustaining European market access. For New Entrants and Emerging Players: India's PLI scheme incentives for electronics manufacturing open a window for portable etching machine suppliers establishing local service infrastructure before incumbent footprint solidification. Vietnam's electronics assembly migration presents greenfield installation opportunities outside established Japanese supply networks. A service-first go-to-market angle bundling predictive maintenance with equipment sales penetrates cost-conscious contract manufacturers relocating from China. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive electrolyte chemistry capabilities and validated REACH-compliant formulation portfolios. Pulse etching technology suppliers serving wafer-level redistribution layer fabrication exhibit strongest long-term viability framing. Watch ECHA substance evaluation acceleration timelines as inflection indicator for equipment replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Chemistry | Captive formulation capabilities insulate margins from ECHA substitution mandate volatility. |
| High-Frequency Module R&D Expansion | Adaptive impedance matching investment addresses sub-micron precision requirements in South Korean packaging corridors. |
| Multi-Site Service Agreement Bundling | Pearl River Delta substrate fabricators consolidate procurement leverage through integrated equipment-consumables-maintenance contracts. |
| Greenfield Installation in Vietnam | Contract manufacturer relocation from China creates first-mover advantage outside established supply networks. |
| AI-Driven Process Optimization Integration | Machine learning parameter control reduces waste and improves yield consistency for MEE carbon efficiency compliance. |
Research Methodology
Document review covered SEC 10-K filings, ECHA substance evaluation databases, and MEE enforcement circulars, complemented by interviews with plant engineers at PCB fabrication facilities, procurement leads at semiconductor packaging houses, aftermarket service heads, and technical R&D directors at electrolyte chemistry suppliers. Bottom-up and top-down triangulation validated equipment shipment data against capacity expansion announcements across the Yangtze River Delta and Gyeonggi Province manufacturing clusters.
Historical equipment replacement patterns were cross-referenced against panel input from industry stakeholders to construct the analytical framework across the analysis window. Segmentation dimensions modeled include technology type, application substrate complexity, end-user procurement scale, and regional regulatory cluster. CAGRs were derived through regression analysis of capital expenditure trends and chemistry compliance cost trajectories. Forecast inputs incorporated MEE dual carbon goal enforcement intensity and ECHA substitution timeline acceleration scenarios.
The model assumes a particular technology adoption path favoring pulse etching module deployment; alternative pathways for legacy DC system retrofit integration would alter the outlook through extended commissioning periods and disrupted production schedules. Forecasts reflect assumptions regarding REACH restriction implementation speed and hexavalent chromium substitution validation timelines. A small set of named triggers—ECHA substance evaluation acceleration, MEE carbon efficiency standard tightening, and high-frequency module supply disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market