
 SMT Reflow Soldering Equipment Market | 2026-2036
SMT Reflow Soldering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
SMT Reflow Soldering Equipment Market Analytics
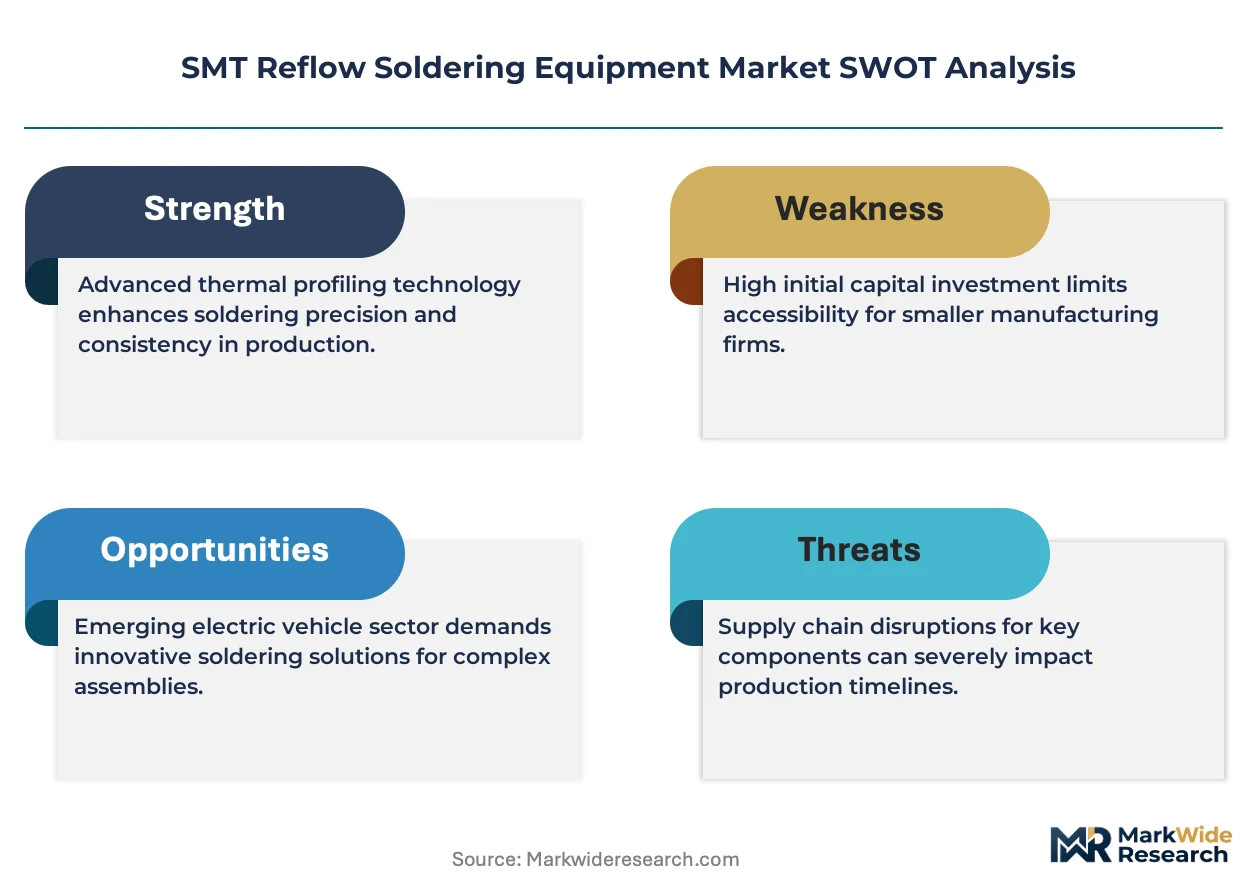
REACH compliance is recalibrating the cost-of-entry calculus for European equipment vendors by mandating restricted substance documentation across solder paste chemistries and thermal process byproducts. Kurtz Ersa leverages its German engineering base to sustain premium positioning in convection reflow systems for automotive tier-one suppliers. Heller Industries anchors North American demand through extensive service infrastructure and localized thermal process expertise. Senju Metal Industry Co., Ltd. competes on integrated solder material-to-equipment workflows that reduce customer process variability.
SMT reflow soldering equipment comprises automated thermal processing systems that heat printed circuit boards through controlled temperature zones to melt solder paste and form permanent electrical connections, typically operating across profiles ranging from 150°C preheat to 250°C peak with conveyor speeds adjustable to 1.5 meters per minute. Inline systems dominate volume deployment in high-throughput electronics manufacturing, while vapor phase technology captures premium margins in medical device and aerospace applications demanding oxygen-free thermal environments. Contract manufacturers represent the fastest-growing end user segment as EMS providers expand capacity to serve fabless semiconductor and IoT device designers.
FDA medical device quality system regulations and EU MDR conformity requirements shape equipment validation protocols, forcing vendors to supply documented thermal profile repeatability and process traceability. China's GB standards and MIIT industrial equipment directives establish electromagnetic compatibility and energy efficiency benchmarks that determine market access for imported reflow ovens. Stakeholders must monitor evolving solder alloy compositions driven by RoHS substance restrictions and anticipate thermal profile adjustments as lead-free and low-temperature solder formulations gain process share.
Market Dynamics
Electric vehicle powertrain electrification is compressing thermal profile tolerances to ±2°C across multi-zone reflow systems as battery management modules demand solder joint reliability under thermal cycling stress.
Growth Catalysts
- EU F-Gas Regulation:Equipment replacement cycles accelerate as fluorinated greenhouse gas restrictions force manufacturers to retire legacy thermal systems and adopt nitrogen-based convection technologies.
- EV battery management systems:Automotive tier-one suppliers expand SMT line capacity for power electronics assemblies requiring high-thermal-mass board processing capabilities.
- Low-temperature solder formulations:Lead-free alloy innovations below 180°C peak temperatures reduce energy consumption while maintaining joint integrity for temperature-sensitive substrates.
Market Restraints
- Nitrogen supply concentration:Bulk gas infrastructure bottlenecks in industrial zones outside Germany and China inflate operating costs for oxygen-free reflow environments.
- REACH documentation burden:Substance of very high concern declarations across solder paste flux chemistries extend equipment qualification timelines by 4-8 months for European vendors.
- Vapor phase equipment cost structure:Perfluoropolymer working fluid prices and sealed system maintenance requirements limit adoption outside medical device and aerospace certification tiers.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor packaging and EMS operations create first-mover advantage for reflow oven vendors establishing local service infrastructure.
- Dual carbon policy alignment:China's MIIT energy efficiency benchmarks favor thermal recovery system adoption, opening upgrade revenue streams among domestic contract manufacturers.
- AI-driven predictive maintenance:Machine learning integration with thermal profiling software enables outcome-based service contracts displacing traditional break-fix arrangements.
Industry Challenges
- Thermal process engineer scarcity:Specialized expertise in multi-zone profile optimization for heterogeneous component boards commands 40% wage premiums in Shenzhen and Detroit manufacturing clusters.
- FDA 21 CFR Part 820 validation:Medical device manufacturers require documented thermal profile repeatability studies extending equipment commissioning timelines for qualified system deployments.
- Legacy ERP integration:MES connectivity protocols vary across semiconductor fabs and EMS providers, complicating Industry 4.0 data architecture standardization for smart reflow oven deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SMT Reflow Soldering Equipment Market |
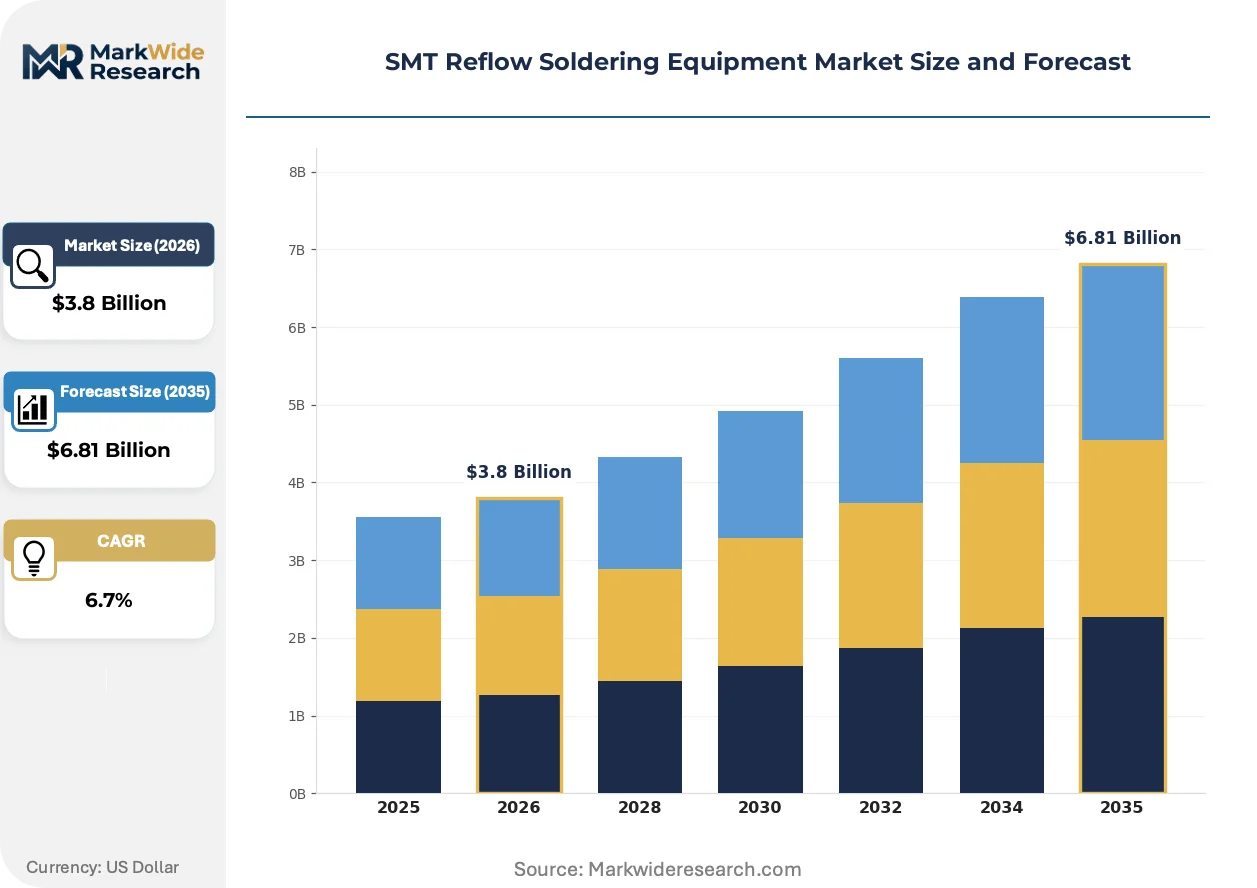
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch, Inline, Hybrid, Desktop Application: Consumer Electronics, Automotive Electronics, Industrial Electronics, Medical Devices Technology: Convection, IR, Laser, Vapor Phase End User: OEMs, Contract Manufacturers, Repair Services, Prototyping Houses |
| Companies Covered | DDM Novastar Inc., Kurtz Ersa, AUTOTRONIK-SMT GMBH, UniTemp GmbH, Tamura Corporation, Intek Corp., Senju Metal Industry Co., Ltd., Heller Industries, Madell Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SMT Reflow Soldering Equipment Market Evolving Landscape
Reflow soldering technology is converging with advanced process control systems as thermal profiling digitization and real-time adjustment algorithms compress defect rates and energy consumption simultaneously.
Closed-loop thermal management systems are automating zone-by-zone temperature correction through infrared pyrometer feedback and adaptive conveyor speed modulation. Automotive electronics manufacturers in Stuttgart and Shanghai deploy these systems for power module assemblies where thermal gradient control determines solder joint fatigue life. The technology is automating quality assurance labor while reducing nitrogen consumption through precision atmosphere control.
Europe's F-Gas Regulation mandates equipment phase-out timelines for thermal processes utilizing fluorinated gases above specified global warming potential thresholds. Industrial oven operators face capital expenditure decisions between retrofitting existing convection systems or full replacement with nitrogen-inerted alternatives. Medical device manufacturers in Ireland and Switzerland accelerate compliance timelines to maintain MDR conformity certification validity.
Contract manufacturers are consolidating equipment procurement under multi-site framework agreements with standardized thermal process specifications. EMS providers serving fabless semiconductor designers in Taiwan and California negotiate master service contracts bundling equipment, consumables, and predictive maintenance across regional facility networks. This concentration is visible most acutely in Shenzhen where top-five EMS operators control 60% of new SMT line investments.
SMT Reflow Soldering Equipment Market Segmentation
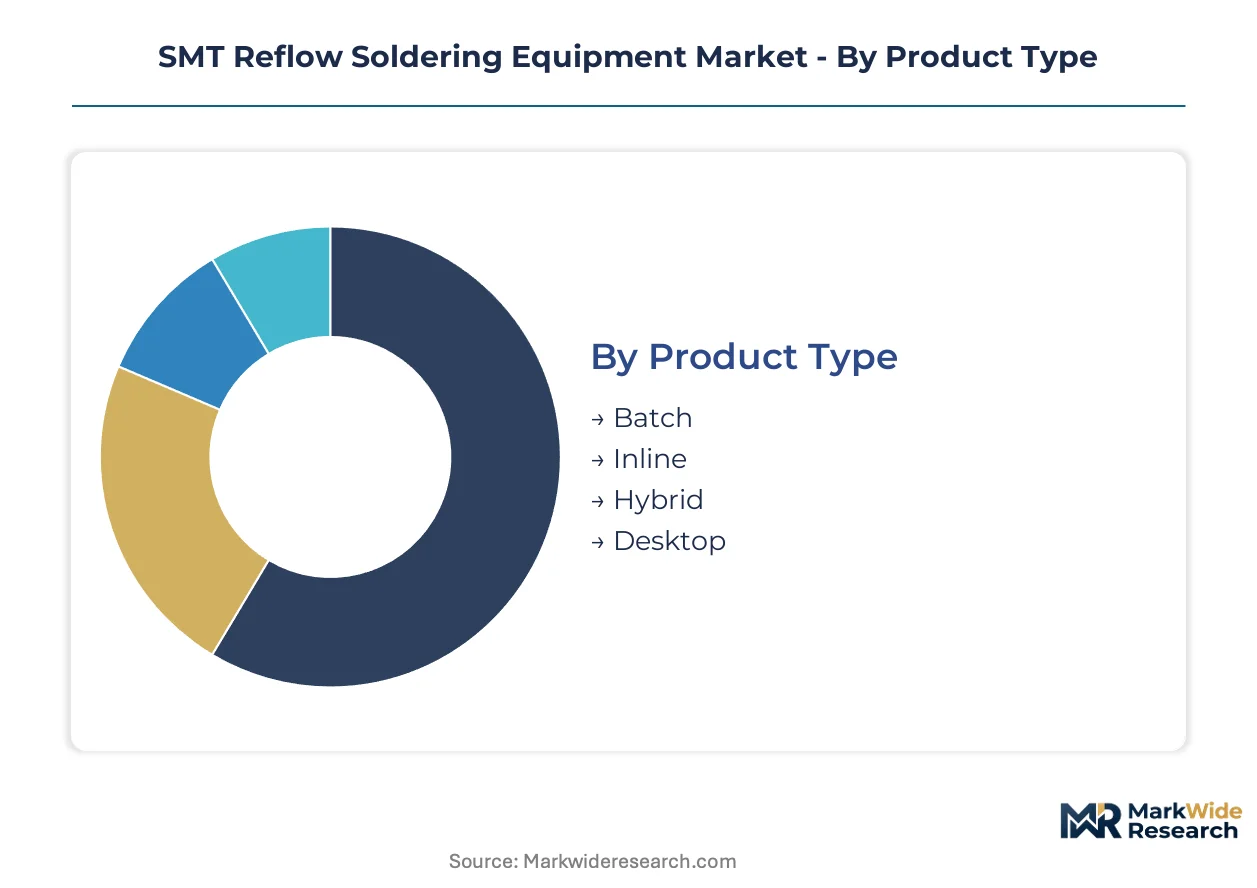
Reflow soldering equipment segmentation reveals divergent technology requirements across production scales and thermal precision demands. Volume-driven consumer electronics favor high-throughput inline systems while medical device and aerospace applications command premium vapor phase technologies. Understanding these segment boundaries enables vendors to align R&D investment with margin concentration points.
Product Type:
Inline systems dominate volume deployment while batch configurations retain niche premium positioning for low-volume high-mix manufacturing.
- Inline:Continuous conveyor systems process boards through 8-12 independently controlled thermal zones with conveyor speeds adjustable to 1.5 meters per minute. Automotive tier-one suppliers in Stuttgart and Shanghai deploy these for power module assemblies where thermal gradient control determines solder joint fatigue life under power cycling stress.
- Batch:Chamber-based systems process board lots in discrete thermal cycles with programmable atmosphere control. Medical device manufacturers in Ireland and Switzerland specify batch configurations for MDR-compliant process validation where thermal profile repeatability documentation is mandatory.
- Hybrid:Combines inline conveyor mechanics with batch-style atmosphere isolation for specialized substrate processing.
- Desktop:Compact single-board systems serve prototyping houses and repair services with limited footprint requirements.
Mature deployment sits with Inline systems. Newer deployment is concentrated in Hybrid configurations bridging throughput and flexibility demands.
Application:
Automotive electrification is compressing thermal profile tolerances while consumer electronics sustain volume scale.
- Automotive Electronics:Battery management systems and powertrain modules demand ±2°C thermal profile accuracy across multi-zone systems. EV manufacturers in China are scaling SMT line capacity for advanced driver-assistance modules requiring high-thermal-mass board processing capabilities.
- Consumer Electronics:Smartphones, wearables, and IoT devices drive high-throughput demand for compact component soldering. Contract manufacturers in Shenzhen control the majority of new SMT line investments serving fabless semiconductor designers.
- Industrial Electronics:Factory automation controllers and power supply modules require extended thermal profiles for heavy copper substrates.
- Medical Devices:Implantable and diagnostic equipment mandates oxygen-free thermal environments with full process traceability.
Volume concentration favors Consumer Electronics. Steepest expansion trajectory belongs to Automotive Electronics as electrification accelerates.
Technology:
Convection systems capture mainstream share while vapor phase commands medical and aerospace certification tiers.
- Convection:Forced hot air systems with nitrogen inerting dominate high-volume manufacturing. Europe's F-Gas Regulation accelerates replacement of legacy thermal systems with nitrogen-based convection technologies as fluorinated greenhouse gas restrictions tighten.
- Vapor Phase:Condensing vapor blankets deliver uniform heating without thermal shock for temperature-sensitive substrates. Perfluoropolymer working fluid costs and sealed system maintenance requirements limit adoption outside medical device and aerospace applications demanding oxygen-free environments.
- IR:Radiant heating systems offer rapid thermal response for specific substrate configurations.
- Laser:Selective soldering for localized thermal processing of heat-sensitive components.
Established deployment centers on Convection systems. Emerging deployment concentrates in Vapor Phase for critical reliability applications.
End User:
Contract manufacturers consolidate procurement power while OEMs retain captive capacity for proprietary designs.
- Contract Manufacturers:EMS providers serving fabless semiconductor and IoT device designers negotiate multi-site framework agreements bundling equipment, consumables, and predictive maintenance. Top-five EMS operators in Shenzhen direct the majority of regional SMT line investments.
- OEMs:Original equipment manufacturers in automotive and medical verticals maintain captive soldering capacity for intellectual property protection and process control. FDA 21 CFR Part 820 validation requirements extend equipment commissioning timelines for qualified system deployments.
- Repair Services:Aftermarket rework operations require portable thermal profiling capabilities for board-level repair.
- Prototyping Houses:Quick-turn electronics developers prioritize flexibility over throughput for design iteration cycles.
Traditional deployment rests with OEMs. Fastest-growing deployment concentrates in Contract Manufacturers as EMS consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-designated advanced manufacturing clusters concentrate SMT reflow equipment procurement in Shenzhen and Suzhou special economic zones. Germany's automotive electronics corridor along the Stuttgart-Munich axis sustains premium equipment demand. India's PLI scheme for semiconductor packaging is redrawing capacity maps across South Asia.
China
EV battery management system manufacturers in Shenzhen and Dongguan are scaling SMT line capacity for advanced driver-assistance modules. MIIT industrial equipment directives establish electromagnetic compatibility and energy efficiency benchmarks that determine market access for imported reflow ovens. The Yangtze River Delta cluster around Suzhou hosts contract manufacturers serving fabless semiconductor designers with high-throughput inline systems.
Germany
Automotive tier-one suppliers in Stuttgart and Munich demand ±2°C thermal profile accuracy for powertrain electrification assemblies. ECHA's REACH compliance mandates restricted substance documentation across solder paste chemistries, extending equipment qualification timelines. Bavaria's precision engineering base sustains premium positioning for convection reflow systems serving electrified powertrain manufacturers.
United States
Medical device manufacturers in Minnesota and Massachusetts require FDA 21 CFR Part 820 validation for thermal profile repeatability studies. EPA industrial emissions frameworks intersect with state-level clean manufacturing incentives in California and Texas. The Pacific Northwest electronics corridor concentrates prototyping houses and EMS providers negotiating multi-site framework agreements.
India
PLI scheme incentives for semiconductor packaging and EMS operations are creating first-mover advantage opportunities for reflow oven vendors. BIS certification requirements and DGFT import regulations shape equipment specification standards for domestic contract manufacturers. Karnataka's Electronics City and Tamil Nadu's Sriperumbudur corridor host emerging SMT capacity for IoT device assembly.
Japan
Automotive electronics and industrial controller manufacturers in Aichi and Kanagawa prefectures sustain demand for high-thermal-mass board processing. METI energy efficiency standards and JIS industrial equipment specifications govern thermal recovery system adoption. The Chubu region around Nagoya anchors captive soldering capacity for proprietary power module designs.
SMT Reflow Soldering Equipment Market Competitive Landscape
German engineering houses anchor the premium-tier segment; Japanese and North American specialists hold differentiated positions in precision thermal processing. The vendor base distributes across three strategic tiers: integrated solder-material-to-equipment workflows, standalone system fabricators, and regional service-anchored distributors. Consolidation pressure concentrates among mid-scale European and Asian producers seeking geographic expansion. Technology licensing agreements and predictive maintenance service contracts represent the dominant competitive moves displacing traditional equipment-only transactions.
Within the integrated-materials tier, Senju Metal Industry Co., Ltd. occupies a position bridging solder alloy supply and thermal process equipment. Among German precision engineering specialists, Kurtz Ersa exemplifies premium convection system positioning anchored in automotive tier-one supplier relationships. Heller Industries represents the North American service-infrastructure archetype, sustaining demand through localized thermal process expertise and extensive field support networks.
| Leading Market Players |
|---|
| DDM Novastar Inc. |
| Kurtz Ersa |
| AUTOTRONIK-SMT GMBH |
| UniTemp GmbH |
| Tamura Corporation |
| Intek Corp. |
| Senju Metal Industry Co., Ltd. |
| Heller Industries |
| Madell Technology Corporation |
| Others |
Value Network & Pricing Analysis
Perfluoropolymer working fluid indices cascade through vapor phase equipment pricing tiers, compressing margins for European medical device manufacturers facing F-Gas Regulation compliance deadlines while nitrogen-based convection systems capture procurement share from legacy thermal process operators.
Pricing Analysis
Short lead-time premiums command pricing separation between spot nitrogen-inerted convection systems and long-cycle vapor phase configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal zone count and atmosphere control sophistication, with automotive tier-one suppliers in Stuttgart and Shanghai absorbing certification-grade premiums while contract manufacturers in Shenzhen negotiate volume discounts on standardized inline platforms. Cost compression in economy-tier batch systems is intensifying because Chinese domestic vendors are scaling thermal recovery technology without per-unit licensing fees. EMS providers serving fabless semiconductor designers exhibit highest price sensitivity; medical device OEMs in Ireland and Switzerland demonstrate lowest sensitivity due to MDR-mandated validation requirements.
Supply Chain Analysis
Freight cost volatility from German engineering hubs to Southeast Asian contract manufacturers is reshaping regional inventory positioning strategies. Component fabrication concentrates in Germany, Japan, and China, with precision conveyor mechanics drawing from Bavarian machine tool suppliers and infrared pyrometer assemblies resting on Japanese sensor manufacturers. Solder paste flux chemistries hinge on specialized chemical processors in China and South Korea. Single-source vulnerability pervades perfluoropolymer working fluid supply. Distribution runs through authorized service distributors anchoring local thermal process expertise in manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where ECHA REACH documentation mandates erect qualification barriers that favor incumbent vendors with established substance traceability infrastructure.
For Market Incumbents: To counter margin erosion from Chinese domestic equipment vendors, Kurtz Ersa and Heller Industries should deepen backward integration into nitrogen atmosphere control subsystems while expanding captive service infrastructure in India's PLI-designated electronics corridors. Certification investment in FDA 21 CFR Part 820 validation protocols preserves medical device tier pricing power. For New Entrants and Emerging Players: Enter via India's semiconductor packaging incentives where BIS certification requirements remain less stringent than EU REACH compliance, targeting Karnataka's Electronics City EMS operations with rental-based thermal profiling service models rather than capital equipment sales. White-space concentration sits with prototyping houses in the US Pacific Northwest seeking flexible batch configurations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European convection specialists with established automotive tier-one relationships in Germany, where F-Gas Regulation replacement demand sustains equipment refresh revenue. Watch nitrogen supply infrastructure buildout in Indian industrial zones as inflection signal for contract manufacturer procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Contracts | Machine learning integration displaces break-fix arrangements for EMS providers in Shenzhen. |
| Backward Integration into Solder Materials | Senju Metal Industry's alloy-to-equipment workflow reduces customer process variability. |
| Geographic Expansion into India PLI Corridors | Local service infrastructure captures semiconductor packaging equipment procurement share. |
| F-Gas Regulation Compliance Retrofit Programs | European medical device manufacturers accelerate nitrogen-inerted system adoption timelines. |
| AI-Driven Thermal Profile Optimization | Real-time adjustment algorithms compress defect rates for automotive power module assemblies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with SMT line engineers, thermal process specialists, EMS procurement directors, automotive tier-one supplier quality managers, and reflow oven service technicians. ECHA REACH substance databases, MIIT equipment certification registries, FDA 510(k) device listings, and semiconductor industry association capacity surveys provided validation benchmarks. Bottom-up equipment shipment tallies triangulated against top-down contract manufacturer capital expenditure disclosures.
Granularity-level modeling disaggregated volume and value across the projection horizon by product type, application vertical, thermal technology, and end-user archetype, with additional segmentation by regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis intersecting with EV powertrain electrification timelines and F-Gas Regulation phase-out schedules. Forecast inputs incorporated nitrogen infrastructure development trajectories in Indian industrial zones and low-temperature solder alloy adoption curves in consumer electronics assembly.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH substance restriction amendments or nitrogen supply disruptions in Chinese manufacturing clusters. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market