
 Tape Storage Market | 2026-2036
Tape Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Tape Storage Market Intelligence
Enterprise procurement of tape storage is fragmenting as cloud service providers build direct relationships with cartridge manufacturers while systems integrators lose intermediary control. Fujifilm dominates advanced barium ferrite media formulation, leveraging proprietary particle technology to extend areal density roadmaps. IBM anchors mainframe-attached tape library architectures, sustaining decades of institutional design investment. Spectra Logic competes on deep storage robotics, specializing in exabyte-scale tape library automation for government and research installations.
Tape storage comprises sequential-access magnetic recording media wound on reels within cartridges, employing longitudinal or helical scan methods to write data onto coated substrates with coercivity exceeding 300 kA/m for archival stability spanning thirty-plus years. Its primary commercial purpose is offline, immutable retention of infrequently accessed datasets where latency tolerance permits minutes-to-hours retrieval in exchange for cost and energy advantages over spinning disk. LTO drives the installed base volume across enterprise and cloud segments, while library systems capture the dominant share of capital expenditure due to robotics, cooling, and software integration complexity. Disaster recovery applications are expanding fastest among end users as ransomware insurance mandates harden requirements for air-gapped, offline copies.
FCC data center energy reporting rules, NIST SP 800-88 media sanitization standards, and SEC recordkeeping regulations collectively shape product design cycles and sales cycles across United States deployments. Compliance officers now specify WORM-capable cartridges and encrypted key management as baseline procurement criteria. Stakeholders must monitor whether emerging quantum-resistant encryption standards force cartridge hardware refreshes before existing media reaches end of life.
Market Dynamics
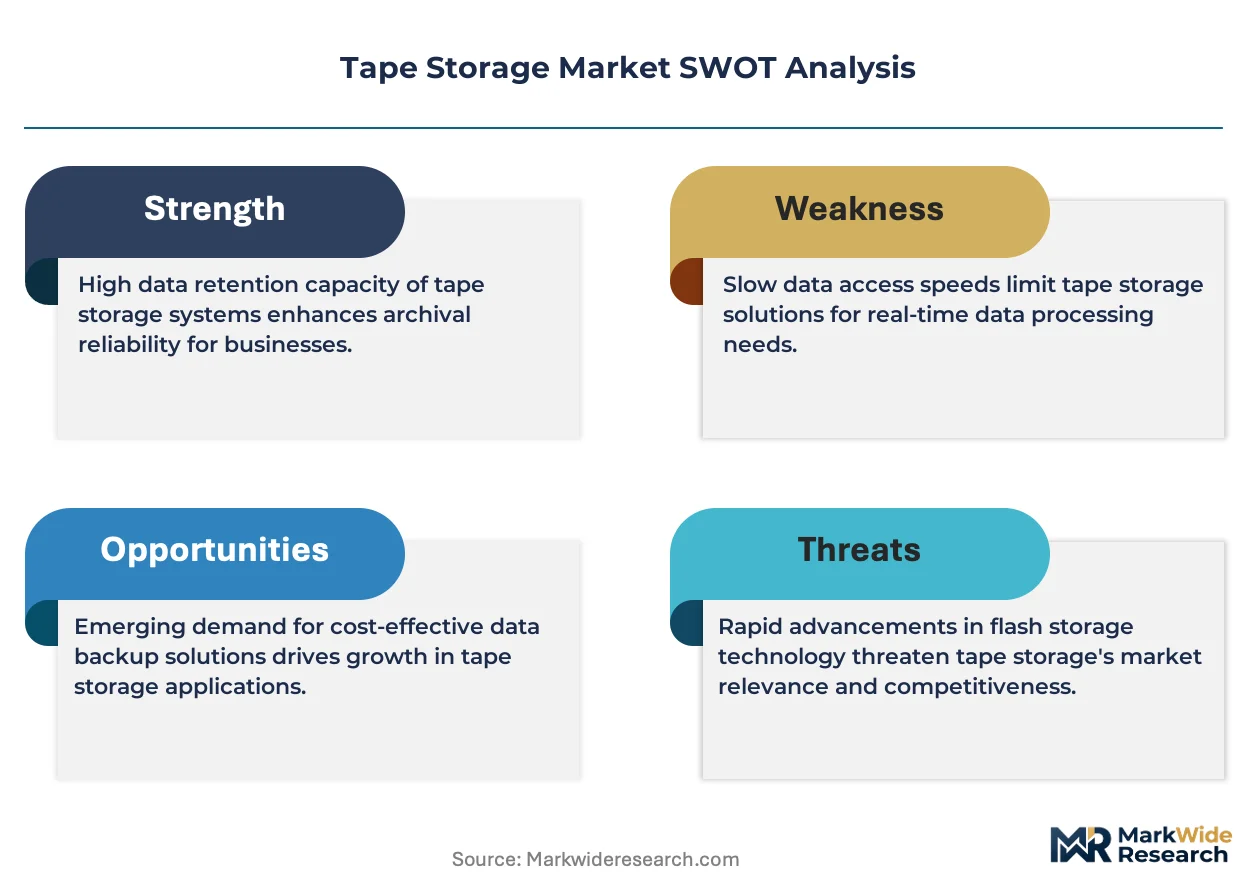
Hyperscale cloud operators are compressing procurement cycles by negotiating directly with barium ferrite media manufacturers, bypassing traditional systems integrators and fragmenting established channel hierarchies across enterprise tape storage.
Growth Catalysts
- SEC recordkeeping mandates:Extended retention periods for financial audit trails force institutional investors toward WORM-capable tape archives that satisfy immutable storage requirements.
- Japan's manufacturing cluster:Concentrated R&D investment in magnetic particle engineering sustains areal density roadmaps that outpace competing archival technologies.
- Ransomware insurance underwriting:Cyber liability carriers now stipulate air-gapped offline copies as policy conditions, accelerating disaster recovery procurement.
Market Restraints
- Helium supply concentration:Drive manufacturing depends on helium for sealed chamber assembly, with extraction concentrated in Qatar and Algeria creating input volatility.
- Helical scan obsolescence:Proprietary Sony formats face interoperability barriers against LTO dominance, locking legacy archives into unsupported hardware.
- Object storage substitution:Amazon Glacier Deep Archive and Azure Archive tiers compete on retrieval latency, pressuring tape's cost advantage at petabyte scale.
Strategic Opportunities
- Quantum-resistant encryption standards:NIST post-quantum cryptography guidelines will mandate hardware refreshes, creating replacement demand before media end-of-life.
- Research installation expansion:Radio astronomy and genomics facilities in Australia and Germany generate exabyte-scale cold data with decades-long retention horizons.
- Energy reporting arbitrage:FCC data center power disclosure rules position tape's watt-per-terabyte efficiency as a compliance asset against spinning disk.
Industry Challenges
- Robotics engineering scarcity:Library automation requires mechatronics specialists familiar with precision tape handling, a skillset concentrated at IBM and Spectra Logic with limited external pipeline.
- Key management complexity:Encrypted cartridge ecosystems demand HSM integration that exceeds typical enterprise security team capabilities, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tape Storage Market |
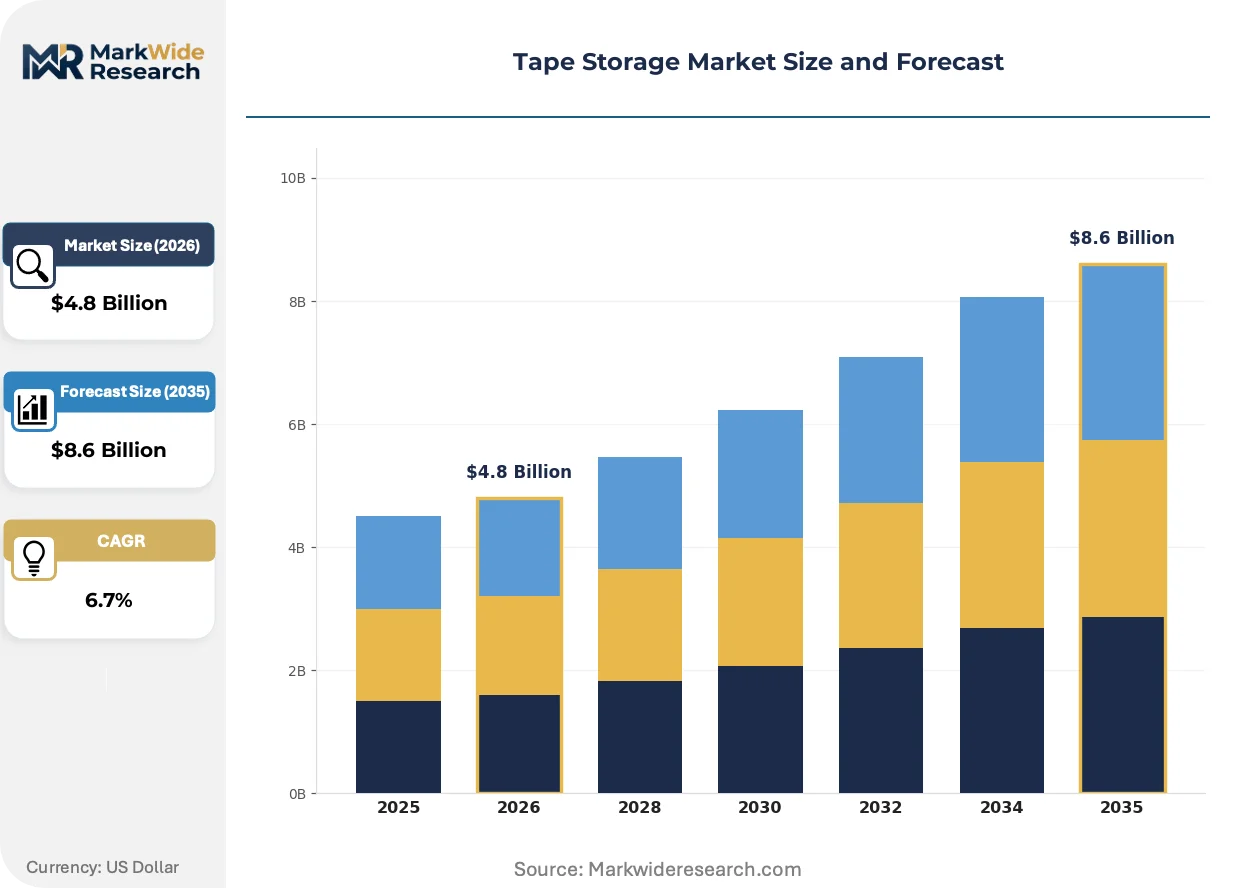
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
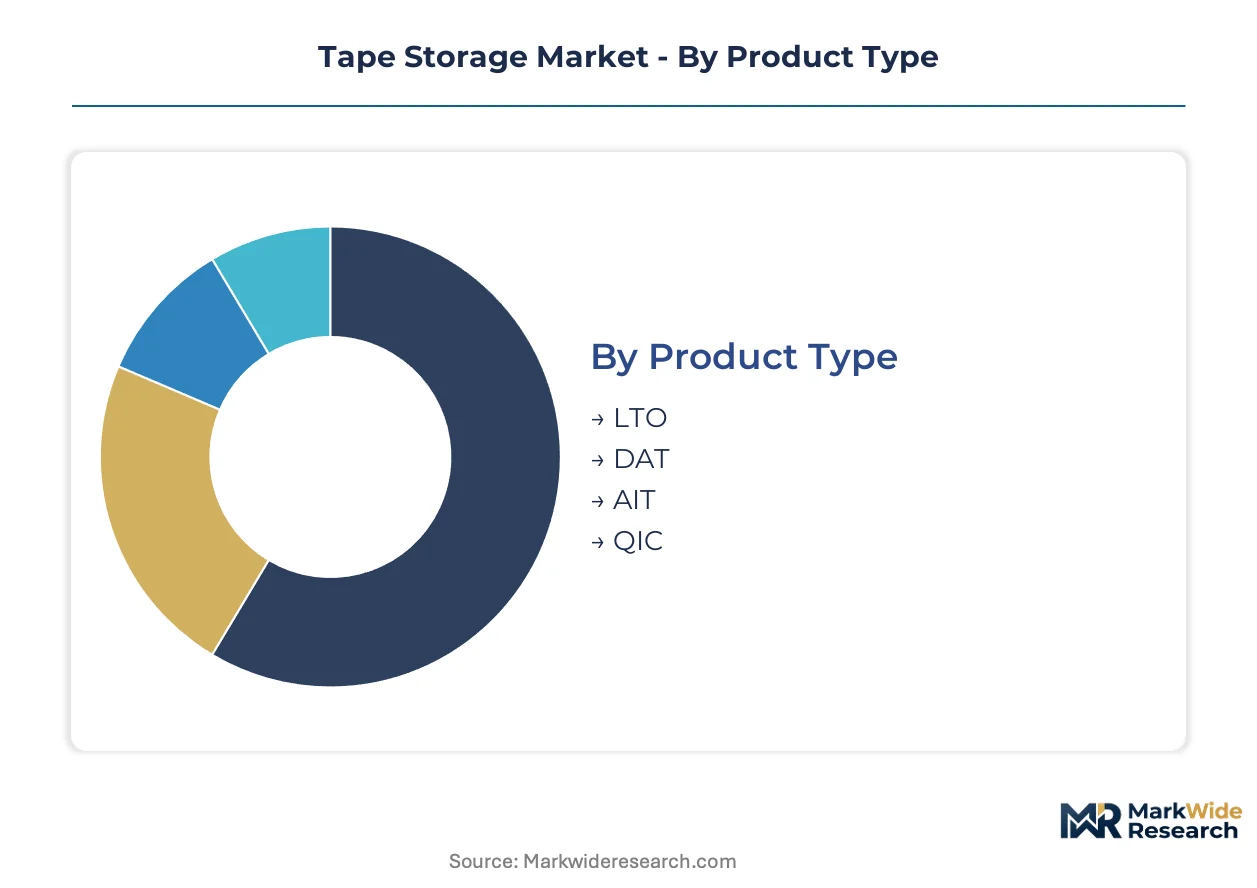
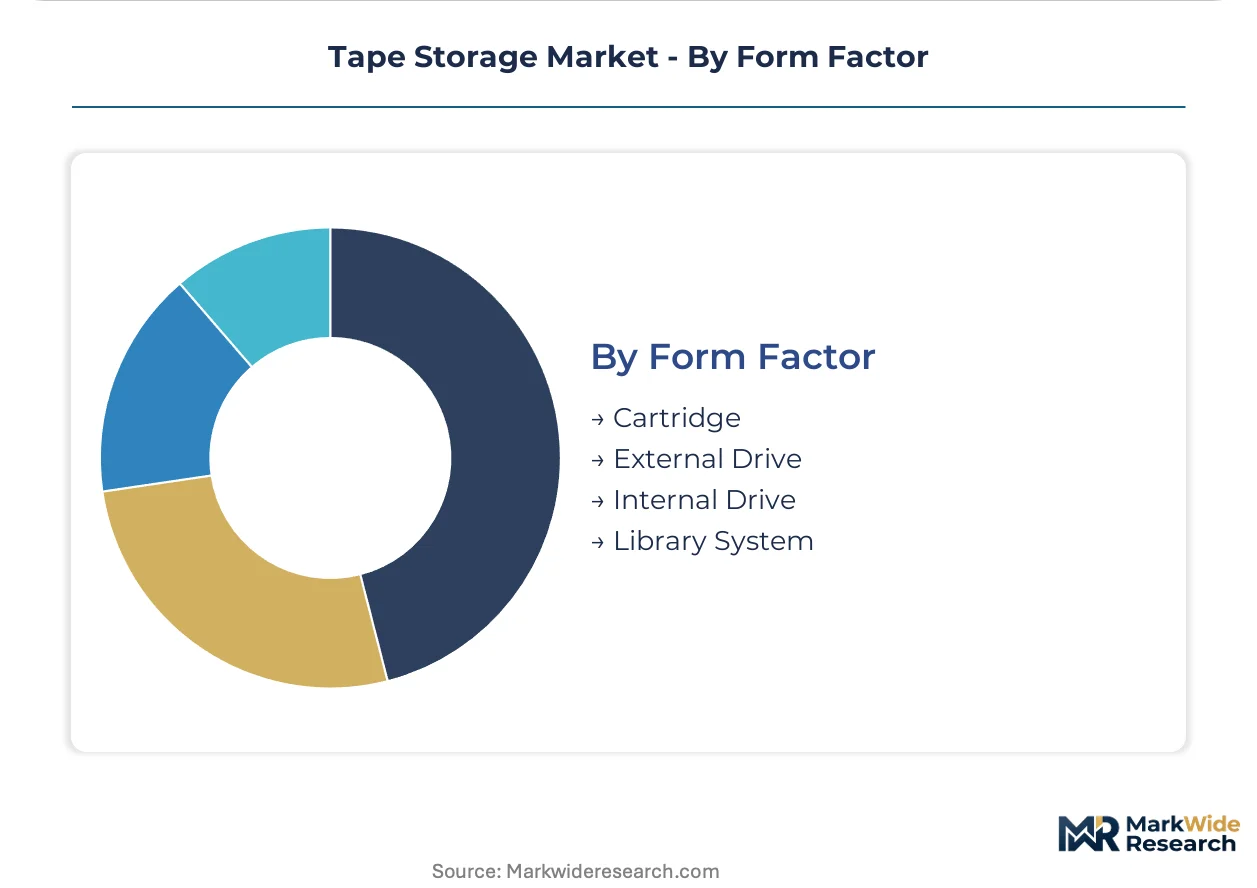
| Segmentation | Product Type: LTO, DAT, AIT, QIC End User: Cloud Service Providers, Enterprises, Media Agencies, Healthcare Organizations Application: Data Backup, Archiving, Disaster Recovery, Long-Term Storage Form Factor: Cartridge, External Drive, Internal Drive, Library System |
| Companies Covered | Fujifilm, Dell Technologies, IBM, NetApp, Hitachi, Quantum, Sony, Spectra Logic, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tape Storage Market Strategic Shifts & Innovations
Barium ferrite particle engineering is compressing bit dimensions while extending archival stability, rendering prior metal particle formulations structurally uncompetitive across compliance-driven procurement.
Advanced barium ferrite media operates at coercivity levels exceeding 300 kA/m, enabling thirty-year retention without signal degradation. Financial services and healthcare archives are standardizing on this substrate for SEC and HIPAA-mandated retention. The technology is rendering obsolete cobalt-doped metal particle tapes that dominated prior LTO generations.
NIST SP 800-88 media sanitization standards now govern federal agency decommissioning protocols, mandating physical destruction or cryptographic erasure for classified tape cartridges. Defense contractors and cleared facilities must maintain sanitization audit trails that extend hardware refresh cycles. Government procurement specifications increasingly embed these requirements as non-negotiable evaluation criteria.
Cloud service providers are unbundling storage hardware from management software, selling tape library capacity as metered archive tiers rather than capital equipment. Systems integrators that previously controlled enterprise sales cycles face margin compression as AWS, Google Cloud, and Microsoft Azure negotiate direct cartridge supply agreements. This disintermediation concentrates most visibly in North American hyperscale regions where compliance-bound enterprises dominate demand.
Tape Storage Market Segmentation
Tape storage procurement cycles vary dramatically across product categories, with media cartridges turning over every 3-5 years while library systems operate on 10-15 year depreciation schedules. Understanding these temporal patterns helps vendors align R&D investment with replacement demand windows.
Product Type:
Replacement cycles separate commodity media from durable drive hardware, with format obsolescence risk concentrated in proprietary architectures.
- LTO:Open-standards linear tape-open format dominates enterprise interoperability with backward-compatible read capability across five generations. Cloud service providers in the United States and Japan standardize procurement on LTO-9 barium ferrite media for exabyte-scale cold storage tiers.
- DAT:Digital audio tape helical scan technology persists in legacy healthcare imaging archives where HIPAA-mandated retention locks institutions into unsupported hardware. Migration costs to LTO infrastructure deter replacement despite Sony's discontinued manufacturing.
- AIT:Advanced intelligent tape proprietary Sony format faces accelerated obsolescence as spare parts depletion forces federal research laboratories into emergency data migration programs.
- QIC:Quarter-inch cartridge format retains niche demand among industrial control system operators requiring quarter-century retention for SCADA audit trails.
LTO dominates installed base. DAT is where expansion concentrates among organizations finally exiting legacy helical scan dependencies.
End User:
Procurement sophistication tiers separate hyperscale operators with direct manufacturer relationships from intermediary-dependent enterprise buyers.
- Cloud Service Providers:AWS, Google Cloud, and Microsoft Azure negotiate barium ferrite cartridge supply directly with Fujifilm, bypassing distribution channels to compress unit costs at petabyte scale.
- Enterprises:Financial services and manufacturing firms rely on systems integrators for library deployment, extending sales cycles through security review and compliance validation stages.
- Media Agencies:Film studios and broadcast archives prioritize LTO for uncompressed 8K raw footage retention, with Hollywood facilities driving demand for high-capacity cartridge formats.
- Healthcare Organizations:Hospital networks and payers face SEC and HIPAA dual compliance burdens, mandating WORM-capable archives for patient records and financial audit trails.
Cloud service providers dominate capital expenditure. Healthcare organizations are climbing the fastest as ransomware insurance mandates harden offline copy requirements.
Application:
Latency tolerance and retrieval frequency determine hardware configuration, with air-gap requirements driving library robotics investment.
- Data Backup:Operational recovery scenarios demand 24-hour retrieval windows, positioning LTO libraries against disk-based deduplication appliances in mid-market procurement.
- Archiving:Compliance-bound retention with decade-plus horizons favors tape's energy efficiency, with NIST SP 800-88 sanitization standards governing federal agency decommissioning protocols.
- Disaster Recovery:Ransomware insurance underwriters now stipulate offline, immutable copies as policy conditions, accelerating library automation procurement among Fortune 500 risk managers.
- Long-Term Storage:Research installations in radio astronomy and genomics generate exabyte-scale datasets with thirty-year retention mandates, sustaining demand for highest-density barium ferrite formulations.
Data backup dominates operational procurement. Disaster recovery is where vendor margins concentrate as robotics complexity justifies premium pricing.
Form Factor:
Capital intensity and operational complexity scale from removable media to automated robotics, with software integration requirements determining total cost of ownership.
- Cartridge:Barium ferrite media in standardized shells represents the consumable revenue base, with Fujifilm's proprietary particle engineering sustaining areal density leadership.
- External Drive:USB-attached LTO units serve small enterprise and media workstation backup, competing with cloud gateway appliances on simplicity.
- Internal Drive:Server-bay LTO mechanisms integrate with backup software stacks, requiring SAS connectivity and driver certification that extends qualification timelines.
- Library System:Robotic tape handling with thousands of cartridge slots captures dominant capital expenditure share, with IBM and Spectra Logic anchoring mechatronics engineering scarce elsewhere in the supply base.
Cartridge media dominates recurring revenue. Library systems are where expansion concentrates as exabyte-scale deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands pricing leverage through concentrated barium ferrite manufacturing, while the United States absorbs premium library system costs driven by SEC compliance mandates. This asymmetry shapes procurement patterns across enterprise and cloud segments.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center corridors negotiate direct cartridge supply contracts, compressing distribution margins. SEC recordkeeping regulations mandate WORM-capable archives for financial audit trails, hardening procurement specifications. IBM sustains mechatronics engineering for mainframe-attached libraries from its research installations in New York State.
Japan
Fujifilm and Sony anchor magnetic tape manufacturing and particle R&D in the Kanto industrial belt. METI industrial policy supports areal density roadmaps that outpace competing archival substrates. Sendai and Odawara production facilities supply advanced barium ferrite media to cloud operators worldwide.
Germany
Automotive and industrial machinery enterprises in Baden-Württemberg and Bavaria deploy tape libraries for CAD archive retention spanning decades. REACH chemical regulations govern coating substrate compliance for European data center deployments. Fraunhofer research institutes in Berlin and Munich validate long-term media stability protocols.
Australia
Radio astronomy facilities in Western Australia generate exabyte-scale datasets requiring thirty-year retention horizons. The national research infrastructure strategy funds cold storage expansion for the Square Kilometre Array telescope. Perth and Canberra host government-backed data centers prioritizing energy-efficient archival tiers.
United Kingdom
Financial services firms in the City of London face dual FCA and SEC compliance burdens for cross-border audit trails. NHS trusts across England mandate HIPAA-equivalent archival standards for patient imaging records. Slough and Docklands data center clusters concentrate disaster recovery infrastructure investment.
Tape Storage Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling particle formulation and media substrate supply. The vendor base separates into three strategic archetypes: magnetic media chemists, robotic library engineers, and cloud-integrated storage platform operators. Consolidation pressure concentrates among systems integrators as hyperscale operators bypass intermediary channels. Competitive moves center on direct supply negotiations and quantum-resistant encryption hardware refreshes.
Among Japanese magnetic media specialists, Fujifilm and Sony occupy positions spanning particle engineering through cartridge manufacturing. IBM represents the integrated systems archetype, anchoring mainframe-attached library architectures through decades of institutional design investment. Spectra Logic exemplifies the deep storage robotics specialist, focusing on exabyte-scale automation for government and research installations.
| Leading Market Players |
|---|
| Fujifilm |
| Dell Technologies |
| IBM |
| NetApp |
| Hitachi |
| Quantum |
| Sony |
| Spectra Logic |
| Hewlett Packard Enterprise |
| Others |
Cost & Logistics Intelligence
Helium supply concentration in Qatar and Algeria injects input volatility that compresses margin structures at the drive manufacturing tier while expanding pricing spreads between standard cartridge media and precision-engineered library robotics. This single-source dependency forces buyers into long-term offtake contracts for sealed-chamber components, reshaping procurement risk allocation across enterprise and hyperscale segments alike.
Pricing Analysis
Configured-to-order library systems command substantial premiums over standard cartridge media due to mechatronics complexity and software integration requirements. Pricing stratifies across premium robotics tiers, mid-range automated libraries, and economy-grade standalone drives, with Fujifilm's proprietary barium ferrite particle engineering sustaining brand premiums in media supply. Cost compression in the external drive segment intensifies as USB-attached LTO units face cloud gateway substitution, while hyperscale cloud operators exhibit lowest price sensitivity due to direct manufacturer negotiations that bypass distribution markups.
Supply Chain Analysis
Export-control restrictions on advanced magnetic particle engineering limit technology flows from Japan's Kanto industrial belt to emerging manufacturing zones. Barium ferrite media production draws from concentrated coating substrate supply anchored in Sendai and Odawara facilities, with helium feedstock for drive assembly resting on extraction sites in Qatar and Algeria. Single-source vulnerability in precision robotics engineering concentrates at IBM and Spectra Logic, while distribution runs through direct supply agreements between cloud operators and cartridge manufacturers that disintermediate traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum-resistant encryption mandates represent a regulatory inflection that will force hardware refreshes across installed base volumes, creating replacement demand windows before existing media reaches end-of-life. This compliance-driven disruption favors vendors with NIST-aligned development roadmaps and cryptographic key management integration capabilities.
For Market Incumbents: Entrench barium ferrite particle leadership through METI-supported R&D investment in areal density roadmaps, while securing direct supply relationships with AWS, Google Cloud, and Microsoft Azure to defend against channel disintermediation. IBM and Spectra Logic should expand mechatronics engineering pipelines to address robotics specialist scarcity that constrains library automation deployment timelines.
For New Entrants and Emerging Players: Build out quantum-resistant encryption hardware capabilities ahead of NIST post-quantum cryptography standardization, targeting federal research laboratories and defense contractors with sanitization audit trail requirements. Australia's radio astronomy facilities and Germany's automotive CAD archives offer penetrable white-space segments where exabyte-scale retention mandates outstrip incumbent service coverage.
For Investors and Strategic Acquirers: The market sits at a pre-standardization phase that favors magnetic media chemists with cryptographic integration capabilities over pure robotics hardware vendors. Long-term viability hinges on cartridge format longevity exceeding thirty-year archival horizons, with quantum-resistant certification timelines serving as the critical inflection signal for hardware refresh cycle intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Barium Ferrite Particle R&D Expansion | Fujifilm's proprietary engineering sustains areal density leadership against metal particle obsolescence. |
| Direct Cloud Provider Supply Agreements | Hyperscale negotiations with AWS and Azure compress distribution margins and fragment channel hierarchies. |
| Quantum-Resistant Encryption Hardware Development | NIST post-quantum cryptography guidelines will mandate pre-end-of-life cartridge refreshes across federal agencies. |
| Mechatronics Engineering Pipeline Investment | Robotics automation scarcity at IBM and Spectra Logic constrains exabyte-scale library deployment velocity. |
| Ransomware Insurance Compliance Positioning | Cyber liability carriers stipulate air-gapped offline copies, accelerating disaster recovery procurement among Fortune 500 risk managers. |
Research Approach
Initial hypotheses were tested against primary input from data center infrastructure planners, storage procurement officers at financial services firms, compliance officers managing SEC recordkeeping mandates, and robotics engineers at library automation specialists, then refined through secondary validation. Tape cartridge production data, hyperscaler capital expenditure disclosures, NIST cybersecurity framework documentation, and customs records for magnetic media trade flows anchored supply-side estimation. Bottom-up unit economics for LTO drive and media shipments were triangulated against top-down addressable cold storage capacity projections.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, end user sophistication tier, application latency requirement, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis intersecting with compliance-driven refresh mandates, with helium supply volatility and quantum-resistant encryption standardization timelines serving as scenario-weighting inputs for sensitivity testing.
Practitioners should monitor NIST post-quantum cryptography publication schedules and SEC recordkeeping rule amendments for early signals of hardware refresh acceleration. Forecasts reflect assumptions about barium ferrite media stability claims and robotics engineering pipeline expansion that could revise if particle degradation rates exceed thirty-year specifications or mechatronics talent scarcity intensifies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Flash Memory Market
Data Storage
Germany Data Center Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Universal Flash Storage Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
North America SSD Caching Market
Data Storage
SSD Controller Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Data Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Flash-Based Array Market
Data Storage
Storage Class Memory Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Ethernet Storage Market
Data Storage
North America Next Generation Storage Market