
 Pin Insertion Machine Market | 2026-2036
Pin Insertion Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pin Insertion Machine Market Outlook
A capital-intensity divergence between servo-electric specialists and pneumatic legacy suppliers is reorganizing competitive tiers in the pin insertion machine landscape. TE Connectivity leverages its integrated connector-to-automation portfolio to anchor large automotive programs. SPIROL International Corporation specializes in precision fastener insertion systems for aerospace tier-one suppliers. HARMONTRONICS competes on electromechanical platform modularity across Asian electronics manufacturing hubs.
Pin insertion machines are automated or semi-automated equipment designed to press electrical pins, terminals, or connectors into printed circuit boards, wire harnesses, or plastic housings with positional accuracy typically measured in hundredths of a millimeter. These systems serve the fundamental industrial purpose of replacing manual crimping and soldering in high-volume electrical interconnection manufacturing. Automatic platforms dominate volume production in consumer electronics and automotive PCB assembly, where cycle time compression determines factory economics. Servo-driven technology is displacing pneumatic actuation in applications demanding programmable force-distance curves and real-time quality verification. Semi-automatic configurations retain relevance in aerospace harness assembly, where lot sizes remain small and component variability demands operator judgment.
ISO standards for machine safety and the EU Machinery Directive shape product design requirements for equipment sold into European automotive and industrial manufacturing end markets. The EPA's hazardous substance rules in the United States and China's GB standards for industrial equipment safety create divergent compliance pathways that influence regional product configurations. Buyers should monitor how servo technology maturation alters the total cost of ownership equation against pneumatic alternatives when evaluating capital deployment timelines.
Market Dynamics
Servo-electric actuation is displacing pneumatic systems across automotive wire harness manufacturing, compressing cycle times while enabling programmable force-distance verification that EV battery pack assembly demands.
Growth Catalysts
- EU Green Deal industrial emissions rules:German automotive suppliers around Stuttgart and Wolfsburg are retrofitting factories with servo-electric insertion systems to meet binding carbon reduction mandates.
- EV production targets:Automotive OEMs are expanding automated pin insertion capacity to handle high-voltage connector volumes for battery management systems and power electronics.
- ISO machine safety standards:European equipment buyers are specifying certified servo-driven platforms to satisfy CE marking requirements under the EU Machinery Directive.
Market Restraints
- Servo motor and drive cost volatility:Rare earth magnet supply concentration in China creates input price instability for precision motion components.
- Pneumatic legacy installed base:Existing compressed air infrastructure at tier-two suppliers creates switching cost friction against full electromechanical conversion.
- GB standards divergence:China's industrial equipment safety certification requirements force product configuration variants that fragment manufacturing scale economies.
Strategic Opportunities
- India PLI scheme for automotive:The production-linked incentive framework is attracting wire harness manufacturing investment that requires automated insertion capacity.
- Aerospace harness assembly:Semi-automatic configurations with operator judgment retention are penetrating defense and commercial aviation programs with small lot sizes.
- Vision-guided robotics convergence:Integration of machine vision with servo insertion is opening precision applications in medical device connector assembly.
Industry Challenges
- Mechatronics technician scarcity:Servo system commissioning and maintenance requires skills that outpace vocational training pipeline output in Midwestern US manufacturing corridors.
- Legacy MES integration:Brownfield automotive plants face protocol translation complexity when connecting new insertion equipment to existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pin Insertion Machine Market |
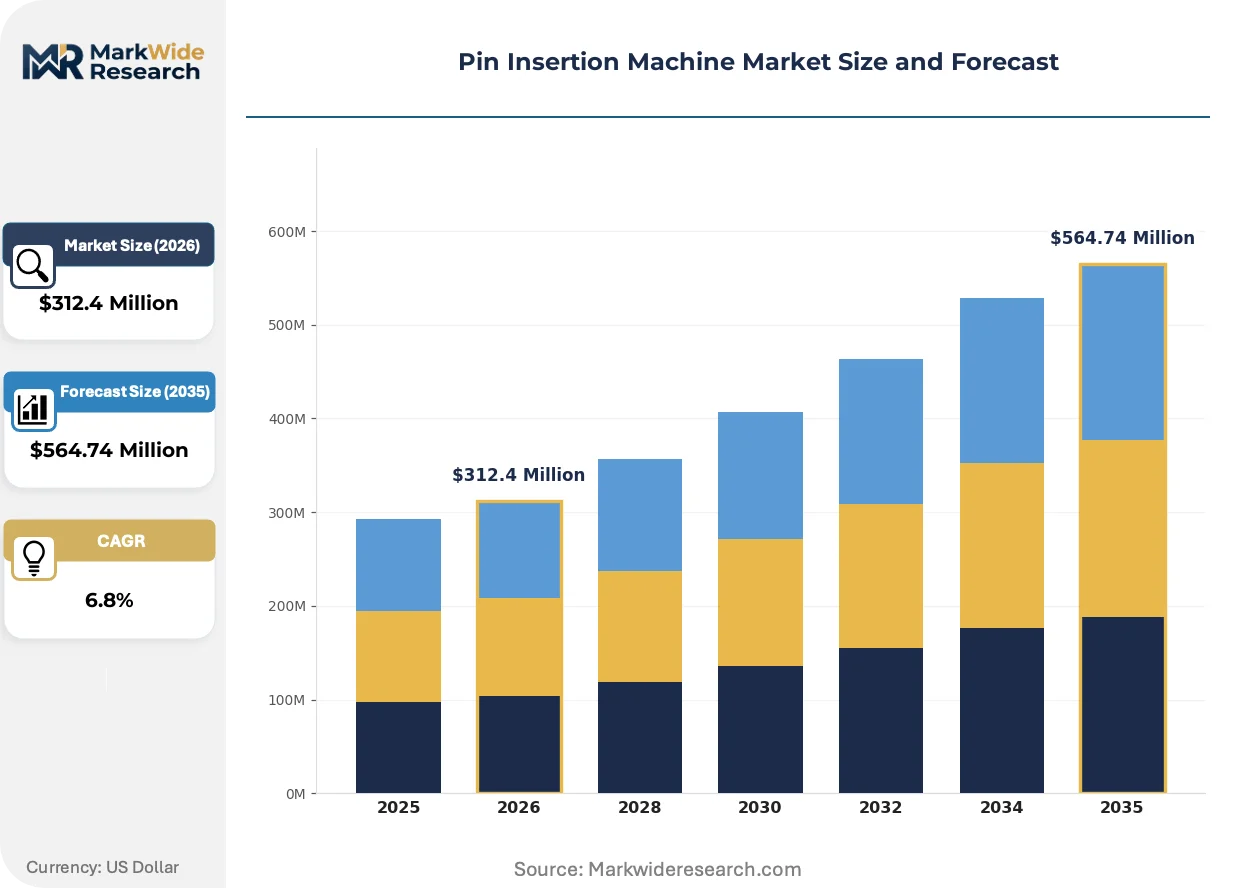
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Fully-Automated End User: Consumer Electronics, Automotive, Aerospace, Industrial Manufacturing Technology: Electromechanical, Pneumatic, Hydraulic, Servo Application: PCB Assembly, Component Insertion, Harness Assembly, Equipment Manufacturing |
| Companies Covered | TE Connectivity, Autosplice, Föhrenbach, Assembly and Automation Technology, Inc., UMG Technologies, HARMONTRONICS, SPIROL International Corporation, Visumatic Industrial Products, Finecs Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pin Insertion Machine Market Strategic Shifts
Real-time quality verification and force-feedback programming are redefining competitive specifications. Equipment buyers now demand insertion traceability that pneumatic systems cannot deliver.
Servo-electric pin insertion technology is bifurcating the installed base. High-volume automotive PCB assemblers are adopting programmable force-distance curves for connector press-fit applications. Pneumatic legacy suppliers are retreating to cost-sensitive consumer electronics segments where cycle time tolerance remains wider.
REACH substance restrictions and RoHS compliance requirements are reshaping connector material specifications. European automotive suppliers must validate that inserted pins meet hazardous substance thresholds. German equipment manufacturers are integrating material traceability modules into insertion system software to automate compliance documentation.
Buyer concentration among tier-one automotive wire harness suppliers is compressing equipment evaluation cycles. Purchasing departments now bundle insertion machine procurement with connector supply agreements. This pattern is most visible in supplier corridors serving Stuttgart-based OEMs, where TE Connectivity leverages integrated portfolio positioning to anchor multi-year programs.
Pin Insertion Machine Market Segmentation
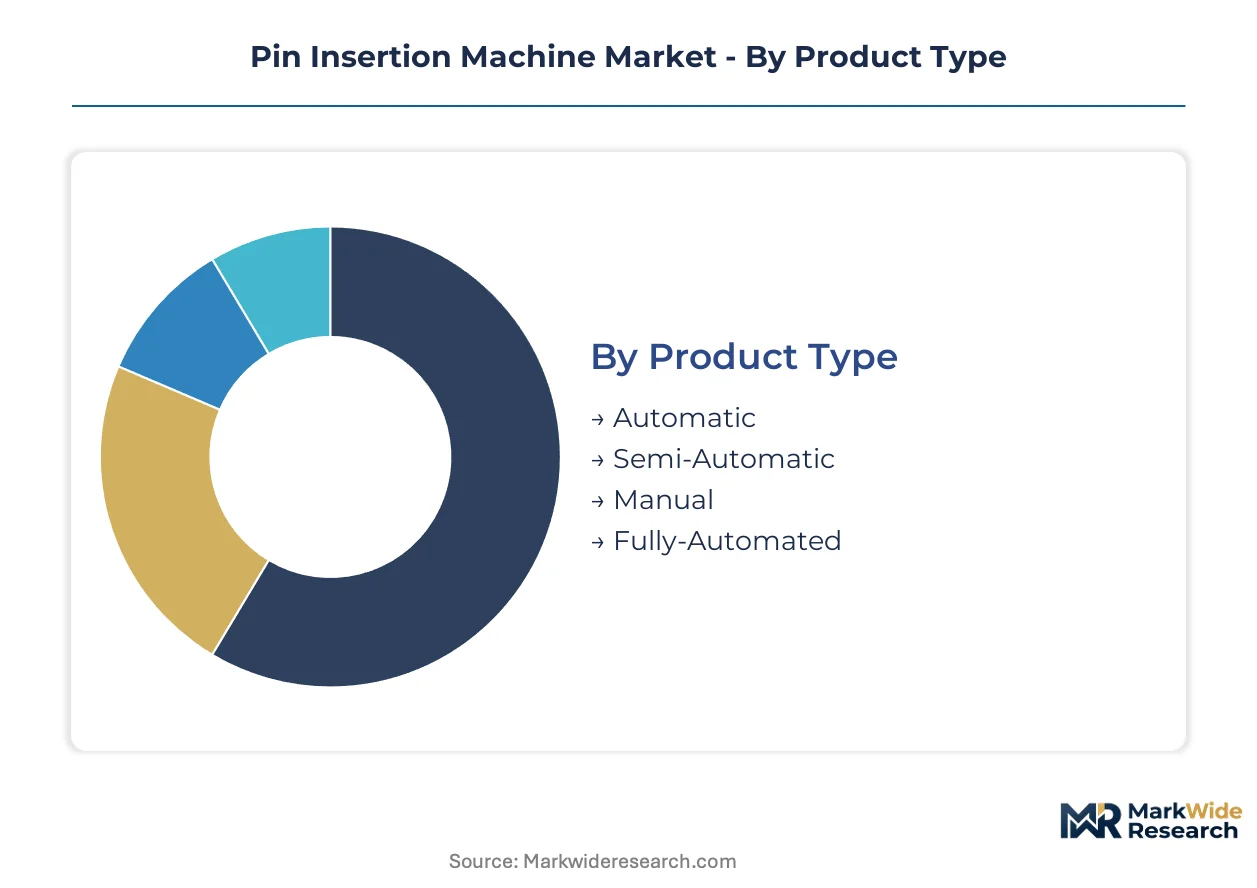
Pin insertion machine procurement patterns diverge sharply between high-volume automotive programs and precision aerospace contracts. Equipment specification cascades from end-use cycle time requirements through technology selection to final product configuration.
Product Type:
Domestic demand concentrates in automatic and fully-automated systems for automotive wire harness plants, while semi-automatic and manual platforms serve export-led aerospace and defense programs with stringent operator oversight requirements.
- Automatic:These systems integrate programmable logic controllers with servo-driven actuation to achieve sub-100-millisecond cycle times in consumer electronics PCB assembly. TE Connectivity deploys automatic platforms across Stuttgart-area automotive supplier corridors to meet EV battery connector volume targets. Demand concentrates where ISO machine safety certification and CE marking under the EU Machinery Directive are mandatory procurement filters.
- Fully-Automated:Complete robotic integration with machine vision and force-feedback verification enables unattended operation in high-volume automotive harness facilities. German OEMs around Wolfsburg specify fully-automated lines to satisfy EU Green Deal industrial emissions rules through servo-electric actuation. The segment commands premium positioning where programmable force-distance curves are non-negotiable for high-voltage connector assembly.
- Semi-Automatic:Operator-assisted configurations retain judgment loops for small-lot aerospace harness assembly where component variability exceeds machine vision tolerance.
- Manual:Hand-actuated bench tools persist in prototype shops and maintenance-repair-overhaul operations with sub-thousand-unit annual volumes.
Automatic systems hold the largest share; momentum sits with fully-automated platforms as EV production targets harden.
End User:
Cost tier stratification separates capital-intensive automotive programs from margin-protected aerospace contracts, with consumer electronics and industrial manufacturing occupying intermediate positions.
- Automotive:Wire harness manufacturers deploy servo-electric insertion systems to handle high-voltage connector volumes for battery management systems and power electronics. The EU Green Deal's binding carbon reduction mandates are retrofitting German supplier factories around Stuttgart and Wolfsburg. Procurement bundles insertion equipment with connector supply agreements, compressing evaluation cycles.
- Consumer Electronics:High-volume PCB assemblers prioritize cycle time compression over force-programmability, accepting pneumatic actuation where cost sensitivity dominates.
- Aerospace:Harness assembly for defense and commercial aviation programs demands semi-automatic configurations with operator judgment retention due to small lot sizes and component variability.
- Industrial Manufacturing:Equipment manufacturers integrate pin insertion into broader automation cells, with demand fragmented across machinery OEMs and contract manufacturers.
Automotive commands the revenue concentration; aerospace delivers the margin premium.
Technology:
Application requirements dictate actuation selection, with electromechanical and servo systems displacing pneumatic legacy in force-verification-critical operations while hydraulic retention persists in heavy-gauge terminal insertion.
- Servo:Closed-loop motor control enables real-time force-distance curve programming and quality verification that EV battery pack assembly demands. Rare earth magnet supply concentration in China creates input price volatility for precision motion components. German automotive suppliers specify servo platforms to satisfy CE marking and EU Machinery Directive requirements.
- Electromechanical:Stepper-motor and ball-screw configurations occupy mid-tier positioning between servo precision and pneumatic cost, prevalent in consumer electronics where cycle time tolerance permits.
- Pneumatic:Compressed air infrastructure at tier-two suppliers creates switching cost friction against full electromechanical conversion, relegating pneumatic systems to cost-sensitive segments.
- Hydraulic:High-force applications in heavy-gauge power connector insertion retain hydraulic actuation where pneumatic force density proves insufficient.
Servo technology is expanding most quickly; pneumatic maintains installed-base inertia.
Application:
Customer type segmentation separates OEM captive operations from contract manufacturing demand, with PCB assembly and harness assembly representing divergent volume-precision tradeoffs.
- PCB Assembly:Press-fit connector insertion demands programmable force-distance curves to prevent substrate damage in high-density boards. Consumer electronics and automotive PCB assemblers drive volume, with automatic platforms dominating where cycle time determines factory economics.
- Harness Assembly:Wire termination and connector insertion for automotive and aerospace applications spans automatic high-volume lines to semi-automatic operator-assisted cells. The India PLI scheme for automotive is attracting wire harness manufacturing investment requiring automated insertion capacity.
- Component Insertion:Discrete component and terminal placement into plastic housings serves industrial equipment and appliance manufacturers with intermediate volume requirements.
- Equipment Manufacturing:Capital goods OEMs integrate insertion systems into production machinery, creating dispersed demand across machinery builders and system integrators.
PCB assembly holds the volume concentration; harness assembly carries the technology upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive wire harness buyers in Germany tolerate premium servo-electric pricing, while tier-two suppliers in Mexico and India remain price-sensitive to pneumatic alternatives. This demand elasticity split shapes regional technology adoption timelines.
United States
EV battery plant construction in Michigan and Tennessee drives servo-electric insertion demand for high-voltage connector assembly. NHTSA safety standards and EPA hazardous substance rules shape equipment certification requirements. Midwestern manufacturing corridors face mechatronics technician scarcity that slows servo system commissioning.
Germany
Stuttgart and Wolfsburg automotive supplier clusters retrofit factories with servo-electric systems to meet EU Green Deal binding carbon reduction mandates. CE marking under the EU Machinery Directive filters procurement toward certified servo platforms. Baden-Württemberg equipment manufacturers integrate material traceability modules to automate REACH compliance documentation.
China
Domestic EV production targets compress insertion equipment evaluation cycles at Shenzhen and Shanghai PCB assemblers. GB standards for industrial equipment safety force product configuration variants that fragment manufacturing scale economies. Rare earth magnet supply concentration creates input price volatility for precision servo motion components.
India
The PLI scheme for automotive attracts wire harness manufacturing investment to Tamil Nadu and Gujarat requiring automated insertion capacity. BIS certification requirements shape equipment specification for domestic market entry. Supplier parks near Chennai deploy automatic platforms to serve export-oriented automotive OEM contracts.
Japan
Precision connector assembly for robotics and medical devices sustains demand for force-feedback programmable systems in Nagoya and Osaka manufacturing belts. METI industrial policy supports servo technology maturation through domestic automation vendor ecosystems. Kansai-based electronics manufacturers prioritize cycle time compression in consumer electronics PCB assembly.
Pin Insertion Machine Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the pin insertion machine landscape. The upper tier combines connector manufacturing with captive automation development, while mid-tier players compete on electromechanical platform modularity or precision fastener specialization. Strategic archetypes include integrated connector-automation portfolios, precision aerospace specialists, and Asian electronics manufacturing hub suppliers. Competitive moves center on portfolio diversification into adjacent automation cells and geographic expansion through regional system integrator partnerships.
Within the integrated tier, TE Connectivity anchors multi-year automotive programs through bundled connector and equipment supply agreements. SPIROL International Corporation exemplifies the precision aerospace specialist archetype serving tier-one defense and commercial aviation harness manufacturers. HARMONTRONICS occupies a position among Asian hub suppliers competing on platform modularity across electronics manufacturing centers. These three represent distinct strategic positions rather than market share dominance.
| Leading Market Players |
|---|
| TE Connectivity |
| Autosplice |
| Föhrenbach |
| Assembly and Automation Technology, Inc. |
| UMG Technologies |
| HARMONTRONICS |
| SPIROL International Corporation |
| Visumatic Industrial Products |
| Finecs Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term bundled procurement contracts between tier-one automotive wire harness suppliers and equipment manufacturers lock in servo-electric system access while stabilizing lifetime service revenue visibility. This contract structure concentrates pricing power with integrated portfolio holders in Germany's Stuttgart corridor, where EU Green Deal compliance mandates override pure cost competition.
Pricing Analysis
After-sales service contracts and spare parts provisioning drive lifetime value capture beyond initial hardware placement. Pricing stratifies across premium servo-electric tiers with CE marking certification, mid-tier electromechanical platforms, and economy pneumatic configurations for cost-sensitive consumer electronics. Cost compression in the pneumatic segment intensifies as Asian electronics manufacturers squeeze cycle-time tolerance for price concessions. Tier-two suppliers in Mexico and India exhibit the highest price sensitivity, while German automotive OEMs prioritize programmable force-verification over acquisition cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints elevate inbound logistics costs for precision motion components sourced from East Asian manufacturing hubs. Rare earth magnet production concentrates in China, with secondary supply from Japan and limited Western alternatives. Servo motor and drive assemblies hinge on neodymium supply concentration that creates single-source vulnerability during export license disruptions. Distribution runs through regional system integrator partnerships that localize commissioning and aftermarket service capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pin insertion machine vendors increasingly monetize software-enabled force-programming updates and predictive maintenance subscriptions that expand faster than hardware replacement cycles. This service-attach layer now constitutes the primary margin expansion vector as equipment commodification pressures intensify.
For Market Incumbents: Fortify captive connector supply agreements with automotive OEMs by embedding insertion equipment into multi-year procurement bundles. Invest in CE marking certification depth to preempt regulatory displacement under evolving EU Machinery Directive interpretations. Defensive consolidation of regional service networks in Baden-Württemberg and Michigan protects against emerging Asian platform modularity threats. For New Entrants and Emerging Players: CE marking fast-track certification enables penetration of mid-tier European automotive suppliers seeking second-source servo platforms. White-space opportunity concentrates in India's Tamil Nadu supplier parks, where PLI scheme incentives attract wire harness investment without incumbent equipment lock-in. Target aerospace semi-automatic configurations with operator-assist features that incumbent automatic specialists underserve. For Investors and Strategic Acquirers: Precision fastener insertion specialists with aerospace defense program credentials represent attractive acquisition targets given margin premiums in small-lot harness assembly. Long-term viability centers on servo technology maturation displacing pneumatic installed bases over the next decade. Monitor rare earth magnet export policy shifts from Chinese regulators as inflection indicators for input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Sourcing | Mitigates Chinese supply concentration risk for servo motor manufacturers facing input price volatility. |
| CE Marking Certification Expansion | Unlocks German automotive supplier procurement filters under EU Machinery Directive requirements. |
| Regional Service Network Densification | Reduces commissioning delays in Midwestern US corridors facing mechatronics technician scarcity. |
| Software-Defined Force Programming | Enables recurring revenue from EV battery pack assembly customers requiring curve updates. |
| India Manufacturing Footprint Establishment | Captures PLI scheme-driven wire harness investment in Tamil Nadu and Gujarat supplier parks. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at automotive wire harness manufacturers, procurement leads at tier-one electronics assemblers, and aftermarket service heads at equipment OEMs, then refined through secondary validation. Bottom-up demand modeling drew from customs trade data, SEC equipment manufacturer filings, and IHS Markit vehicle production databases. Top-down market sizing triangulated against ISO certification registries and EU industrial emissions compliance disclosures.
Variance decomposition across technology, end-use, and geographic adoption pattern dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro industrial automation investment trends. Forecast inputs incorporated EV battery plant construction pipelines, REACH substance restriction timelines, and rare earth magnet supply elasticity assumptions.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable Sino-Japanese rare earth trade flows; material deviation would warrant model refresh. Forecasts reflect these base assumptions alongside servo technology cost parity trajectories against pneumatic alternatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Servo Drive Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Snowrator Market
Industrial Equipment
CNC Tool Storage System Market