
 OTG Pen Drive Market | 2026-2036
OTG Pen Drive Market Size, Share, and Industry Trends Forecast 2026-2036
OTG Pen Drive Market Analytics
China is fragmenting as contract manufacturers diversify assembly across Vietnam and India to hedge supply chain exposure. SanDisk leverages vertically integrated NAND flash sourcing to sustain margin control across premium tiers. Kingston Technology anchors enterprise-grade reliability positioning through industrial-temperature product lines. Samsung Electronics differentiates via proprietary V-NAND integration in high-capacity OTG formats.
An OTG pen drive is a dual-interface flash storage device incorporating both standard USB-A and micro-USB, USB Type-C, or Lightning connectors, enabling direct host-to-host data exchange without intermediate computing hardware. These devices typically employ MLC or TLC NAND flash with USB 3.2 Gen 1 controllers supporting transfer rates up to 5 Gbps, serving commercial purposes spanning field data collection, mobile content creation workflows, and cross-platform file mobility. USB Type-C OTG variants command expanding shelf space as smartphone OEMs eliminate legacy ports, while 128GB capacity brackets capture disproportionate margin pools from professional content creators. Standard OTG and Micro USB segments face demand erosion as Android device portfolios at Samsung Electronics and Xiaomi complete port transitions.
FCC electromagnetic emissions standards in the United States, CE marking requirements under EU Radio Equipment Directive, and BIS compulsory registration schemes in India collectively shape product certification roadmaps and market access timelines for OTG pen drive vendors. REACH substance restrictions and RoHS hazardous material limits further constrain PCB solder compositions and connector plating specifications across European distribution channels. Stakeholders must monitor interface standardization timelines at USB-IF and device OEM port roadmaps to align inventory commitments with accelerating Type-C transition curves.
Market Dynamics
USB Type-C interface standardization is compressing product lifecycles across the OTG pen drive sector, forcing inventory rebalancing as Android OEMs eliminate legacy Micro USB ports from mid-tier and entry-level device portfolios.
Growth Catalysts
- Mobile-First Workflows in Southeast Asia:Smartphone users across Indonesia, Vietnam, and India bypass traditional PC intermediaries for direct mobile-to-mobile file transfers, expanding addressable demand for dual-interface storage.
- BIS Compulsory Registration:India's quality enforcement scheme accelerates formal channel consolidation by disqualifying uncertified imports, elevating compliant domestic and multinational suppliers.
- NAND Flash Cost Curves:TLC and QLC density improvements reduce per-gigabyte manufacturing costs, enabling 128GB and 256GB capacity tiers to penetrate professional content creator segments previously served by portable SSDs.
Market Restraints
- Port Standardization Lag:Budget smartphone segments in sub-Saharan Africa and South Asia retain Micro USB connectors, fragmenting interface compatibility requirements and diluting SKU economics.
- Cloud Storage Substitution:5G-enabled synchronous backup services from Google, Apple, and regional providers reduce local storage dependency among urban consumers with reliable connectivity.
- Flash Memory Supply Concentration:Korean and Taiwanese foundries control wafer supply, exposing downstream assemblers to allocation volatility during technology node transitions.
Strategic Opportunities
- Lightning-to-Type-C Bridge Products:Apple's EU-mandated USB-C transition creates temporary demand for dual-connector devices serving mixed iOS-Android households and creative professionals.
- Industrial Temperature Specifications:Field data collection in oil & gas, agriculture, and logistics verticals requires extended operating ranges that command premium positioning unavailable from consumer-grade alternatives.
- Direct-to-Creator Distribution:TikTok, YouTube, and Instagram content producers in Brazil, Mexico, and Nigeria represent underserved volume for high-capacity OTG formats bypassing traditional retail markup.
Industry Challenges
- USB-IF Certification Timelines:Extended logo program approval cycles delay product launches, compressing sell-through windows before successor interface standards emerge.
- Legacy Inventory Stranding:Contract manufacturers face write-down exposure on Micro USB connector stockpiles as OEM port roadmaps accelerate Type-C transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTG Pen Drive Market |
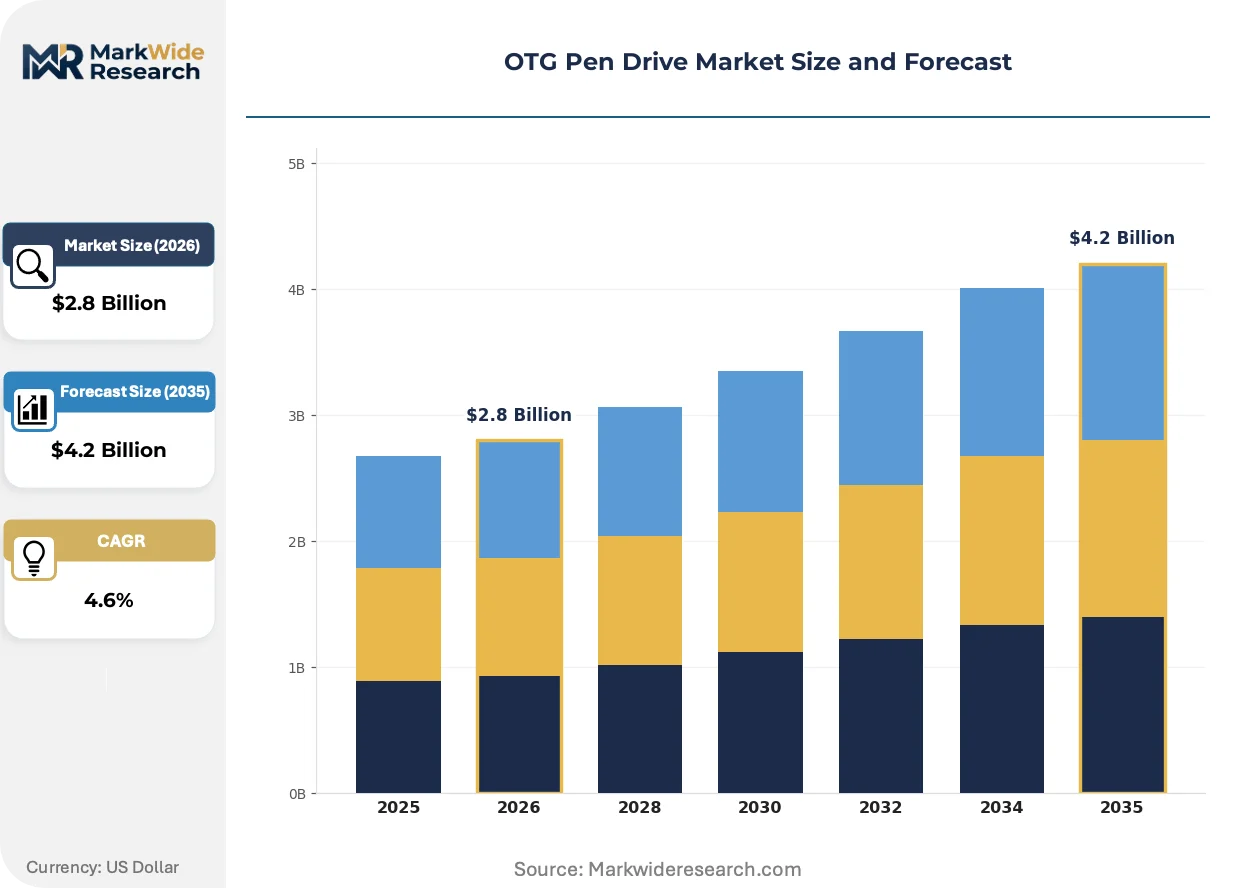
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard OTG, USB Type-C OTG, Micro USB OTG, Lightning OTG Storage Capacity: 8GB, 16GB, 32GB, 64GB, 128GB Application: Data Transfer, Backup & Storage, Media Streaming, Portable Software, Gaming Data End User: Smartphone Users, Tablet Owners, Laptop Users, IT Professionals |
| Companies Covered | SanDisk, Kingston Technology, Samsung Electronics, Transcend Information, ADATA Technology, Toshiba Corporation, Sony Corporation, Lexar Media, Verbatim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTG Pen Drive Market Evolving Landscape
Interface convergence and density scaling are restructuring competitive differentiation in OTG pen drives, compressing hardware margins while elevating firmware and thermal engineering capabilities as value determinants.
USB4 and USB 3.2 Gen 2x2 controller integration is collapsing the performance gap between OTG pen drives and entry-level portable SSDs. Professional videographers and mobile journalists now adopt 1TB+ OTG formats for direct 4K footage offloading without laptop intermediaries. This capability compression is eroding the standalone portable SSD category below 2TB capacities.
REACH substance restrictions and RoHS hazardous material limits are constraining PCB solder compositions and connector plating specifications across European distribution channels. Vendors must reformulate tin-lead alternatives and nickel-gold surface finishes to maintain CE marking compliance. Industrial-grade product lines face disproportionate requalification burdens as high-reliability plating chemistries fall under enhanced substance scrutiny.
Content creators in India, Indonesia, and Vietnam now prioritize instant-sharing workflows over archival storage, compressing purchase cycles and elevating transfer-speed specifications over raw capacity in buying decisions. Regional e-commerce platforms and smartphone accessory bundling programs capture disproportionate volume from this behavioral pivot. Traditional electronics retail chains respond with expedited same-day fulfillment and in-store device-pairing services to defend relevance.
OTG Pen Drive Market Segmentation
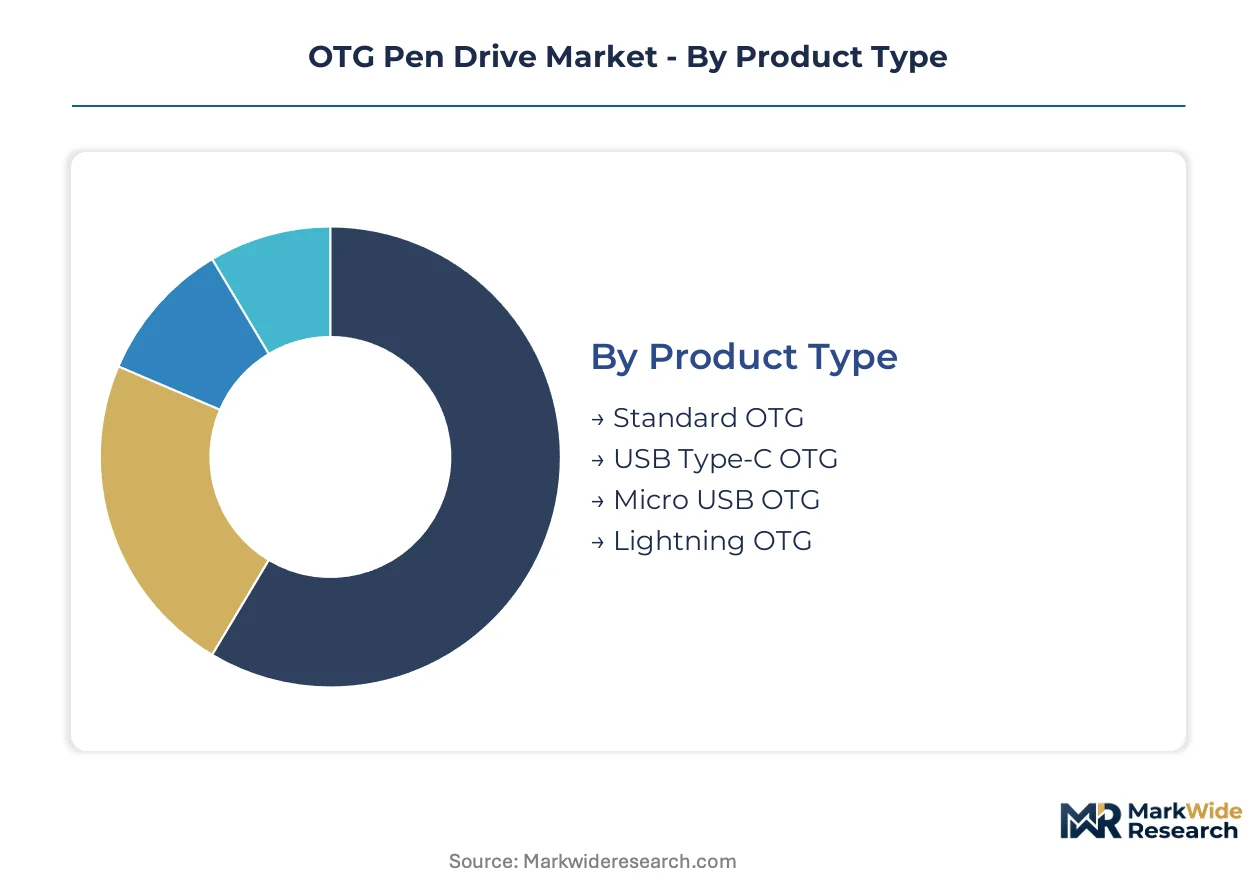
OTG pen drive purchasing patterns diverge sharply across interface standards, capacity tiers, and user workflows. Segmentation reveals where hardware margins concentrate versus where volume liquidates.
Product Type:
Interface transition cycles dictate inventory velocity, with legacy formats turning slowly while Type-C variants rotate fastest through distribution channels.
- Standard OTG:Dual USB-A and Micro USB configurations serve residual Android device bases in South Asia and sub-Saharan Africa. Demand concentrates in rural India and Nigeria where three-to-four-year smartphone replacement cycles extend connector relevance.
- USB Type-C OTG:Dominant format incorporating reversible USB-C and USB-A interfaces for direct smartphone-to-laptop workflows. Samsung Electronics and Xiaomi device portfolios in Vietnam and Indonesia drive replacement demand as OEMs complete port transitions.
- Micro USB OTG:Declining segment tethered to entry-level smartphone segments in Bangladesh and Kenya. BIS registration requirements in India accelerate formal channel exit for uncertified Micro USB imports.
- Lightning OTG:Bridge format serving iOS device ecosystems ahead of Apple's EU-mandated USB-C transition. Creative professionals in Brazil and Mexico adopt dual Lightning-Type-C variants for mixed-device households.
USB Type-C OTG anchors the volume base while Lightning OTG gains share at the steepest rate ahead of interface convergence.
Storage Capacity:
Cost-per-gigabyte curves reshape which capacity brackets penetrate professional versus mass-market segments.
- 8GB:Entry tier for basic document portability and SMS backup in price-sensitive segments. Nigeria and Kenya smartphone users adopt for contact and message migration between devices.
- 16GB:Transitional capacity for lightweight media storage and application sideloading. Indonesian e-commerce bundling programs capture volume from first-time OTG adopters.
- 32GB:Mid-tier sweet spot for photography enthusiasts and social media content creators. Vietnamese TikTok producers utilize for draft video staging before platform upload.
- 64GB:Professional entry point for 1080p video workflows and portable software libraries. Indian freelance videographers in Mumbai and Bangalore adopt for client deliverables.
- 128GB:Premium tier commanding disproportionate margins from 4K content creators and mobile journalists. TLC NAND density improvements enable price positioning competitive with entry-level portable SSDs.
32GB capacity anchors the volume base while 128GB climbs the fastest as creator workflows professionalize.
Application:
Use-case specificity determines performance requirements and corresponding controller and NAND flash specifications.
- Data Transfer:Core application enabling direct host-to-host file exchange without PC intermediaries. Indonesian and Vietnamese smartphone users bypass cloud latency for immediate peer-to-peer sharing.
- Backup & Storage:Archival workflows for contact lists, messages, and application data. Indian consumers utilize BIS-certified devices for compliance-sensitive personal data protection.
- Media Streaming:Direct playback of video libraries from OTG storage to smartphone displays. Brazilian commuters adopt high-capacity formats for offline entertainment during transit.
- Portable Software:Bootable operating systems and productivity applications executed directly from flash storage. IT professionals in Mexico deploy for field diagnostics and system recovery.
- Gaming Data:Mobile game asset storage and save-file portability across devices. Nigerian mobile esports participants utilize for tournament venue device switching.
Data Transfer anchors the volume base while Media Streaming expands most quickly as offline consumption patterns strengthen.
End User:
Technical sophistication and replacement frequency segment the customer base across consumer and professional tiers.
- Smartphone Users:Dominant segment encompassing mobile-first consumers across Southeast Asia and South Asia. Indonesian and Vietnamese users prioritize dual-interface compatibility for device-to-device workflows.
- Tablet Owners:Secondary segment with elevated capacity requirements for productivity and entertainment applications. Indian students and professionals adopt for document portability between tablets and institutional PCs.
- Laptop Users:Bridge segment utilizing OTG devices for ultrabook storage expansion and cross-platform file mobility. Brazilian remote workers deploy for hybrid office-home workflows.
- IT Professionals:Premium segment demanding industrial-temperature specifications and encryption capabilities. Field technicians in Mexico and Nigeria require extended operating ranges for infrastructure diagnostics.
Smartphone Users anchor the volume base while IT Professionals gain share fastest as enterprise mobility requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS registration requirements in India shape certification roadmaps across South Asia, while FCC emissions standards in the United States and CE marking under EU Radio Equipment Directive create divergent compliance timelines for multinational suppliers.
India
Smartphone users in Mumbai and Bangalore drive replacement demand as Samsung Electronics and Xiaomi complete USB Type-C port transitions. BIS compulsory registration schemes disqualify uncertified Micro USB imports, consolidating formal channel share among compliant domestic and multinational suppliers. Delhi-NCR electronics markets concentrate distribution volume for 128GB premium tiers serving freelance videographers.
Indonesia
TikTok content creators in Jakarta prioritize instant-sharing workflows over archival storage, elevating transfer-speed specifications in purchasing decisions. E-commerce bundling programs with smartphone OEMs capture disproportionate first-time OTG adoption volume. Surabaya and Bandung secondary cities expand addressable demand as mobile-first data workflows penetrate beyond Java Island.
Vietnam
Contract manufacturers diversify assembly operations from China to hedge supply chain exposure, concentrating production in Ho Chi Minh City industrial zones. Samsung Electronics device portfolios drive USB Type-C OTG replacement cycles at the fastest rate in Southeast Asia. Hanoi smartphone accessory markets liquidate residual Micro USB inventory ahead of formal channel exit.
United States
FCC electromagnetic emissions standards extend product certification timelines, compressing sell-through windows before successor interface standards emerge. Creative professionals in Los Angeles and New York adopt 1TB+ OTG formats for direct 4K footage offloading without laptop intermediaries. Amazon and Best Buy distribution channels prioritize USB4 controller integration for professional videographer segments.
Brazil
TikTok and YouTube content producers in São Paulo represent underserved volume for high-capacity OTG formats bypassing traditional retail markup. ANVISA alignment with international standards streamlines import pathways for CE-marked devices from Asian contract manufacturers. Rio de Janeiro commuter rail corridors drive offline media streaming adoption for transit entertainment consumption.
OTG Pen Drive Market Competitive Landscape
Capability concentration sits with vertically integrated NAND flash producers; scale advantage sits with contract assemblers distributing across fragmented retail channels. The vendor base stratifies across three tiers: captive memory foundries controlling wafer supply, brand-holding specialists designing controller firmware, and pure-play distributors managing regional logistics. Two dominant competitive moves define current positioning: backward integration into NAND flash production and accelerated USB-IF certification cycles to compress time-to-market.
Among vertically integrated memory producers, SanDisk and Samsung Electronics exemplify the capability-driven tier through captive NAND flash sourcing. Kingston Technology occupies a position bridging scale and specialization, anchoring enterprise-grade reliability positioning through industrial-temperature product lines. These three companies represent the structural fault line between margin control at the component level and channel reach at the distribution level.
| Leading Market Players |
|---|
| SanDisk |
| Kingston Technology |
| Samsung Electronics |
| Transcend Information |
| ADATA Technology |
| Toshiba Corporation |
| Sony Corporation |
| Lexar Media |
| Verbatim |
| Others |
Value Network & Pricing Analysis
The Shenzhen-Ho Chi Minh City freight corridor's container cost dynamics amplify pricing power for NAND flash producers while compressing margins for downstream assemblers, creating divergent price differentiation between captive-memory vendors and pure-play distributors across Southeast Asian retail channels.
Pricing Analysis
Price spreads between India and Vietnam retail channels exceed those between premium and standard tiers within single markets. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified industrial-grade products from uncertified imports and OEM-bundled economy units. Cost compression in 128GB TLC tiers is intensifying because Korean foundry output expansion outpaces creator-segment demand absorption. Nigerian smartphone users exhibit highest price sensitivity, while Mumbai freelance videographers accept premium positioning for USB4 controller integration.
Supply Chain Analysis
Extended payment terms from Ho Chi Minh City contract manufacturers to Taiwanese controller IC suppliers now stretch ninety days, straining working capital for pure-play assemblers. NAND flash wafer supply concentrates in South Korea and Taiwan, while final assembly draws from Vietnam and India. PCB substrate and connector plating feed from Chinese component ecosystems. Single-source vulnerability sits with Korean foundry allocation volatility during technology node transitions. Distribution runs through Jakarta and Lagos electronics markets alongside Amazon and Flipkart e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indonesian and Vietnamese smartphone OEMs through accessory bundling programs, squeezing standalone OTG vendor margins and favoring suppliers with direct OEM certification pathways.
For Market Incumbents: Insulate margin position through captive NAND flash sourcing and accelerated USB-IF certification cycles that compress new entrant time-to-market. Threat from cloud storage substitution intensifies among urban 5G subscribers. Investment in industrial-temperature product lines defends premium positioning against commodity erosion. For New Entrants and Emerging Players: Pursue direct-to-creator distribution in São Paulo and Lagos, bypassing traditional retail markup structures. Brazil's TikTok producer segment remains underpenetrated by incumbent channel strategies. White-label partnerships with regional smartphone OEMs unlock fastest volume scaling. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underutilized NAND flash controller IP and dormant CE marking portfolios. Long-term viability hinges on interface standardization timing and foundry supply security. Watch USB-IF specification release cadence as inflection signal for inventory revaluation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Certification Acceleration | Compresses competitor launch windows ahead of Type-C transition deadlines. |
| Industrial Temperature Product Line Extension | Captures premium positioning in Mexican oil field diagnostics verticals. |
| Direct-to-Creator Distribution Launch | Bypasses Jakarta retail markup for Indonesian TikTok content producers. |
| Backward Integration into NAND Flash | Secures wafer allocation priority during Korean foundry node transitions. |
| BIS Registration Compliance Investment | Disqualifies uncertified competitors from formal Indian distribution channels. |
Research Methodology
Desk research of USB-IF specification databases, BIS registration filings, and Southeast Asian customs records preceded structured interviews with NAND flash procurement directors, contract manufacturing executives, and Indonesian e-commerce category managers. Primary fieldwork with Vietnamese assembly plant operators and Indian electronics distributor principals validated secondary trade flow estimates. Bottom-up capacity modeling and top-down demand triangulation anchored volume forecasts.
Assumptions held fixed include USB Type-C port transition timelines at Samsung Electronics and Xiaomi, TLC NAND cost curves, and BIS enforcement intensity. The analytical framework modeled interface standard, capacity tier, end-use application, and geographic adoption pattern across the projection horizon. CAGRs derived from segment-level volume build-ups incorporating smartphone replacement cycles and creator workflow penetration rates. NAND flash wafer supply forecasts and OEM port roadmaps served as critical model inputs.
Macroeconomic conditions sit as an overlay; deviation in Indonesian rupiah volatility, Indian import tariff schedules, or Vietnamese industrial electricity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding interface transition velocity and foundry supply allocation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Global 3D Nand Flash Memory Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Germany Data Center Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Transparent Cache Market
Data Storage
Storage and Management Market
Data Storage
Digital Recording System Market
Data Storage
North America Next Generation Storage Market
Data Storage
Global Portable Data Storage Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Distributed Storage System Market