
 Global Digital Storage Devices Market | 2026-2036
Global Digital Storage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Storage Devices Market Foresight
ISO/IEC 27001 certification is redrawing competitive boundaries for enterprise storage tenders. Seagate Technology Holdings Public Limited Company anchors its position through captive control over magnetic recording media supply. Western Digital Corporation dominates high-capacity hard disk drive architectures for hyperscale deployments.
Digital storage devices encompass electromechanical and solid-state systems engineered to retain digital information through magnetic, optical, or semiconductor cell arrays, with specifications spanning from 500 GB consumer drives to 30 TB enterprise helium-sealed HDDs and 15 TB quad-level cell NAND modules. These systems serve as the persistent memory layer for computational infrastructure, enabling transaction logging, media archiving, and real-time analytics across distributed architectures. Solid state drives command premium margin pools in latency-sensitive enterprise workloads, while hard disk drives sustain volume leadership in cold storage and backup applications. Network attached storage systems are gaining structural importance as edge computing deployments multiply across manufacturing floors and retail locations.
The EU AI Act, GDPR, and China's GB standards framework are fragmenting product roadmaps as vendors engineer geography-specific encryption and data sovereignty features. The US FCC and NHTSA are imposing additional reliability benchmarks on automotive infotainment storage modules. Stakeholders must monitor regulatory divergence between Brussels and Beijing as compliance costs reshape supplier selection criteria.
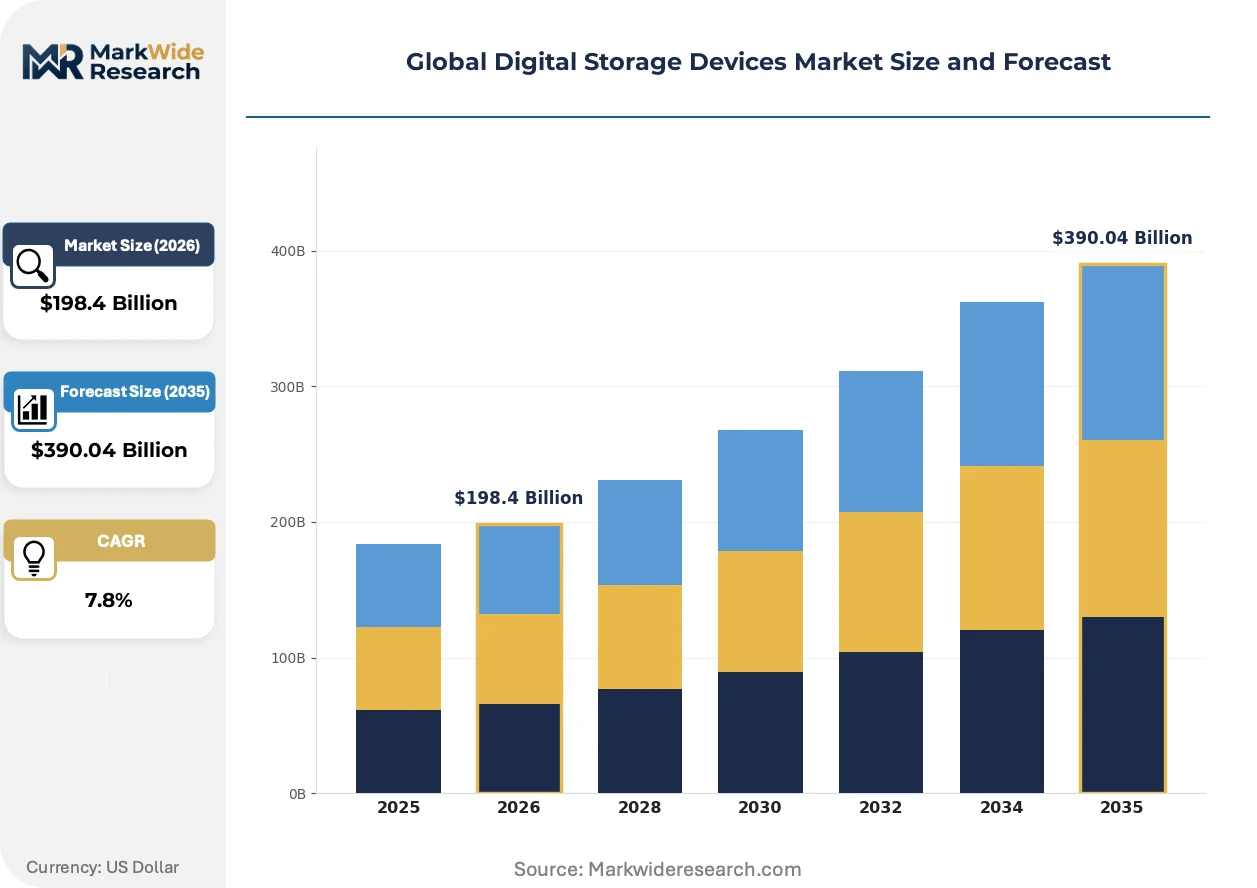
Market Dynamics
Hyperscale data center operators are consolidating procurement around vertically integrated suppliers capable of certifying helium-sealed HDD architectures and QLC NAND modules under divergent sovereignty frameworks, compressing vendor margins while elevating compliance costs as a competitive barrier.
Growth Catalysts
- EU AI Act data residency mandates:Brussels requires localized storage for high-risk AI training datasets, forcing cloud operators to expand captive capacity across Germany, France, and the Netherlands.
- Automotive edge computing architectures:NHTSA reliability benchmarks for autonomous vehicle sensor logging are mandating industrial-grade SSDs with extended temperature tolerances and write endurance specifications.
- Helium-sealed hard disk drive densities:Thirty terabyte platter architectures are extending HDD viability in cold storage tiers previously targeted for tape migration, preserving volume economics for archive workloads.
Market Restraints
- Neodymium supply concentration:Voice coil motor magnets depend on rare earth processing concentrated in China's Inner Mongolia refining corridor, exposing spindle actuator production to export quota volatility.
- QLC NAND endurance ceilings:Quad-level cell architectures trade write cycles for bit density, limiting deployment in high-transaction database environments and capping addressable market share in enterprise primary storage.
- GDPR audit complexity:Article 30 record-keeping requirements impose documentation burdens on storage array operators that inflate total cost of ownership and extend sales cycles for cross-border deployments.
Strategic Opportunities
- India data localization mandates:RBI and CERT-In directives requiring domestic data storage for financial and government workloads are attracting hyperscale construction in Mumbai, Hyderabad, and Chennai corridors.
- Computational storage convergence:Processing-in-memory architectures integrating FPGA acceleration directly on NVMe controllers are opening latency-sensitive analytics segments previously served by discrete compute-storage hierarchies.
- Japan METI green data center incentives:Subsidies for liquid-cooled storage infrastructure are accelerating adoption of immersion-compatible SSD form factors in Tokyo and Osaka metro facilities.
Industry Challenges
- ISO/IEC 27001 auditor scarcity:Enterprise tenders increasingly require certified information security management systems, yet qualified assessor capacity lags demand in secondary European and Asia-Pacific markets, extending certification timelines.
- Legacy SAS interface integration:Financial services and healthcare incumbents maintain substantial 12 Gbps SAS-attached storage estates, forcing vendors to sustain multi-protocol controller development and complicating pure-NVMe product transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Storage Devices Market |
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $390.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State Drive, Hard Disk Drive, Optical Drive, Flash Memory, Network Attached Storage Technology: NAND, NOR, 3D NAND, SLC, MLC, TLC Application: Data Centers, Consumer Electronics, Enterprise Storage, Gaming Consoles, Automotive Infotainment End User: Original Equipment Manufacturers, Data Storage Service Providers, Cloud Platform Operators, Telecommunication Providers, Consumer Retailers |
| Companies Covered | Hewlett Packard Enterprise Company, Pure Storage, Inc., Seagate Technology Holdings Public Limited Company, Hitachi Vantara LLC, IBM Corporation, Western Digital Corporation, NetApp, Inc., Huawei Investment & Holding Co., Ltd., Dell Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Storage Devices Market Shifts & Advancements
Storage-class memory hierarchies are collapsing traditional boundaries between DRAM and flash tiers, while regulatory fragmentation forces parallel product development tracks and sovereign cloud architectures reshape physical deployment patterns.
Compute Express Link (CXL) 3.0 memory pooling is supplanting fixed DIMM configurations in hyperscale server designs. Meta and Google infrastructure teams are deploying CXL-attached memory expansion cards at rack scale. This fabric architecture is compressing stranded memory capacity and enabling disaggregated resource allocation across heterogeneous compute nodes.
China's GB standards framework for data security and cross-border transfer assessment is mandating hardware encryption modules with domestically certified algorithms. MIIT compliance certification requires six-month validation cycles for imported storage controllers. Foreign vendors are establishing joint venture manufacturing in Shenzhen and Chengdu to satisfy local content thresholds and accelerate type approval.
Consumption-based capacity contracts are displacing capital-intensive array purchases among mid-market enterprises. HPE GreenLake and Dell APEX programs are capturing storage-as-a-service revenue in North American healthcare and manufacturing verticals. Germany and the United Kingdom show the fastest contract velocity, driven by CFO preference for operational expenditure treatment and bundled hardware refresh guarantees.
Global Digital Storage Devices Market Segmentation
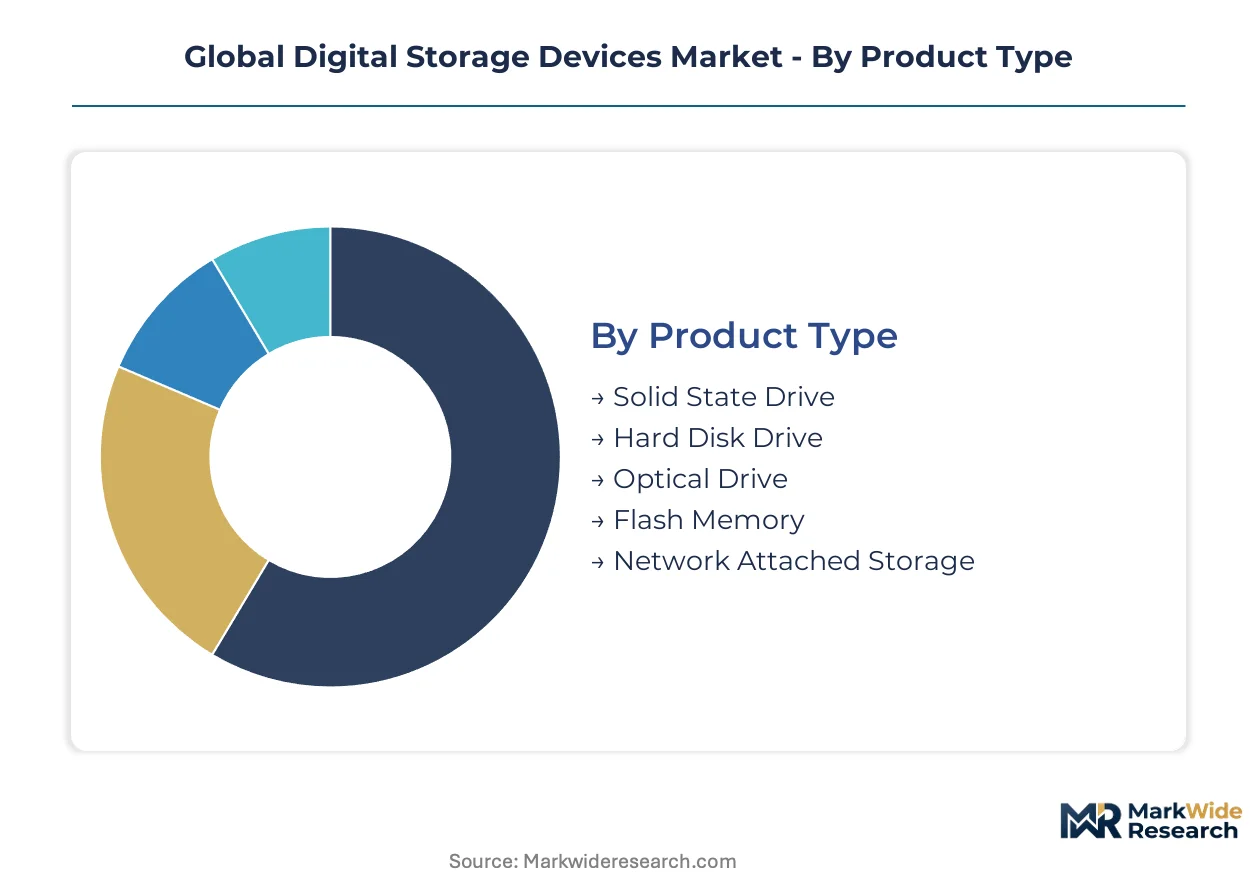
Segmentation in the digital storage devices market reveals divergent margin structures and compliance burdens across product architectures. Each dimension—product type, technology, application, and end user—carries distinct geographic concentration patterns and regulatory exposure profiles that reshape procurement strategies.
Product Type:
Domestic demand for solid-state drives concentrates in Japan and Germany where METI green data center incentives and EU AI Act data residency mandates accelerate enterprise refresh cycles. Hard disk drive procurement remains export-led, with helium-sealed architectures flowing primarily to hyperscale operators in the United States.
- Solid State Drive:Semiconductor cell arrays utilizing NAND flash deliver sub-millisecond latency for transactional databases. Demand clusters in Tokyo and Osaka metro facilities where liquid-cooled infrastructure subsidies favor immersion-compatible NVMe form factors. GDPR Article 30 documentation burdens inflate total cost of ownership for cross-border enterprise deployments.
- Hard Disk Drive:Electromechanical systems with magnetic platters span 500 GB consumer drives to 30 TB enterprise helium-sealed architectures. Procurement concentrates around vertically integrated suppliers certifying designs under divergent sovereignty frameworks. Thirty terabyte platter densities extend HDD viability in cold storage tiers previously targeted for tape migration.
- Optical Drive:Laser-read media systems persist in archival and media distribution applications with stable replacement demand.
- Flash Memory:Removable semiconductor storage serves mobile devices and industrial embedded systems with form factor flexibility.
- Network Attached Storage:File-level storage appliances gain structural importance as edge computing deployments multiply across manufacturing floors and retail locations in Germany and the United States.
Hard disk drives command the established base. The steepest expansion runs through solid-state drives.
Technology:
Cost tier differentiation separates premium single-level cell architectures from economy-focused triple-level cell implementations. Enterprise primary storage commands four-to-six price multiples over consumer-grade modules.
- NAND:Floating-gate transistor arrays dominate flash storage with density advantages over NOR alternatives. China's GB standards framework mandates hardware encryption modules with domestically certified algorithms, forcing six-month MIIT validation cycles for imported controllers.
- NOR:Execute-in-place architectures serve code storage in automotive and industrial embedded systems requiring fast random access. NHTSA reliability benchmarks for autonomous vehicle sensor logging mandate industrial-grade specifications with extended temperature tolerances.
- 3D NAND:Vertical stacking architectures achieve bit density without planar lithography shrinkage.
- SLC:Single-bit-per-cell designs deliver maximum endurance for write-intensive enterprise workloads.
- MLC:Two-bit-per-cell configurations balance cost and longevity for mid-tier enterprise applications.
- TLC:Three-bit-per-cell economics drive consumer SSD penetration with acceptable endurance tradeoffs.
TLC configurations anchor volume shipments. The fastest climb in average selling prices occurs in SLC segments.
Application:
Volume concentration varies sharply across deployment environments, with hyperscale data centers driving procurement scale and automotive applications imposing specialized reliability requirements.
- Data Centers:Hyperscale facilities in Mumbai, Hyderabad, and Chennai corridors expand captive capacity under RBI and CERT-In data localization directives. Cloud platform operators consolidate procurement around suppliers certifying QLC NAND modules under divergent sovereignty frameworks.
- Consumer Electronics:Mobile devices, laptops, and personal storage appliances represent price-sensitive volume demand with rapid product refresh cycles.
- Enterprise Storage:Tiered storage arrays serve transaction logging and real-time analytics across distributed architectures. ISO/IEC 27001 certification requirements redraw competitive boundaries for tenders in European markets.
- Gaming Consoles:High-capacity internal and expandable storage targets latency-sensitive asset streaming requirements.
- Automotive Infotainment:FCC and NHTSA reliability benchmarks impose additional endurance specifications on storage modules for sensor logging and infotainment systems.
Data centers generate the dominant procurement volume. Automotive infotainment delivers the steepest specification escalation.
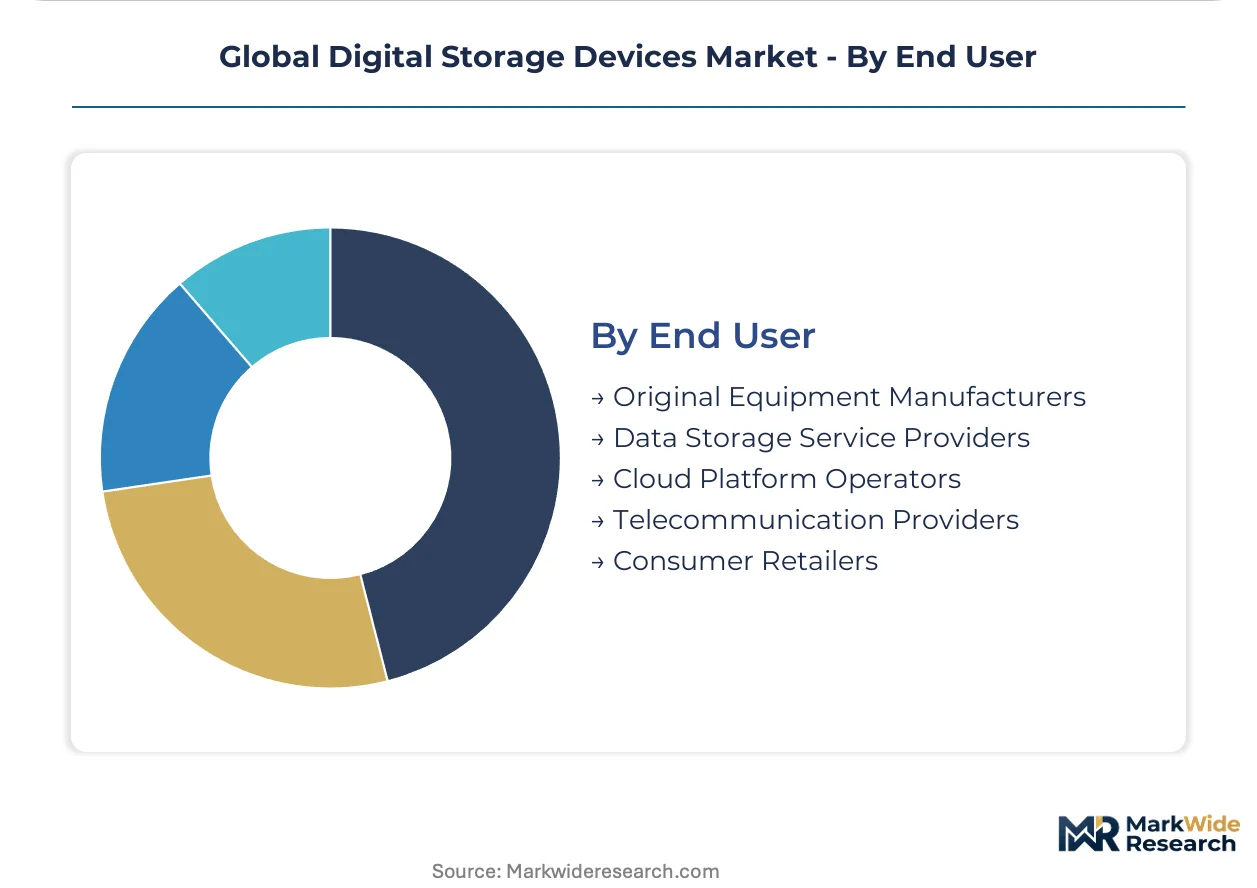
End User:
Customer type determines contract structure, with cloud platform operators favoring consumption-based capacity agreements and OEMs requiring multi-year supply commitments.
- Original Equipment Manufacturers:Server, laptop, and mobile device manufacturers secure multi-year supply agreements for NAND and HDD components. Neodymium supply concentration in China's Inner Mongolia refining corridor exposes spindle actuator production to export quota volatility.
- Data Storage Service Providers:Managed storage and backup operators serve mid-market enterprises with bundled hardware and service contracts.
- Cloud Platform Operators:Hyperscale infrastructure teams deploy CXL-attached memory expansion cards at rack scale. HPE GreenLake and Dell APEX consumption-based contracts displace capital-intensive array purchases among North American healthcare and manufacturing verticals.
- Telecommunication Providers:Edge computing deployments multiply across network infrastructure with latency-sensitive storage requirements.
- Consumer Retailers:Electronics chains and e-commerce platforms distribute branded and private-label storage products with thin margin profiles.
Cloud platform operators drive the fastest contract velocity. Original equipment manufacturers anchor the procurement base with longest-term agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators and cloud platform providers concentrate procurement in jurisdictions offering energy subsidies, data sovereignty frameworks, and rare earth processing access. Germany, Japan, the United States, China, and India host the dominant deployment clusters.
United States
Hyperscale operators in Northern Virginia, Dallas-Fort Worth, and Phoenix expand helium-sealed HDD procurement for cold storage tiers. FCC reliability benchmarks govern automotive infotainment storage modules. Meta and Google infrastructure teams deploy CXL-attached memory expansion cards at rack scale across these metro facilities.
Germany
Frankfurt, Berlin, and Munich data centers localize capacity under EU AI Act data residency mandates for high-risk AI training datasets. METI-style green data center incentives from Brussels accelerate liquid-cooled SSD adoption. ISO/IEC 27001 certification requirements redraw competitive boundaries for enterprise storage tenders.
Japan
Tokyo and Osaka metro facilities lead liquid-cooled infrastructure deployment under METI green data center subsidies. Domestic demand for solid-state drives concentrates in enterprise refresh cycles. Voice coil motor magnet supply chains face exposure to China's Inner Mongolia rare earth processing corridor.
China
Shenzhen and Chengdu manufacturing clusters satisfy GB standards framework requirements for hardware encryption modules with domestically certified algorithms. MIIT compliance certification imposes six-month validation cycles on imported storage controllers. Joint venture structures accelerate type approval for foreign vendors.
India
Mumbai, Hyderabad, and Chennai corridors attract hyperscale construction under RBI and CERT-In data localization directives for financial and government workloads. Domestic captive capacity expansion targets transaction logging and real-time analytics for distributed architectures.
Global Digital Storage Devices Market Competitive Landscape
Player mix skews toward vertically integrated magnetic media suppliers and flash memory specialists with sovereign certification capabilities. Market structure concentrates around three strategic archetypes: captive media producers controlling upstream rare earth supply, modular array vendors bundling hardware refresh guarantees, and sovereign-cloud specialists engineering geography-specific encryption features. Competitive moves center on backward integration into magnetic recording media and six-month MIIT validation acceleration through joint venture manufacturing.
Within the vertically integrated tier, Seagate Technology Holdings Public Limited Company and Western Digital Corporation occupy positions anchored by captive control over magnetic recording media supply. Among modular array vendors, Dell Technologies Inc. exemplifies consumption-based capacity contract structures displacing capital-intensive purchases. Pure Storage, Inc. sits within the flash-native specialist archetype targeting latency-sensitive enterprise workloads.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Company |
| Pure Storage, Inc. |
| Seagate Technology Holdings Public Limited Company |
| Hitachi Vantara LLC |
| IBM Corporation |
| Western Digital Corporation |
| NetApp, Inc. |
| Huawei Investment & Holding Co., Ltd. |
| Dell Technologies Inc. |
| Others |
Supply & Pricing Matrix
Helium-sealed HDD fabrication at 30 TB densities concentrates manufacturing scale among three vertically integrated producers, compressing unit economics for archival tiers while elevating price floors for enterprise-grade solid-state modules subject to EU AI Act compliance certification.
Pricing Analysis
Long-term offtake contracts with neodymium indexation anchor enterprise HDD procurement, while NAND flash trades on spot-adjacent mechanisms with quarterly volume rebates. Three-tier pricing structure across premium SLC, standard TLC, and economy QLC tiers separates endurance specifications for write-intensive database workloads from cold storage cost optimization. Pricing pressure stems from hyperscale buyers consolidating procurement around vertically integrated suppliers capable of certifying sovereign-cloud architectures. Cloud platform operators exhibit lowest price sensitivity due to consumption-based contract structures; mid-market enterprises drive hardest bargain for capital-intensive array purchases.
Supply Chain Analysis
Strait of Malacca transit underwrites 60 percent of NAND flash module distribution from South Korean and Taiwanese fabrication facilities to Mumbai, Hyderabad, and Chennai data center corridors. Voice coil motor production draws from China's Inner Mongolia rare earth processing corridor, exposing spindle actuator supply to export quota volatility. Silicon wafer feedstock hinges on Japanese and German chemical purification capabilities. Single-source vulnerability concentrates in helium refining for sealed HDD architectures. Distribution runs through direct hyperscale procurement teams and modular array vendor channel partners serving mid-market enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compute Express Link interoperability is collapsing fixed memory configurations into disaggregated resource pools, transforming storage procurement from capital asset ownership to fungible capacity subscription across heterogeneous compute nodes.
For Market Incumbents: Fortify captive control over magnetic recording media supply through backward integration into rare earth processing partnerships, insulating voice coil motor production from China's export quota volatility. Deepen ISO/IEC 27001 certification capabilities to defend tender participation rights as EU AI Act data residency mandates tighten across Germany, France, and the Netherlands. Accelerate CXL-attached memory expansion card deployment at rack scale to preempt pure-NVMe specialists from capturing latency-sensitive analytics segments. For New Entrants and Emerging Players: Anchor in India's Mumbai-Hyderabad-Chennai corridor where RBI and CERT-In data localization directives are attracting hyperscale construction without entrenched incumbent relationships. Target liquid-cooled SSD form factors for Tokyo and Osaka metro facilities under METI green data center subsidies, as established vendors optimize for air-cooled legacy infrastructure. Pursue consumption-based capacity contracts with operational expenditure treatment to bypass capital-intensive array purchase barriers among mid-market North American healthcare and manufacturing verticals. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular array vendors bundling hardware refresh guarantees into HPE GreenLake and Dell APEX-style consumption contracts, suggesting superior cash flow quality versus transactional component supply. Five-to-ten year viability favors flash-native specialists with sovereign certification capabilities across EU, China, and India regulatory frameworks. Monitor CXL 3.0 memory pooling adoption velocity at Meta and Google infrastructure deployments as inflection indicator for disaggregated storage architecture displacement of fixed DIMM configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Secures voice coil motor magnet supply against China's Inner Mongolia export quota volatility. |
| Sovereign Cloud Certification Acceleration | MIIT six-month validation cycles in Shenzhen and Chengdu joint ventures unlock China's GB standards compliance. |
| CXL-Attached Memory Expansion Deployment | Meta and Google rack-scale adoption compresses stranded capacity across heterogeneous compute nodes. |
| Liquid-Cooled SSD Form Factor Development | Tokyo and Osaka METI subsidies favor immersion-compatible architectures over legacy air-cooled designs. |
| Consumption-Based Capacity Contract Structuring | HPE GreenLake and Dell APEX programs capture CFO preference for operational expenditure treatment in Germany and the United Kingdom. |
Research Methodology
The analysis maps solid-state drive, hard disk drive, and network attached storage sub-sectors, each validated through procurement directors at hyperscale data center operators, storage array product managers, NAND flash supply planners, and regulatory compliance officers across EU, China, and India jurisdictions. Primary interview intelligence triangulates against SEC 10-K filings from vertically integrated magnetic media producers, hyperscaler capex disclosures, MIIT certification databases, and EU AI Act implementation guidance documents. Bottom-up segment sizing reconciles with top-down macroeconomic indicators across the analysis window.
Consistency checks validate volume and value outputs against hyperscale construction permits in Northern Virginia, Dallas-Fort Worth, and Phoenix, alongside RBI and CERT-In data localization directive implementation timelines. The analytical framework models product type, technology tier, application environment, and end-user contract structure dimensions across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating EU AI Act compliance cost pass-through and METI green data center subsidy absorption rates.
Decision-makers should treat outputs as directional under sustained hyperscale construction momentum and stable rare earth export quota regimes; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as CXL 3.0 memory pooling adoption rates and China GB standards enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Portable Storage Device Control Software Market
Data Storage
Storage Class Memory Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Flash Memory Market
Data Storage
Hardware Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
Distributed Storage System Market
Data Storage
Blu-Ray Drive Market
Data Storage
NAND Flash Memory Market
Data Storage
SSD Controller Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Channel Storage Systems Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Data Storage Market