
 Universal Flash Storage Market | 2026-2036
Universal Flash Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Universal Flash Storage Market Intelligence
The increasing integration of UFS into automotive electronics and enterprise storage is restructuring the market's traditional reliance on the smartphone segment. Samsung Electronics leverages its significant manufacturing scale and early technology leadership to maintain a dominant position. SK Hynix competes through focused R&D in next-generation NAND flash memory for UFS 4.0 applications. Micron Technology differentiates with its portfolio targeting data center operators and automotive Tier-1 suppliers.
Universal Flash Storage is a high-performance, low-power storage interface standard designed for embedded systems and removable cards. It utilizes a full-duplex LVDS serial interface, enabling simultaneous read and write operations to boost throughput. The UFS 4.0 product type represents the fastest-growing segment, driven by performance demands in premium smartphones and virtual reality devices. While smartphones remain the largest application, the enterprise storage segment offers higher margin potential for specialized vendors.
Product development adheres to specifications set by the JEDEC Solid State Technology Association, ensuring interoperability across devices. Compliance with environmental regulations like the EU's RoHS directive and China's GB standards for electronics governs material use and market entry. Component suppliers must navigate the strategic trade-off between investing in premium UFS 4.0 capacity and servicing the high-volume, cost-sensitive UFS 3.1 market.
Market Dynamics
The market's central dynamic is the bifurcation between performance-driven and cost-sensitive segments. This split forces component suppliers to balance high-cost investment in UFS 4.0 production against the need to service the vast, lower-margin UFS 3.1 volume market.
Growth Catalysts
- Automotive Integration:Demand for high-bandwidth storage in advanced driver-assistance systems and complex infotainment platforms is pulling UFS adoption into the automotive sector, creating a new, high-reliability application vertical.
- Consumer Electronics Demand:The appetite for high-capacity storage for 8K video and mobile gaming in devices from manufacturers in China and South Korea propels volume demand for larger UFS modules.
- JEDEC Standardization:The formal release and industry-wide adoption of the UFS 4.0 specification provides a clear performance roadmap, encouraging OEMs to upgrade flagship devices to differentiate on speed and responsiveness.
Market Restraints
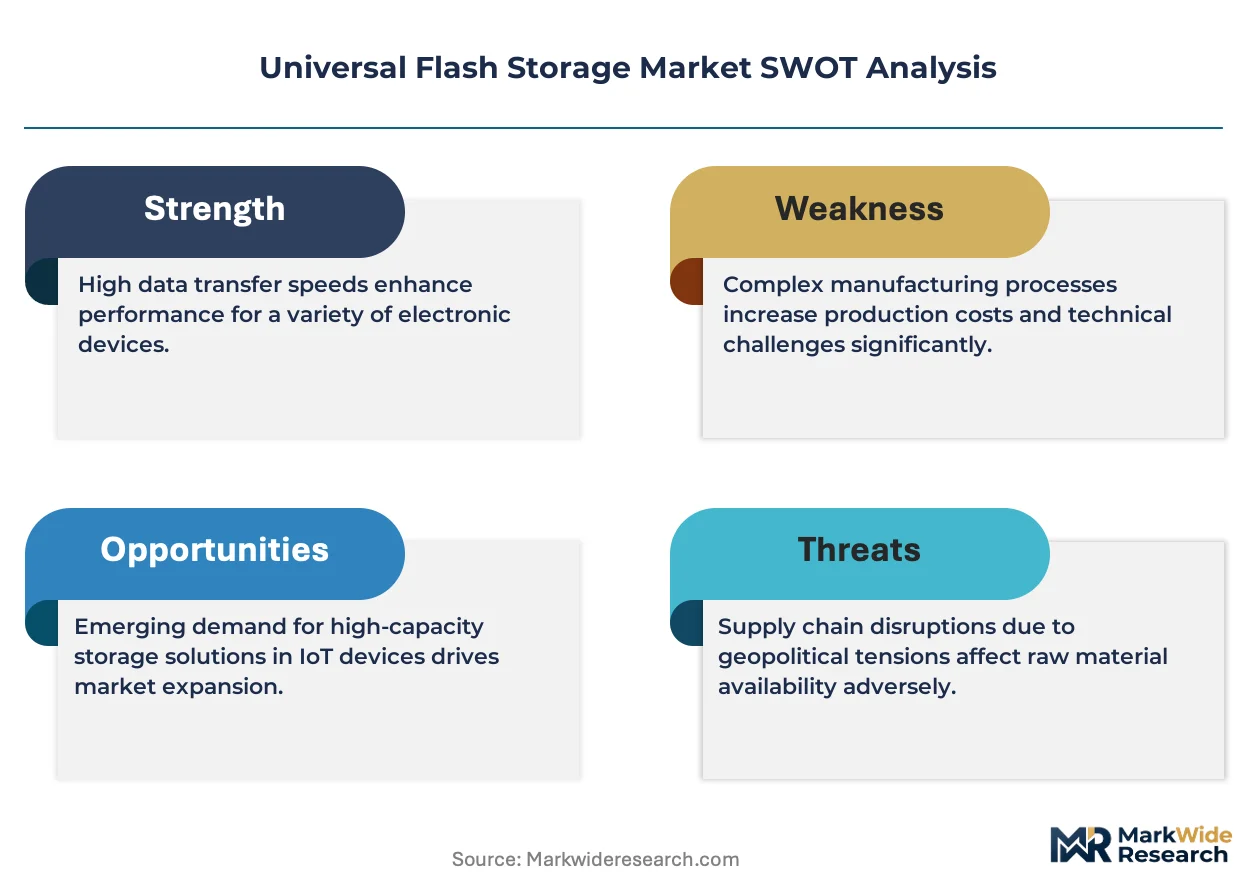
- Fabrication Cost:The immense capital expenditure required to build and equip semiconductor fabs for next-generation 3D NAND flash memory, the core component of UFS, limits the number of suppliers and constrains supply.
- Legacy Technology Inertia:In highly cost-sensitive electronics, particularly entry-level smartphones and IoT devices, the lower price of older eMMC storage solutions slows the transition to UFS despite its performance advantages.
- Supply Chain Concentration:The geographic consolidation of advanced NAND flash manufacturing in a few countries, primarily South Korea, exposes the entire UFS supply chain to significant geopolitical and logistical risks.
Strategic Opportunities
- Enterprise and Edge Storage:Specialized UFS solutions designed for low-power, high-endurance applications in edge computing gateways, network equipment, and data center boot drives represent a high-margin growth frontier.
- Mid-Range Smartphone Penetration:As UFS 3.1 costs decline, there is a significant opportunity to displace eMMC in mid-range smartphones across emerging markets in Latin America and Southeast Asia, expanding the addressable market.
- On-Device AI Convergence:Integrating UFS with on-chip AI accelerators to create faster, more efficient data pipelines for machine learning tasks on-device opens new possibilities for smart cameras, vehicles, and personal assistants.
Industry Challenges
- Regulatory Compliance:Navigating the divergent and evolving environmental regulations, such as the EU's RoHS directive and China's GB standards, adds complexity and cost to material sourcing and product design.
- Investment Dilemma:UFS suppliers face a difficult strategic choice between allocating capital to leading-edge UFS 4.0 capacity for the premium market or optimizing production for the high-volume, cost-sensitive UFS 3.1 segment.
- System-Level Integration:Ensuring flawless performance and compatibility of UFS controllers with a growing variety of System-on-Chip platforms from different vendors requires extensive and costly validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Universal Flash Storage Market |
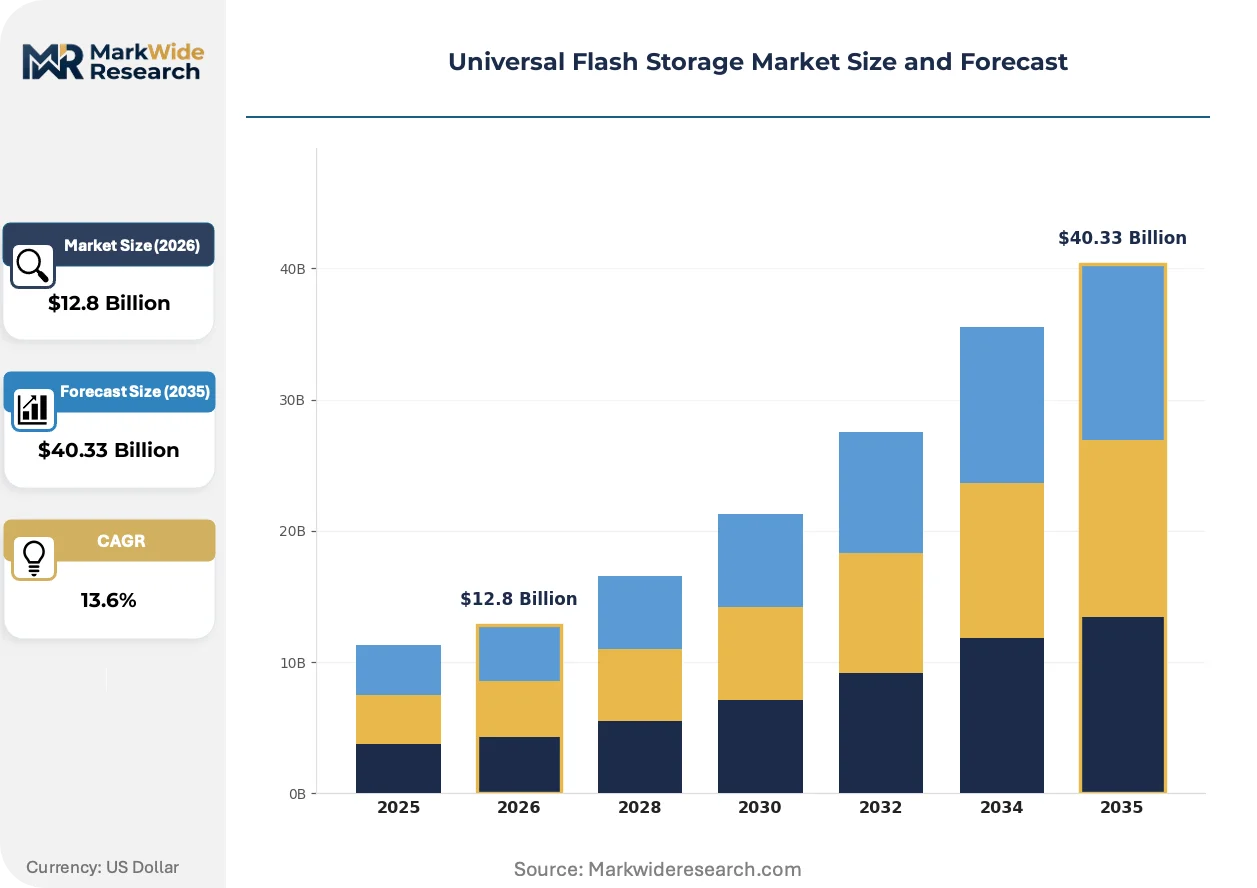
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $40.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UFS 2.0, UFS 3.0, UFS 3.1, UFS 4.0 Application: Smartphones, Digital Cameras, Tablets, Virtual Reality Devices, Enterprise Storage End User: Consumer Electronics Manufacturers, Telecommunications Firms, Data Center Operators, Automotive Tier-1 Suppliers Deployment: Embedded Systems, Removable Storage Devices, Cloud Data Infrastructure, Automotive Electronics |
| Companies Covered | Samsung Electronics, Western Digital, SK Hynix, Micron Technology, Kioxia Holdings, Kingston Technology, ADATA Technology, Transcend Information, Phison Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Universal Flash Storage Market Strategic Shifts & Innovations
Innovation in the Universal Flash Storage market is defined by a dual pursuit of peak performance and extreme power efficiency. This focus influences everything from low-level interface standards to high-level system integration strategies, responding to demands from next-generation mobile and automotive applications.
The UFS 4.0 standard introduces multi-lane gear scaling to dynamically adjust performance. Premium smartphone and augmented reality device makers are rapidly adopting this feature to manage power budgets. This technology is automating power management at the storage interface level, improving battery life in high-performance devices without requiring complex software overhead from the main processor.
China's national dual carbon goals and related GB standards for electronics are compelling changes in manufacturing. These policies mandate reductions in the energy consumption of NAND flash fabrication and promote the use of more sustainable materials in UFS module construction. The consumer electronics segment is most affected, requiring suppliers to provide transparent lifecycle carbon data for devices sold in the Chinese market.
A significant shift in procurement behavior sees device manufacturers moving beyond simple capacity metrics. They now specify storage using holistic performance scores that blend speed, latency, and power use under specific workloads like mobile gaming. This disrupts traditional purchasing models and is most prominent among high-end Android device manufacturers in South Korea and China, who demand application-specific performance validation.
Universal Flash Storage Market Segmentation

The Universal Flash Storage market's segmentation reflects diverse performance and cost requirements across various electronic applications. Understanding these distinct segments is crucial for component suppliers to align product development with specific end-user needs and market demand.
Product Type:
Buyer decisions for Universal Flash Storage product types primarily revolve around a trade-off between performance specifications and unit cost.
- UFS 4.0:This advanced standard offers peak sequential read/write speeds, leveraging multi-lane LVDS for enhanced data throughput. Demand concentrates among premium smartphone manufacturers in South Korea and China, driven by complex virtual reality applications and 8K video processing.
- UFS 3.1:Delivering robust performance at a more accessible price point, this product type balances speed with cost-effectiveness. High-volume consumer electronics manufacturers, particularly for mid-range smartphones in Southeast Asia and Latin America, drive significant demand for UFS 3.1 modules.
- UFS 2.0:This foundational UFS standard provides reliable performance for cost-sensitive embedded applications. Digital cameras and entry-level IoT devices frequently incorporate UFS 2.0 solutions.
- UFS 3.0:Offering an intermediate performance tier, UFS 3.0 bridges the gap between older standards and the latest UFS 3.1 specifications. Certain tablet models and infotainment systems utilize UFS 3.0 for balanced performance.
Volume sits with UFS 3.1; growth tilts toward UFS 4.0.
Application:
The application landscape for Universal Flash Storage dictates specific requirements for speed, capacity, and endurance.
- Smartphones:These devices represent the largest volume application for UFS, requiring high-speed storage for operating systems, apps, and multimedia content. Manufacturers in China and South Korea integrate UFS extensively to support advanced mobile gaming and high-resolution video recording.
- Enterprise Storage:Specialized UFS solutions cater to data center boot drives, edge computing gateways, and network equipment, prioritizing endurance, reliability, and low power consumption. Data center operators seek UFS for its robust performance in mission-critical, high-margin environments.
- Digital Cameras:UFS enhances burst photography and 4K/8K video recording capabilities in high-end digital cameras. Professional photographers benefit from faster image processing and storage.
- Tablets:Tablet performance improves significantly with UFS, supporting demanding applications and multitasking. Premium tablet brands integrate UFS for a smoother user experience.
- Virtual Reality Devices:UFS provides the low-latency, high-bandwidth storage essential for immersive VR experiences. Rapid data access is critical for rendering complex virtual environments.
Smartphones command the largest share of UFS consumption, while enterprise storage exhibits the steepest expansion trajectory.
End User:
End-user segments define distinct procurement patterns and technical specifications for Universal Flash Storage components.
- Consumer Electronics Manufacturers:These companies integrate UFS into a wide array of devices including smartphones, tablets, and digital cameras, demanding cost-effective, high-volume solutions. Manufacturers in China and Vietnam drive significant procurement volumes for their mass-market products.
- Automotive Tier-1 Suppliers:Supplying advanced infotainment systems and ADAS units, these suppliers require UFS solutions with extreme reliability, extended temperature ranges, and long-term support. German and Japanese automotive suppliers emphasize UFS for critical vehicle electronics.
- Telecommunications Firms:UFS supports network infrastructure components and specialized communication devices for telecommunications firms. Edge computing applications within telecom networks utilize UFS for local data processing.
- Data Center Operators:These operators deploy UFS in server boot drives and specialized storage appliances, valuing endurance and consistent performance. Hyperscale data centers increasingly consider UFS for efficiency gains.
Consumer electronics manufacturers account for the majority of UFS units, with automotive Tier-1 suppliers seeking higher-margin, specialized solutions.
Deployment:
The deployment method of Universal Flash Storage influences its form factor, ruggedization, and integration complexity.
- Embedded Systems:UFS is integrated directly onto the PCB of devices like smartphones and tablets, functioning as the primary internal storage. This deployment emphasizes compact size and high-speed data transfer within the device's architecture.
- Automotive Electronics:UFS modules are specifically designed for the harsh conditions of vehicles, supporting infotainment, navigation, and ADAS. Reliability and thermal management are paramount for UFS deployed in automotive systems.
- Removable Storage Devices:While less common for UFS, some high-performance memory cards or external drives could leverage the UFS interface. These applications demand user-swappable, robust storage.
- Cloud Data Infrastructure:UFS finds niche applications in cloud environments for boot drives or specialized caching layers within servers. Its low power profile benefits energy-efficient data centers.
Embedded systems represent the foundational deployment of UFS, while automotive electronics drive innovation in ruggedized solutions.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China, such as the Yangtze River Delta, drive significant concentration for Universal Flash Storage manufacturing and consumption. This global market sees varied demand patterns and regulatory influences across key countries. Geopolitical considerations and technological advancements shape regional investment in UFS fabrication and adoption.
China
Chinese manufacturers in Shenzhen demand high-capacity UFS for 8K video and mobile gaming applications. The country's GB standards for electronics and dual carbon goals influence sustainable material use. Shenzhen's robust consumer electronics hub integrates UFS extensively into flagship smartphones.
South Korea
South Korea's premium smartphone segment requires UFS 4.0 for advanced features and virtual reality devices. The Ministry of Trade, Industry and Energy supports semiconductor R&D initiatives. Gyeonggi Province, a major semiconductor fabrication region, focuses on next-generation NAND flash memory development.
Germany
German automotive Tier-1 suppliers integrate UFS into advanced driver-assistance systems and complex infotainment platforms. The KBA sets stringent reliability standards for in-vehicle electronics. Stuttgart's automotive industry cluster drives demand for high-end, ruggedized UFS solutions.
Vietnam
Vietnamese consumer electronics manufacturers seek cost-effective UFS 3.1 modules for high-volume mid-range devices. The government offers investment incentives to attract electronics assembly plants. Ho Chi Minh City's burgeoning electronics manufacturing sector produces a wide array of UFS-enabled products.
Universal Flash Storage Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting diverse market demands. The market features highly integrated device manufacturers alongside specialized NAND flash developers. Portfolio diversification into automotive and data center applications represents a significant competitive move. Capacity expansion in advanced NAND flash production also defines market rivalry.
At the scale-driven end, Samsung Electronics exemplifies a dominant integrated device manufacturer with extensive fabrication capabilities. SK Hynix, a South Korean-based semiconductor company, occupies a position as a key innovator in next-generation NAND flash memory. Micron Technology, an American corporation, anchors the market for specialized solutions targeting data center operators and automotive Tier-1 suppliers.
| Leading Market Players |
|---|
| Samsung Electronics |
| Western Digital |
| SK Hynix |
| Micron Technology |
| Kioxia Holdings |
| Kingston Technology |
| ADATA Technology |
| Transcend Information |
| Phison Electronics |
| Others |
Cost & Logistics Intelligence
Vertical integration into NAND flash manufacturing anchors the supply position of dominant players like Samsung, enabling them to exert significant pricing power across UFS product tiers. This extensive control over core component production directly influences market pricing dynamics.
Pricing Analysis
Premium pricing for UFS 4.0 modules with short lead times reflects the advanced technology and rapid adoption by flagship device makers. Transactional, per-unit pricing dominates the market, with performance specifications and volume scale serving as key differentiation drivers. Pricing softness for UFS 3.1 stems from intense competition in the high-volume, cost-sensitive mid-range smartphone segment. Automotive Tier-1 suppliers exhibit the lowest price sensitivity due to stringent reliability and longevity requirements.
Supply Chain Analysis
Workforce availability for highly specialized semiconductor engineers in South Korea and China significantly impacts the UFS supply chain. Geographic supply concentration in these two countries, particularly for advanced 3D NAND flash memory, creates single-source vulnerability. The supply chain draws from specialized controllers and advanced packaging materials. Geopolitical and logistical risks pose a structural threat to consistent supply. Distribution runs through direct sales channels to large OEMs and specialized component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Universal Flash Storage market presents a cost-of-compliance story, where adherence to environmental regulations like the EU's RoHS directive creates a significant barrier to entry for non-compliant component suppliers. This regulatory moat favors established players with robust material sourcing and manufacturing processes.
For Market Incumbents:Anchor existing UFS 3.1 market share by optimizing production efficiencies and securing long-term contracts with high-volume consumer electronics manufacturers in Vietnam. Defend premium UFS 4.0 margins through continuous R&D investment in next-generation NAND flash memory, mitigating the threat of margin erosion from emerging competitors. Expand capacity in Gyeonggi Province to meet growing demand from South Korean premium smartphone makers.
For New Entrants and Emerging Players:Begin with specialized UFS solutions for enterprise storage, targeting low-power, high-endurance applications in edge computing gateways. The mid-range smartphone segment in Southeast Asia offers a penetrable market for cost-effective UFS 3.1 modules. A focused go-to-market angle should emphasize application-specific performance validation and robust technical support to differentiate from established players.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized NAND flash developers or vertically integrated memory solution providers with strong IP portfolios. Long-term viability over a 5-10 year window hinges on deep expertise in advanced manufacturing processes and strong relationships with automotive Tier-1 suppliers. A signal to watch is the sustained increase in UFS content per vehicle, indicating deeper automotive integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced NAND | Expanding manufacturing capacity in Gyeonggi Province ensures supply for premium UFS 4.0 modules demanded by South Korean OEMs. |
| Targeted R&D in Next-Gen NAND | Focused research by SK Hynix into next-generation NAND flash memory enhances performance for UFS 4.0 applications. |
| Portfolio Diversification into Enterprise | Micron Technology's expansion into data center boot drives addresses the high-margin enterprise storage segment. |
| Proactive Regulatory Compliance | Adherence to China's GB standards for electronics facilitates market entry and ensures material sustainability for consumer electronics. |
| Application-Specific Performance Validation | Providing tailored performance scores for mobile gaming supports high-end Android device manufacturers in China. |
Research Approach
JEDEC Solid State Technology Association specifications, company annual reports from leading semiconductor manufacturers, and trade association data formed the secondary backbone for this market analysis. Primary research involved combining insights from interviews with OEM engineers, supply chain managers, and automotive Tier-1 procurement specialists. This dual approach facilitated bottom-up data collection and top-down validation, ensuring comprehensive market understanding.
Historical trendline analysis, coupled with a forward-looking assessment of technological advancements, underpinned the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end user, deployment method, and regional regulatory cluster. Compound Annual Growth Rates were derived by projecting future demand based on anticipated adoption rates and content-per-device increases. Semiconductor fab utilization rates served as a key industry-specific forecast input.
Underlying measurement precision varies by segment; the smartphone and automotive electronics segments carry tighter precision than others due to established reporting. Forecasts reflect assumptions regarding technological evolution and market demand. Geopolitical shifts impacting NAND flash supply or significant shifts in consumer electronics shipment forecasts represent key risk factors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Next Generation Data Storage Market
Data Storage
OTG Pen Drive Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
APAC SSD Caching Market
Data Storage
Object-Based Storage Market
Data Storage
Storage and Management Market
Data Storage
Blu-Ray Drive Market
Data Storage
Data Center Ssds Market
Data Storage
NOR Flash Market
Data Storage
External Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Ireland Data Center Storage Market