
 Portable Air Purifier Market | 2026-2036
Portable Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Air Purifier Market Analysis
AHAM Verifide certification is bifurcating the competitive landscape into tested performers and uncertified imports. Coway Co., Ltd. leverages its Seoul-based R&D campus to sustain filtration efficiency leadership across Asian markets. Dyson Ltd. anchors its premium positioning through proprietary solid-state pollutant sensing integrated into cylindrical tower designs. Koninklijke Philips N.V. competes on modular filter ecosystems that reduce lifetime ownership costs for European households.
Portable air purifiers are self-contained electromechanical devices designed to reduce airborne particulate matter, volatile organic compounds, and biological contaminants within enclosed spaces, typically employing multi-stage filtration media rated between 99.97% efficiency at 0.3 microns and activated carbon adsorption layers for gas-phase pollutant removal. Their primary commercial purpose centers on improving indoor air quality in environments where centralized HVAC filtration proves inadequate or unavailable. HEPA-based product types command the dominant revenue share due to established consumer trust and healthcare facility procurement standards, while UV-C segments attract faster growth from post-pandemic institutional sterilization protocols. Hybrid technology architectures capture expanding margin pools as manufacturers combine electrostatic precipitation with traditional media filtration to extend filter replacement intervals.
The EPA enforces clean air delivery rate disclosure under AHAM standards, while the EU Green Deal's indoor environment quality directives push member states toward mandatory energy labeling for residential air treatment appliances. China's GB/T 18801 standard administered by SAMR mandates formaldehyde removal testing that shapes product development priorities for manufacturers targeting domestic distribution. Stakeholders must monitor evolving ozone emission thresholds from ionizer technologies as California Air Resources Board restrictions propagate to other state-level jurisdictions.
Market Dynamics
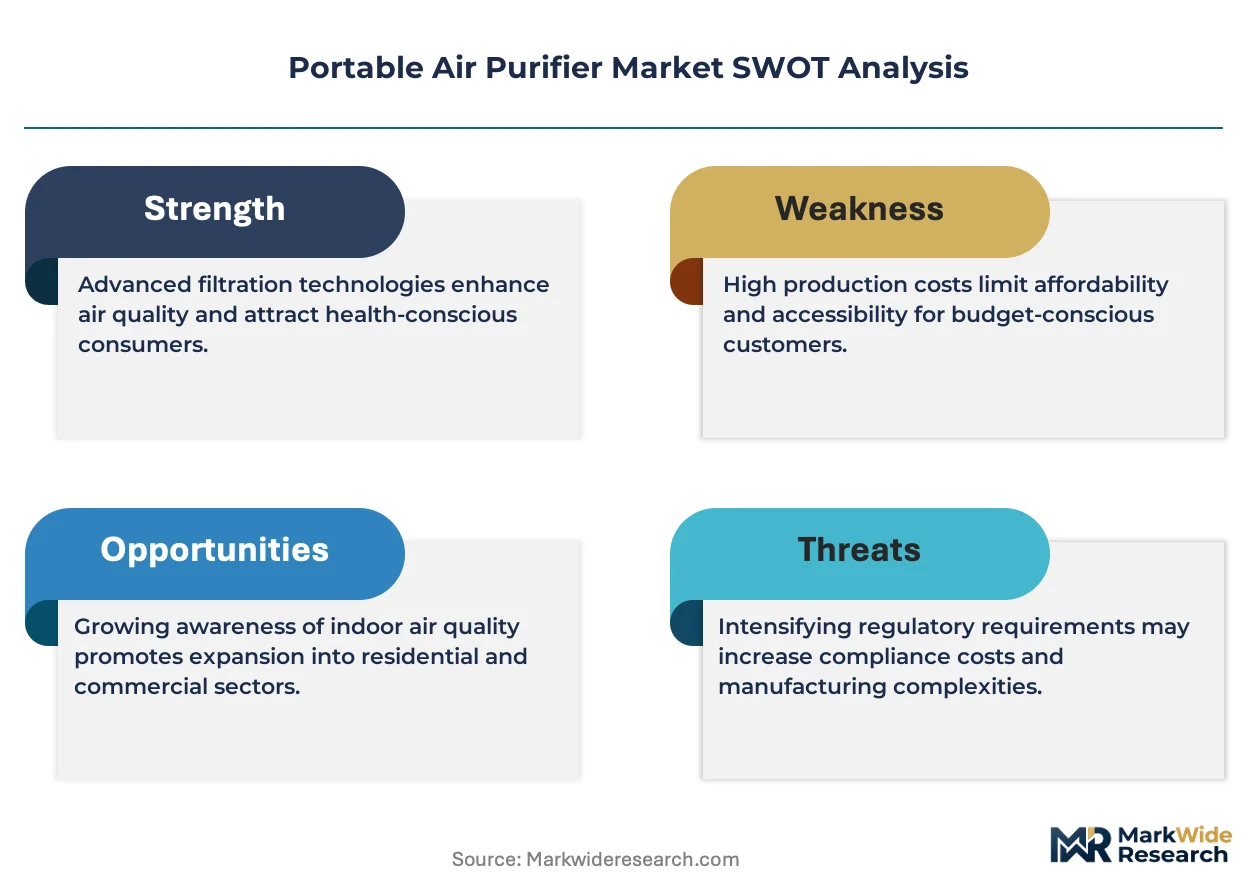
AHAM Verifide certification is compressing margins for uncertified imports while elevating tested performers, creating a bifurcation that rewards filtration efficiency investments and penalizes commodity positioning.
Growth Catalysts
- EPA Clean Air Delivery Rate Enforcement:Stricter disclosure mandates under AHAM standards compel manufacturers to validate performance claims, accelerating replacement cycles among quality-conscious residential buyers in the United States.
- China's GB/T 18801 Formaldehyde Testing:SAMR-mandated removal benchmarks reshape product development priorities for domestic distribution, filtering out underperforming units from tier-one city retail channels.
- Post-Pandemic Institutional Sterilization Protocols:Healthcare facilities and educational institutions specify UV-C augmentation in procurement tenders, expanding addressable demand beyond traditional HEPA replacement markets.
Market Restraints
- Activated Carbon Input Volatility:Coconut shell and coal-based adsorption media face supply concentration in Southeast Asian processing hubs, exposing manufacturers to raw material cost swings.
- California Air Resources Board Ozone Thresholds:Ionizer emission restrictions propagate to additional state jurisdictions, forcing design modifications that degrade electrostatic precipitation efficiency or trigger compliance-driven SKU rationalization.
- Centralized HVAC Upgrade Substitution:Commercial building operators in developed markets prioritize whole-building filtration retrofits over portable unit deployment, capping enterprise segment expansion.
Strategic Opportunities
- EU Green Deal Energy Labeling Mandates:Member state directives toward mandatory efficiency disclosure for residential air treatment appliances create first-mover advantages for manufacturers with established testing infrastructure.
- India Tier-Two Urban Expansion:Deteriorating seasonal air quality indices in secondary cities like Lucknow and Jaipur outpace centralized infrastructure development, opening distribution white space beyond saturated Delhi and Mumbai markets.
- Hybrid Electrostatic-HEPA Convergence:Combined architectures extend filter replacement intervals, enabling subscription-based consumable revenue models that improve lifetime customer value metrics.
Industry Challenges
- AHAM Certification Timeline Compression:Third-party testing backlogs delay product launches by 4-8 months, forcing manufacturers to sequence market entry around laboratory capacity constraints rather than demand signals.
- Filter Ecosystem Integration Complexity:Modular designs require backward compatibility across three to five hardware generations, constraining industrial design freedom and inflating SKU management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Air Purifier Market |
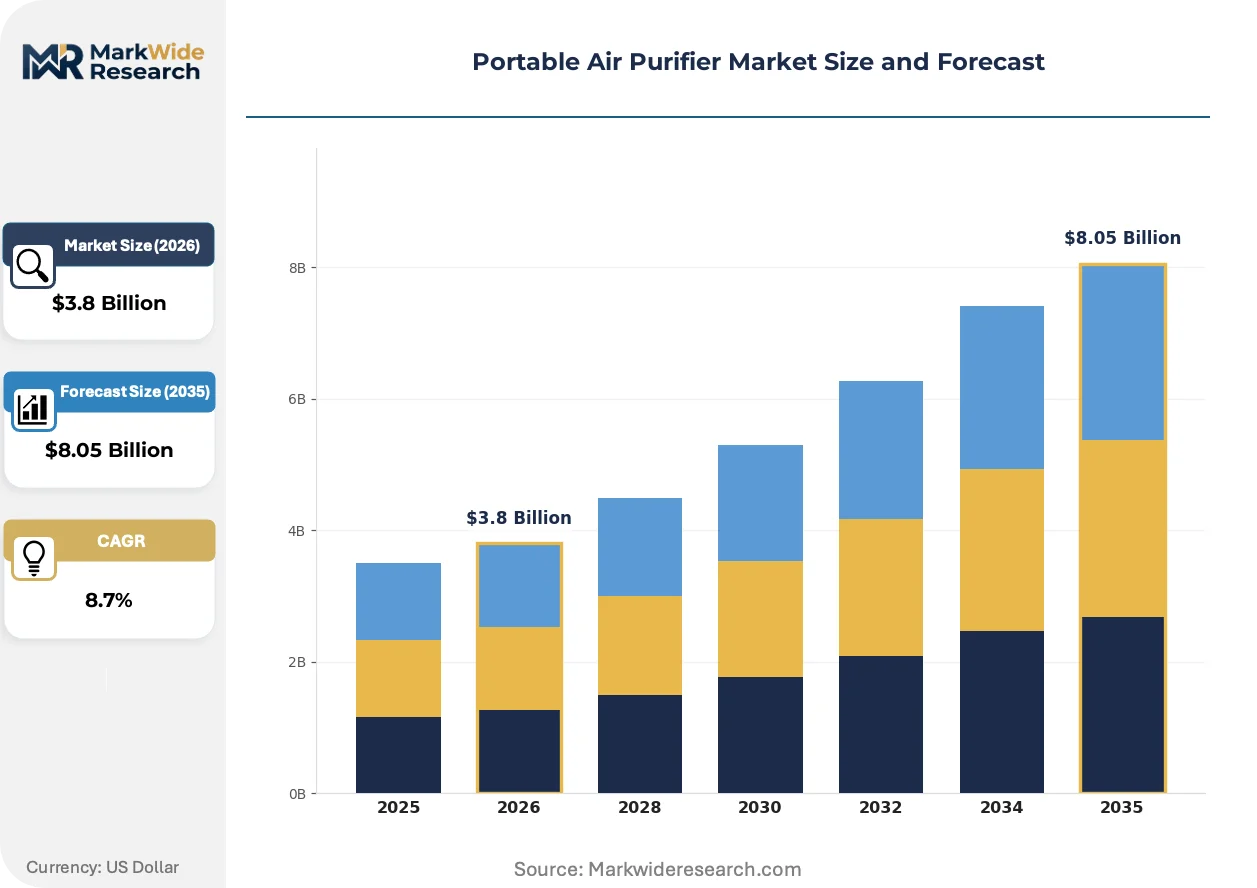
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, UV-C, Ionizer Technology: Filtration, Adsorption, Electrostatic, Hybrid End User: Households, Offices, Vehicles, Hospitals Application: Dust Removal, Odor Elimination, Allergen Reduction, Virus Filtration |
| Companies Covered | Sharp Corporation, Coway Co., Ltd., Samsung Electronics Co., Ltd., Blueair AB, Dyson Ltd., LG Electronics Inc., Koninklijke Philips N.V., Honeywell International Inc., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Air Purifier Market Emerging Trajectories
Solid-state sensing architectures and electrostatic hybridization are compressing form factors while expanding measurable pollutant categories, redefining performance benchmarks and procurement criteria simultaneously.
Photoelectric particulate sensors with laser-based light scattering detection are miniaturizing. Residential buyers in compact urban apartments in Seoul and Tokyo prioritize desk-sized units below 30 centimeters in height. This dimensional compression is miniaturizing the addressable market boundary, enabling bedside and automotive applications that traditional tower designs cannot penetrate.
REACH restrictions on fluorinated greenhouse gases in cooling circuits indirectly elevate air purifier relevance as building operators seek non-refrigerant indoor climate solutions. European commercial procurement frameworks now weight air treatment appliances in green building certification schemes. F-Gas Regulation compliance costs are redirecting HVAC capital toward standalone filtration in Germany and France.
Real-time air quality data integration is reshaping purchase timing and channel selection. Middle-class consumers in Beijing and Shanghai monitor municipal PM2.5 networks via smartphone applications, triggering immediate e-commerce transactions when indices exceed 150 AQI. This behavior concentrates demand spikes during winter heating seasons, straining fulfillment infrastructure and compressing inventory planning horizons for direct-to-consumer brands.
Portable Air Purifier Market Segmentation
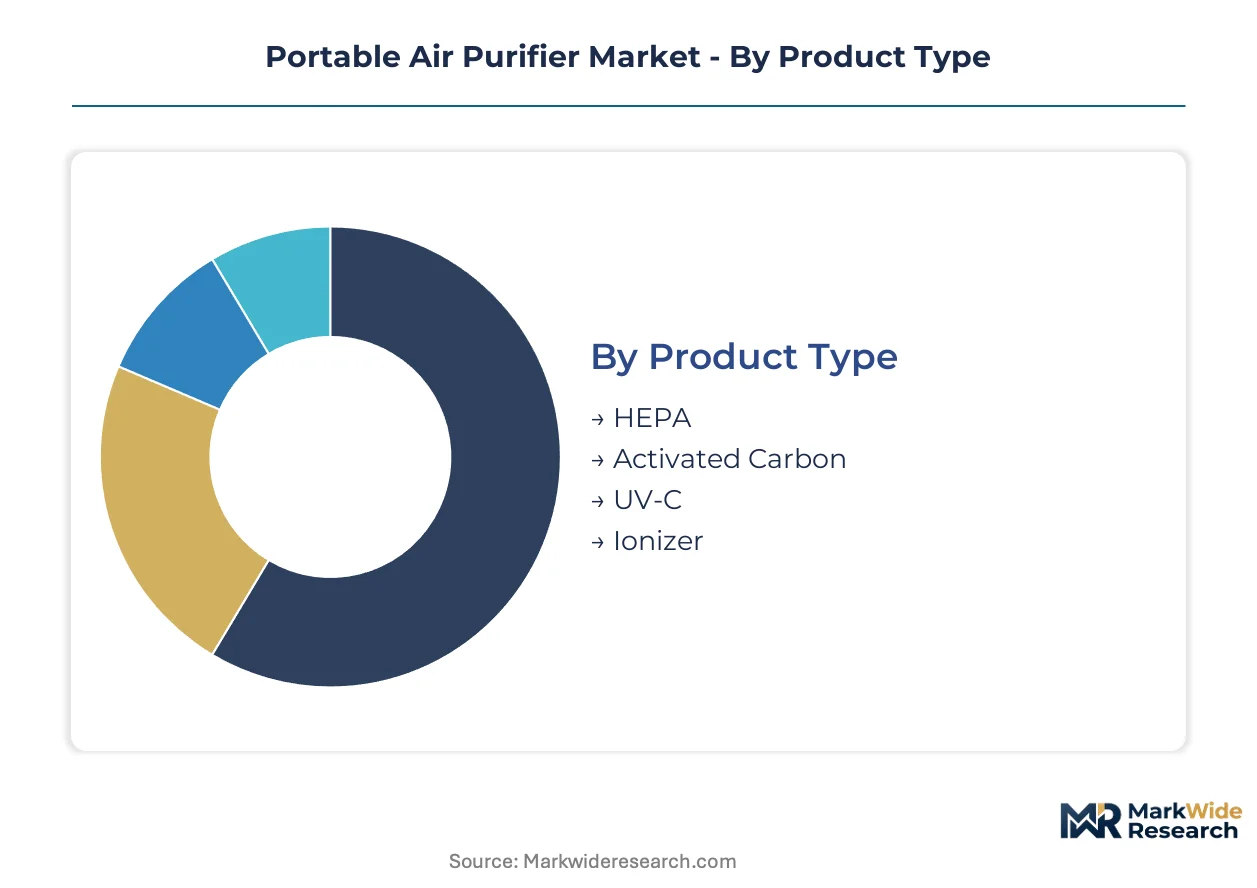
Portable air purifier segmentation reveals how substitution pressures from HVAC upgrades and competing indoor air quality solutions concentrate risk across specific product architectures. Manufacturers must align R&D priorities with segment-specific certification requirements and end-user procurement protocols to defend margin positions.
Product Type:
HEPA-based units face the strongest substitution threat from whole-building filtration retrofits in commercial real estate, while UV-C segments benefit from institutional sterilization mandates that portable formats uniquely satisfy.
- HEPA:Multi-stage mechanical filtration media rated at 99.97% efficiency at 0.3 microns dominates residential procurement in the United States where EPA AHAM disclosure mandates elevate certified units. Hospital procurement standards in Germany and France reinforce specification lock-in despite HVAC upgrade competition.
- Activated Carbon:Coconut shell and coal-based adsorption layers target gas-phase pollutant removal including formaldehyde and volatile organic compounds. Demand concentrates in China's tier-one cities where SAMR GB/T 18801 testing mandates reshape retail availability; coconut shell supply concentration in Southeast Asian processing hubs exposes manufacturers to input cost volatility.
- UV-C:Ultraviolet germicidal irradiation augmentation attracts post-pandemic institutional tenders.
- Ionizer:Electrostatic precipitation technologies confront California Air Resources Board ozone emission thresholds propagating to additional state jurisdictions.
HEPA retains volume leadership; UV-C holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium hybrid architectures from commoditized single-mechanism units, with electrostatic convergence commanding margin premiums through extended filter replacement intervals.
- Filtration:Traditional HEPA and activated carbon media remain the baseline cost tier for price-sensitive residential buyers in India and Southeast Asia.
- Adsorption:Specialized carbon formulations for formaldehyde and VOC targeting occupy the mid-tier in Chinese and European markets.
- Electrostatic:Precipitation technologies without mechanical media reduce consumable costs but face regulatory pressure on ozone byproduct emissions.
- Hybrid:Combined electrostatic-HEPA architectures extend filter replacement intervals by 40-60% through pre-charging of particulate matter. European commercial procurement frameworks under EU Green Deal directives weight these systems in green building certification schemes; subscription-based consumable revenue models improve lifetime customer value metrics for manufacturers with established testing infrastructure.
Filtration dominates unit shipments; hybrid architectures capture expanding margin pools.
End User:
Application context determines performance certification requirements, with hospitals and vehicles imposing the most stringent specification barriers that filter out uncertified competitors.
- Households:Urban residential buyers in Seoul, Tokyo, and Beijing prioritize compact form factors below 30 centimeters for bedside and desk placement. Real-time PM2.5 monitoring via smartphone applications triggers demand spikes during winter heating seasons, straining direct-to-consumer fulfillment infrastructure.
- Offices:Commercial building operators in developed markets increasingly substitute portable units for whole-building HVAC filtration retrofits, capping enterprise segment expansion in Germany and France where F-Gas Regulation compliance costs redirect capital toward standalone filtration.
- Vehicles:Automotive cabin air purification requires miniaturized solid-state sensing and 12V power compatibility.
- Hospitals:Healthcare facility procurement tenders specify UV-C augmentation and AHAM Verifide certification as mandatory qualification criteria, creating specification moats that uncertified imports cannot penetrate.
Households generate the highest unit volumes; hospitals impose the steepest qualification barriers.
Application:
Customer type differentiation separates health-driven allergen and virus filtration from aesthetic odor elimination, with clinical applications commanding price premiums through regulatory validation requirements.
- Dust Removal:Particulate matter reduction for PM2.5 and PM10 dominates baseline residential functionality in urban India and China where seasonal air quality deterioration drives replacement cycles.
- Odor Elimination:Activated carbon-dependent gas-phase removal targets kitchen and pet environments in Japanese and European households.
- Allergen Reduction:HEPA-based pollen and dander filtration attracts health-conscious buyers in the United States and Australia with established seasonal allergy patterns; pediatrician recommendations in these markets elevate specification sensitivity beyond price-only comparison.
- Virus Filtration:Post-pandemic institutional procurement prioritizes UV-C augmentation and sub-micron capture validation for influenza and respiratory pathogen mitigation. Educational facilities in South Korea and Japan specify these capabilities in public tender documents, expanding addressable demand beyond traditional healthcare replacement markets.
Dust removal anchors baseline demand; virus filtration is climbing the fastest on institutional sterilization protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of AHAM disclosure standards and China's SAMR certification mandates are restructuring competitive access across major demand centers. Regulatory divergence between jurisdictions creates compliance complexity for multinational manufacturers.
United States
Residential buyers in California and the Northeast prioritize AHAM Verifide certification as EPA disclosure mandates elevate tested units. The California Air Resources Board enforces ozone emission thresholds that filter out non-compliant ionizer technologies. Chicago and Dallas-Fort Worth retail channels concentrate demand for HEPA-based systems during wildfire seasons.
China
Middle-class households in Beijing and Shanghai trigger demand spikes via real-time PM2.5 monitoring applications when indices exceed thresholds. SAMR administers GB/T 18801 formaldehyde removal testing that shapes domestic product development priorities. Manufacturing clusters in Guangdong and Jiangsu provinces supply filtration media to tier-one city distribution networks.
Germany
Healthcare procurement tenders in Bavaria and North Rhine-Westphalia specify UV-C augmentation for institutional sterilization protocols. The EU Green Deal's energy labeling directives push manufacturers toward efficiency disclosure for residential appliances. Berlin and Frankfurt commercial operators substitute portable units for F-Gas Regulation compliance-driven HVAC capital reallocation.
India
Seasonal air quality deterioration in Delhi-NCR and Mumbai drives replacement cycles among urban residential buyers. The Bureau of Indian Standards develops domestic certification frameworks as imports face technical barrier scrutiny. Secondary cities including Lucknow and Jaipur outpace infrastructure development, opening distribution white space beyond saturated metros.
South Korea
Compact form factors below 30 centimeters dominate Seoul and Busan apartment demand for bedside and desk placement. Educational facilities specify virus filtration capabilities in public tender documents. Daegu-Gyeongbuk industrial zones manufacture solid-state sensing components for miniaturized residential units.
Portable Air Purifier Market Vendor Landscape
Player mix skews toward diversified electronics conglomerates with established appliance distribution networks, supplemented by specialized air treatment firms with filtration-focused R&D campuses. Three strategic archetypes dominate: Seoul and Osaka-based conglomerates leveraging vertical manufacturing integration, European premium specialists commanding certification-driven margin premiums, and Chinese scale players optimizing cost structures for emerging market penetration. Competitive moves concentrate on hybrid technology licensing partnerships and AHAM certification infrastructure investments.
Within the diversified electronics tier, Sharp Corporation and Samsung Electronics Co., Ltd. exemplify conglomerate positioning through established consumer appliance channels. Coway Co., Ltd. anchors the specialized filtration segment with Seoul-based R&D concentration. Dyson Ltd. occupies the premium-tier vector through proprietary sensing integration and cylindrical industrial design. Koninklijke Philips N.V. represents modular ecosystem strategies that reduce lifetime ownership costs for European households.
| Leading Market Players |
|---|
| Sharp Corporation |
| Coway Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Blueair AB |
| Dyson Ltd. |
| LG Electronics Inc. |
| Koninklijke Philips N.V. |
| Honeywell International Inc. |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at HEPA media manufacturing plants in Guangdong and Jiangsu provinces anchors cost structures across the portable air purifier value chain, compressing price floors for uncertified imports while elevating premiums for AHAM Verifide units. This scale concentration simultaneously tightens raw material procurement leverage and widens the certification-driven spread between tested performers and commodity alternatives.
Pricing Analysis
Certification level creates the primary spread between AHAM Verifide units and uncertified alternatives, with three-tier pricing structure across premium, standard, and economy levels reflecting filtration efficiency investments. Brand premium and geographic delivery cost differentiate Coway and Dyson positioning from Chinese scale players in India and Southeast Asia. Cost compression in the economy tier is intensifying because coconut shell activated carbon input volatility exposes margin structures. Price-sensitive residential buyers in tier-two Indian cities drive volume procurement, while hospital procurement committees in Germany and France exhibit minimal price elasticity.
Supply Chain Analysis
Inventory lead times for HEPA media extend 4-8 months due to third-party testing backlogs, forcing manufacturers to sequence launches around laboratory capacity rather than demand signals. Manufacturing concentration centers on China, South Korea, and Vietnam for filtration media, with Germany and Japan supplying precision sensing components. Coconut shell activated carbon from Southeast Asian processing hubs and solid-state laser sensors from Daegu-Gyeongbuk industrial zones constitute critical input dependencies. Single-source vulnerability in AHAM-certified testing infrastructure represents the dominant structural risk. Distribution runs through established appliance retail networks in developed markets and direct-to-consumer e-commerce in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable air purifier market exhibits cyclical recovery characteristics as seasonal air quality deterioration in South Asia and East Asia triggers replacement cycles. Winter heating season demand spikes in Beijing, Delhi, and Seoul concentrate purchasing decisions within compressed windows.
For Market Incumbents: Shield filtration efficiency leadership through backward integration into HEPA media manufacturing in Guangdong and Jiangsu provinces. Accelerate AHAM certification infrastructure investments to compress testing timelines and outpace laboratory capacity constraints that delay product launches. Counter HVAC upgrade substitution in German and French commercial real estate by emphasizing F-Gas Regulation compliance advantages of standalone portable units.
For New Entrants and Emerging Players: Anchor in India's tier-two urban expansion, where Lucknow and Jaipur outpace centralized infrastructure development and distribution white space exceeds saturated Delhi-NCR and Mumbai markets. Target compact form factors below 30 centimeters for Seoul and Tokyo apartment demand, leveraging solid-state sensing component availability from Daegu-Gyeongbuk industrial zones. Pursue direct-to-consumer channel strategies with real-time PM2.5 monitoring integration to capture demand spikes triggered by municipal air quality applications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized filtration firms with established R&D campuses over diversified electronics conglomerates facing appliance channel commoditization. Long-term viability rests on hybrid electrostatic-HEPA architectures that enable subscription-based consumable revenue models and extend filter replacement intervals. Acquisition targets should demonstrate AHAM Verifide certification infrastructure and backward compatibility across three to five hardware generations. Monitor California Air Resources Board ozone threshold propagation as the critical inflection signal for ionizer technology obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| AHAM Certification Infrastructure Investment | Third-party testing capacity locks out uncertified competitors from US retail channels. |
| Hybrid Electrostatic-HEPA Product Launch | Combined architectures extend filter intervals and enable subscription revenue models. |
| Backward Integration into Filtration Media | Captive HEPA manufacturing in Guangdong insulates against raw material cost volatility. |
| Direct-to-Consumer Channel Expansion | Real-time AQI integration captures demand spikes in Beijing and Shanghai winter seasons. |
| Compact Form Factor Development | Sub-30cm designs penetrate Seoul and Tokyo bedside applications tower units cannot reach. |
Methodological Framework
Initial hypotheses were tested against primary input from product development executives at filtration specialists, regulatory affairs leads navigating AHAM and SAMR certification pathways, hospital procurement managers specifying UV-C augmentation, and retail category buyers at appliance distributors. These perspectives were refined against secondary validation from EPA AHAM disclosure filings, SAMR GB/T 18801 testing records, EU Green Deal energy labeling directives, and customs trade data tracking activated carbon input flows. Bottom-up unit shipment estimates triangulated with top-down market value reconstructions across the analysis window.
Variance decomposition across product type, technology architecture, end-user application, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate modeling throughout the forecast period, incorporating hospital sterilization protocol adoption curves, seasonal AQI-driven replacement cycles, and F-Gas Regulation compliance cost trajectories as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EPA enforcement intensity and continued SAMR formaldehyde testing mandates; material deviation in regulatory stringency or HVAC substitution rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Industrial Controllers Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
ECG Sensor Market