
 NAND Flash Market | 2026-2036
NAND Flash Market Size, Share, and Industry Trends Forecast 2026-2036
NAND Flash Market Analytics
OEM direct procurement channels is reconfiguring how memory suppliers engage enterprise buyers, bypassing traditional distributor layers. Samsung Electronics leverages captive wafer capacity to secure volume commitments from server manufacturers. SK hynix anchors high-bandwidth memory portfolios alongside NAND to deepen data center relationships. Micron Technology competes on geographic diversification, operating fabrication facilities across Singapore, Japan, and the United States.
NAND flash constitutes non-volatile storage built from floating-gate or charge-trap transistors organized in memory cell arrays, with 3D architectures now stacking over 200 layers vertically to achieve terabit-scale densities in a single die. Its primary commercial purpose centers on persistent data retention in devices requiring fast read-write cycles without power. The 3D NAND product category dominates manufacturing investment as layer counts escalate and yield economics improve, while the SSD application segment captures the largest margin pool as enterprise and client replacements of hard disk drives accelerate. Triple-Level Cell technology occupies the volume sweet spot between cost-per-bit and endurance for consumer and mainstream enterprise workloads.
South Korea's METI-aligned export controls on advanced fabrication equipment, China's SAMR antitrust reviews of memory supply consolidation, and the United States Commerce Department foreign direct product rules collectively constrain capacity expansion timelines and cross-border technology flows. These frameworks force buyers to qualify second-source suppliers and push manufacturers toward regionally contained supply footprints. Stakeholders must monitor how layer-count roadmaps intersect with equipment availability restrictions to assess which suppliers can sustain cost-down trajectories.
Market Dynamics
Equipment availability restrictions on advanced lithography and etch systems are compressing capacity expansion timelines, forcing manufacturers to prioritize yield optimization over greenfield fabrication investments.
Growth Catalysts
- Hyperscale data center buildouts:Cloud infrastructure operators in the United States and China are absorbing high-density SSD volumes as HDD replacement cycles accelerate in enterprise storage racks.
- MIIT dual carbon mandates:China's energy-efficiency standards for semiconductor fabrication are driving process innovation in low-power 3D NAND architectures and water recycling systems.
- Charge-trap cell architectures:The transition from floating-gate to charge-trap transistor designs enables higher layer stacking with improved vertical scaling economics.
Market Restraints
- Extreme ultraviolet lithography dependency:ASML equipment lead times exceeding 18 months constrain layer-count roadmaps for sub-15nm node transitions.
- South Korean supply concentration:Pyeongtaek and Hwaseong clusters account for disproportionate global bit output, creating geographic vulnerability to seismic or geopolitical disruption.
- QLC endurance limitations:Quad-Level Cell technology remains unsuitable for write-intensive workloads, capping addressable market expansion in enterprise caching applications.
Strategic Opportunities
- India's electronics manufacturing incentives:PLI scheme subsidies for semiconductor assembly and testing attract module packaging investment outside traditional East Asian hubs.
- Automotive edge storage:ADAS sensor fusion and over-the-air update systems in electric vehicles create demand for industrial-grade NAND with extended temperature tolerances.
- PCIe Gen5 interface adoption:Server motherboard refresh cycles enable premium pricing for NVMe controllers supporting doubled bandwidth over previous generation interfaces.
Industry Challenges
- Atomic-layer deposition technician scarcity:Process engineering talent for high-aspect-ratio channel hole formation commands premium compensation and extends hiring timelines.
- Legacy SATA qualification drag:Enterprise IT procurement cycles maintain dual-interface requirements, forcing parallel controller development and inventory complexity.
- Cross-border technology licensing friction:METI-aligned export controls and Commerce Department foreign direct product rules fragment equipment service access and spare parts logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NAND Flash Market |
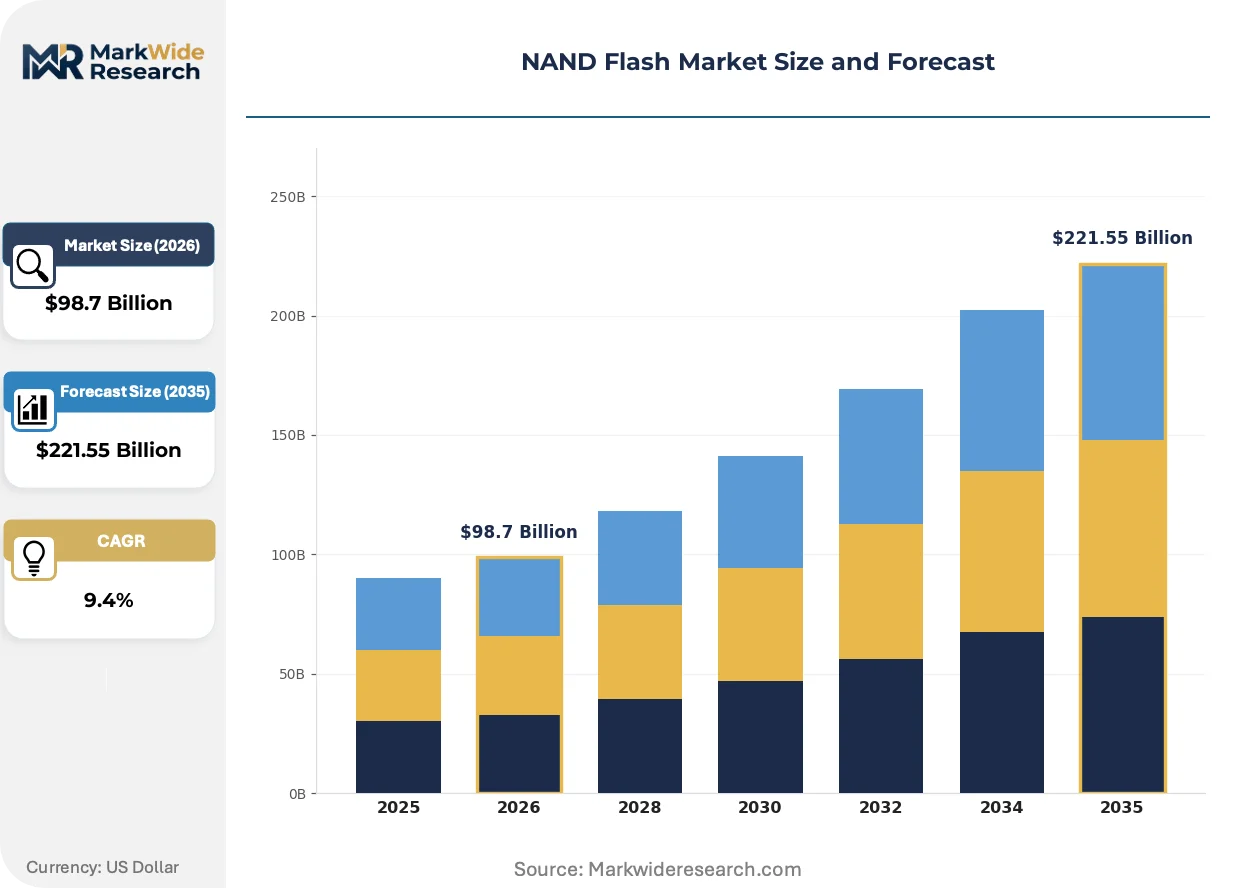
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $221.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D NAND, 2D NAND, SLC, MLC End User: Consumer Electronics, Data Centers, Mobile Devices, Automotive Application: Data Storage, USB Flash Drives, SSDs, Memory Cards Technology: Single-Level Cell, Multi-Level Cell, Triple-Level Cell, Quad-Level Cell |
| Companies Covered | Samsung Electronics, SK hynix, KIOXIA, Micron Technology, Western Digital, YMTC, Intel, Toshiba, SanDisk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NAND Flash Market Evolving Landscape
Layer-count escalation and interface protocol advancement are compressing cost-per-gigabyte trajectories while reconfiguring buyer-supplier contracting structures across enterprise storage procurement.
String stacking with CMOS-under-array architectures is virtualizing the physical constraints of planar scaling by enabling 300+ layer vertical integration without proportional die footprint expansion. Hyperscale operators in the United States and China are qualifying these devices for cold storage tiers where read latency tolerance permits higher-density cell configurations. The technology is virtualizing traditional segmentation between performance and capacity-optimized product lines.
China's GB standards on energy-efficient semiconductor manufacturing are tightening fab power consumption limits and water usage intensity benchmarks. MIIT enforcement of dual carbon goals is accelerating retirement of legacy planar NAND capacity and redirecting investment toward renewable-powered greenfield sites. Domestic Chinese manufacturers face compressed compliance timelines compared to multinational competitors with diversified geographic footprints.
Direct procurement contracts between module suppliers and hyperscale cloud operators are displacing distributor-mediated purchasing for high-volume enterprise SSD programs. Server original equipment manufacturers in Taiwan and the United States are negotiating multi-year bit supply agreements with captive wafer producers. This pattern concentrates most visibly in North American data center clusters where procurement teams maintain dedicated supplier engineering liaison functions.
NAND Flash Market Segmentation
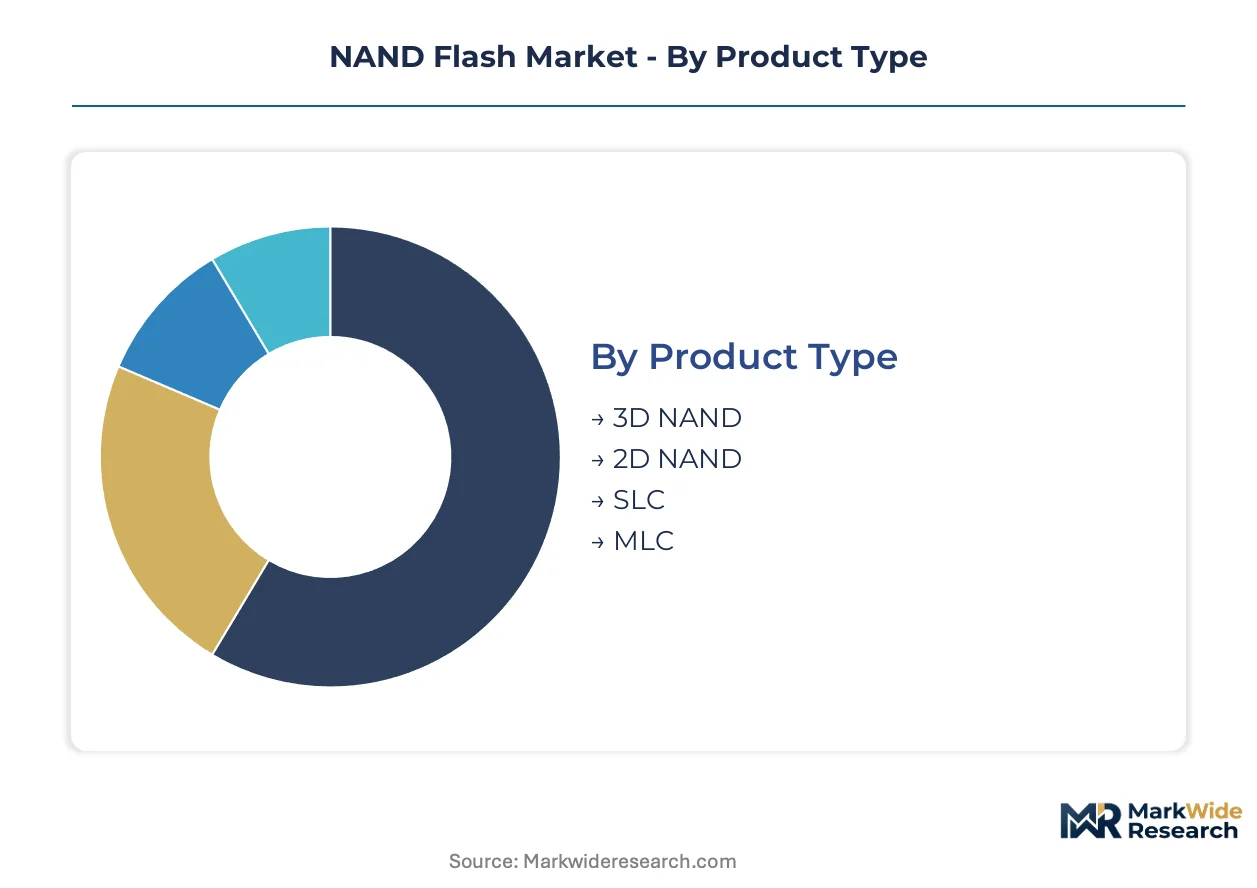
NAND flash segmentation reveals how technical specifications map to divergent margin structures and service requirements. Layer-count roadmaps, cell-level configurations, and interface protocols each impose distinct qualification timelines and procurement patterns on buyers.
Product Type:
After-sales service intensity varies sharply across product architectures, with advanced 3D NAND requiring specialized field engineering support for yield optimization and firmware updates.
- 3D NAND:Vertical stacking architectures now exceed 200 layers, achieving terabit-scale densities through charge-trap transistor designs. Hyperscale data center operators in the United States absorb the highest volumes as HDD replacement accelerates in enterprise storage racks. Samsung Electronics and SK hynix anchor supply through captive wafer capacity in South Korea's Pyeongtaek cluster.
- 2D NAND:Planar architectures persist in legacy industrial applications requiring extended temperature tolerances and proven endurance profiles. China's MIIT dual carbon mandates are accelerating retirement of legacy planar capacity, compressing remaining supply into specialty foundry arrangements.
- SLC:Single-level cell configurations deliver highest endurance for write-intensive workloads in automotive and industrial controllers.
- MLC:Multi-level cell products occupy mid-range enterprise segments balancing cost and performance.
3D NAND holds the largest share; momentum sits with SLC in automotive edge storage applications.
End User:
Customer concentration patterns determine contract structures, with direct procurement displacing distributor channels where volume thresholds justify dedicated supplier engineering liaison functions.
- Data Centers:Hyperscale cloud infrastructure operators in the United States and China qualify high-density SSDs for cold storage tiers where read latency tolerance permits denser cell configurations. PCIe Gen5 interface adoption enables premium pricing as server motherboard refresh cycles accelerate.
- Automotive:Electric vehicle ADAS sensor fusion and over-the-air update systems create demand for industrial-grade NAND with extended temperature tolerances. India's PLI scheme subsidies attract module packaging investment for this segment outside traditional East Asian hubs.
- Consumer Electronics:Notebook and tablet manufacturers drive volume absorption of mainstream TLC configurations.
- Mobile Devices:Smartphone OEMs prioritize low-power architectures with UFS interface compatibility.
Data centers command the highest bit volumes; automotive is climbing the fastest on electrification tailwinds.
Application:
Margin pools concentrate where interface complexity and controller integration create differentiation barriers against commodity competition.
- SSDs:Enterprise and client replacements of hard disk drives capture the largest margin pool, with NVMe controllers supporting doubled bandwidth over previous generation interfaces. Samsung Electronics leverages captive wafer capacity to secure multi-year bit supply agreements with server OEMs in Taiwan and the United States.
- Data Storage:Cold and warm tier architectures in hyperscale facilities absorb QLC configurations where write endurance limitations are acceptable.
- USB Flash Drives:Portable storage remains cost-sensitive, with TLC occupying the volume sweet spot.
- Memory Cards:SD and microSD formats serve camera, drone, and gaming console markets with performance-tiered product lines.
SSDs dominate value capture; USB flash drives face steepest price compression.
Technology:
Cell-level bit density directly trades off against program-erase cycle endurance, constraining addressable market boundaries for each configuration.
- Triple-Level Cell:Three bits per cell delivers optimal cost-per-bit economics for consumer and mainstream enterprise workloads. SK hynix anchors high-bandwidth memory portfolios alongside TLC NAND to deepen data center relationships with integrated supply proposals.
- Single-Level Cell:One bit per cell provides maximum endurance for write-intensive caching layers and industrial controllers. Automotive edge storage qualification timelines favor SLC for safety-critical ADAS data logging.
- Multi-Level Cell:Two-bit configurations persist in legacy enterprise arrays with established qualification baselines.
- Quad-Level Cell:Four-bit density remains unsuitable for write-intensive workloads, capping expansion in enterprise caching despite lowest cost-per-gigabyte.
TLC holds the largest share; QLC is gaining share fastest in cold storage tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Incheon International Airport cargo hub underwrites South Korea's dominance in semiconductor logistics, moving finished NAND dice to assembly sites across Asia. This infrastructure asset connects Pyeongtaek fabrication clusters to global module packaging operations.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center corridors absorb high-density SSD volumes for enterprise HDD replacement cycles. The Commerce Department foreign direct product rules constrain equipment service access for manufacturers with cross-border supply footprints. Boise, Idaho anchors Micron Technology's captive wafer operations serving server OEM procurement teams.
China
Domestic module assembly lines in Suzhou and Shenzhen consume imported wafer dice for enterprise SSD packaging. MIIT dual carbon mandates and GB standards on energy-efficient fabrication accelerate retirement of legacy planar NAND capacity. Yangtze Memory Technologies Corporation operates Wuhan-based facilities subject to SAMR antitrust review timelines.
Japan
KIOXIA maintains Yokkaichi and Kitakami fabrication complexes supplying charge-trap cell architectures for high-layer-count roadmaps. METI-aligned export controls on advanced lithography and etch systems compress capacity expansion timelines for sub-15nm node transitions. Tokyo-based equipment vendors face extended ASML system lead times exceeding eighteen months.
Singapore
Strategic wafer fabrication investments by Micron Technology leverage the city-state's trade infrastructure for geographic diversification against supply concentration risks. The absence of domestic regulatory constraints on equipment licensing attracts greenfield capacity announcements. Tuas industrial zone hosts backend assembly and testing operations serving ASEAN electronics manufacturing networks.
Taiwan
Server original equipment manufacturers in Taipei and Taichung negotiate multi-year bit supply agreements with captive wafer producers for direct procurement channels. The island's foundry ecosystem lacks domestic NAND fabrication, forcing reliance on imported dice from South Korean and Japanese sources. Hsinchu Science Park concentrates controller design houses for NVMe interface development.
NAND Flash Market Competitive Landscape
On the supply side, the industry is consolidated around captive wafer producers with vertically integrated module operations, creating tiered competition between scale-driven memory specialists and diversified semiconductor conglomerates. Three strategic archetypes dominate: Korean chaebol-affiliated producers with captive foundry capacity, American memory specialists competing on geographic diversification, and Chinese state-backed entrants navigating equipment access restrictions. Capacity expansion and direct procurement contract structures represent the dominant competitive moves reshaping buyer-supplier relationships.
Among Korean producers, Samsung Electronics and SK hynix exemplify the chaebol-affiliated archetype with integrated wafer and module operations. Micron Technology occupies a position as the American geographic diversification specialist, operating fabrication facilities across Singapore, Japan, and the United States. KIOXIA represents the Japanese charge-trap technology anchor, while YMTC sits within the Chinese state-backed tier subject to equipment availability constraints.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK hynix |
| KIOXIA |
| Micron Technology |
| Western Digital |
| YMTC |
| Intel |
| Toshiba |
| SanDisk |
| Others |
Value Network & Pricing Analysis
Sub-90% fab utilization at South Korea's Pyeongtaek and Hwaseong clusters is forcing suppliers into aggressive contract negotiations while buyers exploit oversupply windows for multi-year bit supply agreements. This slack capacity environment simultaneously erodes spot-market pricing and accelerates direct procurement channel migration.
Pricing Analysis
Volume-discount tiering separates hyperscale cloud operators securing multi-year offtake agreements from enterprise IT procurement teams facing spot-market volatility. Pricing stratifies across premium PCIe Gen5 NVMe tiers, standard TLC-based enterprise SATA configurations, and economy QLC cold storage modules. Cost compression in the economy tier is intensifying because Chinese module assemblers in Suzhou and Shenzhen are absorbing imported wafer dice at compressed margins. Hyperscale data center operators exhibit lowest price sensitivity due to total-cost-of-ownership framing, while consumer electronics OEMs remain most responsive to per-gigabyte fluctuations.
Supply Chain Analysis
Silicon wafer feedstock draws from Japan's Shin-Etsu and SUMCO operations, with photoresist and specialty gases sourced from Tokyo-based chemical suppliers. Captive wafer production concentrates in South Korea, Japan, and the United States, while module packaging spreads across China, Singapore, and emerging Indian PLI-subsidized facilities. Single-source vulnerability haunts extreme ultraviolet lithography systems where ASML equipment availability constrains layer-count roadmaps. Distribution runs through Incheon International Airport cargo corridors connecting fabrication clusters to ASEAN assembly networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NAND flash market rewards command over atomic-layer deposition talent and charge-trap process engineering—capabilities that remain locked within a handful of fabrication complexes despite surging module assembly investment elsewhere.
For Market Incumbents: Entrench yield optimization leadership by deploying CMOS-under-array architectures ahead of 300-layer roadmaps, while securing captive wafer commitments from server OEMs in Taiwan and the United States before Chinese state-backed entrants qualify alternative sources. Prioritize equipment service access negotiations under METI-aligned export controls and Commerce Department foreign direct product rules. For New Entrants and Emerging Players: Build out automotive edge storage qualification capabilities targeting electric vehicle ADAS sensor fusion applications, where industrial-grade temperature tolerances and extended endurance requirements create defensible positioning against commodity competition. India's PLI scheme subsidies for semiconductor assembly and testing offer the most penetrable geographic entry point for module packaging investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because equipment availability restrictions and cross-border technology licensing friction will strand sub-scale competitors lacking multi-facility geographic diversification. Target controller design specialists with NVMe Gen5 firmware capabilities as acquisition candidates. Monitor ASML system lead time compression as the critical inflection signal for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Layer-Count Roadmap Acceleration | CMOS-under-array architectures enable 300+ layer stacking without die footprint expansion, securing hyperscale qualification timelines. |
| Direct Procurement Channel Development | Bypassing distributor layers captures margin from server OEM procurement teams in Northern Virginia and Oregon data center corridors. |
| Geographic Diversification Investment | Singapore and India facilities reduce seismic and geopolitical exposure concentrated in South Korean Pyeongtaek clusters. |
| Charge-Trap Process Engineering | Transition from floating-gate designs improves vertical scaling economics and yield rates at sub-15nm nodes. |
| Automotive Qualification Pipeline | ADAS sensor fusion and over-the-air update systems in electric vehicles demand industrial-grade NAND with extended temperature tolerances. |
Research Methodology
Desk research of SEC 10-K filings, equipment vendor order backlogs, and MIIT energy-efficiency compliance disclosures preceded structured interviews with NAND flash fabrication engineering directors, hyperscale cloud procurement officers, server OEM supply chain managers, and automotive Tier 1 electronics sourcing leads. Secondary validation drew from customs trade data, ASML quarterly order disclosures, and GB standards documentation on semiconductor manufacturing emissions. Bottom-up bit supply modeling triangulated against top-down data center storage capex projections.
Assumptions held equipment availability restrictions and METI-aligned export controls fixed across the analysis window, while varying hyperscale cloud buildout intensity and electric vehicle penetration scenarios. Segmentation dimensions modeled include product architecture, cell-level configuration, interface protocol, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical bit shipment trajectories and replacement cycle timing for enterprise HDD-to-SSD transitions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by Chinese state-backed entrants or unexpected relaxation of Commerce Department foreign direct product rules would shift outcomes beyond projected ranges. Cross-checking against hyperscaler disclosed storage hardware capex and foundry equipment order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Portable Storage Device Control Software Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Storage and Management Market
Data Storage
Next Generation Data Storage Market
Data Storage
Zoned Flash Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Global Digital Storage Devices Market
Data Storage
North America Next Generation Storage Market
Data Storage
Data Storage Market
Data Storage
NAND Flash Memory Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Storage Area Network Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
USB Key Market