
 Middle East and Africa Lidar Market | 2026-2036
Middle East and Africa Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lidar Market Foresight
Competitive Landscape
A capital-intensity divergence between players is reorganizing competitive tiers across the Middle East and Africa Lidar Market. Innoviz Technologies Ltd leverages its solid-state automotive heritage to navigate emerging mobility applications in Gulf states. RIEGL Laser Measurement Systems anchors its position through deep manufacturing scale in airborne and terrestrial platforms. Trimble Inc. differentiates via integrated GNSS-Lidar workflows that dominate precision agriculture contracts in South Africa.
Technology and Segmentation
Lidar (Light Detection and Ranging) employs pulsed laser beams to generate precise three-dimensional point clouds, with systems typically emitting near-infrared wavelengths at repetition rates exceeding one million pulses per second for topographical and object-detection applications. Airborne Lidar occupies the largest revenue share across Middle Eastern markets due to government-funded national mapping initiatives and coastal zone management priorities. Solid-state technology represents the fastest-expanding category as frequency-modulated continuous wave architectures displace mechanical spinning units in autonomous vehicle trials and smart infrastructure projects.
Regulatory Environment
Saudi Arabia's General Authority for Survey and Geospatial Information and South Africa's Chief Directorate: National Geo-spatial Information enforce data accuracy standards that shape procurement specifications for surveying contractors. The UAE's Telecommunications and Digital Government Regulatory Authority governs spectrum allocation for Lidar sensors operating in unlicensed bands, directly affecting mobile mapping system deployments. Stakeholders must monitor evolving geospatial data sovereignty requirements as Gulf states tighten localization mandates for critical infrastructure surveys.
Market Dynamics
Solid-state frequency-modulated continuous wave architectures are compressing mechanical spinning unit dominance across Middle East and Africa Lidar deployments, forcing incumbent suppliers to reconfigure hardware roadmaps for Gulf autonomous vehicle trials and Saudi national mapping programs.
Growth Catalysts
- Saudi dual carbon goals:The Kingdom's net-zero 2060 target and renewable energy buildout mandate continuous terrain surveying for solar and wind site selection, directly expanding airborne Lidar procurement.
- UAE smart city mandates:Dubai and Abu Dhabi infrastructure codes now require real-time 3D environmental sensing for traffic management and pedestrian safety systems.
- Cadastral modernization:National mapping agencies in Oman, Qatar, and South Africa are replacing legacy photogrammetry with Lidar-derived digital twins for property registration accuracy.
Market Restraints
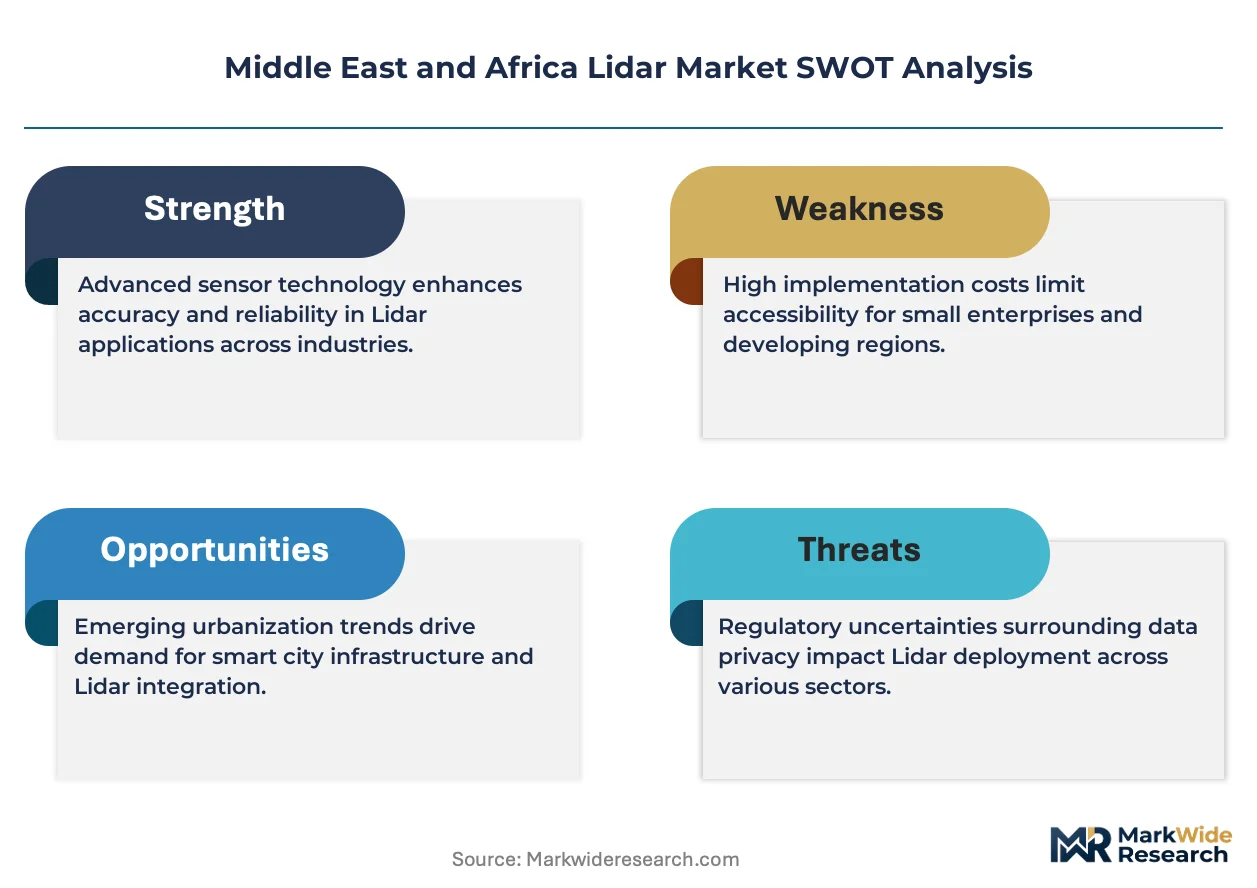
- InP laser diode supply concentration:Indium phosphide semiconductor substrates for 1550nm automotive Lidar originate from a concentrated East Asian supplier base, exposing Gulf integrators to allocation risk.
- SAMR-style geospatial data localization:Emerging data sovereignty frameworks across Gulf Cooperation Council states restrict cross-border point cloud transmission, fragmenting cloud processing architectures.
- Photogrammetry substitution:Satellite-derived digital elevation models from commercial constellations now achieve 30cm vertical accuracy at lower survey cost for low-priority mapping contracts.
Strategic Opportunities
- Kenya and Ethiopia transport corridors:Lamu Port-South Sudan-Ethiopia Transport Corridor and Addis-Djibouti rail extensions lack detailed topographic basemaps, creating first-mover surveying contracts.
- Lidar-GNSS-IMU convergence:Tight integration of inertial measurement units with solid-state sensors enables mobile mapping without ground control points, opening municipal asset inventory applications.
- South African precision agriculture:Viticulture and citrus export operations in Western Cape and Limpopo are adopting tractor-mounted Lidar for canopy volume estimation and yield forecasting.
Industry Challenges
- Geodetic surveyor scarcity:Gulf states lack sufficient licensed professionals capable of processing classified point clouds to national accuracy standards enforced by Saudi General Authority for Survey and Geospatial Information.
- Multi-sensor calibration complexity:Integrating Lidar with hyperspectral or thermal payloads for environmental monitoring contracts demands specialized boresight alignment expertise rarely available in regional system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lidar Market |
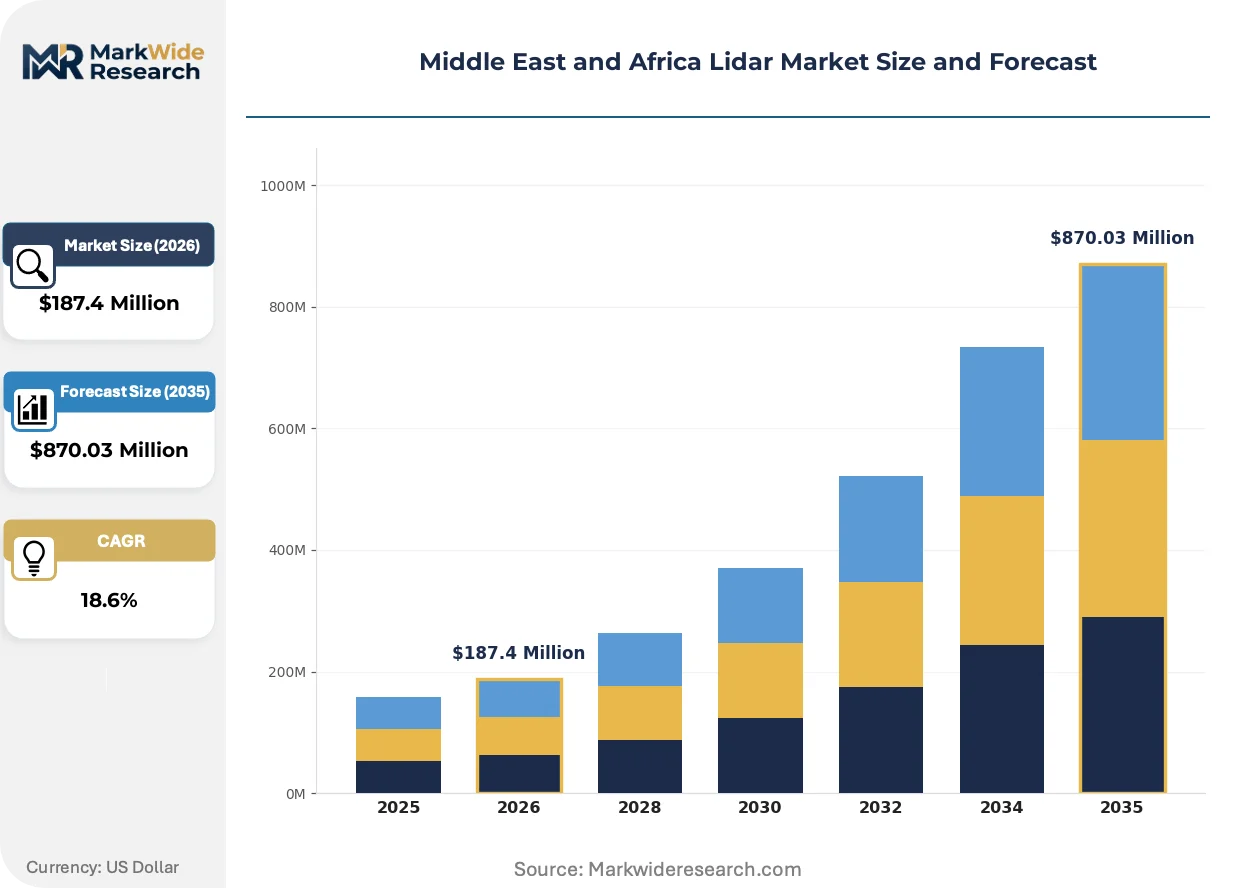
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne Lidar, Terrestrial Lidar, Mobile Lidar, Bathymetric Lidar End User: Aerospace, Agriculture, Forestry, Transportation Technology: Time of Flight, Frequency Modulated Continuous Wave, Solid-State, Multispectral Application: Topographical Mapping, Coastal Management, Environmental Monitoring, Urban Planning |
| Companies Covered | Innoviz Technologies Ltd, Leica Geosystems AG, Trimble Inc., SICK AG, FARO Technologies Inc., Velodyne Lidar Inc., Teledyne Optech, RIEGL Laser Measurement Systems, Ouster Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lidar Market Shifts & Advancements
Frequency-modulated continuous wave solid-state architectures are compressing the mechanical scanner installed base across Middle East and Africa Lidar deployments. Three interconnected developments are restructuring competitive positioning and procurement specifications.
Flash Lidar with single-pulse scene illumination is supplanting scanning architectures in low-speed autonomous shuttle trials at Dubai Expo City and NEOM. Municipal transport authorities specify solid-state reliability for 24/7 operations in desert thermal cycling conditions. This transition is compressing maintenance contract margins previously captured by mechanical scanner refurbishment providers.
Saudi General Authority for Survey and Geospatial Information enacted sub-10cm vertical accuracy mandates for all cadastral boundary surveys, invalidating photogrammetry-derived products for property registration. Engineering consultancies now embed Lidar acquisition clauses in every geomatics tender. South African Chief Directorate: National Geo-spatial Information is harmonizing specifications to enable cross-border project continuity.
Survey contractors now unbundle data acquisition from processing analytics, selling raw point clouds to multiple downstream verticals. Mining operators in Botswana and Ghana purchase identical terrain datasets originally commissioned for transport infrastructure planning. This disintermediation of value-added processing is visible most acutely in South African platinum belt operations where drill-and-blast optimization firms now source directly from aerial surveyors.
Middle East and Africa Lidar Market Segmentation
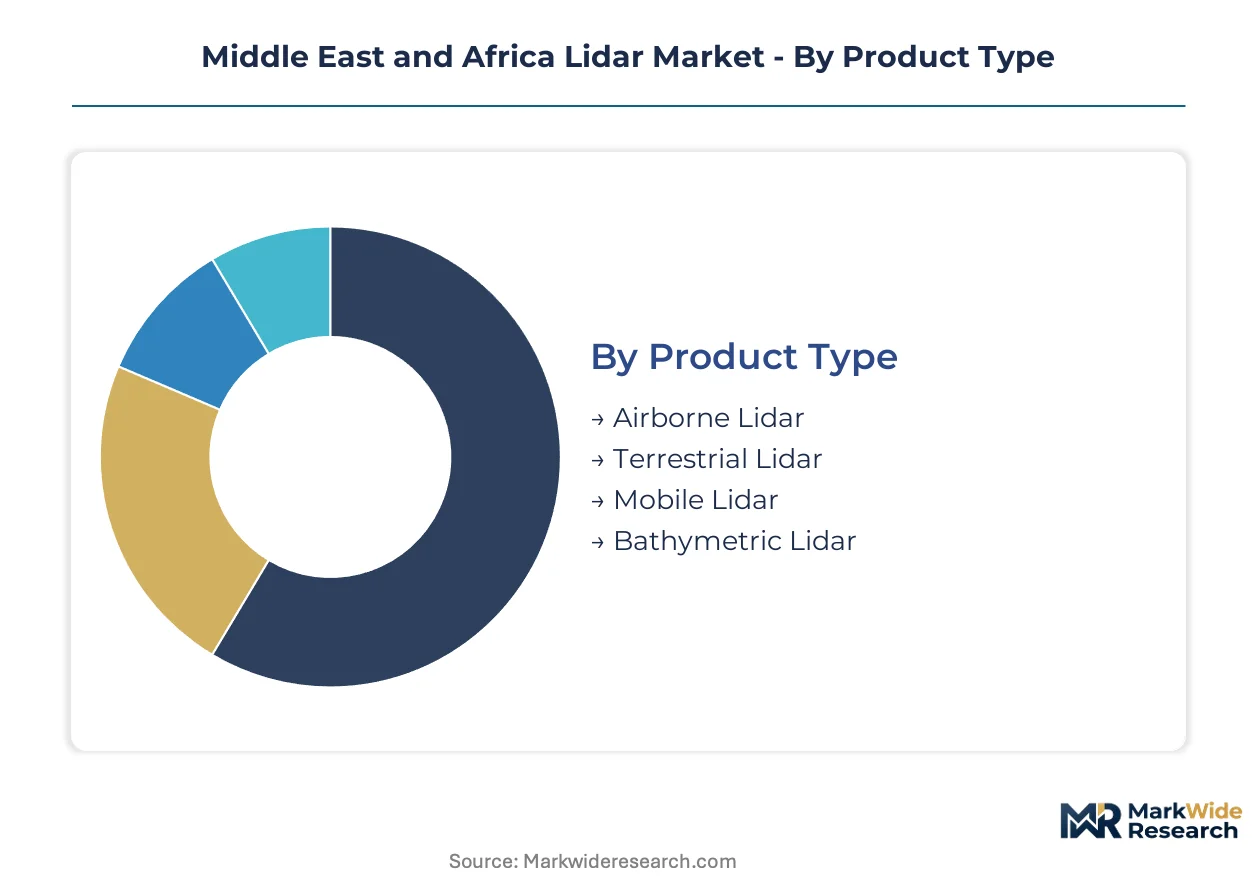
Segmentation in the Middle East and Africa Lidar Market reveals distinct margin architectures across hardware platforms, technology generations, and application verticals. Procurement patterns diverge sharply between government-funded national mapping programs and private infrastructure developments, with each segment demanding calibrated sensor specifications and data processing workflows.
Product Type:
Margin pools concentrate in airborne platforms where government procurement cycles and coastal zone mandates sustain premium pricing, while terrestrial systems compete on surveyor productivity metrics.
- Airborne Lidar:Long-range laser scanners mounted on fixed-wing aircraft and helicopters emit near-infrared pulses at aircraft altitude, generating sub-decimeter vertical accuracy for national mapping initiatives. Saudi Arabia's General Authority for Survey and Geospatial Information mandates airborne acquisition for all cadastral boundary surveys exceeding 500 hectares, locking in sustained procurement volumes through national mapping program renewals.
- Terrestrial Lidar:Tripod-mounted or vehicle-stationary systems capture high-density point clouds at ranges up to 2 kilometers for engineering-grade precision. UAE smart city infrastructure codes in Dubai and Abu Dhabi require terrestrial scanning for as-built documentation of high-rise developments, creating recurring demand from engineering consultancies.
- Mobile Lidar:Vehicle-mounted sensors with integrated GNSS-IMU enable kinematic surveying without ground control points.
- Bathymetric Lidar:Dual-wavelength systems penetrate water columns for coastal zone management.
Airborne Lidar holds installed capacity. Mobile Lidar is rotating up the share rankings.
End User:
Application intensity varies by sector, with transportation corridors and precision agriculture commanding distinct sensor configurations and data delivery timelines.
- Transportation:Road and rail authorities deploy Lidar for corridor planning, tunnel clearance verification, and autonomous vehicle infrastructure readiness. The Lamu Port-South Sudan-Ethiopia Transport Corridor and Addis-Djibouti rail extensions lack detailed topographic basemaps, generating first-mover surveying contracts for integrated mobile mapping systems.
- Agriculture:Viticulture and citrus export operations in South Africa's Western Cape and Limpopo provinces adopt tractor-mounted Lidar for canopy volume estimation and yield forecasting. Trimble's integrated GNSS-Lidar workflows dominate precision agriculture contracts, with canopy analysis driving variable-rate irrigation decisions.
- Aerospace:Airport authorities utilize Lidar for obstacle limitation surface surveys.
- Forestry:Plantation managers apply Lidar-derived biomass estimates for carbon credit verification.
Transportation commands project scale. Agriculture is climbing the fastest as mechanization spreads.
Technology:
Technology selection determines reliability profiles in desert thermal cycling conditions, with solid-state architectures displacing mechanical scanners in 24/7 operational specifications.
- Solid-State:Frequency-modulated continuous wave and flash architectures eliminate moving parts, enabling automotive-grade reliability for autonomous vehicle trials and smart infrastructure. Dubai Expo City and NEOM specify solid-state sensors for low-speed autonomous shuttle operations, invalidating mechanical scanner proposals in municipal tenders.
- Frequency Modulated Continuous Wave:Coherent detection enables direct velocity measurement alongside range, critical for moving platform applications. FMCW architectures are compressing mechanical spinning unit dominance across Gulf autonomous vehicle trials and Saudi national mapping programs requiring Doppler-capable sensors.
- Time of Flight:Pulsed laser architectures dominate installed base.
- Multispectral:Combined laser and spectral imaging supports environmental monitoring.
Time of Flight holds installed base. Solid-State is gaining share fastest through reliability mandates.
Application:
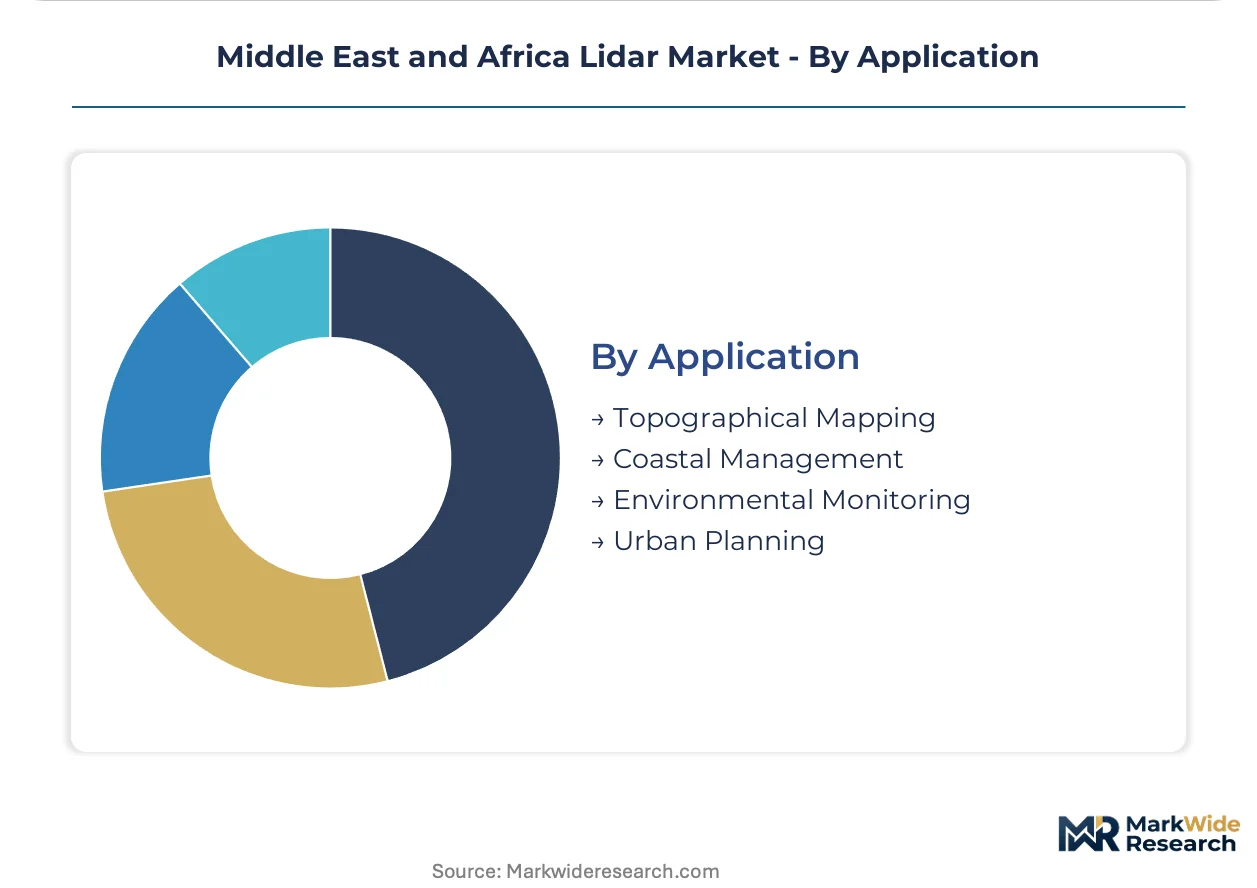
Application prioritization reflects government funding cycles, with topographical mapping and coastal management anchored in national budget allocations.
- Topographical Mapping:National mapping agencies across Oman, Qatar, and South Africa replace legacy photogrammetry with Lidar-derived digital twins for property registration accuracy. Saudi Arabia's sub-10cm vertical accuracy mandate for cadastral boundary surveys invalidates photogrammetry-derived products, embedding Lidar acquisition clauses in every geomatics tender.
- Coastal Management:Bathymetric Lidar penetration of water columns supports port development and erosion monitoring. Red Sea Project developments require continuous terrain surveying for coastal zone management, integrating airborne topographic and bathymetric sensors.
- Environmental Monitoring:Multi-sensor integration with hyperspectral payloads tracks ecosystem change.
- Urban Planning:Municipal authorities deploy Lidar for 3D city modeling and infrastructure asset inventory.
Topographical Mapping holds installed base. Coastal Management is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa Lidar Market exhibits pronounced import dependency for sensor hardware, with regional system integrators sourcing solid-state units and InP laser diodes from East Asian and European suppliers while local value creation concentrates in data processing and survey services.
Saudi Arabia
NEOM and Red Sea Project developments drive continuous airborne Lidar procurement for terrain surveying and coastal zone management. The General Authority for Survey and Geospatial Information enforces sub-10cm vertical accuracy mandates for cadastral boundary surveys, invalidating photogrammetry-derived products. Riyadh-based engineering consultancies now embed Lidar acquisition clauses in every geomatics tender.
United Arab Emirates
Dubai and Abu Dhabi smart city infrastructure codes mandate real-time 3D environmental sensing for traffic management and pedestrian safety systems. The Telecommunications and Digital Government Regulatory Authority governs spectrum allocation for sensors operating in unlicensed bands, directly affecting mobile mapping deployments. Dubai Expo City specifies solid-state sensors for low-speed autonomous shuttle trials.
South Africa
Precision agriculture operations in Western Cape viticulture and Limpopo citrus exports adopt tractor-mounted Lidar for canopy volume estimation and yield forecasting. The Chief Directorate: National Geo-spatial Information harmonizes accuracy specifications with Saudi standards to enable cross-border project continuity. Platinum belt mining operators now source terrain datasets directly from aerial surveyors for drill-and-blast optimization.
Oman
National mapping agency modernization programs replace legacy photogrammetry with Lidar-derived digital twins for property registration accuracy. Coastal management priorities around Duqm Port and Salalah generate bathymetric Lidar demand for port development and erosion monitoring. Engineering consultancies in Muscat report sustained procurement volumes through government-funded surveying contracts.
Ethiopia
Addis-Djibouti rail extensions and transport corridor development lack detailed topographic basemaps, creating first-mover surveying contracts for integrated mobile mapping systems. The Lamu Port-South Sudan-Ethiopia Transport Corridor requires continuous terrain surveying for infrastructure planning. Survey contractors in Addis Ababa unbundle data acquisition from processing analytics to serve multiple downstream mining and agricultural clients.
Middle East and Africa Lidar Market Competitive Landscape
Concentration sits with diversified measurement technology conglomerates and solid-state automotive specialists. The vendor base organizes around three strategic archetypes: precision agriculture integrators with GNSS-Lidar workflows, airborne mapping equipment manufacturers with deep manufacturing scale, and automotive heritage players pivoting to mobility applications. Dominant competitive moves include strategic partnerships between Gulf system integrators and solid-state sensor suppliers, plus portfolio diversification into data analytics services.
Within the automotive-heritage tier, Innoviz Technologies Ltd exemplifies solid-state sensor deployment for Gulf autonomous vehicle trials. RIEGL Laser Measurement Systems anchors the airborne and terrestrial platform segment through Austrian manufacturing scale. Trimble Inc. occupies a position in precision agriculture workflows, with integrated GNSS-Lidar systems dominating South African viticulture and citrus operations.
| Leading Market Players |
|---|
| Innoviz Technologies Ltd |
| Leica Geosystems AG |
| Trimble Inc. |
| SICK AG |
| FARO Technologies Inc. |
| Velodyne Lidar Inc. |
| Teledyne Optech |
| RIEGL Laser Measurement Systems |
| Ouster Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for InP laser diode substrates from East Asian suppliers compress pricing power for Gulf system integrators, while Saudi airborne Lidar procurement cycles lock in configured-to-order premiums for Austrian and German hardware manufacturers serving national mapping mandates.
Pricing Analysis
The customization-premium spread between standard terrestrial units and airborne systems configured to Saudi General Authority for Survey and Geospatial Information accuracy mandates reaches substantial multiples. Project-based pricing dominates government procurement, with after-sales service bundling and calibration certification driving differentiation. Pricing pressure stems from photogrammetry substitution in low-accuracy mapping contracts, eroding margins at the economy tier. National mapping agencies exhibit lowest price sensitivity due to regulatory compliance requirements, while South African precision agriculture operators negotiate aggressively on tractor-mounted unit costs.
Supply Chain Analysis
Inventory buffers for solid-state sensor components rarely exceed sixty days given concentrated East Asian sourcing of InP substrates and VCSEL arrays. Hardware manufacturing anchors in Austria, Germany, and the United States, while semiconductor feedstocks draw from Taiwan, Japan, and South Korea. Single-source vulnerability concentrates in 1550nm automotive-grade laser diodes. Distribution runs through Dubai-based system integrators serving Gulf states and Johannesburg-based survey equipment distributors covering Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market fragments across application verticals as solid-state reliability mandates in UAE smart city codes and Saudi cadastral accuracy standards create distinct procurement specifications that favor specialized over generalist suppliers.
For Market Incumbents: Consolidate around data analytics service layers as raw point cloud commoditization intensifies. Acquire mobile mapping specialists with proven GNSS-IMU integration to defend against unbundling trends in South African mining and Ethiopian transport corridors. Secure backward integration into solid-state sensor calibration to offset mechanical scanner margin compression. For New Entrants and Emerging Players: Anchor in Kenya and Ethiopia transport corridor surveying where topographic basemap gaps persist and first-mover contracts remain unclaimed. Target bathymetric Lidar for Red Sea Project coastal zone management with bundled processing analytics. Lead with Lidar-GNSS-IMU convergence capabilities that eliminate ground control point requirements. For Investors and Strategic Acquirers: Long-term, this sits as a data-services play because unbundling of acquisition from analytics shifts value capture downstream. Target survey contractors with established Saudi GASGI certification relationships and proprietary digital twin pipelines. Watch for inflection when Gulf geospatial data localization mandates force cloud processing architecture restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Sensor Partnership | Secures automotive-grade reliability credentials for Dubai and NEOM autonomous shuttle specifications. |
| Data Analytics Service Launch | Captures value from unbundled point cloud sales to multiple downstream mining and agriculture clients. |
| GNSS-IMU Integration Investment | Enables kinematic surveying without ground control points for Ethiopian transport corridor contracts. |
| Saudi Certification Pathway | Unlocks GASGI-mandated airborne procurement volumes through sub-10cm accuracy compliance. |
| Regional Processing Center | Addresses emerging GCC data sovereignty requirements restricting cross-border point cloud transmission. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating geomatics engineering directors at Saudi and UAE consultancies, procurement leads at national mapping agencies, and technical specialists at solid-state sensor manufacturers. Secondary validation drew from GASGI accuracy mandate documentation, UAE Telecommunications and Digital Government Regulatory Authority spectrum allocation rulings, and South African Chief Directorate: National Geo-spatial Information specification harmonization notices. Bottom-up equipment shipment tracking and top-down national budget allocation analysis were triangulated to anchor volume estimates.
Across the analysis window, forecasts model product type segmentation across airborne, terrestrial, mobile, and bathymetric platforms; technology generation shifts from mechanical to solid-state architectures; and application intensity across topographical mapping, coastal management, and precision agriculture verticals. CAGRs derive from equipment replacement cycle analysis and procurement pipeline visibility. Industry-specific inputs include Saudi renewable energy site survey intensity and UAE smart city sensor density mandates.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf infrastructure investment and stable East Asian semiconductor supply; material deviation would warrant model refresh. Specific risks include accelerated photogrammetry substitution in low-priority contracts and geodetic surveyor scarcity constraining project execution. Revision becomes warranted when InP laser diode allocation disruptions or GCC data localization enforcement thresholds cross critical levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
2D Gesture Recognition Market