
 Level Transmitter Market | 2026-2036
Level Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Level Transmitter Market Intelligence
Aftermarket service revenue is narrowing the gap with original equipment margins as lifecycle contracts replace transactional hardware sales. Emerson Electric leverages its Plantweb digital ecosystem to lock in recurring calibration and diagnostics income. Endress+Hauser sustains its European installed base through factory-authorized service hubs in Basel and Maulburg. VEGA competes aggressively on retrofit compatibility, offering adapter kits that reduce vessel downtime during technology swaps.
A level transmitter measures the height of liquid, solid, or slurry materials within a containment vessel, typically employing radar pulses, ultrasonic waves, or hydrostatic pressure with accuracy ratings reaching ±1 millimeter in critical applications. The device serves primarily to prevent overflow events, optimize inventory turnover, and enable automated batch control in continuous process industries. Radar level transmitters now dominate the product type landscape due to their immunity to vapor, foam, and dust interference that cripple ultrasonic alternatives in chemical processing and oil & gas extraction. Digital signal processing technology anchors the fastest-growing technology segment, as adaptive algorithms filter false echoes in agitated tanks and crystallizing media. Electromechanical float systems retain share in water & wastewater management where simplicity and submerged durability outweigh precision requirements.
The EPA enforces continuous emissions monitoring standards that mandate sealed level measurement on volatile organic compound storage tanks, effectively banning open gauging practices. IEC 61508 functional safety certifications shape procurement criteria in European energy generation and maritime sectors, where SIL-rated transmitters reduce insurance premiums and operational risk. IEEE 802.11 wireless extensions are gaining traction for tank farm retrofit projects where conduit installation proves cost-prohibitive. Stakeholders must weigh the capital expense of radar upgrades against the operational risk of legacy electromechanical failures in corrosive or high-temperature media.
Market Dynamics
Radar level transmitters are displacing ultrasonic and electromechanical alternatives across chemical processing and oil & gas applications, driven by their immunity to vapor, foam, and dust interference that degrades measurement reliability in harsh environments.
Growth Catalysts
- EPA emissions mandates:Continuous emissions monitoring standards in the United States now require sealed level measurement on volatile organic compound storage tanks, eliminating open gauging practices and forcing hardware upgrades.
- Process automation at German chemical clusters:Modernization programs at industrial sites along the Rhine corridor sustain procurement cycles for non-contact radar and guided wave radar devices.
- Digital signal processing advances:Adaptive algorithms filter false echoes in agitated tanks and crystallizing media, expanding addressable applications into previously difficult measurement environments.
Market Restraints
- Stainless steel and exotic alloy costs:Corrosion-resistant housings and process-wetted components face raw material price volatility that compresses hardware margins.
- Specialized calibration labor scarcity:Factory-authorized service capacity concentrates in Basel, Maulburg, and select North American hubs, creating geographic access gaps.
- IEC 61508 certification timelines:SIL-rated functional safety approvals stretch 12-18 months, delaying product launches in European energy and maritime sectors.
Strategic Opportunities
- IEEE 802.11 wireless retrofit channel:Tank farm modernization projects bypass conduit installation costs through wireless extensions, opening brownfield sites previously uneconomical for cable-based upgrades.
- Lifecycle service contracts:Recurring calibration and diagnostics revenue streams displace transactional hardware sales, locking in customer relationships through multi-year agreements.
- Water & wastewater float system replacement:Aging electromechanical installations in municipal treatment facilities present upgrade paths for radar devices with minimal process disruption.
Industry Challenges
- Fieldbus protocol fragmentation:Integration complexity rises as HART, Foundation Fieldbus, and Profinet installations require manufacturer-specific configuration tools.
- False echo suppression tuning:Application engineering bandwidth constrains deployment velocity in crystallizing and agitated media where adaptive algorithms demand site-specific optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Level Transmitter Market |
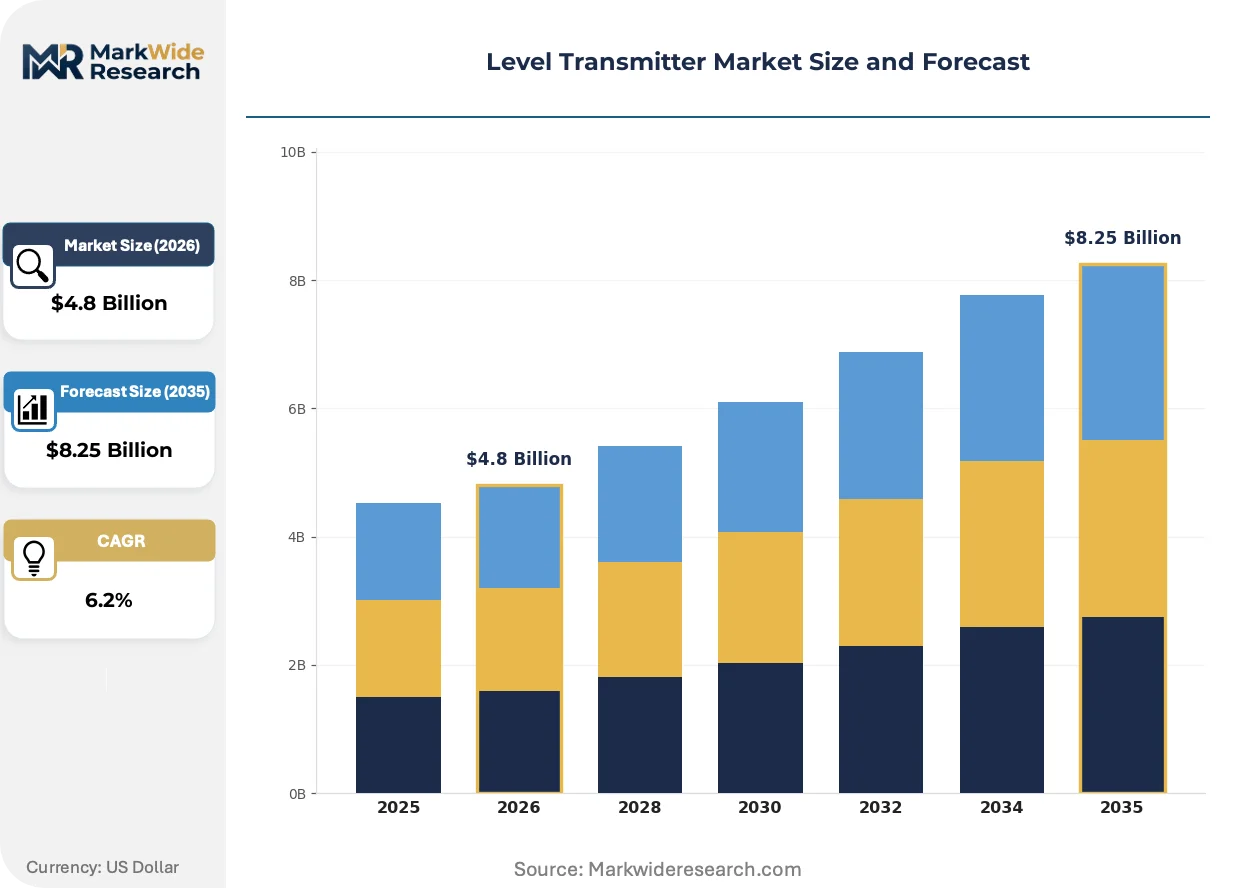
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Ultrasonic, Radar, Magnetostrictive, Laser Technology: Electromechanical, Digital Signal Processing, Microwave, Hydrostatic, Optical Application: Chemical Processing, Water & Wastewater Management, Food & Beverage, Oil & Gas Extraction, Mining End User Industry: Process Control, Energy Generation, Maritime, Pharmaceuticals, Pulp & Paper |
| Companies Covered | Emerson Electric, Endress+Hauser, VEGA, Siemens, KROHNE, ABB, Honeywell, Yokogawa, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Level Transmitter Market Strategic Shifts & Innovations
Measurement hardware is converging with edge computing and predictive diagnostics, transforming level transmitters from passive sensors into active process intelligence nodes that feed digital twin and asset performance management platforms.
80 GHz FMCW radar is hybridizing with cloud-connected analytics architectures to deliver sub-millimeter accuracy in foam-covered and vapor-laden tanks. Chemical processors in the US Gulf Coast and Rotterdam-Antwerp corridor deploy these systems to automate batch control and inventory reconciliation. The technology is compressing total cost of ownership calculations by eliminating manual tank gauging labor and reducing emergency shutdown incidents.
REACH substance restrictions and RoHS hazardous material limits are tightening component sourcing requirements for European market access. Manufacturers reformulate potting compounds and gasket materials to eliminate restricted phthalates and heavy metals. The maritime and offshore energy segment faces the steepest compliance burden, as dual-certification to IEC 61508 and marine classification society rules extends development cycles.
Buyer organizations are consolidating vendor relationships around integrated automation platforms rather than standalone instrument procurement. End-users in the German chemical corridor now specify level transmitters as part of broader digital ecosystem contracts, bundling hardware with calibration services and predictive maintenance software. This behavior compresses the addressable market for point-product specialists while rewarding full-line automation suppliers with multi-year framework agreements.
Level Transmitter Market Segmentation
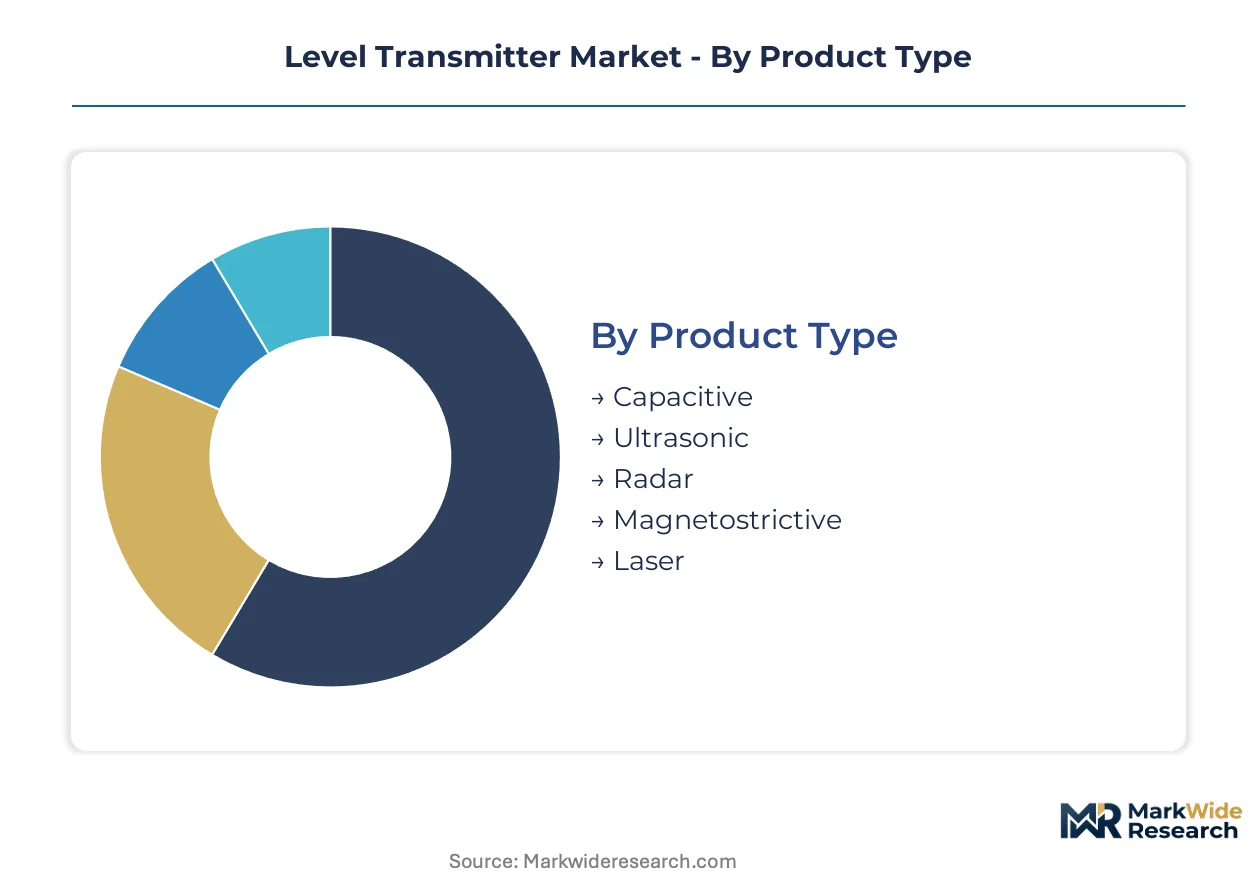
Level transmitter procurement patterns diverge sharply across product architectures and signal processing methodologies. Service attach rates and lifecycle contract penetration vary by segment, reshaping vendor profitability and customer switching costs.
Product Type:
After-sales-service intensity escalates with measurement complexity and electronics density. Radar and laser devices generate recurring calibration revenue streams that capacitive and ultrasonic alternatives rarely capture.
- Radar:Frequency-modulated continuous wave (FMCW) and pulse radar systems dominate chemical processing tank farms. BASF and Bayer procurement cycles along Germany's Rhine corridor sustain demand for 80 GHz devices with adaptive false-echo suppression algorithms.
- Ultrasonic:Piezoelectric transducers measure time-of-flight in non-contact applications. Water & wastewater utilities in the United States specify these for open-channel flow monitoring where vapor interference remains minimal and capital budgets constrain radar adoption.
- Capacitive:Dielectric measurement probes suit small tank installations with conductive media.
- Magnetostrictive:Float-guided magnetostrictive strips deliver high-resolution continuous output in custody transfer applications.
- Laser:Time-of-flight laser sensors address solids level measurement in mining silos where dust clouds obstruct radar propagation.
Radar holds the largest share; momentum sits with laser devices expanding into bulk solids applications.
Technology:
Cost tier stratification separates electromechanical simplicity from digital sophistication. Premium pricing concentrates in signal processing architectures that embed predictive diagnostics.
- Digital Signal Processing:Adaptive algorithms filter vessel obstructions and crystallizing media in agitated tanks. The EPA's emissions monitoring mandates on volatile organic compound storage vessels accelerate displacement of analog gauges.
- Microwave:Guided wave radar transmits electromagnetic pulses along rigid probes or flexible cables. Oil & gas extraction operators in the US Gulf Coast deploy these for interface detection in separator vessels where foam layers complicate non-contact measurement.
- Electromechanical:Float and displacer mechanisms persist in municipal water towers where submerged durability outweighs precision requirements.
- Hydrostatic:Differential pressure transmitters calculate level from liquid head in vented atmospheric tanks.
- Optical:Infrared and laser triangulation systems serve specialized food & beverage applications with hygienic clamp connections.
Digital Signal Processing commands the highest margins; Hydrostatic maintains volume leadership in developing infrastructure markets.
Application:
Customer type fragmentation shapes specification authority and purchasing cadence. Engineering contractors specify for greenfield projects while plant maintenance organizations drive retrofit demand.
- Chemical Processing:Corrosive media and crystallizing products demand exotic alloy wetted parts and heated connections. Rotterdam-Antwerp corridor refineries specify SIL-rated devices per IEC 61508 functional safety standards.
- Oil & Gas Extraction:Separator level control and tank farm inventory management dominate capital allocation. Wireless IEEE 802.11 extensions gain traction in brownfield sites where conduit installation proves cost-prohibitive.
- Water & Wastewater Management:Submersible pressure transmitters and ultrasonic open-channel flow meters constitute the bulk of municipal procurement.
- Food & Beverage:Hygienic 3-A sanitary standards and CIP/SIP compatibility constrain approved device lists.
- Mining:Heavy-duty mechanical switches supplement radar in ore slurry sumps with extreme abrasion.
Chemical Processing generates the highest service contract attachment rates; Oil & Gas Extraction shows the steepest expansion trajectory for wireless retrofit deployments.
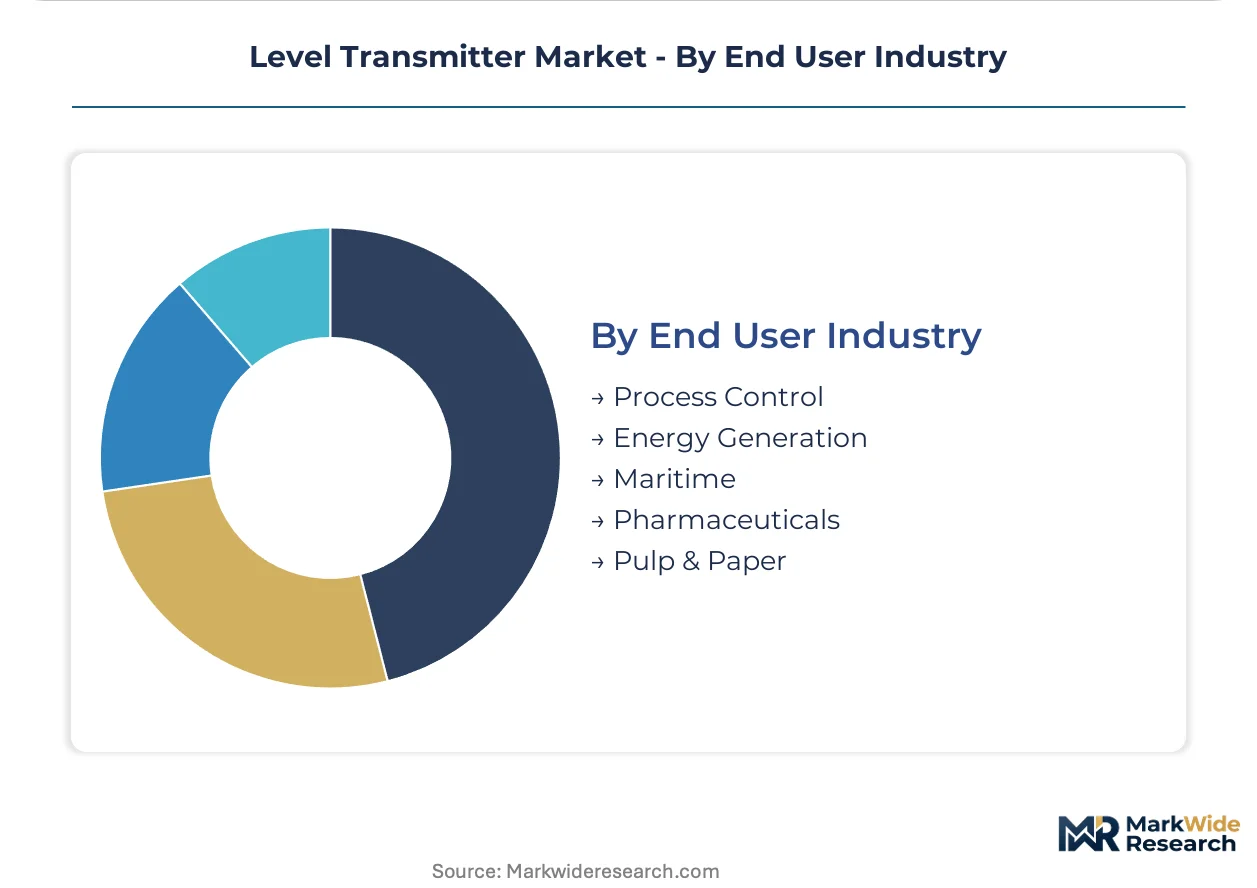
End User Industry:
Supply concentration among automation platform vendors compresses standalone instrument margins. Full-line suppliers bundle level transmitters within digital ecosystem contracts that lock out point-product specialists.
- Process Control:Distributed control system integration and fieldbus protocol compatibility determine procurement decisions. Foundation Fieldbus and Profinet installations require manufacturer-specific configuration tools that raise switching costs.
- Energy Generation:Coal, gas, and nuclear facilities specify redundant level measurement for boiler drum and feedwater tanks. IEC 61508 SIL certifications reduce insurance premiums and operational risk in European utilities.
- Maritime:Classification society rules from Lloyd's Register and DNV extend development cycles with dual-certification requirements.
- Pharmaceuticals:FDA process validation and 21 CFR Part 11 electronic records drive documentation intensity.
- Pulp & Paper:Black liquor recovery boilers and digester level control demand high-temperature ceramic seal designs.
Process Control absorbs the greatest hardware volume; Energy Generation exhibits the most pronounced specification premium for functional safety ratings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's chemical corridor demonstrate the lowest price elasticity, accepting premium instrumentation for functional safety compliance, while municipal water utilities in the United States and India prioritize capital efficiency over precision specifications.
United States
EPA emissions monitoring mandates on volatile organic compound storage tanks eliminate open gauging practices and force hardware upgrades across petrochemical facilities. The agency's continuous emissions standards tighten compliance windows annually. Gulf Coast refineries in Texas and Louisiana deploy 80 GHz radar systems for separator level control and tank farm automation.
Germany
BASF and Bayer modernization programs along the Rhine corridor sustain procurement cycles for SIL-rated non-contact radar devices. IEC 61508 functional safety certifications shape procurement criteria in energy generation and maritime applications. Industrial clusters in Ludwigshafen and Leverkusen specify heated connections and exotic alloy wetted parts for corrosive media handling.
China
Process automation upgrades at state-owned chemical enterprises drive demand for guided wave radar in separator vessels. The Ministry of Ecology and Environment encloses emissions standards that parallel EPA methodologies for storage tank monitoring. Yangtze River Delta petrochemical complexes in Shanghai and Ningbo prioritize wireless retrofit deployments to bypass conduit installation costs.
India
Municipal water utilities specify submersible pressure transmitters and ultrasonic open-channel flow meters where capital budgets constrain radar adoption. The Central Pollution Control Board mandates sealed level measurement on hazardous chemical storage under consolidated environmental norms. Industrial corridors in Gujarat and Maharashtra see gradual displacement of electromechanical floats by radar devices in bulk liquid terminals.
Netherlands
Rotterdam-Antwerp corridor refineries specify IEC 61508 SIL-rated devices for inventory reconciliation and batch control automation. REACH substance restrictions tighten component sourcing requirements for potting compounds and gasket materials. Port terminal operators deploy cloud-connected analytics architectures to compress total cost of ownership through reduced manual gauging labor.
Level Transmitter Market Key Industry Players
Full-line automation platforms and point-product specialists split the market along integration depth versus application focus. Consolidation pressure intensifies as end-users bundle instrumentation within digital ecosystem contracts rather than standalone procurement. Three archetypes dominate: diversified industrial conglomerates with embedded instrument divisions, pure-play measurement specialists with factory-authorized service networks, and regional fabricators competing on retrofit compatibility. Competitive moves concentrate on lifecycle service contract penetration and wireless retrofit channel development.
Within the diversified conglomerate tier, Emerson Electric and Siemens occupy positions anchoring integrated automation platforms that bundle hardware with predictive maintenance software. Endress+Hauser exemplifies the measurement specialist archetype through its European service hub concentration. VEGA represents the retrofit-focused vector with adapter kit strategies that reduce vessel downtime during technology swaps. These three companies illustrate how geographic origin and organizational structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Emerson Electric |
| Endress+Hauser |
| VEGA |
| Siemens |
| KROHNE |
| ABB |
| Honeywell |
| Yokogawa |
| AMETEK |
| Others |
Cost & Logistics Intelligence
Overcapacity in Asian electronics manufacturing hubs compresses component pricing while concentrating bargaining power among tier-one automation suppliers. This utilization dynamic forces mid-tier level transmitter vendors toward lifecycle service bundling to escape commoditization traps.
Pricing Analysis
After-sales calibration and diagnostics contracts now generate the majority of lifetime value across radar and laser device portfolios. Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified functional safety devices from general-purpose instrumentation and basic electromechanical alternatives. Pricing pressure stems from stainless steel and exotic alloy cost volatility that squeezes hardware margins at all tiers. Municipal water utilities exhibit the highest price sensitivity, while German chemical processors accept substantial premiums for IEC 61508 compliance and heated connection specifications.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese, German, and Indian metallurgical suppliers with divergent emissions and labor standards. Critical inputs include 316L stainless steel housings, sapphire ceramic seals for high-temperature applications, and gallium arsenide components for 80 GHz radar modules. Single-source vulnerability concentrates in specialty alloy foundries serving corrosive media specifications. Distribution runs through factory-authorized service hubs in Basel, Maulburg, and Houston that control calibration labor capacity and spare parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Level transmitter procurement is shifting toward integrated automation platform contracts that bundle hardware, software, and predictive maintenance, creating winner-take-most dynamics around digital ecosystem interoperability.
For Market Incumbents: Entrench customer relationships through captive calibration networks and multi-year lifecycle agreements that raise switching costs. Backward integration into specialty alloy machining reduces exposure to raw material price volatility. Prioritize IEEE 802.11 wireless certification investments to capture brownfield retrofit demand where conduit installation economics previously blocked radar adoption.
For New Entrants and Emerging Players: Pursue water and wastewater float replacement opportunities in Indian and US municipal utilities where capital constraints delay radar adoption. Target wireless retrofit channels for tank farm modernization projects requiring minimal vessel downtime. Compete through adapter kit compatibility with legacy electromechanical installations rather than greenfield specification battles against entrenched platform vendors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among measurement specialists with factory-authorized service hub density and SIL-rated certification portfolios. Long-term viability favors vendors capturing digital ecosystem integration contracts rather than point-product transaction share. Monitor EPA enforcement intensity on volatile organic compound storage tanks as the signal indicating hardware replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contract Expansion | Emerson Electric and Endress+Hauser lock in recurring calibration revenue that displaces transactional hardware margins. |
| Wireless Retrofit Channel Development | IEEE 802.11 extensions bypass conduit costs in Yangtze River Delta and US Gulf Coast tank farm projects. |
| Functional Safety Certification Investment | IEC 61508 SIL ratings reduce insurance premiums for Rotterdam-Antwerp corridor refineries and European utilities. |
| Specialty Alloy Backward Integration | In-house 316L and Hastelloy machining insulates margins from nickel price volatility in corrosive media applications. |
| Digital Ecosystem Platform Integration | Plantweb and similar architectures bundle level transmitters with predictive diagnostics, compressing standalone instrument markets. |
Research Approach
A spread of perspectives from plant engineers, procurement leads at chemical processors, aftermarket service heads, and technical R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation against SEC filings, customs and trade data, EPA enforcement records, and IEC certification databases. Bottom-up segment sizing triangulated against top-down industry spend estimates across the analysis window.
Demand-supply-balance modeling anchored projections across product type, technology architecture, application severity, and end-user industry concentration dimensions. CAGRs derived from segment-level growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated EPA mandate implementation timelines, German chemical corridor modernization cadence, and wireless retrofit penetration assumptions in brownfield tank farms.
Sensitivities concentrate around EPA enforcement intensity, stainless steel price volatility, and IEC 61508 certification backlog durations. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or trade policy shifts. Cross-checking against customs import data for radar level transmitter HS codes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Chemical Sensors Market