
 Gas Detectors Market | 2026-2036
Gas Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Detectors Market Analysis
The gap between premium calibrated systems and commodity electrochemical units is realigning procurement patterns across industrial buyers. Honeywell International Inc. leverages its integrated safety platform to dominate large-scale facility deployments. MSA Safety Incorporated anchors its position through captive manufacturing of sensor elements. Drägerwerk AG & Co. KGaA differentiates via specialized breathing apparatus integration.
Gas detectors are electromechanical instruments that measure atmospheric concentrations of combustible, toxic, or oxygen-deficient gases through catalytic bead, infrared absorption, or electrochemical cell technologies, typically calibrated to parts-per-million sensitivity thresholds for hazardous environment alerting. Fixed installations command the largest revenue pool in oil and gas processing, while wireless connectivity represents the fastest structural expansion as mesh networks replace hardwired analog loops. Multi-gas configurations concentrate margin in emergency services applications where simultaneous H2S, CO, and LEL monitoring is mandatory.
OSHA permissible exposure limits and EPA air quality enforcement shape product specification requirements in the United States, while EU ATEX directives and IECEx certification govern equipment approval for explosive atmospheres across member states. China's GB standards and MIIT equipment regulations mandate domestic testing protocols that condition market access. Stakeholders must monitor sensor drift calibration intervals and cloud-platform interoperability as predictive maintenance models displace scheduled replacement cycles.
Market Dynamics
Fixed-system deployments in German industrial manufacturing are accelerating under tightened EU workplace safety directives, while electrochemical sensor miniaturization is compressing form factors for emergency responder wearables. These dual pressures are fragmenting procurement patterns between premium calibrated platforms and commodity electrochemical units.
Growth Catalysts
- EU ATEX Directives:Explosive atmosphere certification mandates are forcing facility upgrades across oil and gas processing corridors, expanding the installed base of fixed detection systems.
- Electrochemical Cell Miniaturization:Reduced power draw and package size are enabling continuous-monitoring wearables for confined-space emergency responders.
- Shanghai-Ningbo Chemical Belt:Concentrated petrochemical expansion under China's GB standards is driving multi-gas detector procurement for new plant construction.
Market Restraints
- Palladium Catalyst Volatility:Catalytic bead sensor production depends on platinum-group metal supply concentrated in South Africa and Russia, creating input cost instability.
- Calibration Drift Burden:Electrochemical cells require six-month recalibration cycles under OSHA permissible exposure limit enforcement, elevating total cost of ownership.
- Infrared Absorption Cost Floor:Non-dispersive infrared technology remains priced above electrochemical alternatives, limiting penetration in budget-constrained municipal fire departments.
Strategic Opportunities
- Cloud-Platform Interoperability:Predictive maintenance models displacing scheduled replacement cycles create white space for sensor-as-a-service offerings in large-scale manufacturing.
- Mesh Network Deployment:Wireless connectivity replacing hardwired analog loops opens retrofit opportunities in legacy oil and gas facilities across the Permian Basin.
- India's PLI Scheme:Domestic manufacturing incentives for industrial safety equipment are attracting component assembly investments near Gujarat chemical zones.
Industry Challenges
- Sensor Element Fabrication Talent:Captive manufacturing of electrochemical cells requires specialized electrochemist expertise that concentrates at MSA Safety and Drägerwerk facilities.
- IECEx Certification Timelines:Explosive atmosphere equipment approval processes extend 14-18 months, delaying product launches for modular detector platforms.
- Legacy System Integration:Hardwired 4-20mA analog loops in decades-old petrochemical plants resist wireless mesh retrofit without control system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Detectors Market |
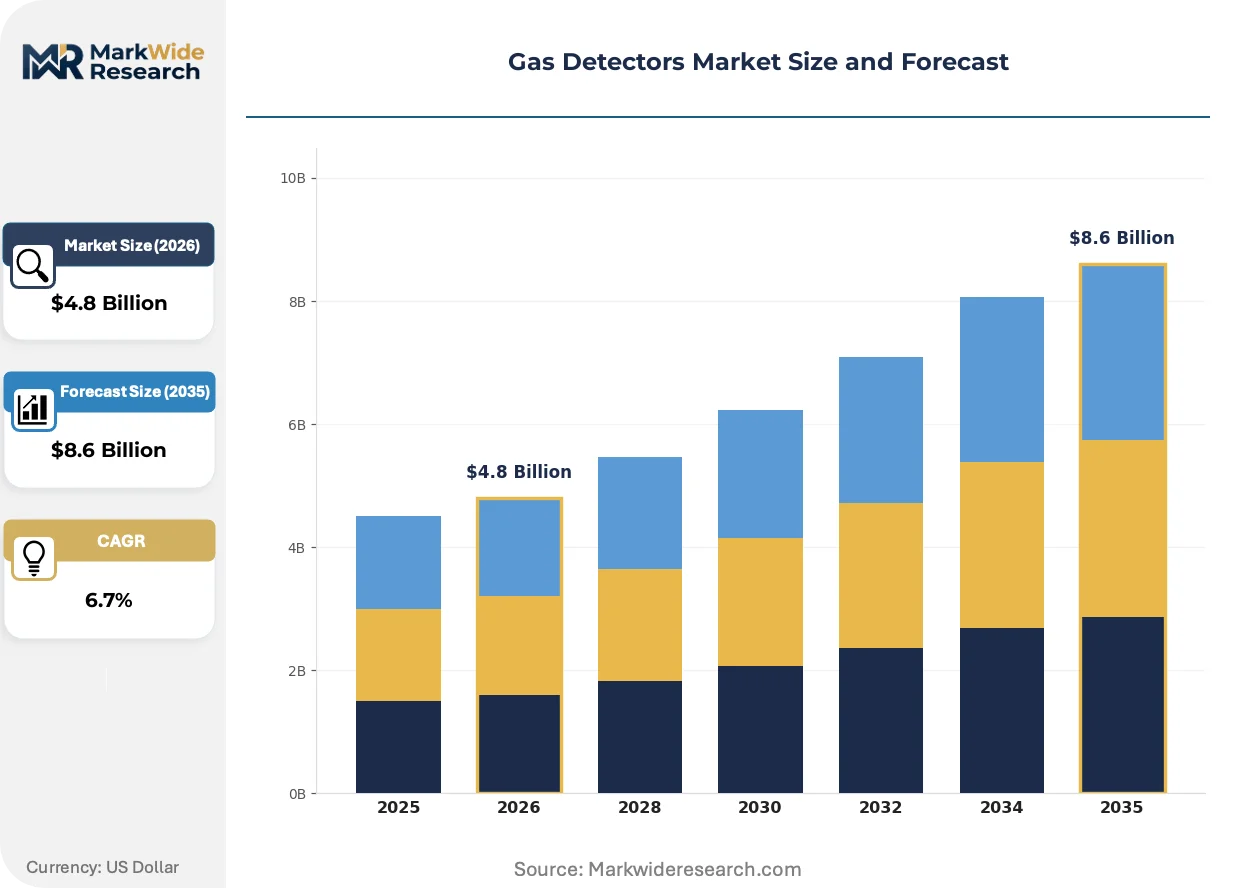
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Wireless, Multi-Gas Technology: Infrared, Electrochemical, Catalytic, PID Application: Industrial, Residential, Oil & Gas, Mining End User: Manufacturing, Healthcare, Emergency Services, Utilities |
| Companies Covered | Honeywell International Inc., MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Industrial Scientific Corporation, Teledyne Gas & Flame Detection, Emerson Electric Co., Siemens AG, RKI Instruments Inc., Halma plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Detectors Market Emerging Trajectories
Sensor fusion architectures and predictive analytics are compressing the traditional divide between detection hardware and safety management software. These convergences are redefining how industrial buyers evaluate total system value.
Photonic integrated circuits for infrared absorption detection are electrifying the path toward chip-scale gas analyzers. Semiconductor foundries in Taiwan and Germany are piloting wafer-level fabrication of tunable laser diodes for methane-specific detection. Oil and gas majors in the North Sea are field-testing these platforms for unmanned platform monitoring, collapsing the size and power requirements of traditional benchtop units.
EPA air quality enforcement under the Clean Air Act is tightening fugitive emission monitoring requirements for petrochemical valve and flange assemblies. Leak detection and repair programs now mandate optical gas imaging or method 21 analyzer deployment at quarterly intervals. Refinery operators in Texas and Louisiana are responding by consolidating procurement under integrated safety platform vendors capable of delivering both hardware and compliance documentation.
Buyer concentration among integrated energy majors is compressing vendor negotiation leverage and unbundling after-sales service contracts from initial equipment sales. Supermajor procurement teams in Houston and Rotterdam are demanding outcome-based calibration guarantees rather than per-unit hardware pricing. This shift is most visible in offshore platform deployments where downtime costs exceed sensor replacement values by orders of magnitude.
Gas Detectors Market Segmentation
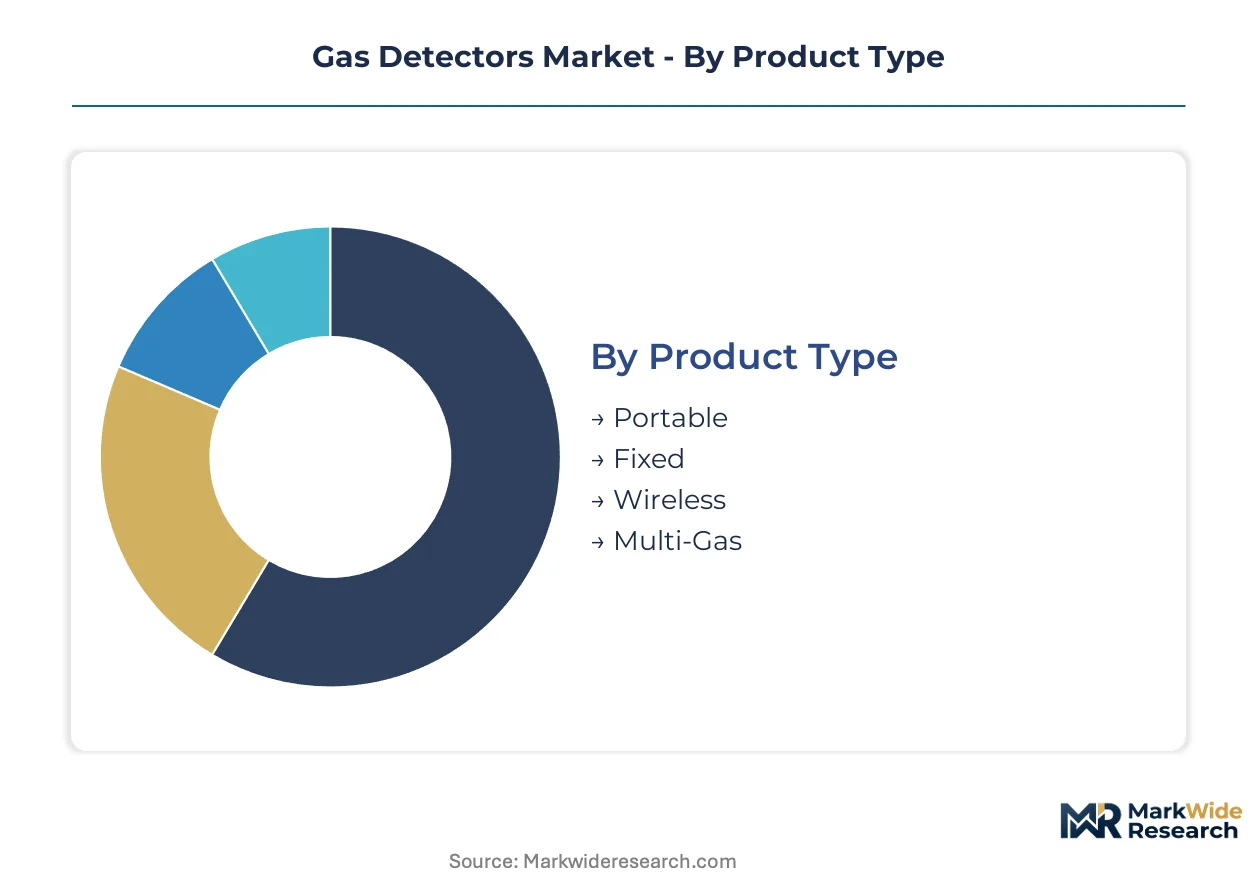
Gas detector procurement patterns fragment sharply across deployment contexts, with industrial buyers prioritizing calibration reliability while emergency responders demand miniaturized portability. Understanding these segment boundaries clarifies where technology investments concentrate and which specifications command premium pricing.
Product Type:
Supply concentration in electrochemical cell manufacturing tilts volume toward integrated platform vendors with captive sensor production.
- Portable:Battery-powered handheld units with electrochemical or catalytic bead sensors, typically weighing under 300 grams for personal protective equipment compliance. Demand clusters with emergency responders in Germany and confined-space contractors across China's chemical processing corridors, driven by EU ATEX directives mandating worker-worn monitoring in explosive atmospheres.
- Fixed:Permanently installed detection systems with 4-20mA analog or digital outputs, hardwired to control room annunciators. Oil and gas processing facilities in the Permian Basin and North Sea unmanned platforms absorb the bulk of deployments, where OSHA permissible exposure limits and EPA Clean Air Act enforcement require continuous perimeter monitoring.
- Wireless:Mesh-networked battery or solar-powered nodes transmitting to cloud dashboards. Municipal fire departments in budget-constrained regions are adopting these for retrofit applications where hardwired infrastructure proves cost-prohibitive.
- Multi-Gas:Simultaneous H2S, CO, LEL, and O2 detection in unified housings. Offshore platform operators and refinery maintenance crews specify these for hot-work permitting and vessel entry protocols.
Fixed systems absorb the bulk of installed capacity; wireless configurations are expanding most quickly as legacy facilities retrofit analog loops.
Technology:
Cost tiering separates premium infrared platforms from commodity electrochemical units, with catalytic bead sensors occupying a narrowing middle ground.
- Infrared:Non-dispersive absorption spectroscopy using tunable laser diodes or broadband sources with optical filters. Semiconductor foundries in Taiwan and Germany are piloting wafer-level fabrication, collapsing size and power requirements for methane-specific detection in North Sea unmanned platforms.
- Electrochemical:Amperometric cells with liquid or gel electrolytes reacting with target gases to generate current proportional to concentration. China's chemical processing belt around Shanghai and Ningbo drives volume procurement for new plant construction under GB standards and MIIT equipment regulations.
- Catalytic:Platinum-group metal bead sensors measuring combustion heat release from flammable gas oxidation. Palladium supply volatility from South African and Russian sources creates input cost instability, compressing margins for standalone sensor vendors without backward integration.
- PID:Photoionization detectors using ultraviolet lamps to ionize volatile organic compounds for total VOC measurement. Environmental remediation contractors and hazmat teams specify these for soil vapor intrusion and spill response characterization.
Electrochemical platforms dominate unit shipments; infrared absorption is gaining share fastest in premium process control applications.
Application:
Customer type differentiation separates specification-heavy industrial buyers from price-sensitive residential adopters, with oil and gas majors consolidating procurement under integrated safety vendors.
- Industrial:Manufacturing facilities with automated production lines requiring continuous atmospheric monitoring. German industrial plants are expanding fixed-system deployments under tightened EU workplace safety directives, with ATEX certification timelines extending 14-18 months.
- Residential:Single and multi-family dwellings with standalone or interconnected smoke and carbon monoxide alarms. Building code adoption varies by jurisdiction, with hardwired interconnected systems mandated in new construction across several US states.
- Oil & Gas:Upstream production, midstream transmission, and downstream refining operations. Supermajor procurement teams in Houston and Rotterdam are demanding outcome-based calibration guarantees rather than per-unit hardware pricing, compressing vendor negotiation leverage.
- Mining:Underground and surface extraction operations with methane, carbon monoxide, and oxygen deficiency hazards. MSHA regulations in the US and similar mining safety frameworks elsewhere mandate multi-gas personal monitors for all underground workers.
Oil and gas applications anchor revenue concentration; residential installations are climbing the fastest as smart home integration drives replacement cycles.
End User:
Margin structure varies dramatically across end users, with manufacturing accepting higher total cost of ownership for predictive maintenance integration while emergency services prioritize device portability.
- Manufacturing:Automotive, electronics, and chemical production facilities with process safety management obligations. Cloud-platform interoperability is displacing scheduled replacement cycles, creating white space for sensor-as-a-service offerings.
- Healthcare:Hospitals, laboratories, and pharmaceutical manufacturing with anesthetic gas and sterilization agent monitoring. Joint Commission accreditation requirements in the US drive specification of calibrated systems with documented traceability.
- Emergency Services:Fire departments, hazmat teams, and confined-space rescue units requiring intrinsically safe personal monitors. Electrochemical sensor miniaturization is compressing form factors for continuous-monitoring wearables.
- Utilities:Electric power generation, water treatment, and natural gas distribution infrastructure. Fugitive emission monitoring requirements under EPA enforcement are tightening procurement specifications for optical gas imaging or method 21 analyzer deployment.
Manufacturing absorbs the bulk of sensor element fabrication output; emergency services are expanding most quickly as wearable form factors mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo chemical belt concentrates multi-gas detector procurement for new plant construction under China's GB standards and MIIT equipment regulations.
United States
Permian Basin oil and gas operators drive wireless mesh retrofit demand as hardwired analog loops reach replacement age. EPA Clean Air Act enforcement tightens fugitive emission monitoring requirements for petrochemical valve assemblies. Refinery operators in Texas and Louisiana consolidate procurement under integrated safety platform vendors capable of delivering compliance documentation.
Germany
Industrial manufacturing facilities expand fixed-system deployments under tightened EU workplace safety directives. ATEX certification timelines extend 14-18 months for explosive atmosphere equipment approval. Chemical processing corridors along the Rhine-Ruhr region absorb the bulk of electrochemical sensor demand for continuous perimeter monitoring.
China
Petrochemical expansion concentrates procurement in the Yangtze River Delta around Shanghai and Ningbo. GB standards and MIIT equipment regulations mandate domestic testing protocols that condition market access. Semiconductor foundries pilot wafer-level fabrication of tunable laser diodes for methane-specific detection in unmanned platform applications.
India
Domestic manufacturing incentives under the PLI scheme attract component assembly investments near Gujarat chemical zones. The country's national industrial safety regulator mandates equipment certification for hazardous atmosphere deployments. Mumbai-Pune manufacturing clusters absorb portable detector volume for pharmaceutical and chemical production facilities.
United Kingdom
North Sea unmanned platforms field-test photonic integrated circuits for infrared absorption detection. EU ATEX directives continue governing equipment approval for explosive atmospheres during the post-Brexit transition. Aberdeen energy services hubs anchor demand for multi-gas configurations in offshore maintenance and hot-work permitting protocols.
Gas Detectors Market Vendor Landscape
Premium-margin players sit above commodity-margin players across calibration reliability and sensor element fabrication depth. Integrated safety platform vendors dominate large-scale facility deployments through bundled hardware and compliance documentation offerings. Three strategic archetypes populate the landscape: diversified industrial conglomerates with captive sensor production, specialized breathing apparatus integrators, and component-focused electrochemical cell manufacturers. Consolidation pressure intensifies as supermajor procurement teams demand outcome-based calibration guarantees rather than per-unit hardware pricing.
Within the integrated platform tier, Honeywell International Inc. and MSA Safety Incorporated occupy positions spanning industrial manufacturing and emergency responder applications. Drägerwerk AG & Co. KGaA anchors the specialized breathing apparatus integration segment. These three entities exemplify how backward integration into sensor element fabrication concentrates technical talent and compresses margins for standalone component vendors without captive electrochemical cell production.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| Industrial Scientific Corporation |
| Teledyne Gas & Flame Detection |
| Emerson Electric Co. |
| Siemens AG |
| RKI Instruments Inc. |
| Halma plc |
| Others |
Supply Flow & Price Mechanics
Specialized electrochemist talent concentrated in Pittsburgh and Lübeck feeds labor-cost differentials that widen pricing-tier spreads between premium calibrated platforms and commodity electrochemical units. This workforce scarcity forces buyers to absorb premium pricing for captive sensor production while budget-constrained municipal fire departments gravitate toward lower-tier alternatives.
Pricing Analysis
Outcome-based calibration guarantees anchor value-based pricing for supermajor procurement teams in Houston and Rotterdam. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified fixed systems from portable wearables and basic residential alarms. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in commodity electrochemical tiers is intensifying because palladium supply volatility from South African sources elevates input costs. Municipal fire departments exhibit highest price sensitivity; offshore platform operators accept premium tiers given downtime cost exposure.
Supply Chain Analysis
Single-source vulnerability sits with South African and Russian platinum-group metal suppliers that feed catalytic bead sensor production. Manufacturing draws from Germany, China, and the United States for electrochemical cell fabrication, with semiconductor foundries in Taiwan piloting wafer-level photonic integration. Raw material dependencies rest on palladium, platinum, and specialized electrolyte formulations. Tariff exposure on sensor element imports threatens margin stability for non-integrated vendors. Distribution runs through integrated safety platform vendors and specialized industrial distributors serving oil and gas corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gas Detectors Market sits in a technology-transition phase as wireless mesh networks displace hardwired 4-20mA analog loops across legacy petrochemical infrastructure. Photonic integrated circuits for infrared absorption are collapsing size and power requirements while reshaping competitive positioning.
For Market Incumbents: Extend cloud-platform interoperability capabilities to capture sensor-as-a-service recurring revenue before predictive maintenance models fully displace scheduled replacement cycles. Deepen backward integration into electrochemical cell production to defend against palladium cost volatility and compress margins for standalone component vendors. Prioritize IECEx certification pipeline investments to reduce 14-18 month approval timelines that delay modular platform launches.
For New Entrants and Emerging Players: EPA Clean Air Act enforcement in the United States opens a window for optical gas imaging specialists to penetrate refinery leak detection and repair programs. Target budget-constrained municipal fire departments in the Permian Basin with wireless mesh retrofit solutions where hardwired infrastructure proves cost-prohibitive. Pursue outcome-based calibration guarantee positioning to differentiate from per-unit hardware pricing commoditization.
For Investors and Strategic Acquirers: The window for entry favors electrochemical cell fabricators with captive sensor element production and specialized electrochemist workforces. Long-term viability centers on platforms capable of bridging detection hardware with safety management software convergence. Watch supermajor procurement consolidation patterns as the inflection signal for vendor negotiation leverage compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Elements | Captive electrochemical cell production insulates margins from palladium supply volatility. |
| Wireless Mesh Network Deployment | Retrofit opportunities in Permian Basin legacy facilities replace aging 4-20mA analog loops. |
| Cloud-Platform Interoperability Development | Predictive maintenance models displace scheduled replacement cycles in manufacturing. |
| IECEx Certification Acceleration | Reduced approval timelines enable faster modular detector platform launches under EU directives. |
| Photonic Integrated Circuit Adoption | Wafer-level fabrication in Taiwan collapses size requirements for North Sea unmanned platforms. |
Methodological Framework
Independent corroboration across safety equipment procurement managers, plant engineers at petrochemical facilities, and electrochemical sensor R&D directors underwrites the qualitative findings. Primary interviews with emergency responder equipment specialists, oil and gas maintenance directors, and industrial distributors combined with secondary validation from OSHA enforcement records, EPA Clean Air Act filings, EU ATEX directive documentation, and SEC 10-K disclosures from integrated platform vendors. Bottom-up unit economics and top-down sector sizing triangulate volume estimates.
Comparable-period anchoring to historical fixed-system deployment rates and portable detector replacement cycles structured the forecast window. Segmentation dimensions modeled include product type, detection technology, application vertical, and end-user category across the projection horizon. CAGRs derived from slope analysis of technology adoption curves and regulatory enforcement intensity. Forecast inputs incorporate IECEx certification timeline distributions and palladium price volatility assumptions.
The model assumes a particular technology adoption path; alternative pathways for photonic integrated circuit scale-up would alter the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and platinum-group metal supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market