
 Acoustic Breathing Sensor Market | 2026-2036
Acoustic Breathing Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Breathing Sensor Market Insights
Project finance for connected health infrastructure is narrowing the competitive field for acoustic breathing sensor developers. Masimo leverages its hospital-installed base to extend into continuous respiratory monitoring platforms. Medtronic anchors its position through deep integration with cardiac and neuromodulation care pathways where breathing metrics add clinical value. Honeywell International competes by applying its industrial sensor expertise to medical-grade acoustic detection at scale.
An acoustic breathing sensor detects and analyzes respiratory sounds, airflow patterns, and thoracic movements using microphone arrays, piezoelectric films, or ultrasonic transducers operating typically in the 20 Hz to 20 kHz audible and near-ultrasonic range to enable non-contact or minimally obtrusive patient monitoring. These devices serve primarily to enable early detection of respiratory deterioration, sleep apnea screening, and chronic obstructive pulmonary disease management without requiring facemasks or airflow cannulas. Wearable devices capture the largest revenue pool today as consumers accept wrist-worn and chest-patch formats for overnight sleep tracking, while integrated modules are growing fastest as original equipment manufacturers embed acoustic breathing capabilities into broader patient monitoring platforms and smart home health hubs. Stationary sensors retain importance in hospital step-down units where nursing staff require centralized multi-bed respiratory surveillance without per-patient disposable costs.
FDA 510(k) pathways and EU MDR Class IIa requirements govern acoustic breathing sensor commercialization, with FDA emphasizing clinical validation against predicate devices and MDR demanding notified body review of biocompatibility and software lifecycle documentation. Japan's PMDA adds a separate pharmaceuticals and medical devices agency consultation layer for acoustic-based diagnostic claims, extending timeline complexity for entrants targeting all three markets. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring and decide whether to pursue multi-regulatory submissions simultaneously or sequence market entry based on predicate device availability and clinical data reuse potential.
Market Dynamics
Remote patient reimbursement codes from CMS and parallel schemes in Germany and Japan are compressing hospital-centric business models toward home-based respiratory monitoring, forcing acoustic sensor developers to rearchitect for consumer-grade durability and cloud-native data pipelines.
Growth Catalysts
- FDA 510(k) predicate pathway:Clearance against existing pulse oximetry and acoustic stethoscope predicates accelerates market entry for novel sensor form factors targeting sleep apnea screening in the United States.
- EU MDR Class IIa respiratory device classification:Harmonized technical documentation requirements across notified bodies reduce fragmentation for manufacturers seeking multi-country European distribution.
- Piezoelectric MEMS fabrication:Wafer-level processing at Taiwan and South Korea foundries drives unit cost reduction for microphone arrays enabling non-contact thoracic movement detection.
Market Restraints
- MEMS microphone supply concentration:Foundry capacity constraints in East Asia create input volatility for sensor module assemblers dependent on 6-inch and 8-inch wafer allocations.
- EU MDR notified body bottlenecks:Extended review timelines for software lifecycle documentation delay commercialization for acoustic diagnostic claims requiring Class IIa certification.
- Optical PPG substitution:Wrist-worn photoplethysmography devices from consumer electronics manufacturers capture overlapping sleep-monitoring demand at lower price points.
Strategic Opportunities
- Japan's PMDA respiratory diagnostic pathway:Early consultation frameworks for acoustic-based disease claims create first-mover positioning for validated clinical datasets.
- Smart home health hub integration:Original equipment manufacturers embedding acoustic breathing modules into ambient monitoring systems unlock recurring software revenue streams.
- Machine learning inference at the edge:On-device neural processing of respiratory sound patterns reduces cloud dependency and latency for real-time deterioration alerts in step-down units.
Industry Challenges
- Clinical validation workforce scarcity:Recruitment of respiratory physiologists and acoustic signal processing engineers extends product development timelines for startups competing against established hospital device manufacturers.
- Legacy patient monitoring system integration:Proprietary data protocols from incumbent bedside monitor vendors require custom middleware development for acoustic sensor interoperability.
- Biocompatibility testing capex:ISO 10993 cytotoxicity and sensitization studies for skin-contact wearable formats demand upfront investment before regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Breathing Sensor Market |
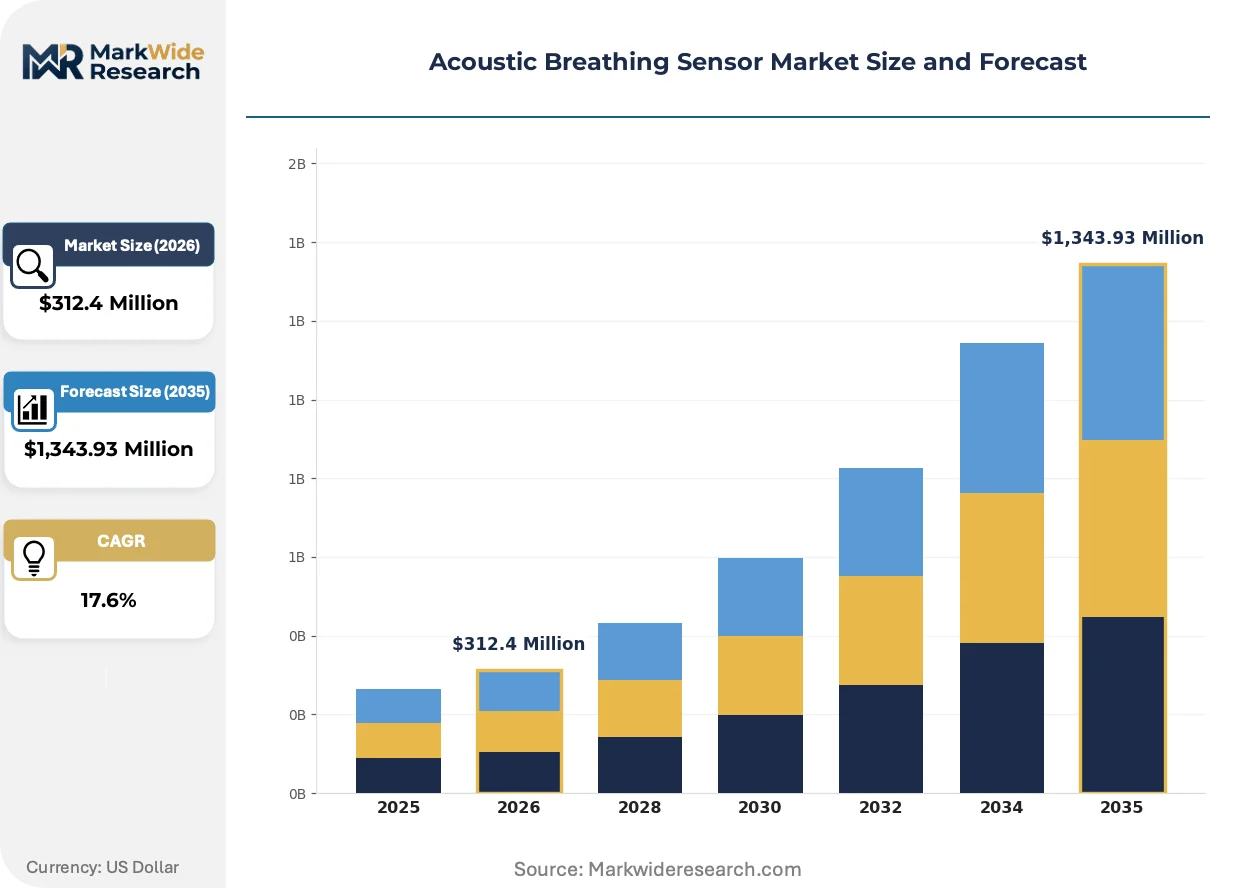
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,343.93 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Device, Stationary Sensor, Integrated Module, Smartphone Accessory Application: Healthcare Monitoring, Sleep Tracking, Fitness Management, Respiratory Diagnostics End User: Hospitals, Home Care, Fitness Centers, Research Institutions Technology: Ultrasonic, Microphone Array, Piezoelectric, Optical |
| Companies Covered | Masimo, Medtronic, Zephyr Sleep Technologies, Vyaire Medical, Nonin Medical, Honeywell International, Murata Manufacturing, TDK Corporation, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Breathing Sensor Market Trends and Innovations
Signal processing architectures and reimbursement policy redesign are converging to relocate respiratory monitoring from intensive care units to domestic environments, compressing the traditional care delivery chain.
Beamforming microphone arrays with adaptive noise cancellation are collapsing the distinction between clinical-grade and consumer-grade acoustic detection. Sleep technology vendors in the United States and Germany are adopting these arrays for overnight breathing analysis without medical device certification. The cost compression is enabling direct-to-consumer distribution channels previously reserved for fitness trackers.
EU MDR's enhanced clinical evidence requirements for software-as-a-medical-device are forcing acoustic breathing sensor developers to maintain prospective patient registries. Manufacturers targeting Class IIa diagnostic claims must now submit post-market surveillance plans during initial conformity assessment. German notified bodies are applying the most stringent interpretation of algorithm change control protocols, extending timeline risk for machine learning-enabled products.
Hospital procurement departments are unbundling respiratory monitoring from bundled capital equipment contracts. Standalone acoustic sensor purchases with software subscription pricing are displacing multi-parameter monitor upgrades in United States health systems facing margin pressure. This shift is most pronounced in integrated delivery networks with value-based care contracts covering chronic obstructive pulmonary disease readmission penalties.
Acoustic Breathing Sensor Market Segmentation
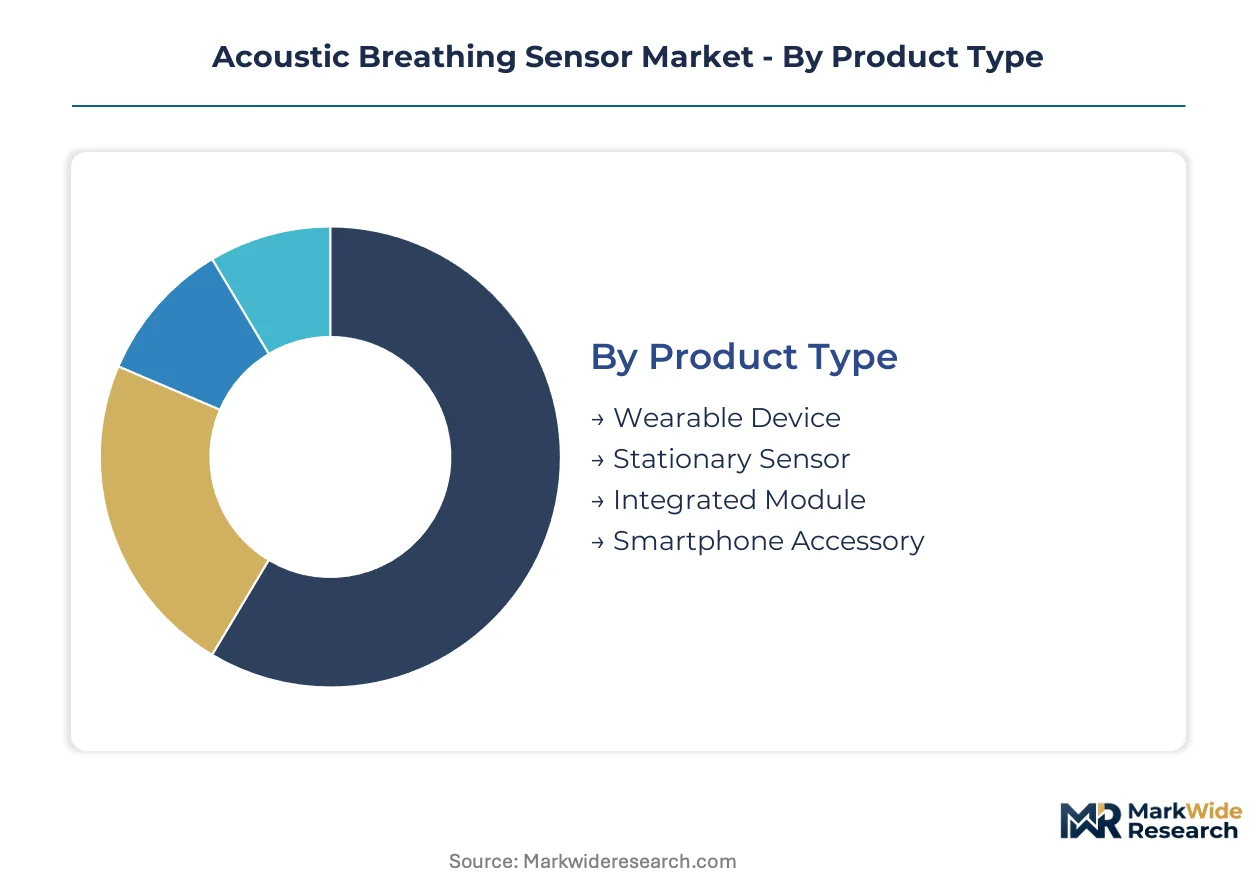
Acoustic breathing sensor manufacturers configure warranty terms and calibration service contracts differently across product architectures. Wearable formats demand frequent firmware updates and battery replacement programs, while stationary installations require multi-year maintenance agreements covering microphone array recalibration.
Product Type:
After-sales service intensity varies sharply by hardware architecture and deployment environment.
- Wearable Device:Wrist-worn and chest-patch formats incorporate MEMS microphone arrays and piezoelectric films for overnight respiratory monitoring. Demand clusters in United States direct-to-consumer channels where sleep apnea screening reimbursement creates pull for prescription-grade units.
- Stationary Sensor:Wall-mounted or bedside units deploy beamforming arrays for multi-patient surveillance in step-down units. German hospital procurement departments favor these for centralized respiratory monitoring without per-patient disposable costs.
- Integrated Module:OEM-embeddable subsystems for patient monitoring platforms and smart home health hubs.
- Smartphone Accessory:Plug-in or clip-on peripherals leveraging phone processing for acoustic analysis.
By volume, Wearable Device leads. By growth pace, Integrated Module is ahead.
Application:
Cost tier stratification separates clinical-grade certifications from consumer wellness positioning.
- Healthcare Monitoring:Continuous respiratory surveillance for early deterioration detection in hospital and home settings. United States integrated delivery networks with COPD readmission penalties drive procurement of FDA-cleared devices with cloud-native data pipelines.
- Sleep Tracking:Overnight breathing pattern analysis for apnea screening and sleep quality assessment. Japanese consumers show strong acceptance of non-contact thoracic movement detection for home-based diagnostic workflows.
- Fitness Management:Breathing rate tracking during exercise for athletic performance optimization.
- Respiratory Diagnostics:Acoustic-based disease characterization for clinical decision support.
Healthcare Monitoring commands premium pricing. Sleep Tracking is expanding most quickly.
End User:
Customer type determines regulatory pathway complexity and sales cycle duration.
- Hospitals:Acute care and step-down units requiring Class IIa MDR or FDA 510(k) cleared devices with EMR integration. German notified bodies apply stringent algorithm change control protocols for machine learning-enabled products in this channel.
- Home Care:Post-discharge monitoring and chronic disease management in domestic settings. CMS remote therapeutic monitoring reimbursement codes in the United States compress hospital-centric business models toward this segment.
- Fitness Centers:Wellness-oriented breathing analysis for member retention programs.
- Research Institutions:Clinical validation studies and algorithm development partnerships.
Home Care shows the steepest expansion trajectory. Hospitals retain the highest average selling prices.
Technology:
Supply concentration for core components shapes manufacturing geography and cost structure.
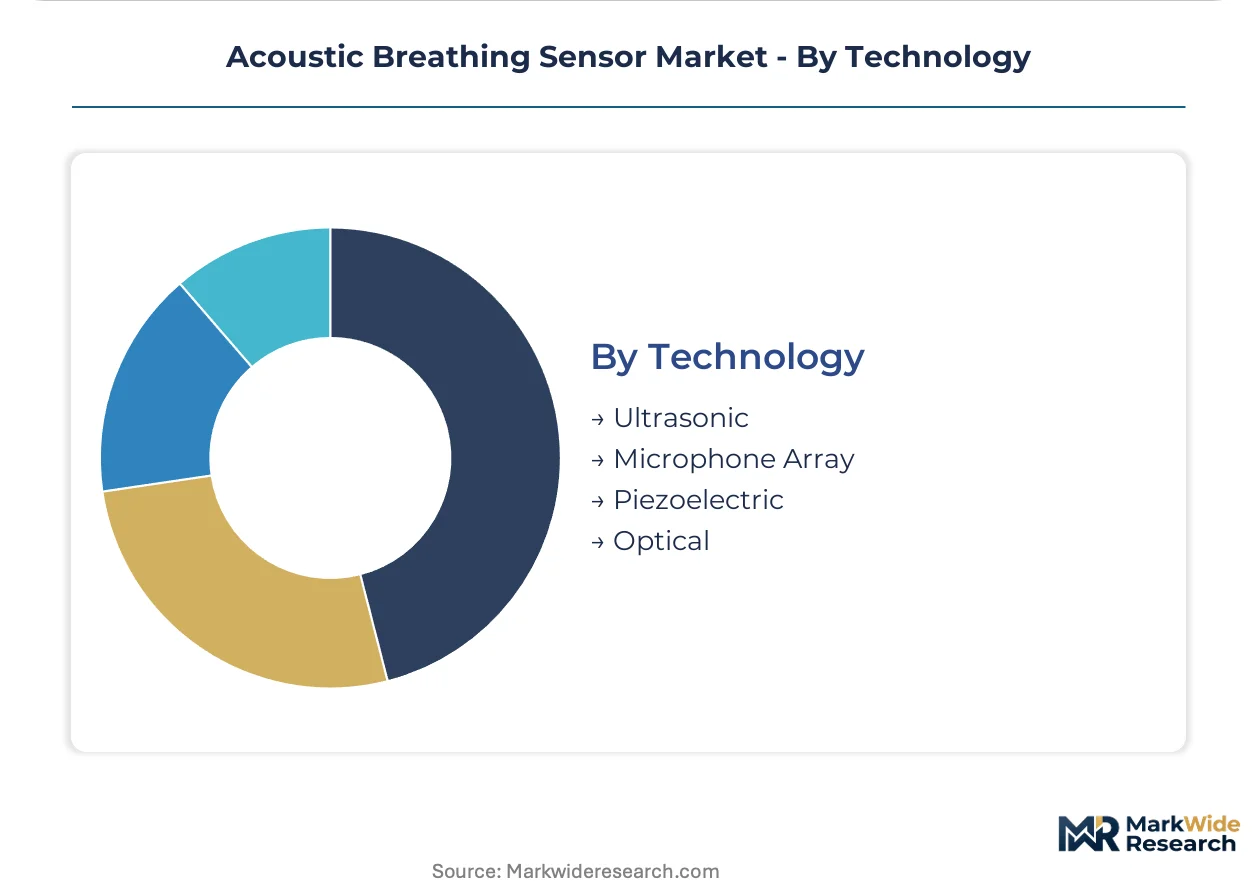
- Ultrasonic:Near-audible frequency transducers for non-contact thoracic movement detection without skin contact.
- Microphone Array:Beamforming configurations with adaptive noise cancellation collapsing the clinical-consumer grade distinction. Taiwan and South Korea foundries supply wafer-level MEMS fabrication.
- Piezoelectric:Thin-film sensors detecting mechanical deformation from breathing-induced body surface vibrations.
- Optical:Photoplethysmography-based alternatives capturing overlapping respiratory signals through light absorption analysis.
Microphone Array dominates unit shipments. Piezoelectric is gaining share fastest in wearable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers capture premium pricing for FDA-cleared acoustic breathing sensors, while German producers face margin compression from EU MDR compliance costs and notified body bottlenecks.
United States
Integrated delivery networks with COPD readmission penalties drive procurement of cloud-native respiratory monitoring platforms. CMS remote therapeutic monitoring reimbursement codes compress hospital-centric business models toward home-based deployment. Greater Boston and Silicon Valley clusters concentrate venture-backed acoustic sensor startups targeting direct-to-consumer sleep apnea screening channels.
Germany
Hospital procurement departments favor centralized multi-bed respiratory surveillance without per-patient disposable costs. EU MDR Class IIa notified bodies apply stringent algorithm change control protocols for machine learning-enabled diagnostic claims. The Baden-Württemberg medical technology corridor hosts established patient monitor manufacturers embedding acoustic modules into broader platforms.
Japan
Aging demographics and home-based diagnostic workflow acceptance create sustained demand for non-contact thoracic movement detection. PMDA pharmaceuticals and medical devices agency consultation requirements extend timeline complexity for acoustic-based disease claims. The Kanto region around Tokyo concentrates respiratory device distributors navigating reimbursement negotiations with national health insurance.
South Korea
Wafer-level MEMS microphone fabrication at domestic foundries supplies cost-competitive microphone arrays for wearable formats. MFDS medical device regulations align with international standards but require Korean-language labeling and local clinical evidence. The Seoul Capital Area anchors contract manufacturing relationships with United States and European acoustic sensor developers.
United Kingdom
NHS long-term plan commitments to remote patient monitoring create procurement pull for home-deployable respiratory surveillance. MHRA post-Brexit regulatory pathways maintain alignment with EU MDR technical standards while streamlining domestic conformity assessment. The Oxford-Cambridge arc concentrates acoustic signal processing research partnerships between universities and medical device developers.
Acoustic Breathing Sensor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying MEMS microphone arrays and piezoelectric films to module assemblers. The acoustic breathing sensor market structures around three archetypes: hospital-installed base extenders leveraging bedside monitor relationships, industrial sensor crossover players applying manufacturing scale to medical-grade detection, and semiconductor foundries capturing value through wafer-level acoustic component fabrication. Dominant competitive moves include strategic partnerships for EMR interoperability middleware and backward integration into MEMS fabrication capacity to secure supply.
Among diversified industrial technology groups, Honeywell International exemplifies the crossover archetype applying sensor manufacturing scale to medical acoustic detection. Masimo and Medtronic represent the hospital-installed base tier, with the former extending pulse oximetry platforms into continuous respiratory monitoring and the latter anchoring integration with cardiac and neuromodulation care pathways. These three companies occupy distinct competitive positions without direct product overlap, reducing price-based confrontation in favor of channel-specific segmentation.
| Leading Market Players |
|---|
| Masimo |
| Medtronic |
| Zephyr Sleep Technologies |
| Vyaire Medical |
| Nonin Medical |
| Honeywell International |
| Murata Manufacturing |
| TDK Corporation |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Taiwan's MEMS foundry cluster in Hsinchu Science Park anchors wafer-level microphone fabrication, translating capacity allocation decisions directly into module pricing power for acoustic sensor assemblers. German hospital procurement departments and United States integrated delivery networks absorb cost volatility differently, with the former favoring multi-year maintenance contracts and the latter accepting per-unit SaaS pricing for cloud-native respiratory platforms.
Pricing Analysis
Configured-to-order pricing for FDA-cleared hospital systems commands substantial premiums over standard direct-to-consumer sleep tracking units. Three-tier pricing structure across premium, standard, and economy levels separates Class IIa MDR-certified diagnostic devices from wellness-grade consumer formats and unbranded OEM modules. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in consumer tiers is intensifying because optical PPG substitutes from consumer electronics manufacturers capture overlapping sleep-monitoring demand. Home care buyers show highest price sensitivity; hospital purchasing committees with COPD readmission penalty exposure demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for acoustic sensor developers sourcing packaged MEMS components. Manufacturing concentrates in Taiwan, South Korea, and China for wafer-level MEMS fabrication, piezoelectric film deposition, and final module assembly. Raw material dependencies include silicon wafers, rare-earth elements for piezoelectric ceramics, and specialized acoustic membranes. Single-source vulnerability concentrates in 6-inch and 8-inch foundry capacity for beamforming microphone arrays. Distribution runs through medical device distributors in Germany, GPO contracts in United States health systems, and direct-to-consumer channels for sleep technology vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as EMR interoperability becomes the primary value capture mechanism, with hospital system partnerships and middleware integration determining which sensor architectures achieve sustained procurement pull.
For Market Incumbents: Pre-empt optical PPG substitution by embedding acoustic modules into broader patient monitoring platforms with proprietary data protocols. Backward integration into MEMS fabrication capacity in Taiwan or South Korea secures supply against foundry allocation volatility. Deepen software subscription revenue through cloud-native respiratory analytics that lock hospital customers into integrated workflows. For New Entrants and Emerging Players: Establish a beachhead in Japan's home-based diagnostic workflow segment where PMDA consultation requirements deter rapid incumbent response. Target direct-to-consumer sleep apnea screening in United States markets where CMS reimbursement codes create prescription-grade pull without hospital sales cycle complexity. Lead with smartphone-integrated accessories leveraging existing device processing power to minimize hardware BOM costs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial technology groups with undermonetized medical sensor divisions and stranded MEMS fabrication assets. Five-to-ten year viability hinges on regulatory data moats rather than hardware differentiation alone. Watch for FDA 510(k) clearance acceleration timelines as the signal indicating which algorithm-enabled products achieve sustainable reimbursement positioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway Acceleration | Clearance against pulse oximetry predicates compresses entry timelines for novel form factors in United States sleep apnea screening. |
| EU MDR Class IIa Certification Investment | Notified body relationships in Germany unlock multi-country European distribution with harmonized technical documentation requirements. |
| Hospital System Partnership Development | Integrated delivery networks with COPD readmission penalties prioritize EMR-embedded respiratory surveillance with subscription pricing. |
| MEMS Foundry Capacity Securement | Wafer-level fabrication commitments in Taiwan and South Korea insulate against input volatility for microphone array supply. |
| Smart Home Health Hub Integration | OEM-embeddable modules unlock recurring software revenue through ambient monitoring platforms in domestic environments. |
Research Methodology
The analysis maps wearable devices, stationary sensors, integrated modules, and smartphone accessories, each validated through respiratory physiologists, biomedical engineers, hospital purchasing committee members, and acoustic signal processing specialists. Primary interviews with device manufacturers, foundry operators, and reimbursement consultants combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and GPO contract repositories. Bottom-up unit shipment modeling and top-down value chain triangulation converged on segment-level estimates.
Assumptions held fixed include regulatory pathway timelines, foundry capacity allocation patterns, and reimbursement code stability, while pricing elasticity and substitution rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass product architecture, application tier, end-user channel, and technology type alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to validated base-year estimates, with acoustic algorithm clinical validation timelines and cloud infrastructure deployment rates as key forecast inputs across the projection horizon.
Stress conditions across MEMS supply concentration, EU MDR notified body backlog duration, and optical PPG substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement policy continuity and regulatory harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market