
 Europe Pressure Sensors Market | 2026-2036
Europe Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pressure Sensors Market Foresight
The Europe pressure sensors landscape is recalibrating around a widening gap between precision-engineered units for safety-critical applications and cost-optimized commodity sensors for bulk industrial use. ABB Ltd leverages its process automation heritage to dominate high-reliability installations in chemical and energy infrastructure. Bosch Sensortec GmbH anchors the automotive tier with MEMS-based designs calibrated for electric vehicle thermal management. Endress+Hauser AG differentiates through vertical integration into sensor-specific silicon fabrication, sustaining margin pools that commodity competitors cannot replicate.
Pressure sensors are transducers that convert fluid or gas pressure into electrical signals, typically operating across ranges from millibars to thousands of bars with accuracy classes down to 0.025 percent of span. Piezoelectric variants exploit crystalline quartz or ceramic elements to measure dynamic pressure pulses in combustion and injection systems, while capacitive designs use micromachined diaphragms for stable low-pressure sensing in HVAC and medical ventilation. Silicon-based MEMS technology leads unit volume across European automotive and consumer applications due to batch-fabrication economies, though optical pressure sensing is gaining ground in hazardous environments where electrical isolation prevents ignition risks. Smart pressure sensors with embedded diagnostics and digital communication protocols represent the fastest-expanding product category as Industry 4.0 architectures demand edge-level data preprocessing.
The EU Green Deal and F-Gas Regulation are mandating tighter leak detection in refrigeration and industrial cooling, directly expanding demand for differential and gauge pressure instrumentation with parts-per-million sensitivity. EMA and national notified bodies enforce CE marking and MDR compliance for sensors deployed in medical and safety-critical contexts, raising barriers for non-European suppliers lacking established conformity infrastructure. REACH restrictions on hazardous substances further constrain material choices in sensor packaging and bonding processes. Stakeholders must monitor how the EU AI Act and emerging cybersecurity standards for connected industrial devices reshape certification requirements for smart sensor platforms before committing to next-generation product roadmaps.
Market Dynamics
The Europe pressure sensors market is bifurcating around precision-grade instrumentation for safety-critical applications versus commodity sensors for bulk industrial deployment, with MEMS fabrication economics and F-Gas Regulation compliance timelines acting as the dominant sorting mechanisms.
Growth Catalysts
- EU Green Deal mandates:The F-Gas Regulation tightens leak detection thresholds in refrigeration and industrial cooling, forcing OEMs to source differential pressure sensors with parts-per-million sensitivity for compliance.
- Automotive electrification:Battery thermal management systems in electric vehicles require multi-point pressure monitoring, expanding sensor counts per vehicle from legacy internal combustion architectures.
- Silicon MEMS batch fabrication:Wafer-level processing at foundries in Germany and France compresses unit costs for high-volume automotive and consumer applications, enabling price-competitive substitution of legacy piezoresistive designs.
Market Restraints
- Raw material concentration:High-purity silicon wafer supply concentrates among a handful of European and Asian suppliers, exposing sensor fabricators to input cost volatility and allocation risk during semiconductor cycle peaks.
- REACH substance restrictions:The European Chemicals Agency limits hazardous materials in sensor bonding and packaging processes, forcing reformulation of established product lines and extending qualification timelines.
- Optical sensing substitution:Fiber-optic pressure transducers penetrate hazardous environments where electrical isolation prevents ignition risks, displacing conventional electrical sensors in oil and gas installations.
Strategic Opportunities
- Poland and Czech manufacturing corridors:Industrial automation investments concentrate in Central European automotive and electronics clusters, creating localized demand for mid-range pressure instrumentation with shorter logistics lead times.
- EU AI Act certification:Early alignment of smart sensor platforms with emerging cybersecurity and algorithmic transparency standards opens preferential positioning for connected industrial devices in EU-procured infrastructure.
- Edge preprocessing convergence:Integration of MEMS sensing elements with embedded AI accelerators enables real-time anomaly detection at the sensor node, reducing bandwidth burdens on Industry 4.0 control systems.
Industry Challenges
- MDR conformity timelines:Medical device regulation certification for sensors deployed in ventilation and dialysis equipment extends validation cycles, compressing product refresh windows and straining regulatory affairs staffing.
- Legacy system integration:Analog-output pressure sensors predominate in installed industrial base, forcing digital-native suppliers to maintain dual-protocol product lines and field retrofit expertise.
- Cross-functional talent scarcity:Sensor design requires simultaneous competence in MEMS fabrication, signal conditioning electronics, and embedded software, with European technical universities producing insufficient hybrid graduates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pressure Sensors Market |
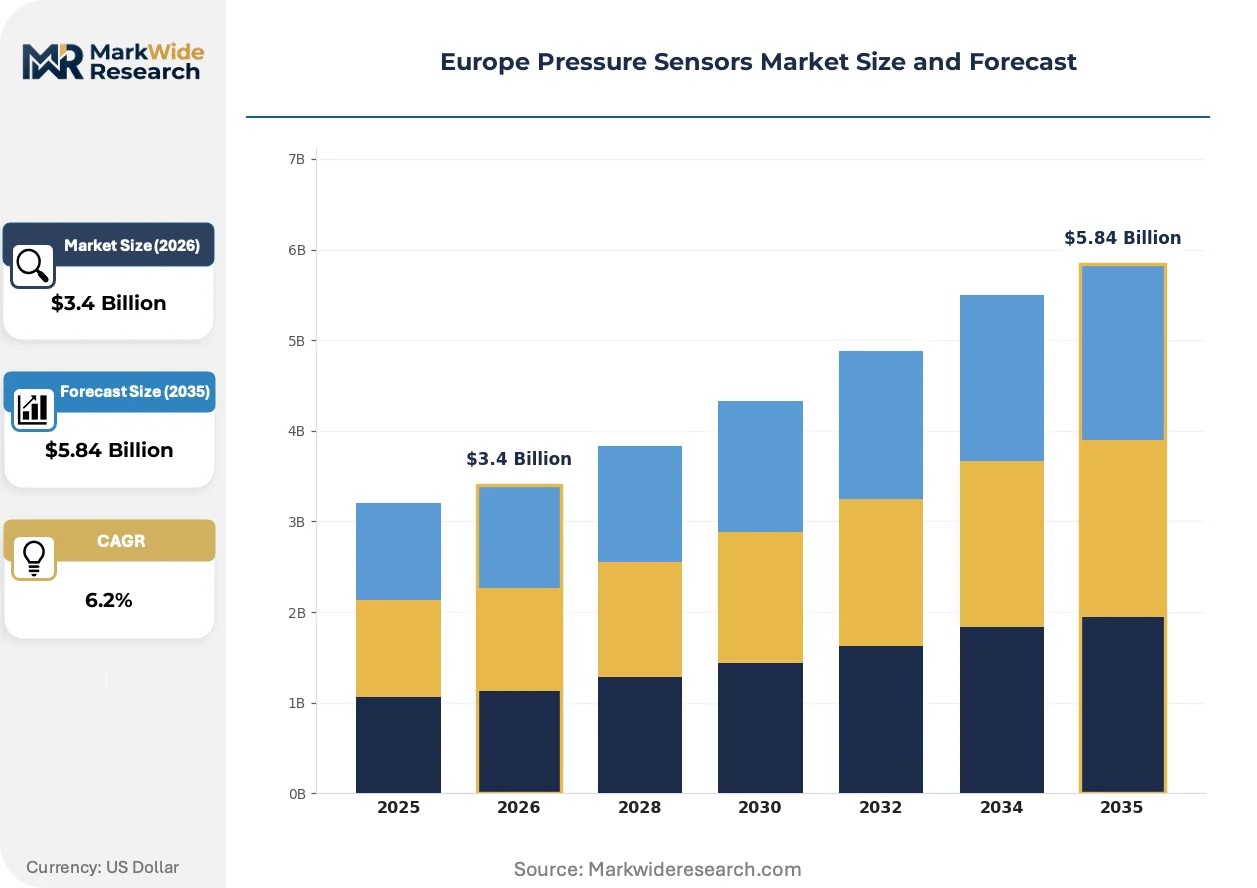
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Gauge, Differential, Smart Technology: Silicon, Piezoelectric, Capacitive, Optical End User: Aerospace, Automotive, Healthcare, Industrial Application: Process Control, Level Measurement, HVAC, Food & Beverage |
| Companies Covered | ABB Ltd, Bosch Sensortec GmbH, Endress+Hauser AG, Schneider Electric SE, Kistler Group, Siemens AG, Honeywell International Inc., Infineon Technologies AG, TE Connectivity Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pressure Sensors Market Shifts & Advancements
Sensor architectures are fragmenting between edge-intelligent platforms with embedded diagnostics and stripped-down commodity units, with connectivity protocols and preprocessing capabilities becoming the primary differentiation vectors.
Silicon carbide MEMS pressure sensing is modularizing thermal management architectures in electric vehicle battery packs. Automotive tier-one suppliers in Germany are adopting these designs for 800-volt architectures. The technology is modularizing sensor integration with cooling loop manifolds, reducing component count and assembly labor.
The EU AI Act establishes conformity requirements for autonomous decision-making in industrial control systems. Smart pressure sensors with embedded diagnostic algorithms face expanded documentation and validation burdens. Process automation OEMs in France and Italy are front-loading compliance investments to secure notified body approval ahead of enforcement deadlines.
After-sales service unbundling accelerates as German chemical and energy operators pressure sensor vendors to separate hardware procurement from calibration contracts. Third-party metrology laboratories in the Netherlands and Belgium capture recurring revenue streams. This pattern concentrates in safety-critical installations where ISO 17025 traceability supersedes manufacturer certificates.
Europe Pressure Sensors Market Segmentation
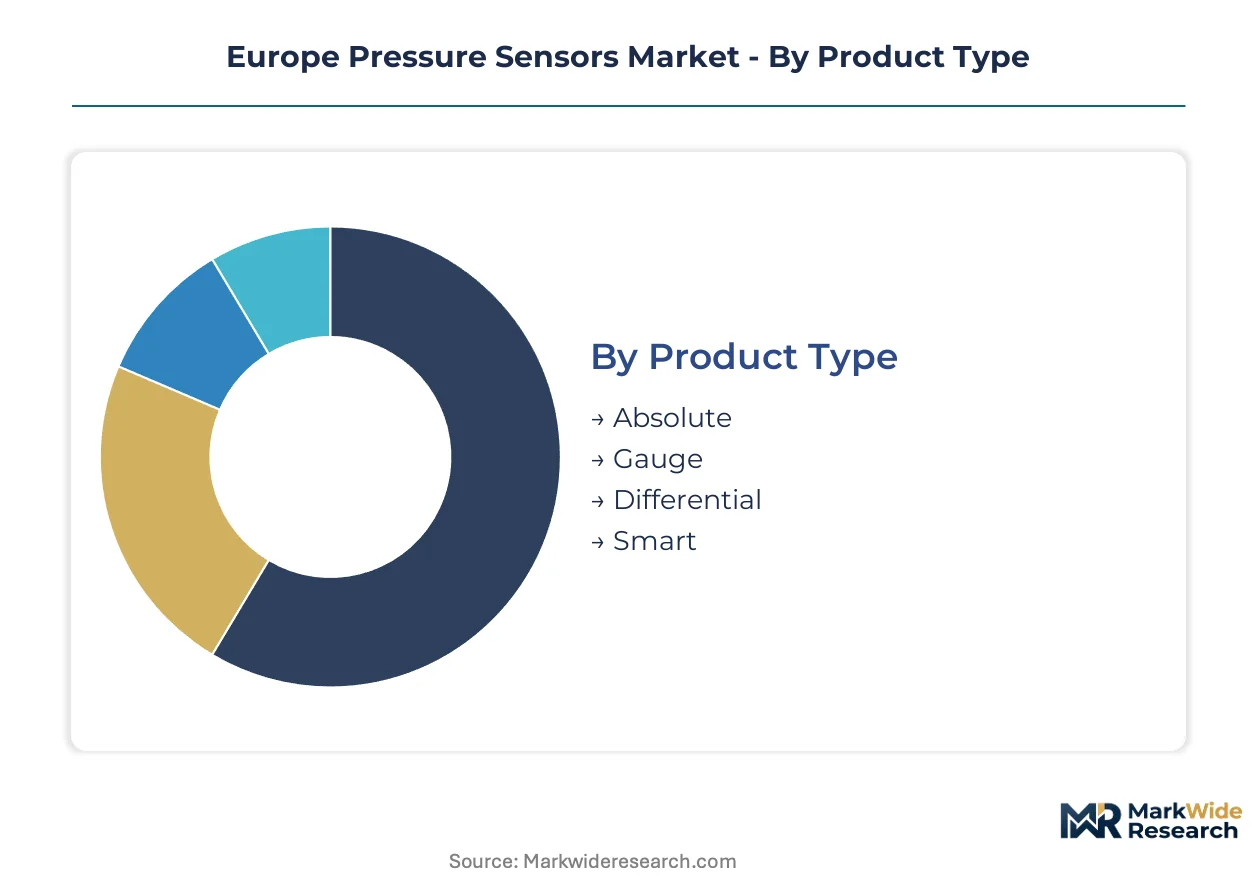
Pressure sensor procurement in Europe splits sharply between precision-grade instrumentation for safety-critical environments and cost-optimized units for bulk industrial deployment. The F-Gas Regulation and MDR compliance timelines force buyers to weight certification grade heavily in sourcing decisions.
Product Type:
Buyers differentiate primarily by measurement reference frame and intelligence integration, with regulatory compliance costs driving tiered procurement strategies.
- Absolute:Measures pressure relative to a perfect vacuum using sealed reference cavities. German automotive battery pack manufacturers specify these for altitude-compensated thermal management in electric vehicles, where barometric drift would corrupt cooling loop calculations.
- Gauge:References ambient atmospheric pressure through vented designs. Industrial automation corridors in Poland and the Czech Republic absorb bulk volumes for pneumatic system monitoring, prioritizing unit cost over absolute accuracy.
- Differential:Captures pressure variance between two process points. REACH-constrained bonding processes limit supplier options for high-purity variants used in pharmaceutical cleanrooms.
- Smart:Embeds diagnostics and digital communication protocols. EU AI Act pre-certification investments by French process automation OEMs concentrate development resources here.
Gauge sensors lead volumes today; Smart sensors are gaining share fastest.
Technology:
Manufacturing scale and material purity requirements sort technologies into automotive high-volume versus industrial specialty tiers.
- Silicon:Leverages wafer-level MEMS batch fabrication at foundries in Germany and France. Piezoresistive elements diffuse into micromachined diaphragms for automotive thermal management and consumer applications where unit economics dominate.
- Optical:Fiber-optic transducers eliminate electrical ignition risks in hazardous environments. North Sea oil and gas operators specify these for subsea wellhead monitoring, displacing conventional electrical sensors where ATEX compliance is prohibitive.
- Piezoelectric:Quartz or ceramic crystals measure dynamic pressure pulses. Italian combustion system manufacturers deploy these for injection timing optimization in high-performance engines.
- Capacitive:Micromachined diaphragms vary electrode spacing for stable low-pressure sensing. HVAC and medical ventilation equipment in the Netherlands and Belgium specify these for drift-critical applications.
Silicon dominates unit shipments; Optical is expanding most quickly in hazardous environment substitution.
End User:
End-use concentration in Central European manufacturing clusters concentrates demand for mid-range instrumentation with localized logistics requirements.
- Automotive:Battery thermal management systems multiply sensor counts per vehicle. German tier-one suppliers specify silicon MEMS designs calibrated for 800-volt architectures and coolant manifold integration.
- Industrial:Process automation investments concentrate in Polish and Czech automotive-electronics corridors. Chemical operators in Germany unbundle calibration contracts from hardware procurement, shifting recurring revenue to third-party metrology laboratories.
- Healthcare:MDR certification for ventilation and dialysis equipment extends validation cycles. EMA and notified body scrutiny compresses product refresh windows for sensor vendors.
- Aerospace:Flight-critical applications demand traceable calibration chains. French and Italian airframe manufacturers specify piezoelectric variants for engine monitoring with ISO 17025 documentation requirements.
Industrial absorbs the largest volume; Automotive is climbing the fastest on electrification sensor multiplication.
Application:
Application selection tracks directly to regulatory enforcement intensity, with F-Gas Regulation leak detection mandates creating differentiated demand profiles.
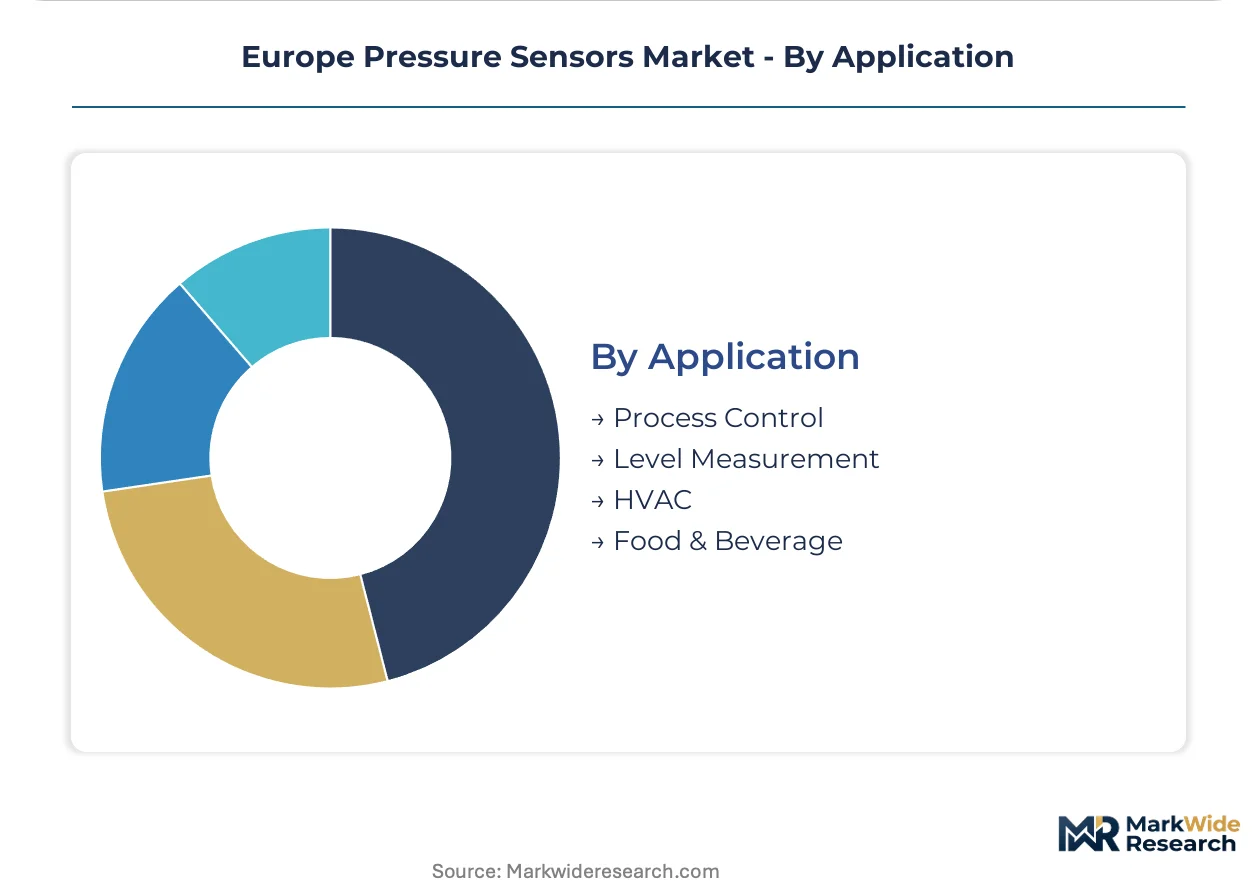
- HVAC:F-Gas Regulation mandates tighten leak detection thresholds in refrigeration and industrial cooling. Differential pressure sensors with parts-per-million sensitivity face forced replacement cycles across installed building stock.
- Process Control:Continuous manufacturing lines demand real-time pressure feedback. German chemical operators specify smart sensors with embedded diagnostics to reduce bandwidth burdens on Industry 4.0 control architectures.
- Level Measurement:Hydrostatic pressure inference monitors tank and vessel contents. Food and beverage processors in Spain and Portugal prioritize hygienic designs with CIP-compatible wetted materials.
- Food & Beverage:EFSA hygiene regulations constrain material choices in sensor packaging. Stainless steel diaphragm designs with 3-A sanitary certifications dominate new equipment specifications.
Process Control leads current deployment; HVAC faces the steepest expansion trajectory on regulatory compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized MEMS fabrication engineers and precision instrumentation technicians concentrate in Central European manufacturing corridors, anchoring regional supply capacity for automotive and industrial sensor demand.
Germany
Battery thermal management systems for 800-volt electric vehicle architectures multiply sensor counts per vehicle. The KBA enforces type approval standards for automotive safety systems, compressing qualification timelines for new designs. Stuttgart and Munich manufacturing clusters host tier-one supplier engineering centers where silicon MEMS integration with cooling loop manifolds reduces assembly complexity.
France
Process automation OEMs front-load EU AI Act compliance investments for smart sensor platforms with embedded diagnostics. The ANSM and notified bodies scrutinize connected device cybersecurity documentation. Lyon and Grenoble industrial corridors concentrate development resources on pre-certification validation for edge-intelligent pressure instrumentation.
Italy
Combustion system manufacturers deploy piezoelectric variants for injection timing optimization in high-performance engines. ECHA REACH restrictions on hazardous substances constrain bonding process formulations in established product lines. Turin and Bologna automotive clusters absorb precision-grade instrumentation for powertrain development and testing facilities.
Poland
Industrial automation investments in automotive-electronics corridors generate localized demand for mid-range pressure instrumentation. CE marking requirements under the EU Green Deal tighten emissions monitoring specifications for manufacturing equipment. Warsaw and Krakow logistics hubs enable shorter lead times for pneumatic system monitoring deployments across Central European manufacturing networks.
Netherlands
Third-party metrology laboratories capture recurring calibration revenue streams from German chemical operators unbundling service contracts. The EMA enforces MDR compliance timelines for sensors deployed in ventilation and dialysis equipment. Eindhoven and Rotterdam technology corridors concentrate HVAC and medical device manufacturers specifying capacitive designs for drift-critical low-pressure applications.
Europe Pressure Sensors Market Competitive Landscape
Top-tier vendors anchor high-reliability process automation, while mid-tier specialists occupy automotive MEMS fabrication and commodity industrial instrumentation. The vendor base stratifies around certification-grade differentiation, with F-Gas Regulation compliance and MDR conformity acting as sorting mechanisms. Three archetypes dominate: precision-engineered instrumentation specialists, high-volume MEMS fabricators, and vertically integrated smart sensor platforms. Competitive moves concentrate on backward integration into sensor-specific silicon production and strategic partnerships for AI-enabled edge preprocessing capabilities.
Among Swiss and German precision instrumentation groups, ABB Ltd and Endress+Hauser AG exemplify the high-reliability tier with captive supply chain control over critical fabrication stages. Bosch Sensortec GmbH anchors the automotive MEMS segment, representing the volume-driven archetype calibrated for electric vehicle thermal management integration. These three entities occupy positions that illustrate the market's bifurcation between safety-critical precision engineering and cost-optimized batch fabrication economics.
| Leading Market Players |
|---|
| ABB Ltd |
| Bosch Sensortec GmbH |
| Endress+Hauser AG |
| Schneider Electric SE |
| Kistler Group |
| Siemens AG |
| Honeywell International Inc. |
| Infineon Technologies AG |
| TE Connectivity Ltd |
| Others |
Supply & Pricing Matrix
High-purity silicon wafer spot prices cascade through European pressure sensor fabrication, compressing margins on commodity MEMS units while reinforcing pricing power for precision-grade instrumentation with captive silicon supply. German and French foundry allocation cycles force tier-one automotive suppliers toward long-term offtake contracts, bifurcating procurement economics between volume buyers locked into silicon futures and specialty fabricators absorbing spot volatility.
Pricing Analysis
The bundled-versus-unbundled service split separates German chemical operators seeking ISO 17025-traceable calibration contracts from Polish industrial buyers prioritizing hardware-only procurement. Pricing stratifies across certification-grade tiers: MDR-compliant medical sensors command premium positioning against CE-marked industrial units, while F-Gas Regulation leak-detection mandates force HVAC replacement cycles regardless of price sensitivity. Cost compression in automotive MEMS intensifies as wafer-level batch fabrication scales, though raw material volatility exposes non-integrated suppliers. Polish and Czech pneumatic system buyers exhibit highest price elasticity, whereas French process automation OEMs front-loading EU AI Act compliance show lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from German automotive tier-ones mandate qualified silicon wafer supply from both domestic foundries and Asian backup channels, complicating inventory positioning across 800-volt battery program ramps. High-purity silicon wafers, ceramic bonding substrates, and fiber-optic cable assemblies draw from Germany, France, and Taiwan production nodes. Single-source vulnerability concentrates in specialized MEMS diaphragm etching equipment, where ASML-adjacent tooling constrains expansion timelines. Distribution runs through Stuttgart and Lyon engineering centers for design-in support, with Warsaw and Krakow logistics hubs serving Central European manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe pressure sensors market functions as a stable compounder, with regulatory compliance mandates generating replacement-driven revenue visibility regardless of industrial cycle positioning.
For Market Incumbents: Hedge silicon input exposure through backward integration into captive wafer supply or long-term foundry offtake agreements with German and French batch fabrication specialists. Optical sensing substitution in North Sea oil and gas installations threatens piezoresistive legacy positions; defend through hazardous-environment certification investments and fiber-optic partnership structures. Channel control via third-party metrology laboratory acquisitions captures recurring calibration revenue from unbundling German chemical operators. For New Entrants and Emerging Players: Direct-to-engineer digital platforms enable design-in bypass of established distributor networks for mid-range Polish and Czech industrial automation demand. White-space concentrates in smart sensor edge-preprocessing modules for Industry 4.0 retrofits, where legacy analog-output infrastructure forces hybrid-protocol solutions underserved by digital-native incumbents. Target HVAC F-Gas Regulation compliance retrofit cycles with differential pressure instrumentation certified for parts-per-million leak detection sensitivity. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated precision instrumentation specialists combining captive silicon fabrication with notified body certification infrastructure. Five-to-ten-year viability hinges on EU AI Act pre-certification positioning for embedded diagnostic platforms. Watch German KBA type-approval timeline compression for 800-volt battery thermal management sensors as inflection indicator for automotive MEMS demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Fabrication | Captive wafer supply insulates German automotive tier-ones from foundry allocation volatility during semiconductor cycle peaks. |
| EU AI Act Pre-Certification Investment | French process automation OEMs front-load validation to secure notified body approval ahead of enforcement deadlines. |
| Third-Party Metrology Laboratory Acquisition | Dutch and Belgian calibration specialists capture recurring revenue from German chemical operators unbundling service contracts. |
| Smart Sensor Edge-Preprocessing Development | Embedded AI accelerators reduce bandwidth burdens on Industry 4.0 control architectures for German chemical operators. |
| F-Gas Regulation Compliance Product Line | Parts-per-million differential pressure sensitivity addresses forced replacement cycles across European HVAC installed base. |
Research Methodology
Bottom-up automotive and industrial automation modeling reconciled against top-down silicon wafer supply tracking forms the analytical core. Primary interviews with MEMS fabrication engineers, Tier 1 supplier procurement leads, process automation OEM technical directors, and notified body certification specialists combined with secondary validation against ECHA REACH substance restriction filings, KBA type-approval databases, EU Green Deal implementation progress reports, and SEC 10-K disclosures from listed sensor vendors. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped sensor content per vehicle across electric vehicle thermal management architectures, cross-referenced against IHS Markit vehicle production databases and foundry capacity utilization reports. Segmentation dimensions spanned product type, technology node, end-use industry, application, and country-level regulatory cluster. CAGRs derived from regression analysis of historical shipment data against enforcement timelines for F-Gas Regulation and MDR compliance deadlines, with sensitivity testing for silicon price volatility and optical substitution rates.
Semiconductor cycle downturns, REACH substance restriction scope expansions, and EU AI Act enforcement delays are the dominant revision risks. Deviation in KBA type-approval timeline compression for 800-volt battery architectures would shift the automotive MEMS outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Timing Device Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Sensor Bearing Market