
 Capacitive Position Sensors Market | 2026-2036
Capacitive Position Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Position Sensors Market Insights
Germany's precision component manufacturing belt is rewriting supply chain logic for capacitive sensing across Europe. Infineon Technologies AG leverages its Munich-based fab network to sustain captive wafer supply for automotive-grade position chips. SICK AG anchors industrial automation demand through its specialized encoder and sensing portfolio for smart factories. Micro-Epsilon competes on sub-micron measurement resolution, occupying the premium non-contact segment with laser-calibrated capacitive systems.
Capacitive position sensors detect displacement through changes in electrical capacitance between conductive plates, typically achieving resolutions below one micrometer with sampling rates exceeding ten kilohertz for real-time closed-loop control. Their primary purpose spans precision motion tracking in robotics, semiconductor wafer alignment, and automotive throttle-by-wire systems where mechanical wear must be eliminated. Non-contact product types lead volume shipments due to elimination of mechanical degradation in high-cycle environments, while absolute encoding variants capture expanding margin pools as safety-critical automotive and aerospace applications demand position verification at power-on without homing sequences. Touch sensing technology dominates consumer electronics integration, though proximity sensing architectures are gaining fastest in collaborative robotics where human-robot spatial awareness requires multi-zone detection.
The EU Machinery Directive and IEC 61000 electromagnetic compatibility standards shape product certification requirements for factory-floor deployment, while FDA 21 CFR Part 820 quality system regulations govern healthcare imaging and surgical robot applications in the United States. China's GB standards for industrial automation equipment and MIIT sensor industry development guidelines further fragment compliance pathways for multinational suppliers. Stakeholders must monitor evolving functional safety classifications under ISO 13849 as collaborative robotics and autonomous mobile platforms expand the addressable base for certified position feedback systems.
Market Dynamics
The EU Machinery Directive's functional safety mandates are forcing sensor suppliers to redesign capacitive architectures for ISO 13849 PLd certification, compressing development timelines while expanding addressable markets in collaborative robotics.
Growth Catalysts
- China MIIT Sensor Industry Guidelines:Domestic robot density targets in the Yangtze River Delta manufacturing corridor are accelerating local sourcing mandates for high-resolution position sensing modules.
- Automotive throttle-by-wire electrification:Elimination of mechanical linkages in electric vehicle powertrains is creating specification pull for absolute encoding capacitive sensors with power-on position verification.
- IEC 61000 electromagnetic compatibility harmonization:Factory-floor sensor integration standards are converging across European industrial automation buyers, reducing certification fragmentation for qualified suppliers.
Market Restraints
- Specialized electrode material concentration:High-purity aluminum oxide substrates for precision capacitive plates face supply bottlenecks from limited German and Japanese ceramic processors.
- Optical encoder substitution threat:Magnetic and optical position sensing technologies are capturing mid-resolution applications above five micrometers where capacitive cost premiums cannot be justified.
- REACH substance restriction complexity:Candidate list updates for electronics manufacturing chemicals are forcing reformulation of dielectric coatings without proven field reliability data.
Strategic Opportunities
- Surgical robotics FDA 21 CFR Part 820 pathway:Healthcare imaging and robotic surgery equipment represents underpenetrated demand for sterilizable non-contact position feedback with traceable quality systems.
- Capacitive-inductive fusion architectures:Hybrid sensing modules combining capacitive precision with inductive robustness are opening specification windows in autonomous mobile platforms.
- India PLI scheme for industrial automation:Production-linked incentives for electronic component manufacturing are creating localized assembly opportunities for export-oriented sensor suppliers.
Industry Challenges
- Multi-physics simulation talent scarcity:Electromagnetic field modeling for capacitive sensor optimization requires specialized expertise concentrated in Munich and Tokyo engineering clusters.
- ISO 13849 certification timeline compression:Functional safety validation for collaborative robotics applications demands extended fault injection testing that extends product launch cycles.
- Legacy analog infrastructure integration:Brownfield factory automation deployments require signal conditioning bridges that add cost and failure modes to pure digital capacitive outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Position Sensors Market |
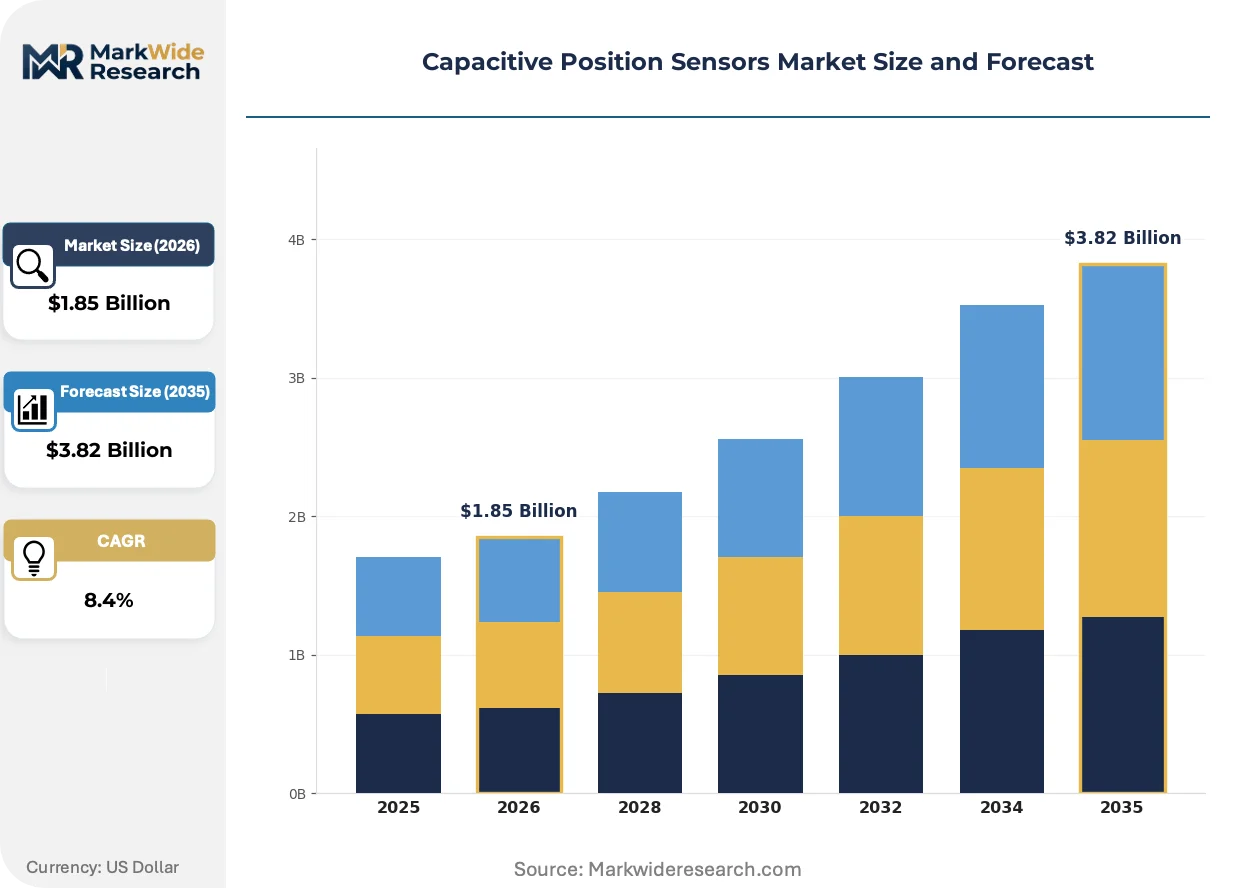
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Contact, Contact, Absolute, Incremental Application: Industrial Automation, Consumer Electronics, Robotics, Automotive Technology: Capacitance Sensing, Touch Sensing, Proximity Sensing, Gesture Recognition End User: Aerospace, Healthcare, Manufacturing, Telecommunications |
| Companies Covered | Honeywell International Inc., SICK AG, Infineon Technologies AG, TE Connectivity, Texas Instruments Inc., NXP Semiconductors NV, Sensata Technologies, Micro-Epsilon, KEYENCE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Position Sensors Market Trends and Innovations
Capacitive position sensing architectures are undergoing fundamental reconstruction as solid-state electrode patterning, regulatory safety mandates, and procurement centralization reshape competitive requirements across industrial and automotive verticals.
Printed electronics manufacturing is collapsing the traditional ceramic-substrate cost structure for capacitive sensing elements. Automotive tier-one suppliers in Germany are qualifying screen-printed silver-palladium electrode arrays for throttle position modules at sub-dollar unit economics. This electrode fabrication shift is collapsing the price floor for high-volume absolute encoding applications previously reserved for optical technologies.
The EU AI Act's risk classification framework is tightening documentation requirements for sensor feedback loops in autonomous systems. Industrial robot OEMs must now maintain algorithmic audit trails for position data integrity in safety-critical motion paths. German smart factory deployments are responding by specifying capacitive sensors with embedded cryptographic authentication to satisfy conformity assessment body scrutiny.
Consolidated procurement through automotive platform engineering centers is compressing supplier qualification cycles. Tier-one buyers in Stuttgart and Toyota City are mandating single-source sensor architectures across model lines to reduce validation overhead. Japanese industrial automation distributors are responding with technical specification bundling that locks in capacitive sensor families for five-year platform commitments.
Capacitive Position Sensors Market Segmentation
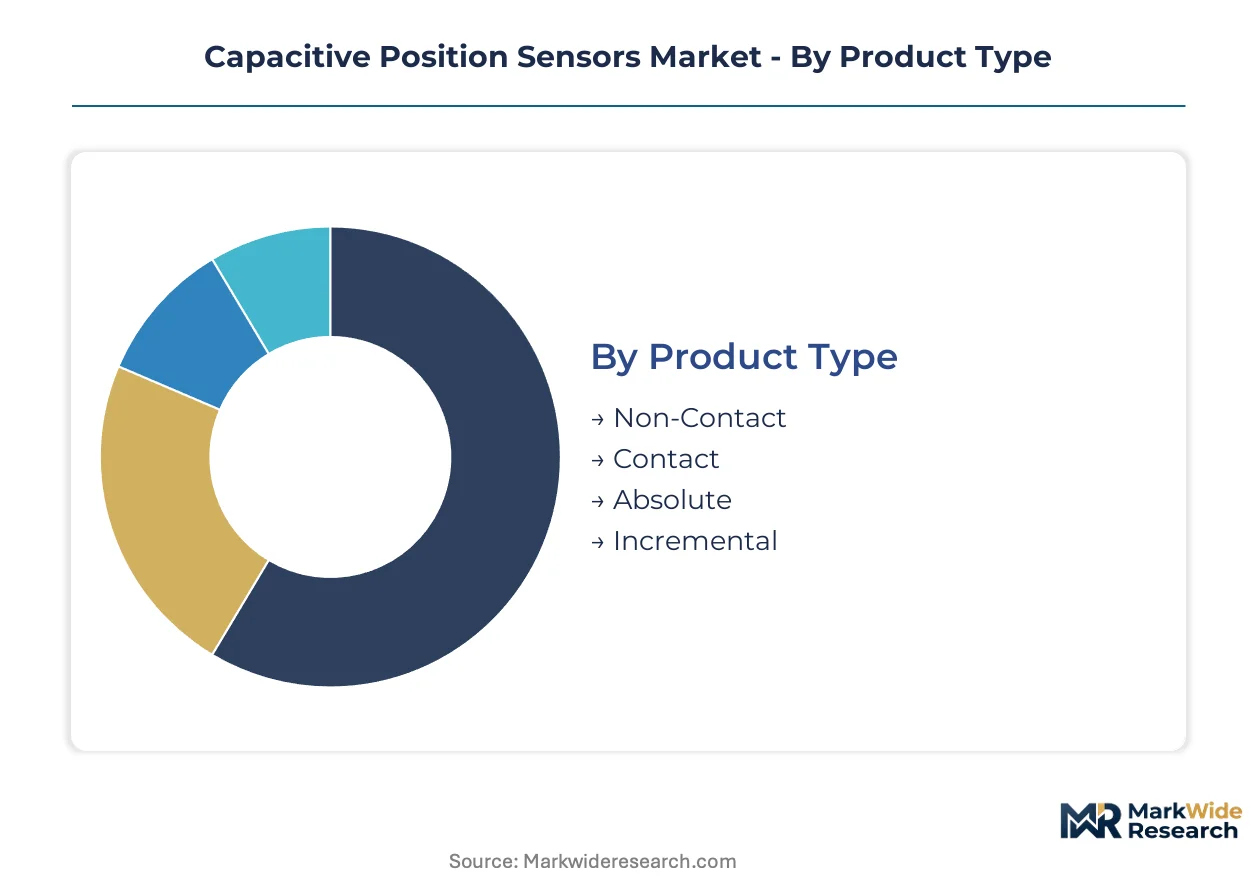
Capacitive position sensor architectures fragment across four critical dimensions: mechanical interface design, deployment environment, signal processing methodology, and buyer industry vertical. Each segmentation axis carries distinct margin profiles, certification requirements, and supplier qualification barriers that reshape competitive positioning.
Product Type:
Mechanical interface design separates segments by wear characteristics, resolution ceilings, and homing requirements.
- Non-Contact:Electrode arrays detect displacement through air-gap capacitance modulation without physical engagement. Semiconductor wafer alignment systems in Taiwan and South Korea specify these for sub-micron repeatability over millions of cycles.
- Absolute:Encoded electrode patterns provide instantaneous position verification at power-on without homing sequences. Automotive throttle-by-wire architectures in Stuttgart engineering centers mandate absolute encoding for functional safety compliance.
- Contact:Sliding or rolling conductive elements maintain physical engagement with measured surfaces. Legacy machine tool retrofits in Japan's Aichi Prefecture manufacturing belt retain contact designs for cost-sensitive position feedback.
- Incremental:Pulse-counting architectures track relative displacement from a reference point. Conveyor positioning systems in Germany's Ruhr industrial corridor deploy incremental variants where absolute verification remains unnecessary.
Non-Contact commands the established base. The steepest expansion runs through Absolute.
Application:
Deployment environment determines electromagnetic shielding requirements, sampling rate specifications, and integration complexity.
- Industrial Automation:Factory-floor motion control demands IEC 61000 electromagnetic immunity and ISO 13849 functional safety certification. Collaborative robot deployments in Bavaria require multi-zone capacitive arrays for human-robot spatial awareness.
- Automotive:Powertrain electrification eliminates mechanical linkages, creating specification pull for temperature-stable position feedback. Throttle pedals and steering columns in Toyota City platform engineering centers specify automotive-grade capacitive modules.
- Robotics:Precision joint encoding and end-effector positioning drive resolution requirements below five micrometers. Surgical robot OEMs in Massachusetts corridor target FDA 21 CFR Part 820 quality systems for sterilizable feedback.
- Consumer Electronics:Touch interfaces and haptic controllers prioritize cost compression over absolute precision. Smartphone assembly lines in China's Guangdong Province integrate capacitive position sensing for camera module alignment.
Industrial Automation commands the established base. Automotive exhibits the steepest expansion trajectory.
Technology:
Signal processing methodology differentiates architectures by detection range, multi-point capability, and algorithmic complexity.
- Capacitance Sensing:Direct measurement of electrode pair capacitance variation achieves highest precision for linear and angular displacement. Metrology equipment manufacturers in Switzerland specify these for nanometer-scale calibration systems.
- Proximity Sensing:Field disturbance detection enables multi-zone spatial awareness without physical contact. Autonomous mobile robot platforms in Singapore deploy proximity arrays for obstacle avoidance and navigation.
- Touch Sensing:Human interface detection prioritizes response latency and multi-point recognition. Gaming peripheral manufacturers in California integrate touch sensing for controller joystick position tracking.
- Gesture Recognition:Pattern classification algorithms interpret capacitive field variations as command inputs. Automotive infotainment systems in Munich specify gesture recognition for driver distraction reduction.
Capacitance Sensing commands the established base. Proximity Sensing climbs the fastest.
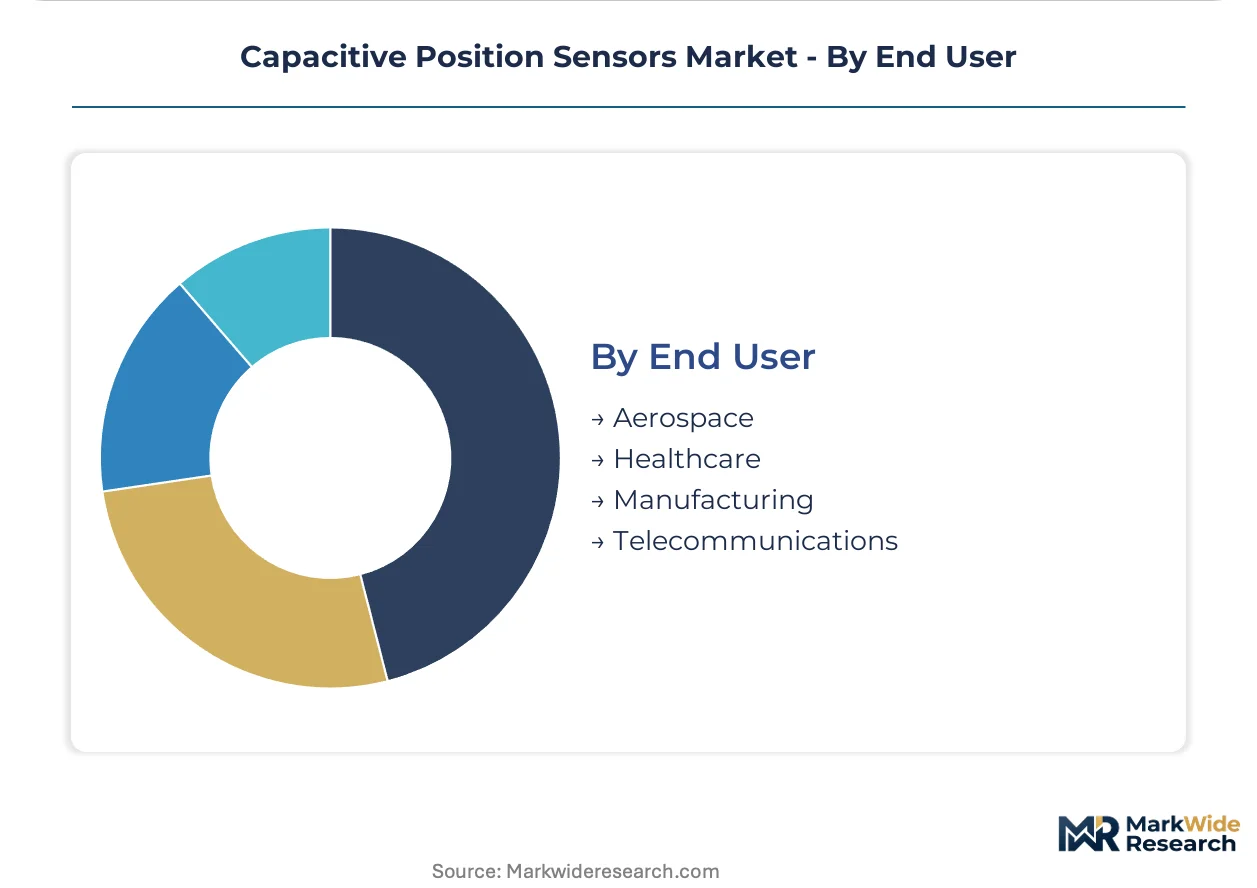
End User:
Buyer verticals impose distinct certification regimes, reliability specifications, and procurement consolidation patterns.
- Manufacturing:Factory automation buyers concentrate demand through platform engineering centers in Germany and Japan. Smart factory deployments in the Yangtze River Delta accelerate local sourcing mandates for high-resolution modules.
- Aerospace:Flight control surface positioning and landing gear extension monitoring demand DO-178C software assurance and extended temperature operation. Tier-one suppliers in Toulouse specify capacitive encoders for fly-by-wire architectures.
- Healthcare:Imaging equipment and surgical robotics require sterilizable non-contact feedback with traceable quality systems. FDA 21 CFR Part 820 compliance governs market access for US healthcare applications.
- Telecommunications:Antenna positioning and satellite communication systems prioritize reliability in harsh environmental conditions. Ground station equipment manufacturers in Colorado specify capacitive sensors for precision azimuth tracking.
Manufacturing commands the established base. Healthcare gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication capacity for precision capacitive sensing elements concentrates in Germany, Japan, and Taiwan, creating supply dependencies that reshape procurement patterns across automotive and industrial automation verticals. Multinational buyers must navigate divergent certification regimes while securing qualified supply from these concentrated manufacturing clusters.
United States
Surgical robotics OEMs in the Massachusetts corridor drive demand for FDA 21 CFR Part 820 compliant sterilizable position feedback systems. The FDA maintains stringent quality system regulations for healthcare imaging equipment. Boston-area medical device clusters specify capacitive encoders with traceable calibration chains for robotic surgery platforms.
Germany
Automotive tier-one suppliers in Stuttgart engineering centers mandate absolute encoding capacitive modules for throttle-by-wire electrification programs. The KBA enforces functional safety validation under EU Machinery Directive transpositions. Bavarian smart factory deployments integrate multi-zone capacitive arrays from Munich-based sensor specialists for collaborative robotics.
China
Domestic robot density targets in the Yangtze River Delta manufacturing corridor accelerate local sourcing mandates for high-resolution position sensing modules. MIIT sensor industry development guidelines prioritize indigenous supply chain development. Shanghai and Suzhou industrial automation clusters are qualifying domestic capacitive sensor suppliers for precision motion control.
Japan
Precision component manufacturers in Toyota City platform engineering centers specify automotive-grade capacitive position chips for steering column and pedal applications. METI industrial technology roadmaps emphasize sensor fusion architectures for autonomous systems. Nagoya-area industrial automation distributors bundle capacitive sensor families into five-year platform commitments.
South Korea
Semiconductor wafer alignment system manufacturers in Suwon and Pyeongtaek specify non-contact capacitive sensors for sub-micron repeatability requirements. MFDS medical device regulations govern diagnostic imaging equipment position feedback. Seoul Capital Area robotics OEMs deploy proximity sensing arrays for human-robot spatial awareness in collaborative applications.
Capacitive Position Sensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with differentiated electrode patterning and signal conditioning expertise. The vendor base stratifies across three tiers: diversified electronics conglomerates with captive sensor divisions, pure-play sensing specialists with metrology-grade calibration capabilities, and regional fabricators serving cost-optimized industrial retrofit markets. Two strategic archetypes dominate competitive positioning: precision measurement specialists competing on sub-micron resolution specifications, and automotive-grade suppliers competing on functional safety certification breadth. Capacity expansion in printed electrode manufacturing and strategic partnerships for multi-physics simulation access represent the dominant competitive moves.
Among diversified technology conglomerates, Honeywell International Inc. and Texas Instruments Inc. occupy positions spanning industrial automation and aerospace sensing tiers. Infineon Technologies AG anchors the automotive-grade semiconductor segment with Munich-based fabrication assets. SICK AG exemplifies the precision industrial automation specialist archetype through its encoder and sensing portfolio concentration. These named entities represent distinct strategic postures without implying specific market share positions or competitive rankings.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| SICK AG |
| Infineon Technologies AG |
| TE Connectivity |
| Texas Instruments Inc. |
| NXP Semiconductors NV |
| Sensata Technologies |
| Micro-Epsilon |
| KEYENCE |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Taiwan's semiconductor wafer fabrication network is compressing electrode substrate pricing while concentrating supplier power among German and Japanese ceramic processors, creating asymmetric margin pressure across the capacitive sensor value chain.
Pricing Analysis
The EU Machinery Directive dictates the pricing tier structure across factory-floor sensor deployments. Certification-grade pricing stratifies across ISO 13849 PLd-verified premium tiers, standard industrial grades with basic EMC compliance, and economy retrofit modules for legacy analog integration. Price differentiation hinges on functional safety validation depth and automotive-grade temperature specifications. Cost compression in consumer electronics proximity sensing is intensifying because printed electrode manufacturing is collapsing unit economics below optical encoder parity. Automotive tier-one buyers in Stuttgart exhibit lowest price sensitivity due to platform consolidation mandates, while industrial retrofit distributors in China's Pearl River Delta manufacturing belt demand aggressive volume discounts.
Supply Chain Analysis
Export-control restrictions on high-purity aluminum oxide substrate technology limit flows from German and Japanese specialty ceramic processors to Chinese sensor fabricators. Wafer fabrication capacity concentrates in Taiwan, Germany, and Japan, with electrode patterning equipment anchored in Dutch and Swiss lithography clusters. Raw material dependencies include high-k dielectric coatings, precision-machined ceramic substrates, and automotive-grade encapsulation resins. Single-source vulnerability runs through the limited qualified suppliers of sub-micron electrode alignment systems. Distribution runs through automotive platform engineering centers in Stuttgart and Toyota City, industrial automation distributors in Bavaria and Nagoya, and direct OEM supply agreements for surgical robotics OEMs in Massachusetts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capacitive position sensor market presents a defensive moat rooted in regulatory entrenchment—ISO 13849 certification timelines and FDA 21 CFR Part 820 quality system validation create switching costs that protect incumbent positions across automotive and healthcare verticals.
For Market Incumbents: Pre-empt optical encoder substitution in mid-resolution applications by accelerating printed electrode cost reduction programs in Germany. Expand captive wafer supply through backward integration into ceramic substrate processing to offset aluminum oxide supply bottlenecks. Deepen ISO 13849 PLd certification coverage to lock out emerging entrants from collaborative robotics specification windows.
For New Entrants and Emerging Players: Pursue surgical robotics sterilizable feedback modules in the Massachusetts corridor, where FDA 21 CFR Part 820 compliance requirements have kept penetration low among established industrial sensor suppliers. Target India's PLI scheme for industrial automation component manufacturing to establish export-oriented assembly capacity with favorable tariff positioning. Lead with capacitive-inductive fusion architectures as the go-to-market differentiator for autonomous mobile robot platforms requiring multi-physics robustness.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across printed electrode manufacturing as screen-printed silver-palladium arrays displace traditional ceramic-substrate fabrication. Long-term viability favors suppliers with metrology-grade calibration capabilities and embedded cryptographic authentication IP for EU AI Act compliance. Acquisition target archetype: precision sensing specialists with ISO 13849 certification infrastructure and automotive platform engineering relationships. The signal to watch is tier-one automotive procurement consolidation velocity in Stuttgart and Toyota City.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13849 PLd Certification Investment | Unlocks collaborative robotics specification windows in Bavarian smart factory deployments. |
| Printed Electrode Manufacturing Scale-Up | Collapses unit economics for automotive throttle-by-wire absolute encoding modules. |
| Capacitive-Inductive Fusion Architecture Development | Opens specification windows in autonomous mobile platforms requiring multi-physics robustness. |
| FDA 21 CFR Part 820 Quality System Implementation | Enables market access for sterilizable surgical robotics feedback in Massachusetts corridor. |
| India PLI Scheme Localization | Creates export-oriented assembly capacity for industrial automation component manufacturing. |
Research Methodology
A standing panel of automotive platform engineers, industrial automation procurement directors, surgical robotics OEM technical leads, and semiconductor wafer alignment system specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from SEC filings, EU Machinery Directive transposition documents, FDA 510(k) clearance databases, and MIIT sensor industry development guidelines. Bottom-up demand modeling across product type, application, technology, and end-user segments triangulated with top-down macroeconomic overlays.
Scenario-bracketing anchored the analytical framework across the projection horizon, with CAGRs derived from segment-level demand elasticity modeling and supply-side capacity constraints. Segmentation dimensions included mechanical interface design, deployment environment, signal processing methodology, and buyer industry vertical, with additional granularity on certification tier and geographic sourcing mandate intensity. Forecast inputs incorporated automotive electrification program timelines, industrial robot density targets in the Yangtze River Delta, and REACH substance restriction reformulation schedules.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or automotive production schedules would shift the trajectory. Forecasts reflect underlying assumptions about regulatory compliance timelines and electrode material supply continuity. Material shifts in EU AI Act risk classification enforcement or aluminum oxide export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market