
 Global Capacitive Sensor Market | 2026-2036
Global Capacitive Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capacitive Sensor Market Foresight
Asian semiconductor foundries are realigning capacity toward MEMS and touch controller wafers as capacitive sensing demand broadens beyond mobile devices. Infineon Technologies AG leverages its power semiconductor heritage to anchor high-voltage capacitive sensing for industrial motor drives. STMicroelectronics sustains technology leadership through integrated MCU-sensor platforms that reduce bill-of-materials complexity for appliance designers.
Capacitive sensors detect proximity, position, or touch by measuring changes in electrical capacitance between conductive plates, typically operating at excitation frequencies from tens of kilohertz to several megahertz depending on target material and required response time. Their primary purpose is delivering non-contact, wear-free measurement and human-machine interface functionality across environments where mechanical switches degrade or contaminate. Proximity sensors command durable industrial margins due to their penetration in hazardous-area automation, while multi-touch sensors face price compression from display-integrated controller consolidation. Projected capacitive technology leads consumer-facing applications but competes with emerging optical alternatives in premium automotive interiors.
The EPA governs electromagnetic emissions from capacitive devices sold into US industrial and consumer markets, while the EU F-Gas Regulation indirectly shapes sensor demand by accelerating HVAC equipment replacement cycles that incorporate humidity and pressure capacitive elements. China's GB standards for electromagnetic compatibility and MIIT certification requirements for networked appliances create non-tariff barriers that favor domestic sensor vendors with established testing relationships. Stakeholders must monitor how the EU AI Act and emerging US semiconductor export controls reshape supply chain routing for advanced capacitive controller chips.
Market Dynamics
Display-integrated controller consolidation is compressing margins for standalone capacitive sensor vendors while automotive electrification programs in China and Germany pull high-reliability proximity sensing into battery management and cabin interface systems.
Growth Catalysts
- EU F-Gas Regulation:Accelerated HVAC equipment replacement cycles are expanding procurement of humidity and pressure capacitive elements for climate control systems across industrial and commercial buildings.
- Automotive electrification:Battery electric vehicle platforms in China are integrating capacitive sensing for touchless trunk release, steering wheel detection, and seat occupancy monitoring.
- MEMS foundry realignment:Asian semiconductor foundries are dedicating wafer capacity to touch controller production, lowering unit costs for appliance and wearable manufacturers.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor materials for projected capacitive displays depend heavily on Chinese rare earth processing, exposing sensor makers to export restriction risk.
- Optical fingerprint substitution:Under-display ultrasonic and optical biometric modules are displacing capacitive touch sensors in premium smartphone segments.
- REACH compliance cost escalation:European chemical registration requirements are forcing reformulation of dielectric coatings and electrode materials, extending qualification timelines.
Strategic Opportunities
- Industrial motor drives:High-voltage capacitive position sensing for variable frequency drives remains underpenetrated outside German and Japanese automation markets.
- EU AI Act certification:Touch interface compliance for human-machine interaction in safety-critical systems creates premium certification tiers for automotive and medical device vendors.
- Edge AI convergence:Integration of capacitive sensing with on-device machine learning is enabling predictive maintenance in rotating equipment and smart home appliances.
Industry Challenges
- Electromagnetic compatibility certification:Multi-jurisdiction testing for FCC, CE marking, and China's GB standards extends product launch cycles by 8-14 months for networked appliance controllers.
- Legacy system integration:Industrial automation retrofits require analog-to-digital signal conditioning that complicates deployment of modern capacitive proximity modules in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capacitive Sensor Market |
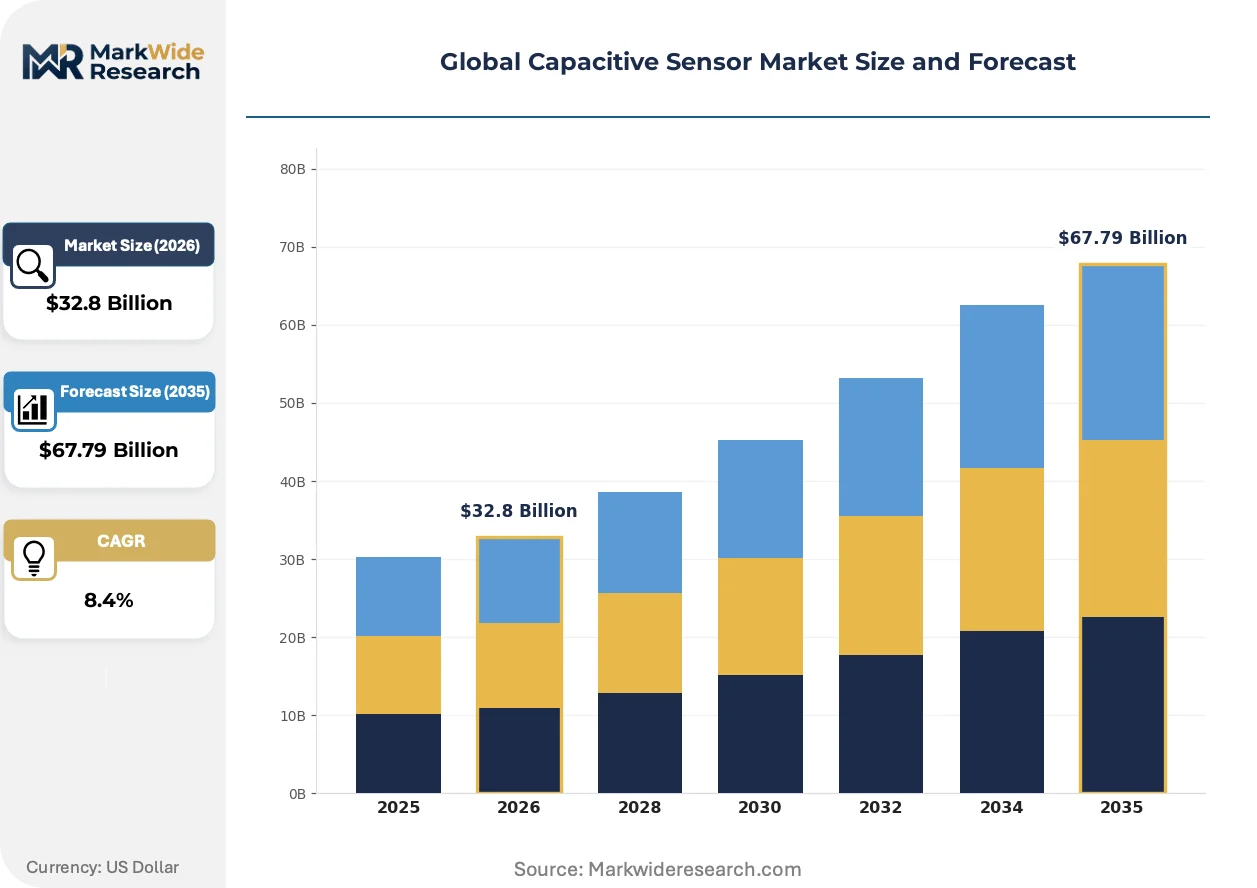
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Sensors, Relative Sensors, Multi-Touch Sensors, Proximity Sensors, Humidity Sensors Technology: Mutual Capacitance, Self Capacitance, Projected Capacitive, Surface Capacitance, Capacitive Tuning Application: Consumer Electronics, Industrial Automation, Aerospace Systems, Agriculture Equipment, Smart Appliances End User: Electronics Manufacturers, Automation Providers, Aerospace Firms, Farming Equipment Suppliers, Home Appliance Makers |
| Companies Covered | Honeywell International Inc., Infineon Technologies AG, STMicroelectronics, Texas Instruments Incorporated, Analog Devices, Inc., TE Connectivity, SICK AG, ams OSRAM AG, Microchip Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capacitive Sensor Market Shifts & Advancements
Capacitive sensing architectures are fragmenting between ultra-low-power wearable implementations and high-voltage industrial designs, with material science and signal processing advances determining competitive positioning across each tier.
Self-capacitance-to-mutual-capacitance hybrid architectures are converging with active noise cancellation algorithms to enable glove-compatible touch detection in automotive and medical environments. Tier 1 suppliers in Germany and Japan are adopting these stacks for next-generation human-machine interfaces. The technology is converging with thin-film piezoelectric deposition processes to create force-sensitive layers that eliminate mechanical button requirements.
China's MIIT certification requirements for networked appliances are mandating electromagnetic compatibility testing that exceeds baseline IEC standards, favoring domestic sensor vendors with established laboratory relationships. This regulatory friction is segmenting export markets from domestic Chinese supply chains. European appliance manufacturers are responding by dual-sourcing from MIIT-certified and CE-marked production lines.
Appliance OEMs are consolidating touch controller procurement through direct foundry relationships, bypassing traditional distributor channels for high-volume programs. This channel compression is squeezing margin for mid-tier sensor module assemblers in Taiwan and South Korea. The shift is most pronounced in white goods manufacturing clusters around Qingdao and Ningbo.
Global Capacitive Sensor Market Segmentation
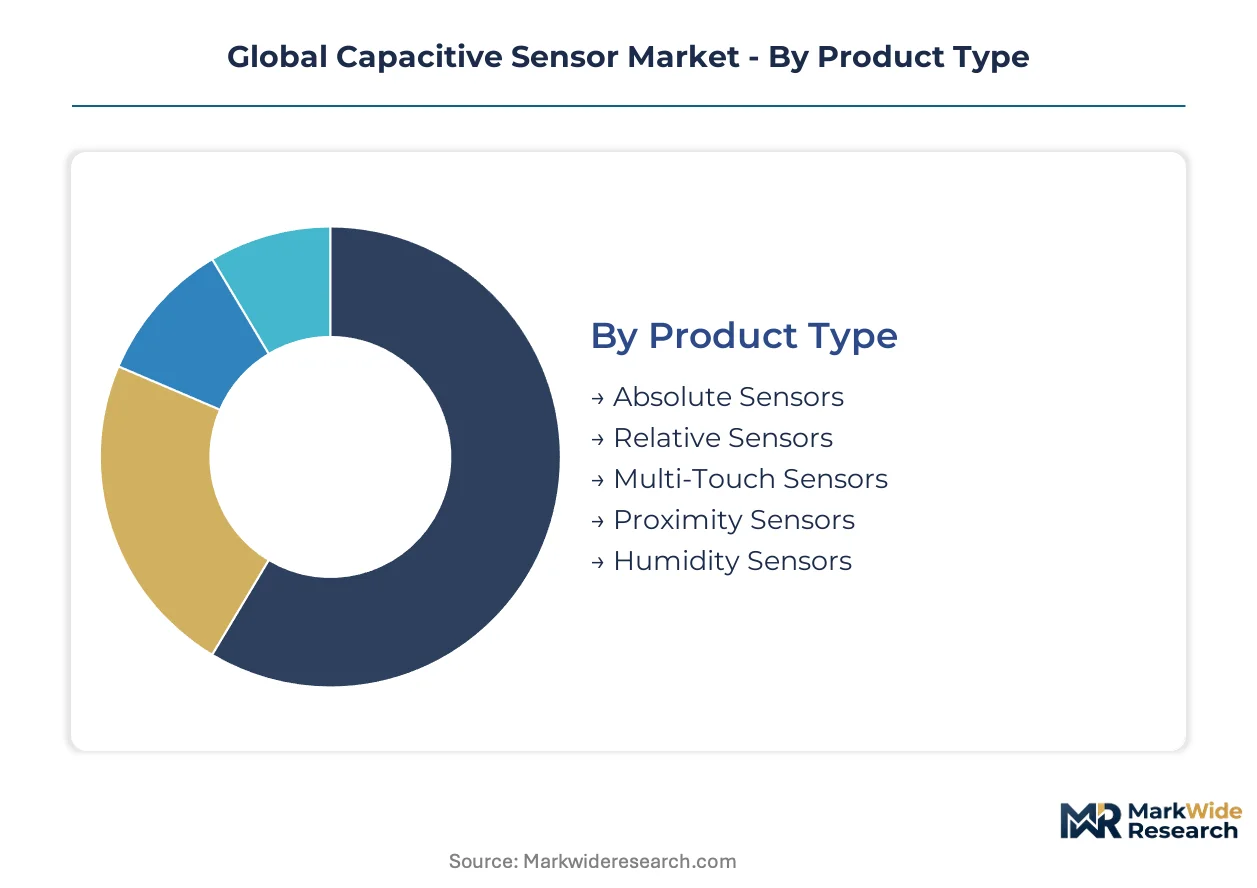
Capacitive sensor architectures fragment sharply between embedded controller-integrated designs and standalone modules, with integration depth determining margin structures, certification burdens, and customer procurement patterns across industrial and consumer tiers.
Product Type:
Integration depth varies dramatically across this category, with some segments shipping as discrete components requiring external signal conditioning while others embed directly into system-on-chip architectures.
- Multi-Touch Sensors:Projected capacitive arrays detect simultaneous contact points through mutual capacitance measurement between orthogonal electrode layers. Smartphone and tablet manufacturers in China and South Korea dominate procurement, though display-integrated controller consolidation is compressing margins for standalone suppliers.
- Proximity Sensors:Single-electrode designs measure capacitance changes induced by approaching conductive or dielectric targets without physical contact. Automotive electrification programs in Germany and China are pulling these into battery management systems and touchless trunk release mechanisms.
- Absolute Sensors:Provide position or level measurements referenced to a fixed calibration point.
- Relative Sensors:Detect displacement or change from a baseline condition rather than absolute position.
- Humidity Sensors:Polymer or ceramic dielectric layers absorb atmospheric moisture to shift capacitance proportionally.
Multi-touch sensors lead volumes today; proximity sensors are gaining share fastest.
Technology:
Signal processing architectures separate cost-optimized consumer implementations from industrial-grade designs requiring noise immunity and extended temperature ranges.
- Projected Capacitive:Electric field projects through an insulating overlay to enable touch detection without direct electrode contact. Consumer electronics OEMs favor this technology for its durability and multi-point capability, though optical alternatives are displacing it in premium smartphone biometric applications.
- Mutual Capacitance:Transmit and receive electrode arrays measure capacitive coupling at intersection points to enable precise multi-touch tracking. Appliance manufacturers in Qingdao and Ningbo are driving procurement for smart white goods interfaces.
- Self Capacitance:Single-electrode designs measure capacitance relative to ground, simpler but limited to single-touch or proximity detection.
- Surface Capacitance:Uniform conductive coating with corner electrodes detects touch location through current distribution.
- Capacitive Tuning:Variable capacitance elements adjust resonant frequency in RF and oscillator circuits.
Projected capacitive dominates current shipments; mutual capacitance architectures are expanding most quickly into appliance and automotive applications.
Application:
End-use concentration determines pricing power, with safety-critical aerospace and industrial segments commanding premium qualification tiers against commoditized consumer volumes.
- Consumer Electronics:Smartphones, tablets, wearables, and peripheral devices integrate capacitive touch and proximity functions. Manufacturers face relentless cost pressure as display-integrated controllers absorb functionality previously served by discrete sensor modules.
- Industrial Automation:Hazardous-area machinery, robotic systems, and process control equipment deploy capacitive proximity sensors for non-contact position sensing. German and Japanese automation markets anchor demand for high-reliability implementations.
- Smart Appliances:Refrigerators, washing machines, and HVAC systems replace mechanical switches with capacitive control panels.
- Aerospace Systems:Aircraft cabin interfaces and avionics controls require EMI-hardened capacitive solutions.
- Agriculture Equipment:Tractor and harvester cabins integrate touch interfaces for climate and implement control.
Consumer electronics commands the largest revenue pool; industrial automation is climbing the fastest as brownfield retrofit programs accelerate.
End User:
Customer scale and technical sophistication shape procurement channels, from direct foundry relationships among high-volume electronics manufacturers to distributor-dependent agricultural equipment suppliers.
- Electronics Manufacturers:Smartphone, tablet, and wearable OEMs procure touch controllers at massive scale. These buyers are consolidating supplier relationships through direct foundry partnerships, bypassing traditional distribution and squeezing mid-tier module assemblers.
- Automation Providers:System integrators and machinery builders specify capacitive proximity sensors for factory automation and process control. REACH and RoHS compliance requirements in the European Union force material qualification processes that extend procurement cycles.
- Home Appliance Makers:White goods manufacturers integrate capacitive control panels into premium product lines.
- Aerospace Firms:Airframe and avionics suppliers demand extended temperature range and EMI immunity certifications.
- Farming Equipment Suppliers:Agricultural machinery builders adopt capacitive interfaces for operator cabin controls.
Electronics manufacturers dominate procurement volumes; automation providers are expanding their share fastest through electrification and safety system upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as sensor vendors migrate manufacturing toward jurisdictions with streamlined electromagnetic compatibility certification pathways and lower REACH compliance overhead.
China
Domestic electrification programs and networked appliance mandates are accelerating procurement of touch controllers and proximity modules. MIIT certification requirements for GB-standard electromagnetic compatibility testing exceed baseline IEC thresholds, favoring vendors with established laboratory relationships in Shenzhen and Shanghai. Qingdao and Ningbo white goods clusters are consolidating touch controller procurement through direct foundry partnerships.
Germany
Industrial automation retrofits and automotive electrification are pulling high-reliability proximity sensing into battery management and cabin interface systems. REACH and RoHS compliance requirements force extended material qualification timelines for dielectric coatings and electrode formulations. Bavarian and Baden-Württemberg automation markets anchor demand for EMI-hardened implementations in hazardous-area machinery.
United States
EPA electromagnetic emissions governance and FCC certification requirements shape industrial and consumer market entry for capacitive devices. The Inflation Reduction Act accelerates HVAC equipment replacement cycles, expanding procurement of humidity and pressure capacitive elements. Texas and Arizona semiconductor fabrication corridors are realigning capacity toward MEMS and touch controller wafer production.
South Korea
Display-integrated controller consolidation is compressing margins for standalone sensor vendors serving smartphone and tablet OEMs. MFDS certification frameworks for medical device touch interfaces create premium qualification tiers. Seoul and Gyeonggi-do electronics manufacturing clusters are driving mutual capacitance procurement for premium wearable implementations.
Japan
METI industrial policy and JIS standards for factory automation equipment sustain demand for high-voltage capacitive position sensing in variable frequency drives. Aging workforce demographics accelerate brownfield retrofit programs requiring non-contact proximity modules. Nagoya and Osaka machinery builder concentrations specify capacitive solutions for robotic system integration.
Global Capacitive Sensor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive electrification and industrial motor drive adjacencies with specialized high-voltage architectures. The vendor base stratifies across integrated semiconductor houses, discrete sensor module assemblers, and system-level automation suppliers. Three archetypes dominate: power semiconductor heritage players leveraging high-voltage expertise, MCU-integrated platform vendors reducing bill-of-materials complexity, and MEMS foundry-aligned specialists capturing wearable cost-down programs. Competitive moves concentrate on direct foundry relationship formation and geographic certification footprint expansion.
Within the integrated platform tier, STMicroelectronics and Infineon Technologies AG exemplify divergent strategic positioning—STMicroelectronics anchoring MCU-sensor convergence for appliance designers, Infineon leveraging power semiconductor heritage for industrial motor drive applications. Texas Instruments Incorporated occupies a position bridging standard and premium tiers through broad analog and embedded processing portfolios. These three represent the competitive spectrum from component-level supply to system-level integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| TE Connectivity |
| SICK AG |
| ams OSRAM AG |
| Microchip Technology, Inc. |
| Others |
Supply & Pricing Matrix
Display-integrated controller consolidation among smartphone OEMs in China and South Korea is forcing standalone capacitive sensor vendors toward direct foundry partnerships or exit, compressing channel margins and accelerating price erosion in multi-touch modules.
Pricing Analysis
Distributor margin compression now defines the Global Capacitive Sensor Market's commercial architecture, with appliance OEMs in Qingdao and Ningbo consolidating procurement through direct foundry relationships that bypass traditional channel markups. Three-tier pricing structure across premium, standard, and economy levels separates EMI-hardened automotive implementations from consumer-grade touch controllers and commodity proximity modules. Cost compression in multi-touch sensors intensifies because display-integrated controllers absorb functionality previously served by discrete modules. Electronics manufacturers exhibit the highest price sensitivity due to volume procurement leverage, while aerospace firms tolerate premium pricing for extended temperature range certifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing for indium tin oxide transparent conductors, exposing projected capacitive display supply to export restriction risk. Manufacturing concentrates in China, Taiwan, and South Korea, with MEMS foundry capacity realigning toward touch controller wafers. Production draws from indium tin oxide sputtering targets, silicon wafer substrates, and polymer dielectric coatings. Tariff exposure runs through US-China semiconductor trade restrictions affecting advanced controller chip routing. Distribution runs through direct OEM-foundry contracts for high-volume programs, with distributor networks serving mid-tier automation and agricultural equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Capacitive Sensor Market functions as a stable compounder, with automotive electrification programs across multiple geographies providing durable demand visibility that smooths cyclicality in consumer electronics procurement.
For Market Incumbents: Cement technology leadership through captive MEMS foundry capacity in Taiwan or South Korea, insulating against Asian semiconductor foundry realignment disruptions. Deepen certification moats by securing MIIT compliance for China's GB-standard electromagnetic compatibility testing ahead of export competitors. Prioritize high-voltage capacitive sensing R&D for industrial motor drives, where German and Japanese automation markets anchor durable margins against optical fingerprint substitution threats in consumer tiers. For New Entrants and Emerging Players: Begin with industrial motor drive applications in variable frequency drives, where underpenetration outside German and Japanese markets creates white-space opportunity. Target brownfield automation retrofit programs requiring analog-to-digital signal conditioning, as legacy system integration complexity deters established vendors. Pursue edge AI convergence positioning, integrating capacitive sensing with on-device machine learning for predictive maintenance in rotating equipment. For Investors and Strategic Acquirers: Asymmetric upside sits with MEMS foundry-aligned specialists capturing wearable cost-down programs through Asian semiconductor capacity partnerships. Five-to-ten year viability hinges on automotive electrification sustaining proximity sensor demand for battery management and cabin interface systems. Monitor EU AI Act certification requirements for touch interfaces in safety-critical systems as the inflection indicator for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Partnership Formation | Qingdao and Ningbo appliance clusters bypass distributors, securing volume pricing and supply priority. |
| MIIT Certification Investment | GB-standard electromagnetic compatibility testing exceeds IEC baselines, creating non-tariff barriers for export competitors. |
| High-Voltage Architecture Development | Industrial motor drive applications in German automation markets command durable margins against consumer price erosion. |
| Edge AI Integration | Predictive maintenance capabilities in rotating equipment differentiate offerings from commodity proximity modules. |
| Dual-Sourcing Production Lines | European appliance manufacturers hedge China's regulatory friction by maintaining MIIT-certified and CE-marked capacity. |
Research Methodology
Bottom-up electronics procurement modeling reconciled against top-down MEMS foundry capacity tracking forms the analytical core of this study. Primary interviews with touch controller procurement managers at smartphone OEMs, appliance platform engineers in Qingdao and Ningbo, and automation system integrators in Germany and Japan combined with secondary validation from SEC 10-K filings, customs trade data, and MIIT certification registries. Top-down triangulation against semiconductor equipment capex disclosures and GB-standard electromagnetic compatibility testing records anchored volume estimates.
Input-output matrices mapped capacitive sensor shipments across product type, technology architecture, application vertical, and end-user scale dimensions over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers including automotive electrification program timelines and HVAC replacement cycle acceleration. Industry-specific forecast inputs incorporated REACH compliance cost escalation trajectories and indium tin oxide supply concentration risk assessments.
Caveats apply where export restriction tightening on Chinese rare earth processing, EU AI Act certification timeline delays, or ultrasonic fingerprint module cost breakthroughs could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
US Smart Air Purifier Market