
 Thermal Anemometer Market | 2026-2036
Thermal Anemometer Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Anemometer Market Analytics
Buyer concentration across HVAC service chains is rebalancing toward national facility management conglomerates and energy retrofit contractors. TSI Incorporated leverages its research-grade calibration protocols to sustain dominance in laboratory and aerospace verification workflows. Kanomax Japan anchors its position through precision hot-wire manufacturing for semiconductor cleanroom applications. Testo SE and Co. KGaA competes aggressively in European building commissioning by bundling thermal anemometry with refrigerant leak detection platforms.
A thermal anemometer measures fluid velocity by detecting heat loss from a heated sensor element exposed to airflow, typically operating with platinum or tungsten wire elements maintained at constant temperature or constant current. The instrument converts convective cooling rates into velocity readings with resolution thresholds reaching fractions of a meter per second, serving critical functions in HVAC balancing, wind tunnel research, and meteorological station networks. Portable units command the largest volume pool due to field service mobility requirements, while wireless segments capture expanding share through IoT-enabled continuous monitoring architectures. Hot wire technology retains primacy in high-frequency turbulence research, though microelectromechanical systems designs are displacing legacy probes in cost-sensitive industrial automation deployments.
The U.S. Environmental Protection Agency enforces ambient air quality monitoring protocols that specify anemometric verification for stack emission measurement systems, while the EU F-Gas Regulation mandates leak-rate documentation procedures dependent on calibrated airflow instrumentation. Japan's Ministry of Economy, Trade and Industry promotes JIS-standard metrology traceability that shapes procurement specifications for domestic semiconductor and automotive test facilities. Stakeholders must monitor evolving building decarbonization mandates and sensor fusion requirements to align product roadmaps with regulatory verification regimes and integrated environmental platform architectures.
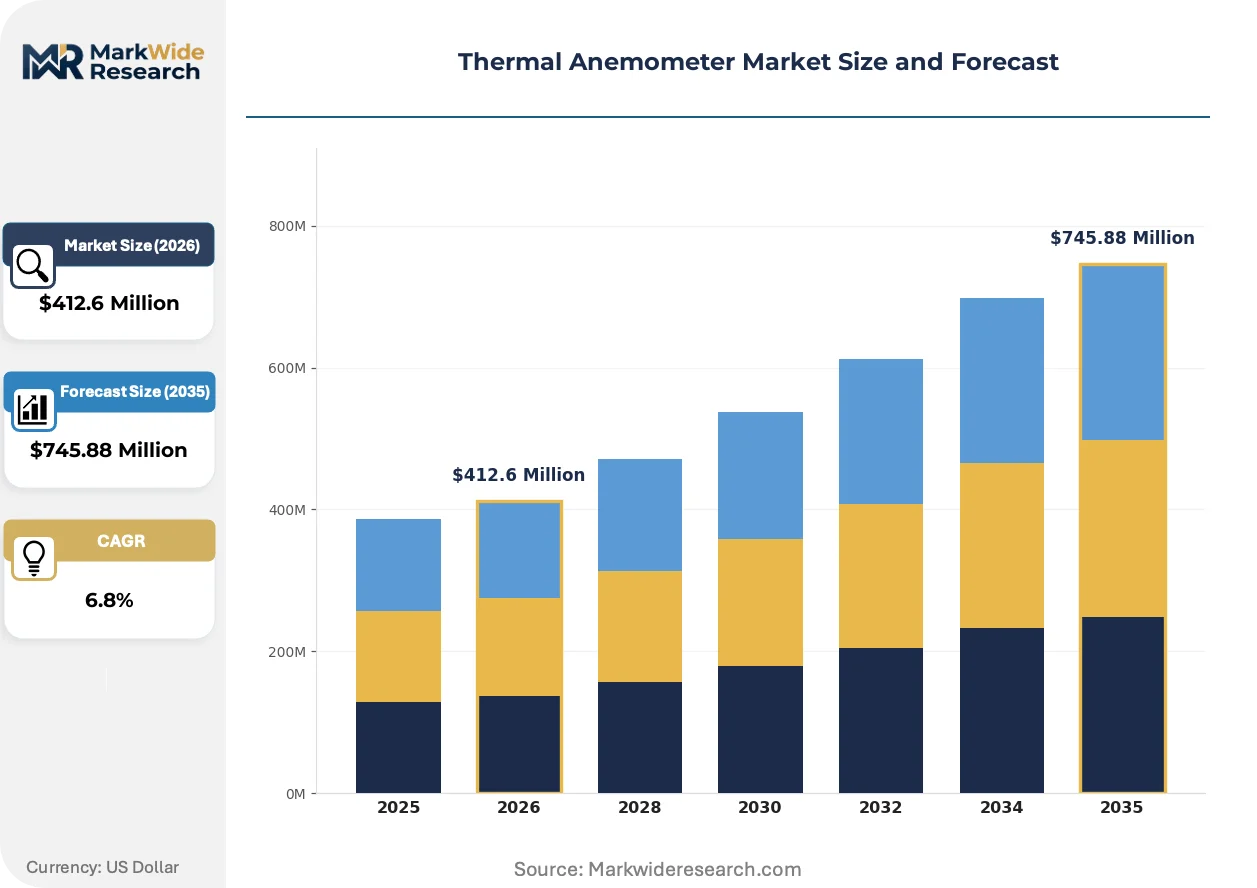
Market Dynamics
The EU F-Gas Regulation and U.S. EPA appliance efficiency standards are compressing commissioning timelines and mandating calibrated airflow verification, forcing instrumentation vendors to bundle wireless telemetry with traditional thermal sensing hardware.
Growth Catalysts
- Passive house construction codes:Germany's building energy standards mandate precise ventilation commissioning, creating pull for portable thermal anemometers in residential and commercial HVAC balancing workflows.
- Semiconductor cleanroom protocols:Precision hot-wire manufacturing requirements in East Asian fabrication facilities sustain demand for research-grade calibration and high-frequency turbulence measurement.
- IoT-enabled continuous monitoring:Wireless sensor architectures are displacing manual spot-checking in building automation systems, expanding addressable volume in facility management networks.
Market Restraints
- Platinum wire supply concentration:Sourcing of sensor-grade platinum elements concentrates in South African and Russian mining operations, exposing manufacturers to geopolitical input volatility.
- MEMS substitution pressure:Microelectromechanical systems anemometers offer lower unit economics for industrial automation, compressing margins in cost-sensitive process control segments.
- Calibration infrastructure gaps:NIST-traceable wind tunnel facilities remain limited outside major metropolitan clusters, extending lead times for certified units in secondary markets.
Strategic Opportunities
- Building decarbonization retrofits:EU Green Deal renovation wave mandates create white space for bundled airflow and refrigerant leak detection platforms in aging commercial building stock.
- Sensor fusion architectures:Convergence of thermal anemometry with particulate and gas sensing enables integrated environmental monitoring platforms for smart city deployments.
- Direct-to-contractor digital channels:HVAC service chains are consolidating procurement through national facility management portals, bypassing traditional distribution tiers.
Industry Challenges
- Metrology talent scarcity:Qualified technicians capable of maintaining hot-wire calibration protocols remain concentrated in aerospace and national laboratory ecosystems.
- Legacy system integration friction:BACnet and Modbus protocol variations across building automation generations complicate wireless sensor deployment in retrofit environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Anemometer Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Wireless, Probes End User: Aerospace, HVAC, Laboratory, Environmental Monitoring Technology: Microelectromechanical Systems, Laser Doppler, Hot Wire, Pitot Tube Application: Research, Industrial Automation, Weather Stations, Ventilation Systems |
| Companies Covered | TSI Incorporated, Testo SE and Co. KGaA, Kanomax Japan, Inc., Fluke Corporation, Omega Engineering, R. M. Young Company, Gill Instruments Ltd., Sensirion AG, Kestrel (Nielsen-Kellerman), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Anemometer Market Evolving Landscape
Electrification of building systems and tightening verification mandates are compressing instrument replacement cycles while expanding the functional perimeter of airflow measurement hardware beyond traditional HVAC boundaries.
MEMS thermal anemometry is electrifying cost structures in industrial automation by replacing platinum hot-wire elements with silicon-based thermal mass sensors. Process control engineers in food and pharmaceutical packaging lines are adopting these units for laminar flow verification. The technology is electrifying entry-level market tiers previously served by mechanical vane anemometers.
The EU F-Gas Regulation mandates documented leak-rate verification procedures dependent on calibrated airflow instrumentation for refrigeration system servicing. This creates binding procurement specifications for dual-function devices combining anemometry with refrigerant detection. European building commissioning contractors are responding by specifying bundled platforms from integrated environmental instrumentation vendors.
Facility management conglomerates are compressing supplier relationships through centralized procurement portals that unbundle after-sales calibration services from hardware acquisition. National HVAC service chains in the United States and Germany are consolidating vendor panels to three approved suppliers per instrument category. This concentration is most visible in energy retrofit contracting, where bundled environmental platform procurement is displacing single-instrument purchasing.
Thermal Anemometer Market Segmentation
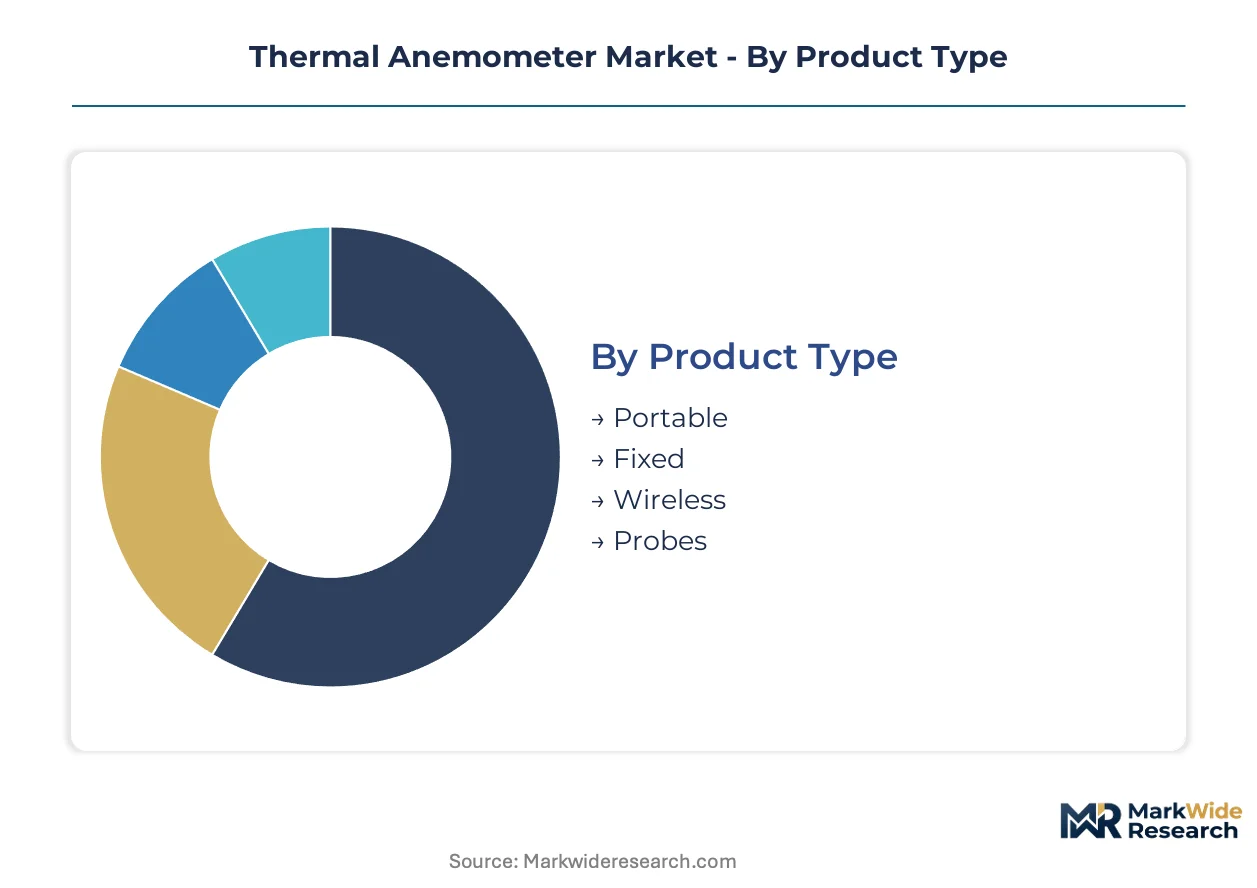
Thermal anemometer procurement patterns diverge sharply across product architectures, end-use environments, and underlying sensing technologies. Understanding these segment boundaries reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Supply concentration in platinum wire sourcing and calibration infrastructure shapes competitive positioning across physical form factors.
- Portable:Battery-powered handheld units with hot-wire or vane sensors dominate field service workflows. HVAC contractors in Germany and the United States concentrate procurement through national facility management portals, compressing vendor panels to three approved suppliers per category.
- Wireless:IoT-enabled nodes transmit continuous airflow data to building automation systems via BACnet or Modbus protocols. Facility management conglomerates are unbundling after-sales calibration from hardware acquisition, accelerating displacement of manual spot-checking routines.
- Fixed:Permanently mounted installations serve meteorological station networks and industrial process control loops.
- Probes:Interchangeable sensor heads enable multi-point measurement grids in wind tunnel research and cleanroom validation.
Today's leader: Portable. Tomorrow's challenger: Wireless.
End User:
Application-specific certification requirements and calibration traceability standards fragment addressable demand across vertical markets.
- HVAC:Building commissioning contractors specify thermal anemometry bundled with refrigerant leak detection platforms to satisfy EU F-Gas Regulation documentation mandates. Germany's passive house construction codes mandate precise ventilation verification, pulling portable units through energy retrofit contracting channels.
- Laboratory:Research-grade calibration protocols with NIST or JIS traceability sustain demand for platinum hot-wire instruments in turbulence research and semiconductor cleanroom applications. METI-standard metrology shapes procurement specifications for Japanese automotive and electronics test facilities.
- Aerospace:Wind tunnel facilities and flight test programs require high-frequency response hot-wire arrays for boundary layer analysis.
- Environmental Monitoring:EPA ambient air quality protocols specify anemometric verification for stack emission measurement systems.
Laboratory commands the steepest expansion trajectory as semiconductor fabrication capacity expands in East Asia.
Technology:
Unit economics and performance specifications determine substitution pressure between legacy and emerging sensing architectures.
- Hot Wire:Platinum or tungsten elements maintained at constant temperature deliver resolution thresholds reaching fractions of a meter per second. Aerospace and national laboratory ecosystems concentrate qualified technicians capable of maintaining calibration protocols, creating capability scarcity outside major metropolitan clusters.
- Microelectromechanical Systems:Silicon-based thermal mass sensors electrify cost structures in industrial automation, displacing mechanical vane anemometers in food and pharmaceutical packaging laminar flow verification.
- Laser Doppler:Non-intrusive optical measurement enables high-precision velocity profiling without probe interference.
- Pitot Tube:Differential pressure instruments persist in aviation and heavy industrial applications requiring mechanical simplicity.
MEMS is gaining share fastest in cost-sensitive process control segments.
Application:
Replacement cycle compression and functional perimeter expansion reshape demand patterns across use-case categories.
- Ventilation Systems:Building decarbonization retrofits under EU Green Deal renovation wave mandates create white space for bundled airflow and refrigerant detection platforms in aging commercial building stock. Electrification of building systems tightens verification requirements.
- Industrial Automation:Process control engineers adopt MEMS thermal anemometry for laminar flow verification in packaging lines, with procurement consolidating through direct-to-contractor digital channels.
- Research:High-frequency turbulence measurement sustains demand for research-grade hot-wire calibration in wind tunnel and atmospheric boundary layer studies.
- Weather Stations:Meteorological networks specify ruggedized fixed installations with wireless telemetry for remote site monitoring.
Ventilation Systems anchors current volume. Industrial Automation represents the fastest-climbing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration technicians and metrology specialists concentrate in aerospace clusters and national laboratory ecosystems across Germany, Japan, and the United States, anchoring regional demand for research-grade instrumentation.
Germany
Passive house construction codes mandate precise ventilation commissioning, pulling portable thermal anemometers through energy retrofit contracting channels. The EU F-Gas Regulation enforces documented leak-rate verification procedures for refrigeration servicing. Stuttgart and Munich host dense concentrations of HVAC engineering firms specifying bundled airflow and refrigerant detection platforms.
United States
EPA ambient air quality monitoring protocols specify anemometric verification for stack emission measurement systems, sustaining demand in environmental compliance workflows. The Department of Energy's appliance efficiency standards tighten airflow verification requirements for HVAC contractors. National laboratory complexes in California and New Mexico concentrate qualified technicians maintaining hot-wire calibration protocols for aerospace applications.
Japan
Precision hot-wire manufacturing requirements in semiconductor cleanroom applications sustain demand for research-grade calibration. METI promotes JIS-standard metrology traceability that shapes procurement specifications for domestic automotive and electronics test facilities. The Chubu region around Nagoya anchors automotive wind tunnel facilities requiring high-frequency turbulence measurement arrays.
China
Semiconductor fabrication capacity expansion in East Asia generates pull for cleanroom validation instrumentation with traceable calibration chains. The country's national environmental regulator enforces ambient air quality standards that specify anemometric verification for industrial emission monitoring. Yangtze River Delta manufacturing clusters are adopting MEMS thermal anemometry for cost-sensitive process control in packaging lines.
South Korea
Semiconductor foundry investments sustain demand for precision airflow measurement in cleanroom environments. The national standards body maintains calibration traceability requirements that shape procurement for domestic electronics test facilities. The Seoul Capital Area concentrates facility management conglomerates consolidating vendor panels for building automation instrumentation.
Thermal Anemometer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures are compressing vendor panels to three approved suppliers per instrument category in national HVAC service chains. Strategic archetypes include research-grade calibration houses, building commissioning platform bundlers, and MEMS cost-displacement specialists. Dominant competitive moves encompass backward integration into sensor-grade platinum sourcing and strategic partnerships for wireless telemetry module integration.
Within the research-grade calibration tier, TSI Incorporated and Kanomax Japan occupy positions exemplifying aerospace and semiconductor cleanroom specialization. Testo SE and Co. KGaA anchors the European building commissioning vector through platform bundling strategies. These three entities represent distinct geographic and application anchoring points rather than direct substitutability.
| Leading Market Players |
|---|
| TSI Incorporated |
| Testo SE and Co. KGaA |
| Kanomax Japan, Inc. |
| Fluke Corporation |
| Omega Engineering |
| R. M. Young Company |
| Gill Instruments Ltd. |
| Sensirion AG |
| Kestrel (Nielsen-Kellerman) |
| Others |
Value Network & Pricing Analysis
Family-owned German metrology specialists and private-equity-rolled-up HVAC service chains anchor procurement discipline, compressing vendor panels while tethering platinum wire sourcing premiums to South African mining volatility and NIST-traceable calibration scarcity.
Pricing Analysis
The bundled-versus-unbundled service split now defines transaction structures. Facility management conglomerates unbundle after-sales calibration from hardware acquisition, forcing three-tier pricing structure across premium, standard, and economy levels based on certification grade and wireless telemetry inclusion. Price differentiation stems from JIS-traceable protocols versus field-grade accuracy and volume scale through national portal procurement. Cost compression in MEMS-based industrial tiers intensifies because silicon thermal mass sensors undercut platinum hot-wire unit economics. HVAC retrofit contractors exhibit highest price sensitivity; aerospace wind tunnel facilities show lowest.
Supply Chain Analysis
Domestic-content mandates in Chinese semiconductor fabrication and Japanese automotive test facilities are reshaping sourcing toward regional calibration infrastructure. Sensor-grade platinum wire concentrates in South African and Russian mining operations; silicon wafer substrates feed from Taiwan and South Korea; precision machining clusters anchor in Germany and Japan. Single-source vulnerability in platinum group metal supply exposes manufacturers to geopolitical input disruption. Distribution runs through national facility management portals consolidating procurement for HVAC service chains, bypassing traditional instrumentation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS cost displacement and wireless telemetry bundling create margin expansion vectors, with silicon-based sensor architectures compressing bill-of-materials while premium-tier research-grade calibration commands sustained pricing power.
For Market Incumbents: Deepen backward integration into captive platinum wire supply arrangements to offset South African and Russian sourcing concentration. Fortify NIST-traceable calibration infrastructure in secondary metropolitan markets where qualified technician scarcity extends certified unit lead times. MEMS substitution pressure in industrial automation segments threatens legacy hot-wire margins; defend through platform bundling with refrigerant detection and BACnet protocol integration.
For New Entrants and Emerging Players: National facility management portals represent the most accessible channel partner type for bypassing traditional distribution tiers. Target EU Green Deal renovation wave contractors in aging German commercial building stock where bundled airflow and leak detection platforms face supply gaps. Penetrate Yangtze River Delta packaging line automation where cost-sensitive MEMS thermal anemometry displaces mechanical vane instruments. Lead with direct-to-contractor digital procurement integration.
For Investors and Strategic Acquirers: Building automation conglomerates are the most active acquirer in this space, consolidating vendor panels to three approved suppliers per instrument category. Long-term viability hinges on sensor fusion architecture capabilities integrating particulate and gas sensing. Acquisition target archetype: MEMS thermal sensor specialists with silicon wafer processing expertise and industrial automation channel relationships. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for dual-function device procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Telemetry Module Integration | Enables IoT-enabled continuous monitoring architectures displacing manual spot-checking in facility management networks. |
| Backward Integration into Platinum Sourcing | Secures sensor-grade wire supply against South African and Russian mining geopolitical volatility. |
| Sensor Fusion Platform Development | Converges thermal anemometry with particulate and gas sensing for smart city environmental monitoring deployments. |
| Direct-to-Contractor Digital Channel Buildout | Bypasses traditional distribution tiers where national HVAC service chains consolidate procurement through centralized portals. |
| NIST-Traceable Calibration Infrastructure Expansion | Addresses technician scarcity outside aerospace and national laboratory metropolitan clusters. |
Research Methodology
Direct dialogue with HVAC commissioning contractors, building automation integrators, semiconductor cleanroom facility engineers, national laboratory metrologists, and platinum wire procurement specialists grounded qualitative findings. Secondary validation drew from EPA ambient air quality protocol documentation, EU F-Gas Regulation implementation guidance, METI JIS standard publications, semiconductor fabrication capacity expansion databases, and HVAC service chain SEC filings. Bottom-up instrumentation unit demand modeling triangulated against top-down building stock retrofit projections.
Market sizing outputs segmented across portable, wireless, fixed, and probe product architectures; HVAC, laboratory, aerospace, and environmental monitoring end users; hot wire, MEMS, laser Doppler, and Pitot tube technologies; and ventilation systems, industrial automation, research, and weather station applications. CAGRs derived from regression analysis of replacement cycle compression trends and regulatory mandate implementation timelines. Forecast inputs incorporated passive house construction code adoption curves and semiconductor fabrication capacity buildouts in East Asia.
Revisions become necessary when platinum supply disruptions, MEMS substitution acceleration, or building decarbonization mandate delays materialize beyond modeled scenarios. Forecasts reflect documented assumptions regarding calibration infrastructure expansion and wireless protocol standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Hall-Effect Sensors Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Europe Sensors Market