
 Bulk Acoustic Wave Sensors Market | 2026-2036
Bulk Acoustic Wave Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Acoustic Wave Sensors Market Outlook
Japan is rewriting the competitive map for bulk acoustic wave sensor fabrication through expanded piezoelectric material foundry investments. Murata Manufacturing leverages captive wafer supply to sustain margin control across resonator product lines. Panasonic anchors high-frequency filter production for telecommunications infrastructure. TDK competes through advanced thin-film deposition expertise in temperature-compensated variants.
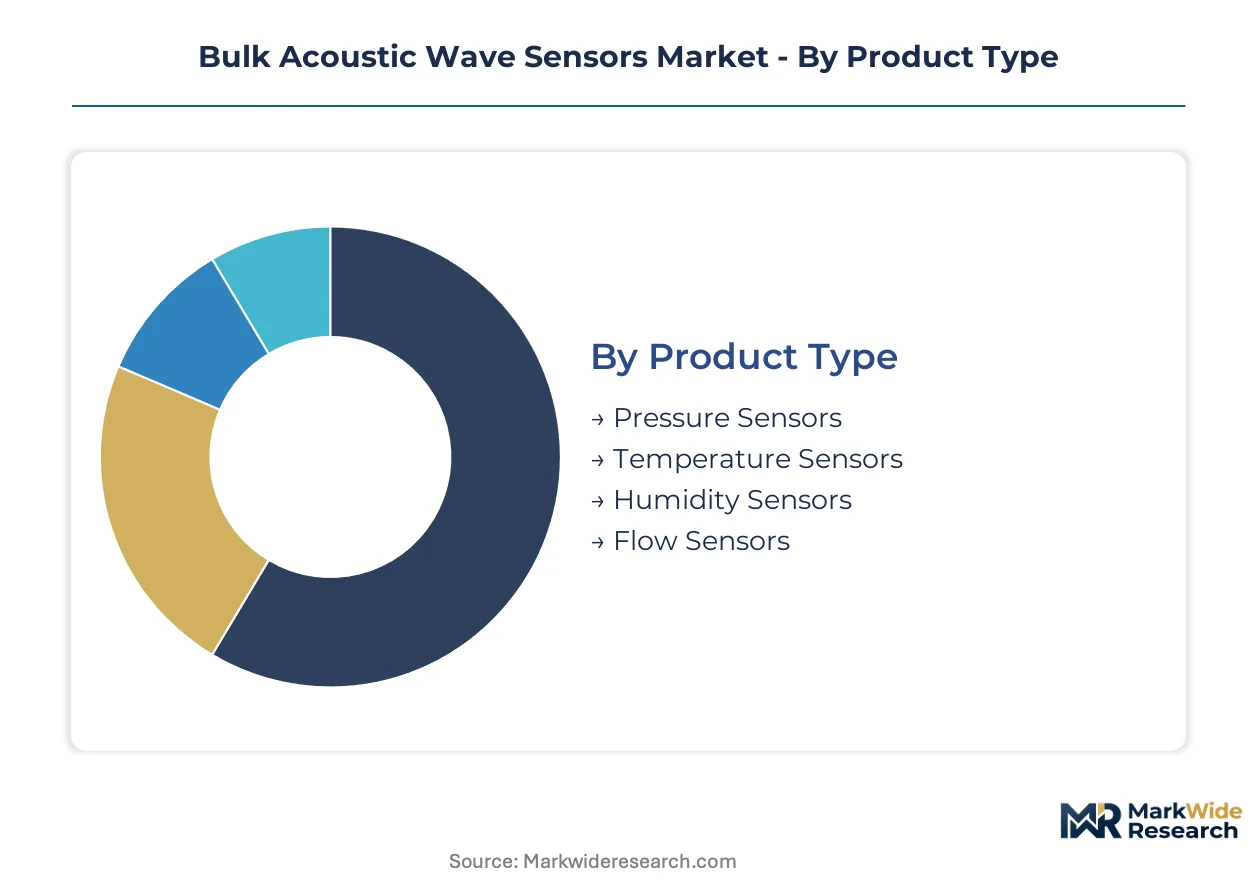
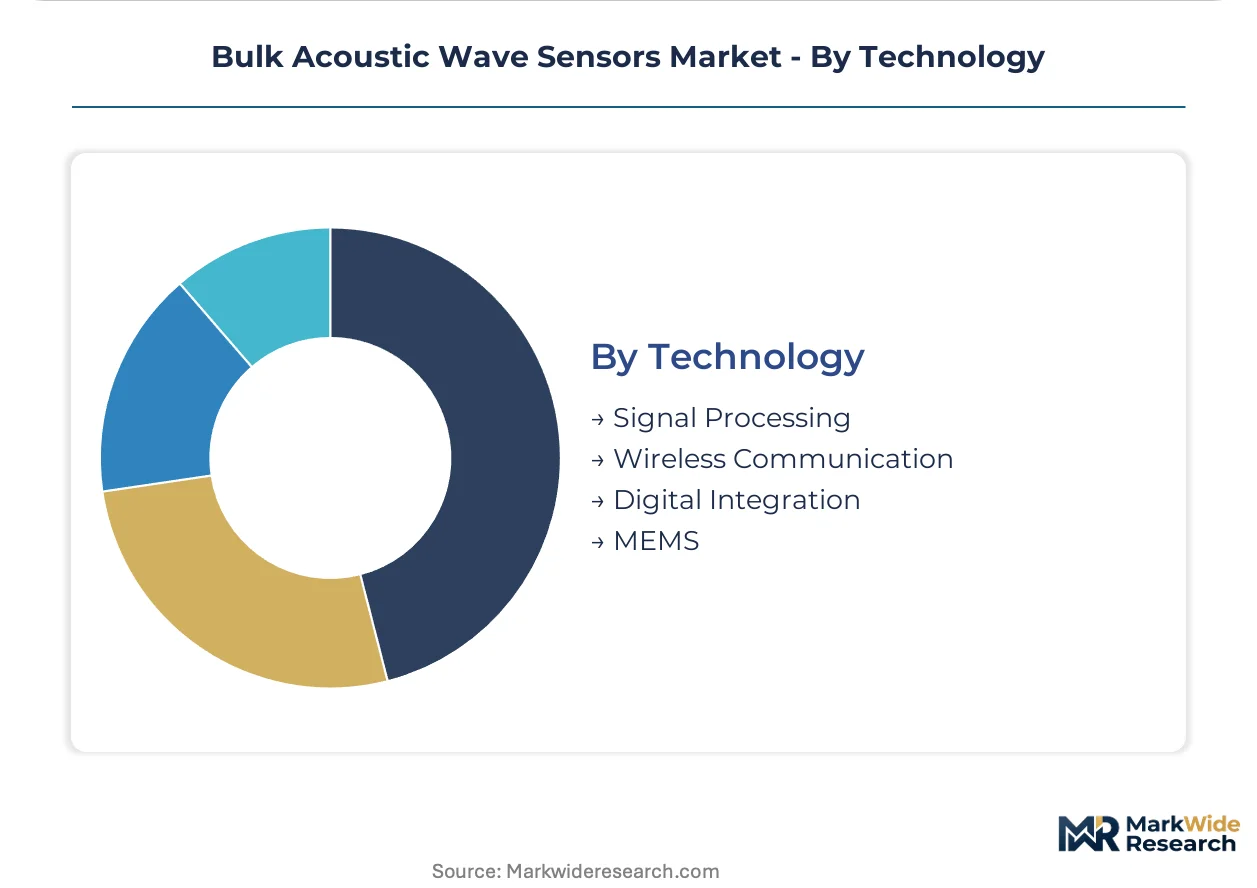
Bulk acoustic wave sensors employ piezoelectric substrates—typically quartz, aluminum nitride, or zinc oxide—to convert mechanical acoustic vibrations into electrical signals at gigahertz frequencies, with quality factors exceeding ten thousand enabling precise frequency control in oscillators and filters. Pressure sensors and temperature sensors occupy the largest revenue pools, while humidity sensors and flow sensors represent faster-expanding niches driven by environmental monitoring mandates and precision agriculture uptake. Wireless communication and MEMS technology segments are attracting disproportionate R&D allocation as 5G infrastructure deployment and miniaturization requirements intensify.
Japan's METI enforces JIS standards for electronic component reliability that shape export qualification protocols, while the US FCC governs spectrum allocation affecting filter performance specifications in telecommunications applications. China's MIIT implements GB standards for domestic sensor certification that condition market access for foreign suppliers. Stakeholders must monitor evolving frequency band reallocations and material sourcing restrictions as determinants of product roadmap viability and geographic manufacturing placement.
Market Dynamics
Vehicle electrification is accelerating sensor integration density across powertrain and battery management systems, while East Asian foundry expansion for piezoelectric substrates concentrates supply leverage among a handful of substrate suppliers.
Growth Catalysts
- Automotive Electrification Mandates:Battery thermal monitoring and inverter control systems require precision frequency references that bulk acoustic wave resonators deliver. Tier-1 automotive suppliers are qualifying these devices for 800V architectures.
- China's GB Standards:MIIT certification requirements for electronic component reliability are tightening quality thresholds, creating replacement demand for imported devices that meet elevated environmental stress testing protocols.
- 5G Infrastructure Deployment:Massive MIMO base stations and small cell networks require temperature-compensated filters with sub-ppm stability. Telecommunications equipment manufacturers are expanding RF front-end module capacity.
Market Restraints
- Quartz Supply Concentration:High-purity cultured quartz crystal production concentrates in limited geographic corridors, exposing resonator manufacturers to substrate availability constraints and price volatility.
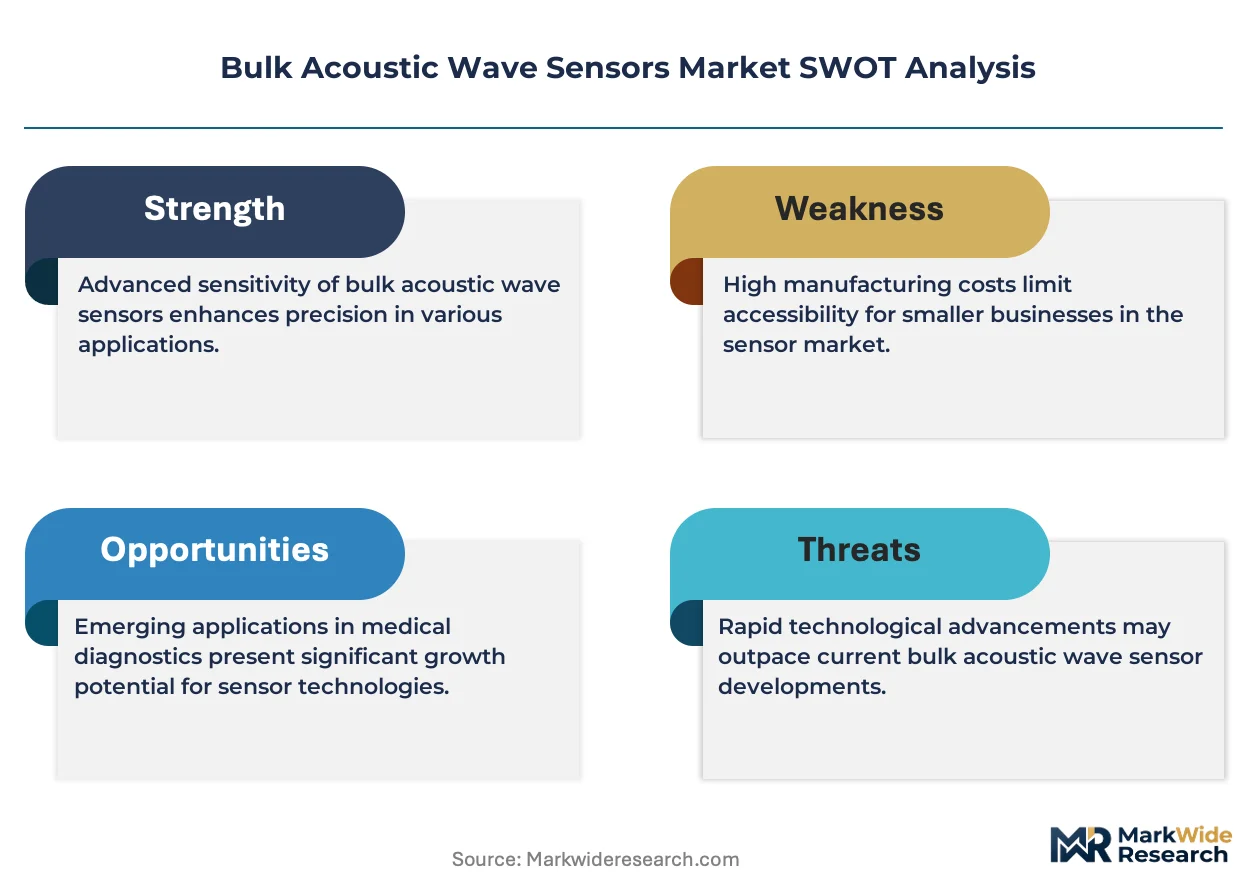
- Aluminum Nitride Deposition Costs:Thin-film piezoelectric layer fabrication requires molecular beam epitaxy or sputtering equipment with extended qualification cycles, elevating capital intensity for new entrants.
- MEMS Oscillator Substitution:Silicon-based timing devices from integrated MEMS foundries are capturing socket share in consumer electronics where absolute frequency precision requirements are relaxed.
Strategic Opportunities
- Precision Agriculture Expansion:Soil moisture and microclimate monitoring networks in water-stressed agricultural regions are creating demand for low-power humidity and temperature sensor nodes with wireless backhaul.
- EU F-Gas Regulation Phase-Down:Refrigerant leak detection mandates under the F-Gas Regulation are accelerating adoption of acoustic wave-based gas sensors in commercial HVAC and cold chain logistics.
- Thin-Film Lithium Niobate Convergence:Hybrid integration of lithium niobate films with CMOS readout circuits is collapsing form factors for high-frequency filters targeting millimeter-wave spectrum.
Industry Challenges
- Piezoelectric Material Science Talent Gap:Foundry engineering roles requiring expertise in crystalline defect engineering and electromechanical coupling optimization remain understaffed relative to expansion timelines.
- Multi-Band Certification Complexity:Filter products supporting carrier aggregation across fragmented regional spectrum allocations require iterative regulatory testing cycles that extend time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Acoustic Wave Sensors Market |
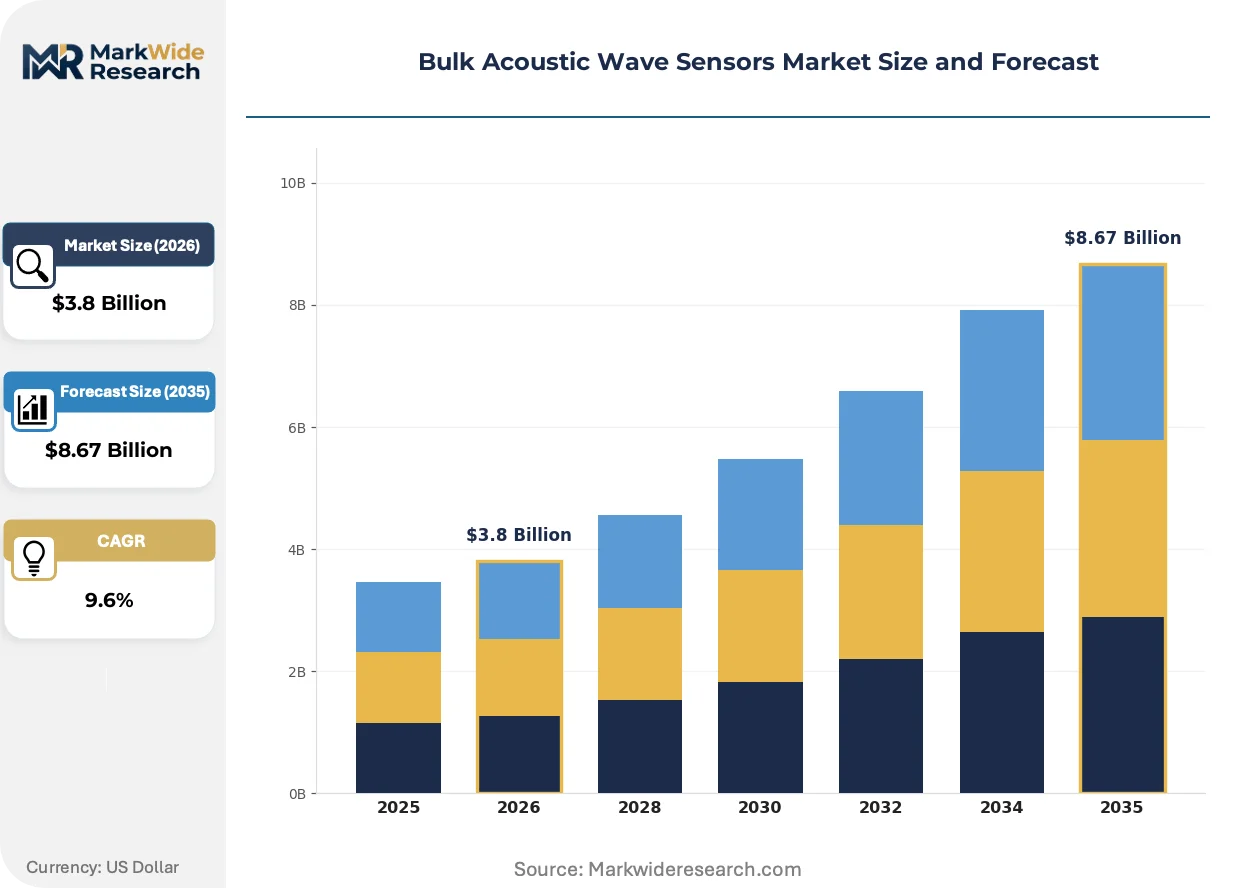
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Humidity Sensors, Flow Sensors Application: Healthcare Monitoring, Environmental Sensing, Automative Testing, Industrial Automation End User: Healthcare Providers, Manufacturing Industries, Aerospace Sector, Consumer Electronics Technology: Signal Processing, Wireless Communication, Digital Integration, MEMS |
| Companies Covered | Murata Manufacturing, Panasonic, TDK, CTS Corporation, Teledyne Technologies, Broadcom, Qorvo, Akoustis Technologies, API Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Acoustic Wave Sensors Market Strategic Shifts
Acoustic wave device architecture is undergoing fundamental restructuring as substrate engineering and packaging integration advance in parallel, compressing traditional performance-cost trade-offs.
Thin-film lithium niobate on insulator is collapsing the power-handling and insertion-loss gap between bulk acoustic wave and surface acoustic wave technologies. Base station OEMs are accelerating qualification of these heterostructures for sub-6 GHz massive MIMO arrays. The technology is collapsing incumbent filter suppliers' ability to defend product line segmentation between macro and small cell applications.
The EU F-Gas Regulation's stepped refrigerant phase-down is mandating pervasive leak detection infrastructure across commercial refrigeration and air conditioning systems. Sensor module integrators are embedding acoustic wave gravimetric detectors with polymer functionalization layers to achieve parts-per-billion sensitivity for hydrofluorocarbon species. Cold chain logistics operators in Germany and France are deploying these nodes ahead of 2025 enforcement milestones.
Consolidated procurement of frequency control components is displacing fragmented supplier relationships among telecommunications infrastructure deployers. Network equipment manufacturers are centralizing resonator and filter sourcing through approved vendor lists with consolidated technical qualification pathways. This concentration is most visible in South Korean 5G rollout programs, where three equipment vendors now control component specification authority.
Bulk Acoustic Wave Sensors Market Segmentation
Bulk acoustic wave sensor procurement patterns diverge sharply across application contexts, with automotive and telecommunications buyers demanding multi-year qualification cycles while environmental monitoring deploys faster-turn sensor nodes. Understanding segment-level velocity and margin structure illuminates where substrate investments concentrate.
Product Type:
Pressure sensors and temperature sensors operate on extended replacement cycles tied to industrial equipment lifespans, while humidity and flow sensors refresh more rapidly as IoT node density increases.
- Pressure Sensors:These devices exploit quartz resonator frequency shifts under mechanical stress to achieve sub-0.1% full-scale accuracy in harsh media. Demand concentrates in automotive powertrain modules where 800V electrification architectures require hermetic, high-temperature-capable sensing elements.
- Temperature Sensors:Temperature-compensated resonator designs leverage aluminum nitride thin-film stacks to maintain frequency stability across -40°C to 150°C operating windows. Battery management systems in German and South Korean EV programs are absorbing disproportionate volume as thermal runaway detection mandates tighten.
- Humidity Sensors:Polymer-coated surface acoustic wave structures enable rapid moisture uptake detection for precision agriculture networks in water-stressed regions.
- Flow Sensors:Gravimetric acoustic wave transducers measure fluid density and viscosity changes for microfluidic diagnostic cartridges.
Pressure sensors dominate installed base. Humidity sensors are where expansion concentrates.
Application:
Cost tiers separate mission-critical healthcare and aerospace qualification pathways from high-volume automotive and environmental sensing procurement.
- Healthcare Monitoring:Implantable and wearable diagnostic platforms require biocompatible packaging and FDA 510(k) clearance pathways. Point-of-care testing cartridges for cardiac biomarker detection are driving miniaturized resonator demand in Massachusetts and California medical device clusters.
- Automotive Testing:Powertrain validation rigs and battery cyclers employ precision frequency references for sensor fusion calibration. Tier-1 suppliers in Stuttgart and Toyota City are qualifying resonators for 800V inverter control loops.
- Environmental Sensing:Distributed air quality networks in the EU and China deploy low-power acoustic wave nodes for particulate and gas detection.
- Industrial Automation:Vibration monitoring and predictive maintenance systems integrate resonator-based pressure transducers for pump and compressor health tracking.
Automotive testing commands premium pricing. Environmental sensing is climbing the fastest.
End User:
Volume concentration varies dramatically, with consumer electronics absorbing billions of units annually while aerospace procurement runs in thousands with extreme qualification overhead.
- Healthcare Providers:Hospital systems and diagnostic laboratories specify resonator-based sensors for hematology analyzers and immunoassay platforms. CLIA-waived testing expansion in US outpatient settings is accelerating disposable cartridge demand.
- Manufacturing Industries:Process control and quality assurance departments integrate acoustic wave sensors for inline viscosity and density monitoring. Chemical plants along the US Gulf Coast and Germany's Rhine corridor are retrofitting legacy instrumentation.
- Aerospace Sector:Satellite and avionics applications require radiation-hardened, hermetically sealed resonators with decades-long reliability documentation.
- Consumer Electronics:Smartphones and wearables incorporate MEMS-competitive timing references where space constraints override absolute precision requirements.
Manufacturing industries anchor volume demand. Healthcare providers are where margin expansion concentrates.
Technology:
Supply concentration for deposition equipment and foundry capacity shapes which technology pathways scale fastest.
- Wireless Communication:Temperature-compensated bulk acoustic wave filters enable carrier aggregation in sub-6 GHz 5G base stations. South Korean and Finnish network equipment vendors are consolidating approved vendor lists for RF front-end modules.
- MEMS:Silicon-based resonator fabrication leverages existing CMOS foundry infrastructure for cost-sensitive consumer applications. Integrated MEMS foundries in Taiwan and Singapore are capturing socket share from quartz-based alternatives.
- Signal Processing:Digital compensation algorithms extend resonator effective temperature range in software-defined instrumentation.
- Digital Integration:CMOS-MEMS monolithic integration collapses form factors for implantable medical devices.
Wireless communication dominates R&D allocation. MEMS is where manufacturing scale concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piezoelectric substrate foundry capacity concentrates in East Asian manufacturing corridors, with Japan, China, and South Korea commanding the bulk of resonator-grade material supply. This geographic clustering shapes qualification protocols and export licensing conditions for sensor manufacturers serving automotive and telecommunications end markets.
Japan
Automotive electrification and 5G infrastructure deployment drive resonator demand from Murata Manufacturing and TDK. METI enforces JIS standards for electronic component reliability that condition export qualification for telecommunications equipment. The Kanto region around Tokyo anchors high-frequency filter production for base station OEMs.
China
Domestic EV battery thermal monitoring and industrial automation expand sensor absorption across BYD and CATL supply chains. MIIT implements GB standards for electronic component reliability that tighten quality thresholds for imported devices. The Yangtze River Delta manufacturing corridor concentrates foundry capacity for aluminum nitride thin-film deposition.
South Korea
Massive MIMO base station rollout and smartphone RF front-end modules sustain filter demand from Samsung Networks and LG Innotek. The national spectrum regulator governs carrier aggregation requirements affecting temperature-compensated resonator specifications. The Seoul Capital Area hosts consolidated procurement offices for telecommunications equipment vendors.
Germany
Industrial automation retrofit programs and refrigerant leak detection mandates under the EU F-Gas Regulation accelerate acoustic wave sensor adoption. The KBA oversees automotive component qualification for 800V powertrain architectures. The Rhine corridor chemical plants and Stuttgart automotive clusters integrate precision pressure transducers for process control.
United States
Satellite constellations and defense avionics require radiation-hardened resonators with decades-long reliability documentation. The FCC governs spectrum reallocation affecting filter performance specifications in telecommunications applications. Greater Boston medical device clusters absorb miniaturized resonators for point-of-care diagnostic cartridges.
Bulk Acoustic Wave Sensors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate and resonator fabrication. The vendor base stratifies between captive foundry operators and fabless design houses. Three archetypes dominate: vertically integrated Japanese conglomerates with in-house piezoelectric material supply, RF semiconductor specialists leveraging compound semiconductor expertise, and MEMS foundries exploiting CMOS-compatible silicon resonator platforms. Competitive moves center on substrate supply security through long-term quartz sourcing agreements and thin-film deposition equipment partnerships.
Among Japanese fabricators, Murata Manufacturing, TDK, and Panasonic exemplify the vertically integrated archetype with captive wafer supply chains. Murata Manufacturing represents the substrate-autonomous model with internal piezoelectric material production. TDK occupies a position emphasizing advanced thin-film deposition capabilities. Panasonic anchors high-frequency filter production for telecommunications infrastructure. These three entities collectively demonstrate how East Asian manufacturing concentration sustains margin control through backward integration into resonator-grade material supply.
| Leading Market Players |
|---|
| Murata Manufacturing |
| Panasonic |
| TDK |
| CTS Corporation |
| Teledyne Technologies |
| Broadcom |
| Qorvo |
| Akoustis Technologies |
| API Technologies |
| Others |
Value Chain & Pricing Dynamics
Cultured quartz crystal production concentrates in limited East Asian corridors, tethering resonator pricing power to substrate availability constraints while margin pools accumulate at thin-film deposition equipment tiers and automotive qualification gateways.
Pricing Analysis
China's GB standards dictate the pricing tier structure across automotive and telecommunications segments. Three-tier pricing stratifies across automotive-grade, industrial-grade, and consumer-grade certification levels, with automotive-grade resonators commanding substantial premia for 800V architecture qualification. Cost compression runs through consumer electronics tiers as MEMS oscillator substitution intensifies. Tier-1 automotive suppliers exhibit the least price sensitivity due to thermal runaway detection mandates, while consumer electronics OEMs drive aggressive procurement negotiations.
Supply Chain Analysis
Murata Manufacturing, TDK, and Panasonic hold captive foundry capacity for piezoelectric substrate fabrication. Japan, China, and South Korea anchor resonator-grade material supply, with the Yangtze River Delta concentrating aluminum nitride thin-film deposition capacity. Supply chains draw from high-purity cultured quartz, molecular beam epitaxy equipment, and polymer functionalization chemistries. Single-source vulnerability concentrates at substrate tier. Distribution runs through approved vendor lists consolidated by South Korean and Finnish telecommunications equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware across calibration, predictive maintenance, and regulatory compliance monitoring layers, with aftermarket sensor node management for precision agriculture networks outpacing unit shipment growth.
For Market Incumbents: Build captive substrate supply moats through long-term quartz sourcing agreements and molecular beam epitaxy equipment partnerships. Deepen backward integration into piezoelectric material production to defend margin position against MEMS oscillator substitution. Expand foundry capacity in the Kanto region to capture 5G infrastructure filter demand from base station OEMs.
For New Entrants and Emerging Players: Build out precision agriculture sensor node offerings targeting water-stressed agricultural regions in the EU and China. The refrigerant leak detection segment under EU F-Gas Regulation mandates offers the most penetrable white space. Pursue direct partnerships with cold chain logistics operators ahead of enforcement milestones.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with RF semiconductor specialists seeking compound semiconductor expertise adjacencies. Long-term viability hinges on substrate supply security and thin-film lithium niobate qualification timelines. Monitor carrier aggregation certification cycles across fragmented regional spectrum allocations as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quartz Sourcing Agreement | Secures substrate supply for Murata Manufacturing against price volatility in resonator-grade material. |
| Thin-Film Lithium Niobate Qualification | Enables TDK to collapse form factors for millimeter-wave spectrum filters in South Korean base stations. |
| Precision Agriculture Node Deployment | Positions Panasonic to capture soil moisture monitoring demand in water-stressed EU agricultural regions. |
| EU F-Gas Regulation Compliance Service | Creates recurring revenue layer for refrigerant leak detection calibration across German cold chain operators. |
| Automotive 800V Architecture Certification | Unlocks tier-1 supplier procurement pathways for battery thermal monitoring in German and South Korean EV programs. |
Study Parameters
A standing panel of resonator design engineers, foundry operations managers, tier-1 automotive supplier procurement leads, and telecommunications equipment RF architects provided ongoing calibration. Primary interviews combined with secondary validation from SEC filings, METI industrial statistics, MIIT certification databases, and customs trade records. Bottom-up unit shipment modeling triangulated against top-down value estimates across the analysis window.
Scenario bracketing anchored low, base, and high cases around substrate availability constraints and MEMS substitution velocity. Segmentation dimensions spanned product type, application context, end-user industry, and technology pathway. CAGRs derived from regression analysis against automotive electrification penetration curves and 5G infrastructure deployment schedules. Thin-film deposition equipment lead times and quartz crystal growth capacity expansion timelines informed supply-side constraints.
Stress conditions across aluminum nitride raw material pricing, spectrum reallocation timing, and MEMS oscillator performance improvement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry capacity expansion and regulatory certification cycle durations. Quarterly review of substrate spot pricing and carrier aggregation certification backlog is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
PID Controller Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
High-Precision Confocal Sensor Market