
 Electric Substation Market | 2026-2036
Electric Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Substation Market Intelligence
Market Context
Skilled substation engineering talent is collapsing across North America and Western Europe as veteran technicians retire faster than apprenticeship pipelines refill. Siemens Energy leverages its transformer manufacturing scale to anchor European grid upgrade cycles, while Hitachi Energy competes through digital substation platforms that integrate protection and control software. ABB dominates high-voltage direct current interconnector projects, a segment where technical complexity creates durable competitive moats.
Technical Definition and Segments
An electric substation is a facility where voltage transforms through switchgear assemblies, circuit breakers, and control systems to enable efficient power transmission and distribution across distances from generation source to end load. Transformer components command the largest value share due to material intensity in core steel and winding copper, though control systems are expanding fastest as utilities deploy IEC 61850-compliant digital architectures. Outdoor installations retain volume leadership for utility-scale applications, while modular and containerized formats are gaining share in remote renewable integration and data center power delivery where deployment speed outweighs unit cost.
Regulatory Environment
FERC Order 2023 and EPA greenhouse gas phase-down rules are reshaping US substation equipment specifications, while the EU F-Gas Regulation and CE marking under MDR pressure European utilities toward sulfur hexafluoride-free switchgear alternatives. China's GB standards and dual carbon goals enforce domestic content requirements that shape competitive access. Stakeholders must monitor how divergent national decarbonization timelines fragment equipment certification regimes and complicate cross-border procurement strategies.
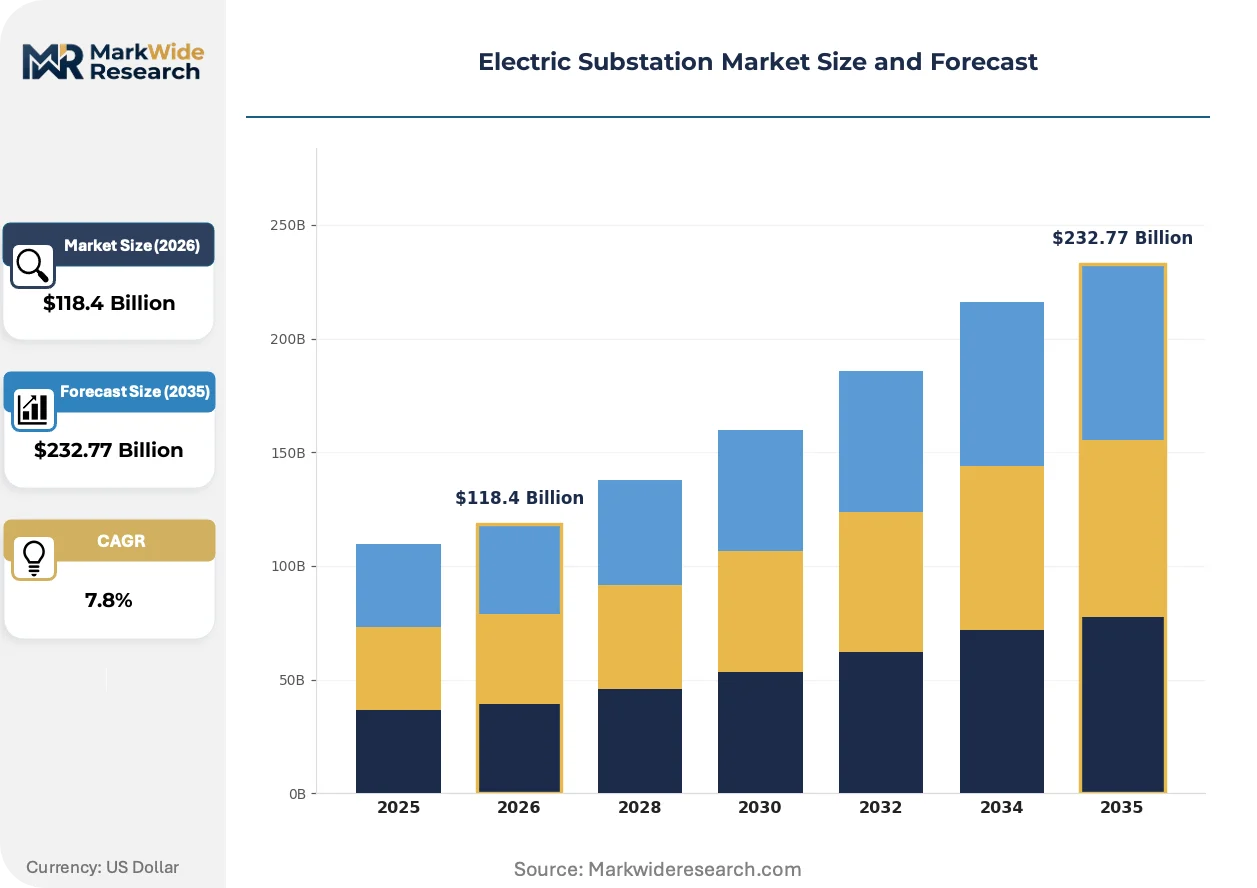
Market Dynamics
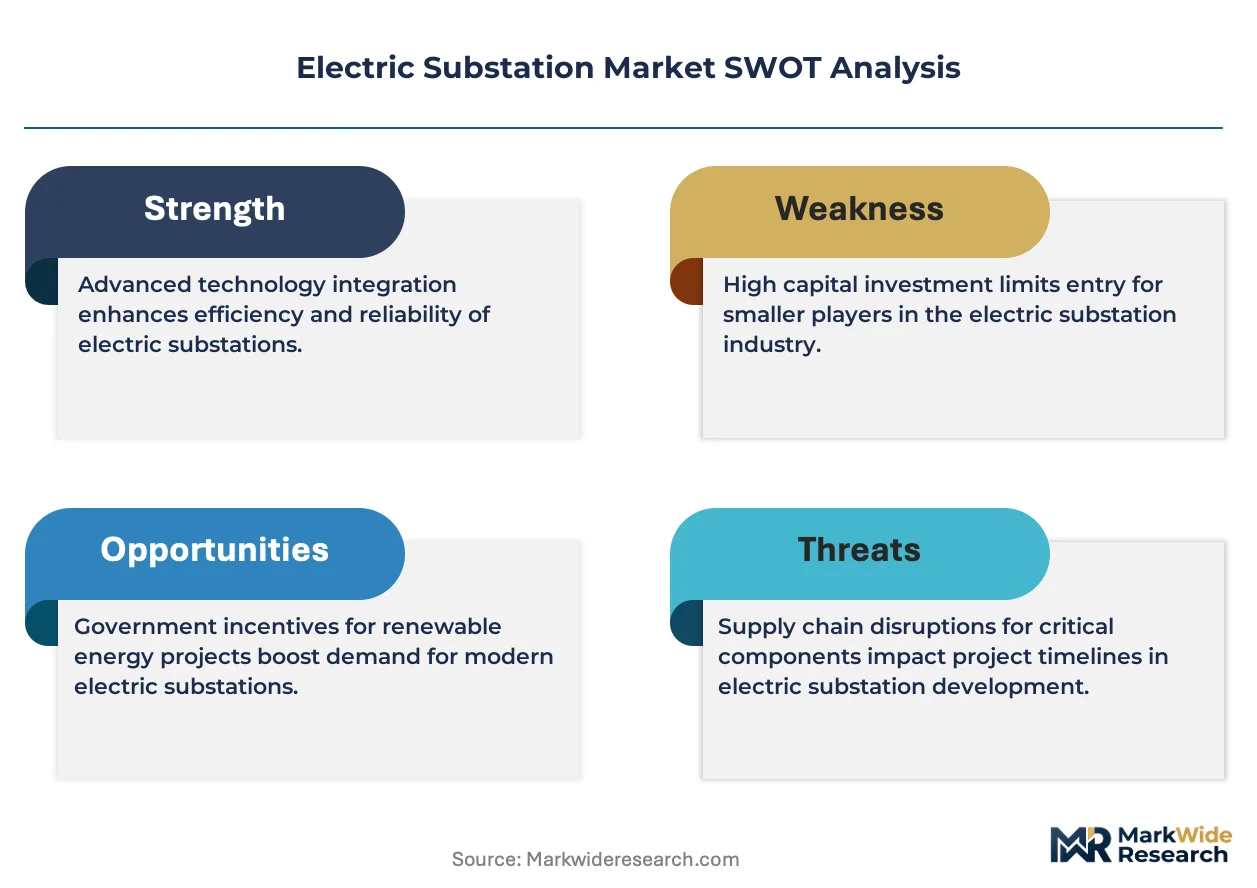
Grid hardening mandates under the US Infrastructure Investment and Jobs Act and parallel European frameworks are compressing replacement cycles while simultaneously constraining transformer supply chains already depleted by skilled labor attrition.
Growth Catalysts
- Renewable Generation Integration:Utility-scale solar and wind farms in China, India, and the United States require high-voltage collection infrastructure to connect remote generation to load centers.
- FERC Order 2023:This US regulatory mandate accelerates interconnection queue processing, forcing utilities to expand substation capacity for queued renewable projects.
- Copper and Core Steel Intensity:Transformer manufacturing scales with raw material throughput, creating procurement urgency as electrification drives winding and core demand.
Market Restraints
- Specialized Labor Collapse:Veteran substation technicians in North America and Western Europe are retiring faster than apprenticeship pipelines refill, extending project timelines.
- SF6 Phase-Down Friction:The EU F-Gas Regulation and EPA greenhouse gas rules pressure switchgear suppliers toward unproven alternatives with limited field history.
- Domestic Content Requirements:China's GB standards enforce local manufacturing quotas that fragment equipment certification regimes and complicate cross-border procurement.
Strategic Opportunities
- Modular Containerized Formats:Remote renewable integration sites and data center power delivery favor deployment speed over unit cost, opening share for factory-built solutions.
- Digital Substation Architectures:IEC 61850-compliant protection and control software convergence creates white space for integrated platform vendors against component specialists.
- India Transmission Expansion:Central Electricity Authority targets and state-level renewable purchase obligations drive greenfield substation construction across Rajasthan, Gujarat, and Tamil Nadu.
Industry Challenges
- Substation Engineering Talent Scarcity:Protection relay programming and high-voltage testing expertise concentrates among aging specialists with limited knowledge transfer mechanisms.
- Legacy Asset Integration Complexity:Digital control system overlays must interface with electromechanical protection schemes installed decades prior, multiplying commissioning risk.
- CE Marking Timeline Compression:MDR and EU F-Gas Regulation convergence forces simultaneous equipment recertification, straining notified body capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Substation Market |
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $232.77 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Transformers, Switchgear, Circuit Breakers, Control Systems Application: Renewable Energy Integration, Grid Modernization, Power Distribution, Industrial Supply End User: Utilities, Industrial Plants, Commercial Buildings, Government Entities Installation Type: Indoor, Outdoor, Modular, Containerized |
| Companies Covered | ABB, Eaton Corporation, Hitachi Energy, Toshiba Energy Systems & Solutions Corporation, Mitsubishi Electric, Siemens Energy, Schneider Electric, Hyosung, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Substation Market Strategic Shifts & Innovations
Digitalization is bifurcating substation procurement between integrated platform vendors and component specialists, while regulatory pressure on sulfur hexafluoride accelerates alternative insulation development.
Gas-insulated switchgear using vacuum interrupters and clean air insulation is fragmenting the high-voltage segment as European utilities under EU F-Gas Regulation pressure pilot SF6-free alternatives. German transmission system operators and Nordic grid operators are deploying these systems at 145 kV and above, compressing the addressable market for conventional GIS manufacturers.
The EPA greenhouse gas phase-down rules and FERC interconnection mandates are reshaping US equipment specifications simultaneously, forcing utilities to reconcile faster deployment timelines with unfamiliar switchgear chemistries. California ISO and ERCOT interconnection regions face the tightest compliance windows as queue volumes surge.
Asset ownership models are diverging as data center operators and renewable developers bypass traditional utility procurement channels to contract directly with OEMs for integrated substation packages. This disintermediation concentrates in Virginia's Northern Virginia cluster and Texas ERCOT zones where hyperscale load growth outpaces utility planning cycles.
Electric Substation Market Segmentation
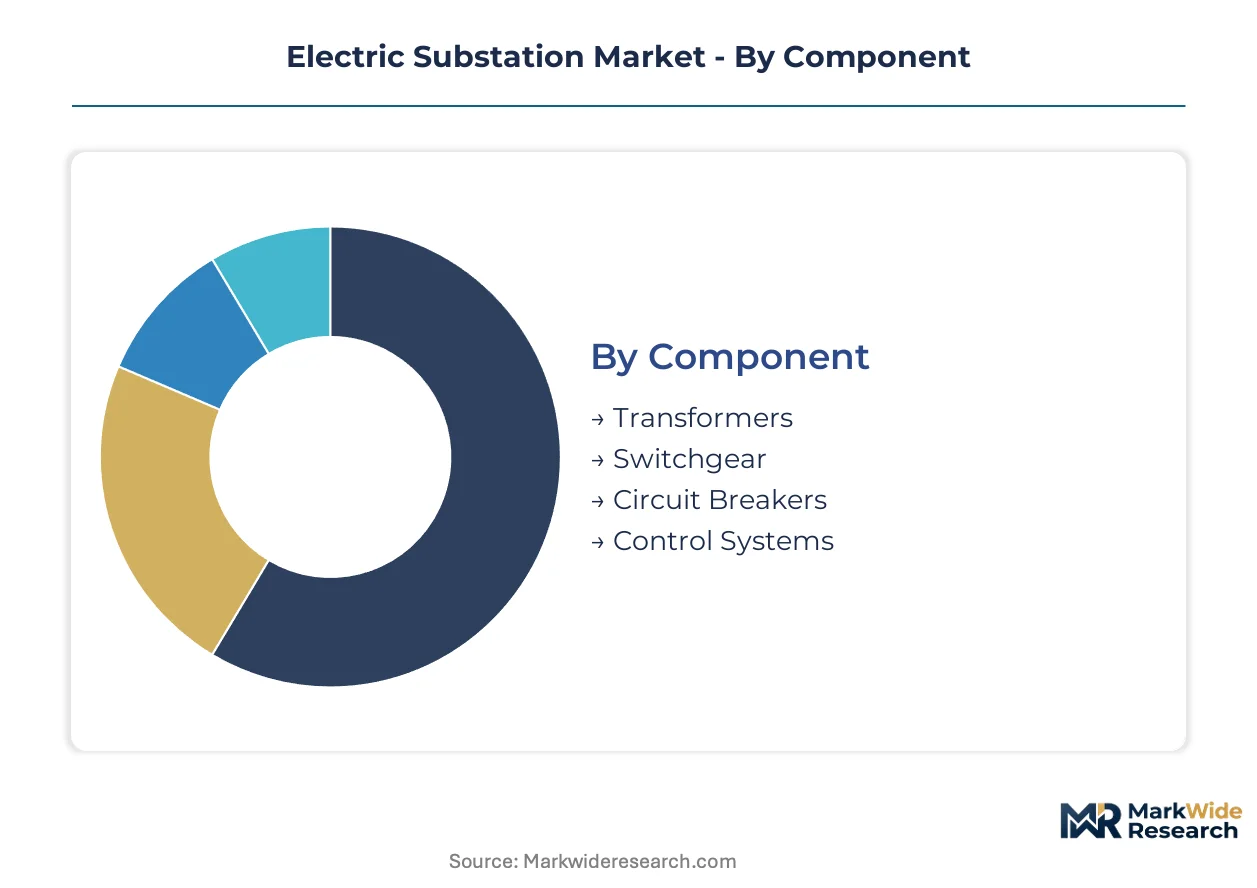
Substation procurement channels diverge sharply by component complexity and project scale. OEM direct sales dominate transformer and switchgear transactions, while system integrators capture control system bundles. Understanding these flow patterns exposes where margin pools concentrate and which segments invite vendor consolidation.
Component:
Channel economics split this category between material-heavy hardware flowing through long-term supply agreements and software-defined systems sold via platform licensing.
- Transformers:Core steel and winding copper assemblies constitute the largest value concentration in any substation build. Procurement urgency intensifies in India and the United States as transmission expansion absorbs renewable generation, yet skilled labor attrition extends manufacturing lead times.
- Switchgear:Gas-insulated and air-insulated assemblies are pivoting toward SF6-free alternatives under EU F-Gas Regulation and EPA greenhouse gas phase-down rules. European utilities pilot vacuum interrupter designs at 145 kV and above, compressing the addressable market for conventional GIS manufacturers.
- Circuit Breakers:High-voltage interruption equipment faces simultaneous recertification pressure from CE marking under MDR and F-Gas Regulation convergence.
- Control Systems:IEC 61850-compliant digital architectures are expanding fastest as protection and control software converges on integrated platforms.
Transformers dominate installed base. Control Systems are where expansion concentrates.
Application:
Project timelines and risk allocation vary dramatically across these use cases, with utility procurement cycles stretching years while industrial buyers prioritize speed.
- Renewable Energy Integration:Utility-scale solar and wind farms in Rajasthan, Gujarat, and Tamil Nadu require high-voltage collection infrastructure to connect remote generation to load centers. FERC Order 2023 accelerates interconnection queue processing, forcing capacity expansion for queued projects.
- Grid Modernization:Aging infrastructure replacement concentrates in Germany and the United States where grid hardening mandates compress asset lifecycles. Siemens Energy anchors European upgrade cycles through manufacturing scale.
- Power Distribution:Last-mile voltage transformation serves fragmented municipal and cooperative utility structures with standardized equipment specifications.
- Industrial Supply:Captive substations for heavy manufacturing favor modular formats where deployment speed outweighs unit cost optimization.
Grid Modernization commands the largest project values. Renewable Energy Integration is climbing the fastest.
End User:
Buyer sophistication and procurement authority shape vendor engagement models, from centralized utility tendering to decentralized industrial direct sourcing.
- Utilities:Vertically integrated transmission and distribution operators specify equipment through multi-year framework agreements. China's State Grid and Southern Power Grid enforce domestic content requirements under GB standards that fragment cross-border procurement.
- Industrial Plants:Steel, chemical, and semiconductor facilities operate captive substations with reliability requirements that justify premium equipment specifications.
- Commercial Buildings:Data center operators in Virginia's Northern Virginia cluster and Texas ERCOT zones bypass traditional utility channels to contract directly with OEMs for integrated packages.
- Government Entities:Military and civilian infrastructure projects carry security screening requirements that limit vendor eligibility to domestic or allied-country suppliers.
Utilities dominate procurement volume. Industrial Plants are gaining share fastest.
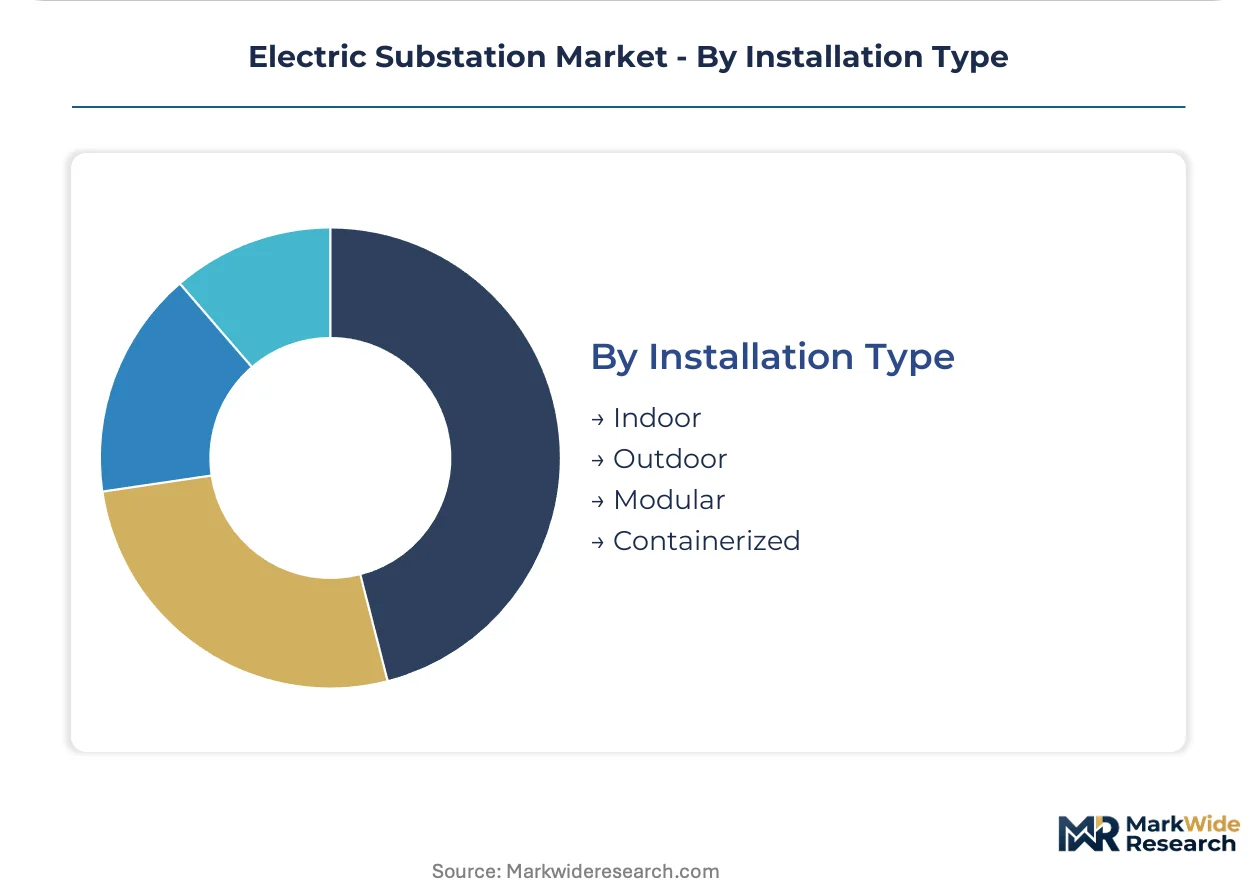
Installation Type:
Capital deployment patterns and operational flexibility tradeoffs differentiate these formats, with legacy infrastructure favoring permanent construction and new load centers demanding mobility.
- Outdoor:Conventional open-air substations retain volume leadership for utility-scale applications where land availability and environmental permitting allow permanent construction. Established supply chains and standardized commissioning protocols reduce execution risk.
- Modular:Factory-built assemblies reduce on-site labor requirements, addressing skilled technician scarcity in North America and Western Europe. Pre-commissioned equipment arrives as plug-compatible blocks.
- Indoor:Urban density constraints and environmental containment drive gas-insulated switchgear deployment in metropolitan substations.
- Containerized:Fully transportable units serve remote renewable integration sites and temporary data center power delivery where deployment speed outweighs unit cost.
Outdoor installations dominate installed base. Modular formats are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys substations at utility-scale renewable velocity, while the United States prioritizes grid hardening over greenfield expansion, and Germany leads SF6-free switchgear piloting under EU F-Gas Regulation pressure.
United States
FERC Order 2023 compresses interconnection queue timelines for solar and wind projects across California ISO and ERCOT zones. The Infrastructure Investment and Jobs Act channels federal funding toward transformer replacement cycles accelerated by wildfire resilience mandates. Virginia's Northern Virginia cluster sees data center operators contracting directly with OEMs for integrated substation packages as hyperscale load growth outpaces utility planning.
China
State Grid and Southern Power Grid expand ultra-high-voltage transmission corridors to absorb remote wind and solar generation from western provinces. GB standards enforce domestic content requirements that shape competitive access for foreign equipment suppliers. The Yangtze River Delta concentrates manufacturing scale for transformer core steel and winding assemblies serving both domestic and export markets.
Germany
Transmission system operators pilot SF6-free gas-insulated switchgear at 145 kV and above under EU F-Gas Regulation compliance timelines. Grid hardening mandates compress replacement cycles for aging infrastructure inherited from reunification-era networks. Bavaria and North Rhine-Westphalia anchor industrial demand for high-reliability substation upgrades serving automotive and chemical manufacturing clusters.
India
Central Electricity Authority targets and state-level renewable purchase obligations drive greenfield substation construction across Rajasthan, Gujarat, and Tamil Nadu. The PLI scheme for power transmission equipment incentivizes domestic manufacturing capacity for high-voltage transformers. Rajasthan's solar parks require collection substations capable of aggregating gigawatt-scale generation from dispersed photovoltaic arrays.
Japan
METI grid modernization programs prioritize earthquake-resilient substation designs for the Tokyo-Osaka industrial corridor. Aging infrastructure replacement concentrates in Tohoku and Kyushu regions where 2011 tsunami damage accelerated depreciation schedules. Semiconductor fabrication clusters in Kyushu demand premium power quality specifications that justify advanced control system investments.
Electric Substation Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with manufacturing scale and digital platform capabilities defining separation. The upper tier commands high-voltage direct current and interconnector projects where technical complexity erects durable barriers. Strategic archetypes include transformer-scale manufacturers, digital substation platform vendors, and SF6-free switchgear pioneers. Competitive moves center on manufacturing capacity expansion for core steel and copper winding throughput, plus IEC 61850-compliant software convergence.
Among integrated European energy technology groups, Siemens Energy and ABB occupy positions anchoring distinct competitive vectors. Siemens Energy leverages transformer manufacturing scale to anchor European grid upgrade cycles, while ABB represents the high-voltage direct current interconnector specialization. Hitachi Energy sits within the digital platform tier, exemplifying protection and control software integration.
| Leading Market Players |
|---|
| ABB |
| Eaton Corporation |
| Hitachi Energy |
| Toshiba Energy Systems & Solutions Corporation |
| Mitsubishi Electric |
| Siemens Energy |
| Schneider Electric |
| Hyosung |
| GE Vernova |
| Others |
Cost & Logistics Intelligence
CE marking under MDR and EU F-Gas Regulation convergence gates both equipment qualification and price differentiation, forcing vendors to absorb recertification costs while tiering offerings by compliance tier and field-proven reliability.
Pricing Analysis
Long-term offtake agreements dominate transformer procurement as utilities lock core steel and winding copper throughput amid raw material volatility. Price differentiation rests on IEC 61850 certification tier and geographic delivery logistics, with SF6-free switchgear commanding premiums over conventional GIS. Cost compression in standard outdoor installations intensifies as Chinese manufacturers expand export capacity. Industrial data center buyers show lowest price sensitivity, prioritizing deployment speed over unit economics.
Supply Chain Analysis
Strategic stockpiling of grain-oriented electrical steel and copper cathode supersedes just-in-time preferences as lead time volatility ripples through transformer manufacturing. Supply concentrates in China, India, and Germany for core steel lamination and winding assemblies. The chain draws from Australian iron ore, Chilean copper concentrate, and Japanese precision steel rolling. Single-source vulnerability in ultra-high-voltage transformer cores creates structural risk. Distribution runs through OEM-direct channels for major components and system integrators for control bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled substation engineering talent is collapsing faster than knowledge transfer mechanisms can replenish, concentrating value capture among incumbents with captive training pipelines and digital platform architectures that reduce labor dependency.
For Market Incumbents: Consolidate manufacturing scale in transformer core steel and winding copper to anchor procurement relationships against emerging Chinese export competition. Deepen backward integration into grain-oriented electrical steel through offtake agreements with Japanese and Korean rolling mills. Capture digital substation platform share by accelerating IEC 61850-compliant software convergence before component specialists can bridge the gap. For New Entrants and Emerging Players: Differentiate on modular containerized formats where deployment speed outweighs unit cost optimization, targeting remote renewable integration sites in Rajasthan and Texas ERCOT zones. Penetrate the SF6-free switchgear segment through vacuum interrupter designs at 145 kV and above, where European utilities under EU F-Gas Regulation pressure seek alternatives with limited incumbent field history. Pursue direct OEM contracting with data center operators bypassing traditional utility procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital substation platforms as software R&D scales displace hardware-centric margin structures. Target acquisition profiles should emphasize vendors with integrated protection and control software stacks rather than component specialists facing commoditization. Watch FERC Order 2023 interconnection queue processing velocity as the signal indicating whether grid hardening investment sustains or compresses replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Transformer manufacturing expansion in India under PLI scheme absorbs regional renewable generation growth. |
| Backward Integration | Captive core steel supply agreements insulate against grain-oriented electrical steel price volatility. |
| Technology Licensing | SF6-free vacuum interrupter designs transfer to European utilities under EU F-Gas Regulation compliance timelines. |
| Vertical Integration into Storage | Integrated substation-plus-battery packages serve data center operators in Virginia's Northern Virginia cluster. |
| Green Certification Program | IEC 61850 compliance certification differentiates digital platform vendors from electromechanical component suppliers. |
Research Approach
The analysis maps transformer, switchgear, circuit breaker, and control system segments, each validated through utility planning officers, EPC contractors, OEM procurement teams, and grid operators. Primary fieldwork combined with secondary validation from FERC filings, EIA transmission project databases, IEA grid investment reports, and Central Electricity Authority targets. Bottom-up equipment shipment tracking and top-down infrastructure spending analysis triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework models component type, application use case, end-user procurement authority, and installation format dimensions. CAGRs derive from segment-level growth rate blending weighted by installed base turnover and greenfield construction pipelines. Forecast inputs include interconnection queue volumes under FERC Order 2023 and renewable capacity addition targets across India and China.
The analysis sits within stated boundaries; outcomes outside sustained grid hardening mandate execution or accelerated SF6 phase-down timelines would require recalibration. Forecasts reflect assumptions about skilled labor attrition rates and raw material supply elasticity. Revision becomes warranted when transformer core steel lead time volatility crosses thresholds that compress project commissioning windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Transformer Oil Testers Market