
 Micro Mobility Battery PACK Market | 2026-2036
Micro Mobility Battery PACK Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Mobility Battery PACK Market Insights
South Korea is fragmenting as battery makers and vehicle OEMs compete for pack assembly dominance. Tian Neng leverages its lead-acid legacy to anchor lithium-ion transitions in Asian markets. Bosch eBike Systems differentiates through proprietary drive-battery integration for premium European e-bikes. Segway-Ninebot controls shared mobility deployment volumes through captive battery specifications for rental fleets.
Micro Mobility Battery PACK denotes an integrated electrochemical energy storage system comprising cells, battery management circuitry, thermal management layers, and mechanical enclosure, typically rated between 36V and 72V with capacities from 250Wh to 2000Wh, engineered to power electric two-wheelers and light personal transport vehicles. Lithium-ion chemistry dominates installed volume due to superior energy density and cycle life versus lead-acid alternatives, though nickel-metal hydride retains niche presence in cost-sensitive replacement markets. Fast Charging technology commands premium positioning in delivery service applications where vehicle uptime directly correlates with route economics, while Swappable configurations are gaining structural traction in shared fleet models that prioritize asset utilization over individual ownership.
China's NMPA and SAMR enforce GB standards that mandate thermal runaway propagation resistance and BMS functional safety certification for domestic pack sales. The EU Green Deal and F-Gas Regulation are reshaping cell sourcing requirements by embedding carbon footprint disclosure into battery passport frameworks. Stakeholders must monitor how regional certification divergence affects cross-border pack interoperability and aftermarket service economics.
Market Dynamics
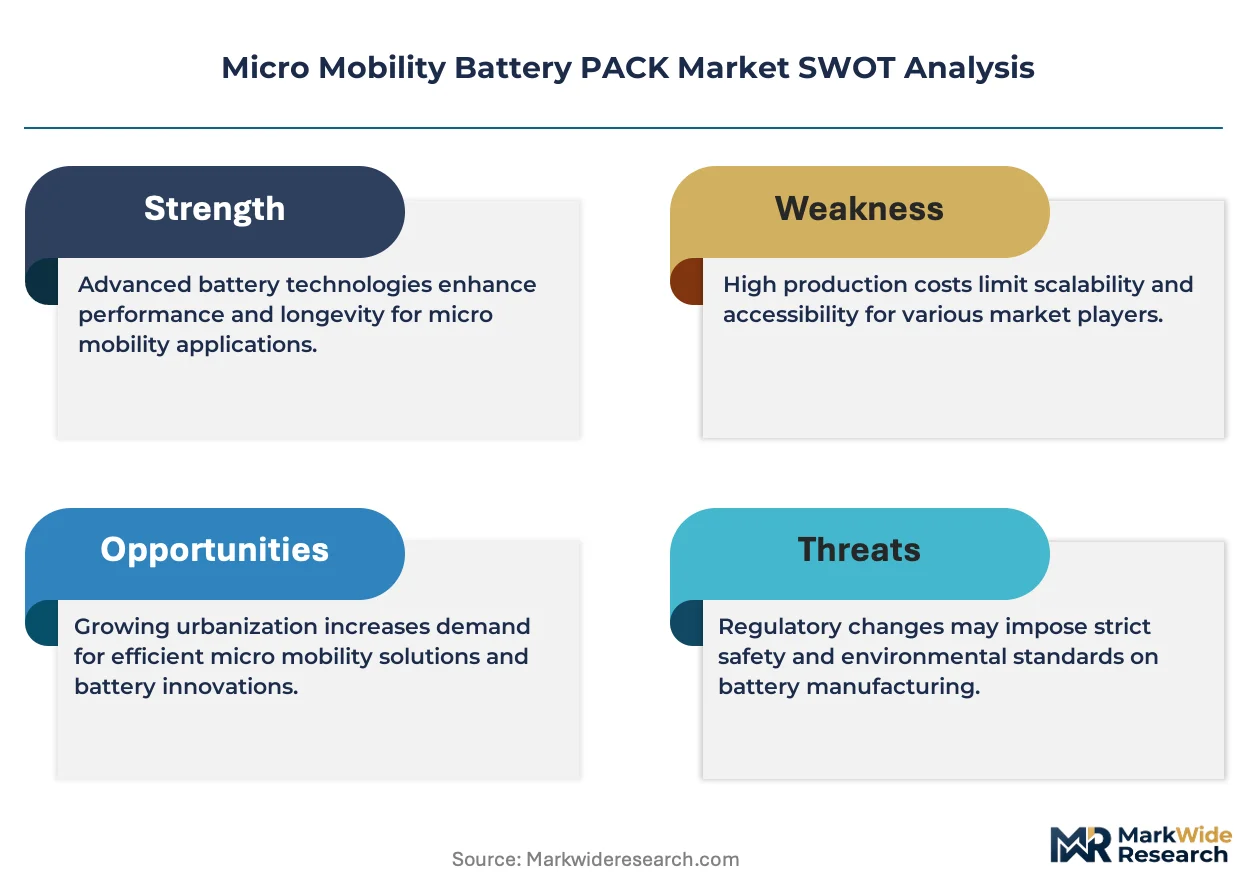
Swappable battery architectures are restructuring fleet economics in shared mobility, forcing pack suppliers to prioritize standardized form factors and rapid-swap mechanical interfaces over energy density optimization for private ownership models.
Growth Catalysts
- EU Battery Passport Mandate:Carbon footprint disclosure requirements under the EU Green Deal are accelerating pack traceability investments across European supply chains, creating certification premiums for compliant suppliers.
- Last-Mile Delivery Electrification:Southeast Asian logistics operators are consolidating procurement around 48V-60V swappable systems to maximize vehicle utilization during peak delivery windows.
- GB Standard Thermal Runaway Resistance:China's NMPA and SAMR enforcement of propagation-resistant cell designs is elevating technical barriers that favor established pack integrators with certified BMS platforms.
Market Restraints
- Lithium Carbonate Volatility:Cathode material cost swings are compressing gross margins for pack assemblers lacking long-term offtake agreements with Chinese refiners.
- Cell Supply Concentration:Tier-one cylindrical and prismatic cell output clusters in China's Yangtze River Delta and South Korea's Gyeonggi corridor, exposing downstream pack makers to geographic supply shocks.
- Lead-Acid Replacement Inertia:Price-sensitive informal repair networks in South Asian markets continue sourcing flooded lead-acid packs for retrofit applications, delaying lithium-ion penetration in the replacement segment.
Strategic Opportunities
- Vietnam Manufacturing Corridor:Low-cost pack assembly capacity in Binh Duong and Dong Nai provinces is capturing contract manufacturing demand from regional last-mile fleet operators seeking tariff-advantaged sourcing.
- Second-Life Stationary Storage:Retired micro-mobility packs with 70-80% remaining capacity are finding secondary applications in telecom backup and residential solar buffering, extending value extraction cycles.
- F-Gas Regulation Thermal Management:EU restrictions on fluorinated greenhouse gases in cooling systems are opening design space for phase-change material and liquid-cooled alternatives in premium European e-bike segments.
Industry Challenges
- BMS Firmware Talent Scarcity:Functional safety engineering expertise for ISO 26262-compliant battery management systems remains concentrated among automotive-tier suppliers, constraining pack maker hiring pipelines.
- Multi-Certification Parallel Tracks:Simultaneous pursuit of China's GB/T, Europe's CE/MDR, and UN 38.3 transport testing is extending product launch timelines by 8-14 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Mobility Battery PACK Market |
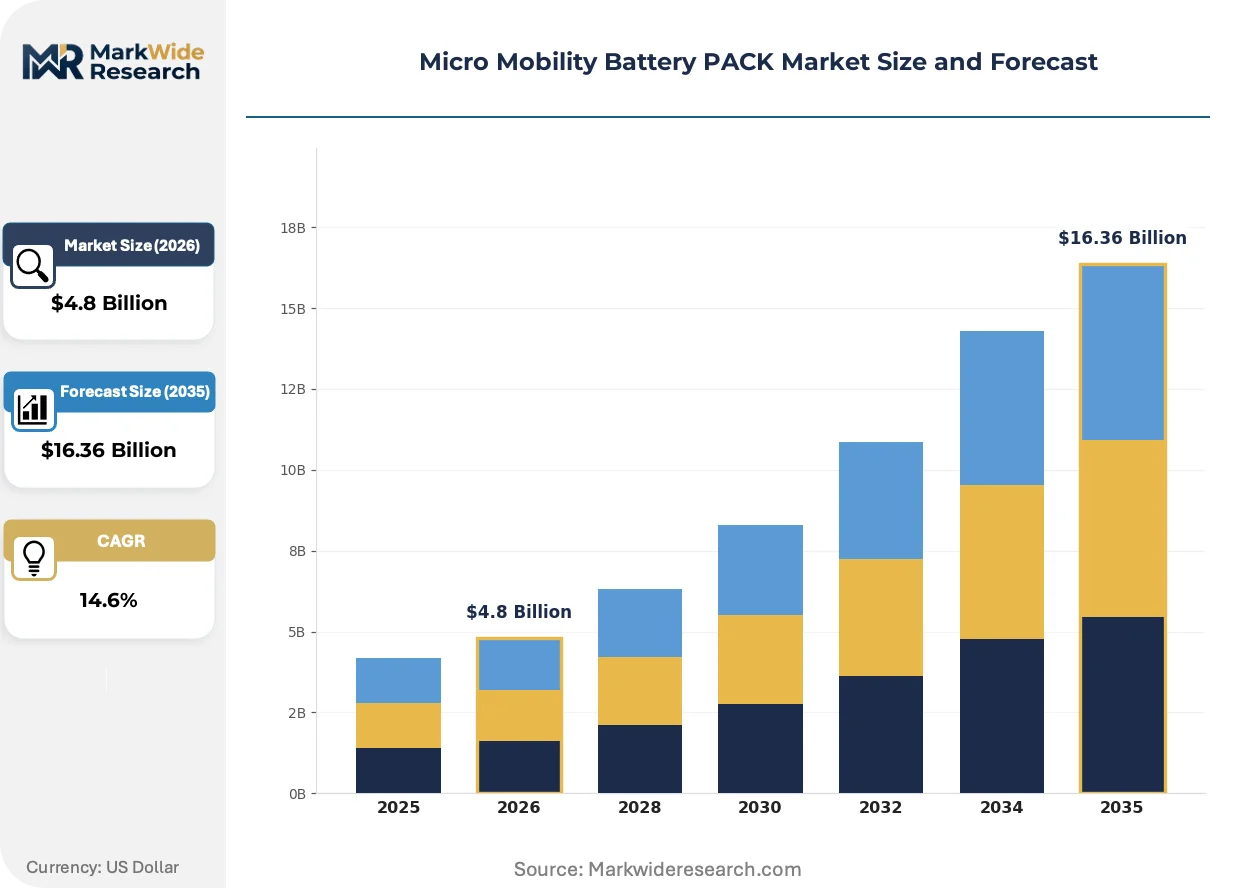
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lithium Polymer, Lead Acid, Nickel-metal Hydride Technology: Fast Charging, Swappable, Regenerative, Standard Charging End User: E-scooters, E-bikes, E-motorcycles, Delivery Services Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Tian Neng, PHYLION, Simplo, Bosch eBike Systems, Yadea Technology Group, Segway-Ninebot, Xiaomi, Giant Manufacturing, Gogoro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Mobility Battery PACK Market Trends and Innovations
Digital intelligence layers are penetrating electrochemical hardware, creating data-enabled differentiation in fleet management and predictive maintenance services that reshape how pack value is captured across ownership models.
Silicon-anode blending is digitizing cell-level monitoring requirements. Higher volumetric expansion rates versus graphite necessitate granular voltage and temperature telemetry that legacy BMS architectures cannot support. Fleet operators deploying these chemistries are mandating over-the-air diagnostic integration, compressing supplier development cycles for connected pack platforms.
The EU F-Gas Regulation is reshaping thermal design priorities for European-sold packs. Restrictions on hydrofluorocarbon-based cooling systems are pushing manufacturers toward dielectric fluid immersion and thermally conductive potting compounds. Premium e-bike OEMs in Germany and the Netherlands are fastest to adopt, driven by sustainability procurement scorecards from corporate fleet buyers.
Shared fleet operators are unbundling battery ownership from vehicle procurement. Rental platforms in Barcelona, Paris, and Berlin are negotiating power-as-a-service contracts where cell degradation risk transfers to pack suppliers in exchange for guaranteed swap-network availability. This model concentrates volume among integrators with captive service infrastructure, marginalizing pure hardware vendors.
Micro Mobility Battery PACK Market Segmentation
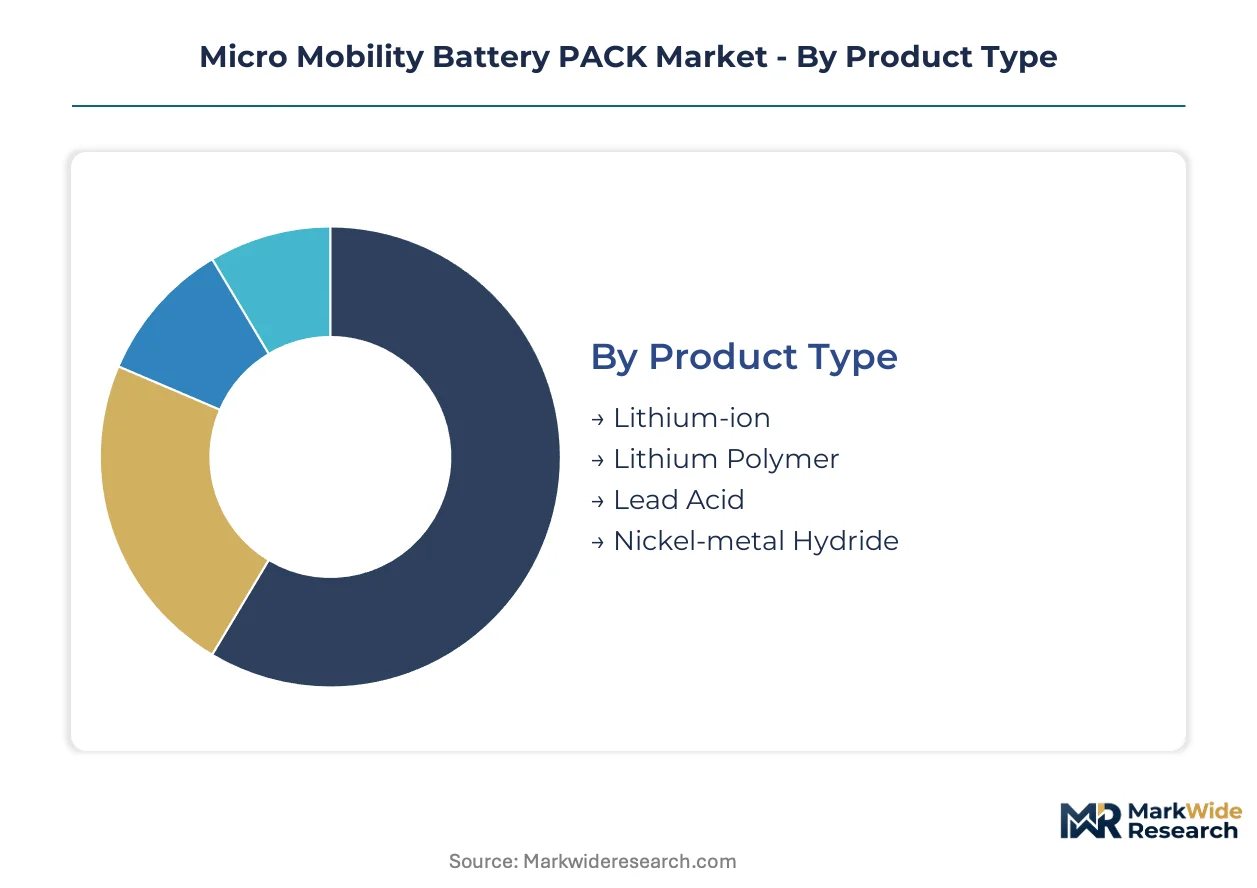
Micro mobility battery pack segmentation reveals how chemistry choices, charging architectures, and capacity tiers map to distinct ownership economics across private and fleet deployment models. Understanding these boundaries exposes where supplier capabilities align with buyer procurement priorities.
Product Type:
Mature chemistries dominate installed base while emerging formulations capture design-in momentum for next-generation platforms.
- Lithium-ion:Cylindrical and prismatic cell configurations deliver 150-250 Wh/kg energy density with 800-1200 cycle life, forming the backbone of premium e-bike and e-motorcycle platforms. Demand concentrates in Germany's corporate fleet procurement channels where EU Battery Passport traceability requirements favor established cell supply partnerships with Korean and Chinese manufacturers.
- Lithium Polymer:Pouch cell architectures enable flexible form factors and 20% weight reduction versus cylindrical equivalents, penetrating foldable e-bike and compact e-scooter designs. Adoption accelerates in Japanese and South Korean urban commuter segments where portability specifications override absolute cycle life metrics.
- Lead Acid:Flooded and AGM variants persist in Southeast Asian replacement markets and low-speed electric three-wheelers.
- Nickel-metal Hydride:Retains niche presence in temperature-extreme applications and legacy hybrid retrofits.
Lithium-ion retains volume leadership; Lithium Polymer holds the steepest expansion curve.
Technology:
Charging architecture selection directly determines fleet utilization rates and asset ownership models.
- Fast Charging:80% state-of-charge recovery in 30-45 minutes requires silicon-carbide power electronics and enhanced thermal management with dielectric fluid circulation. Deployment concentrates in Vietnam and Indonesia's delivery service corridors where route downtime directly compresses driver earnings.
- Swappable:Standardized 48V-60V pack formats with mechanical auto-ejection interfaces enable sub-60-second exchanges, restructuring capital deployment toward battery-as-a-service subscriptions. European shared mobility operators in Paris and Berlin are consolidating procurement around captive swap networks that transfer degradation risk to pack suppliers.
- Regenerative:Captures braking energy through bidirectional inverters, extending range 8-15% in stop-and-go urban environments.
- Standard Charging:Overnight AC charging persists in private ownership segments with predictable daily mileage patterns.
Swappable configurations are gaining structural traction fastest; Standard Charging maintains the largest installed base.
End User:
Application-specific duty cycles and regulatory exposure reshape pack specification priorities.
- Delivery Services:12-16 hour daily utilization with 100-200 km range requirements drives 60V-72V high-cycle configurations with active liquid cooling. Procurement centralizes in Bangkok, Ho Chi Minh City, and Jakarta where platform operators negotiate power-as-a-service contracts bundling hardware, swap infrastructure, and cell replacement guarantees.
- E-scooters:Shared fleet models prioritize IP67 ingress protection and vandal-resistant enclosures over energy density optimization.
- E-bikes:Premium European segments demand EU F-Gas Regulation-compliant thermal management and carbon footprint disclosure documentation.
- E-motorcycles:Higher voltage architectures and sustained discharge rates require automotive-grade BMS functional safety certification.
Delivery Services commands the most aggressive procurement expansion; E-bikes sustains the highest average selling prices.
Capacity:
Energy storage scale segments align with range anxiety thresholds and vehicle weight classification boundaries.
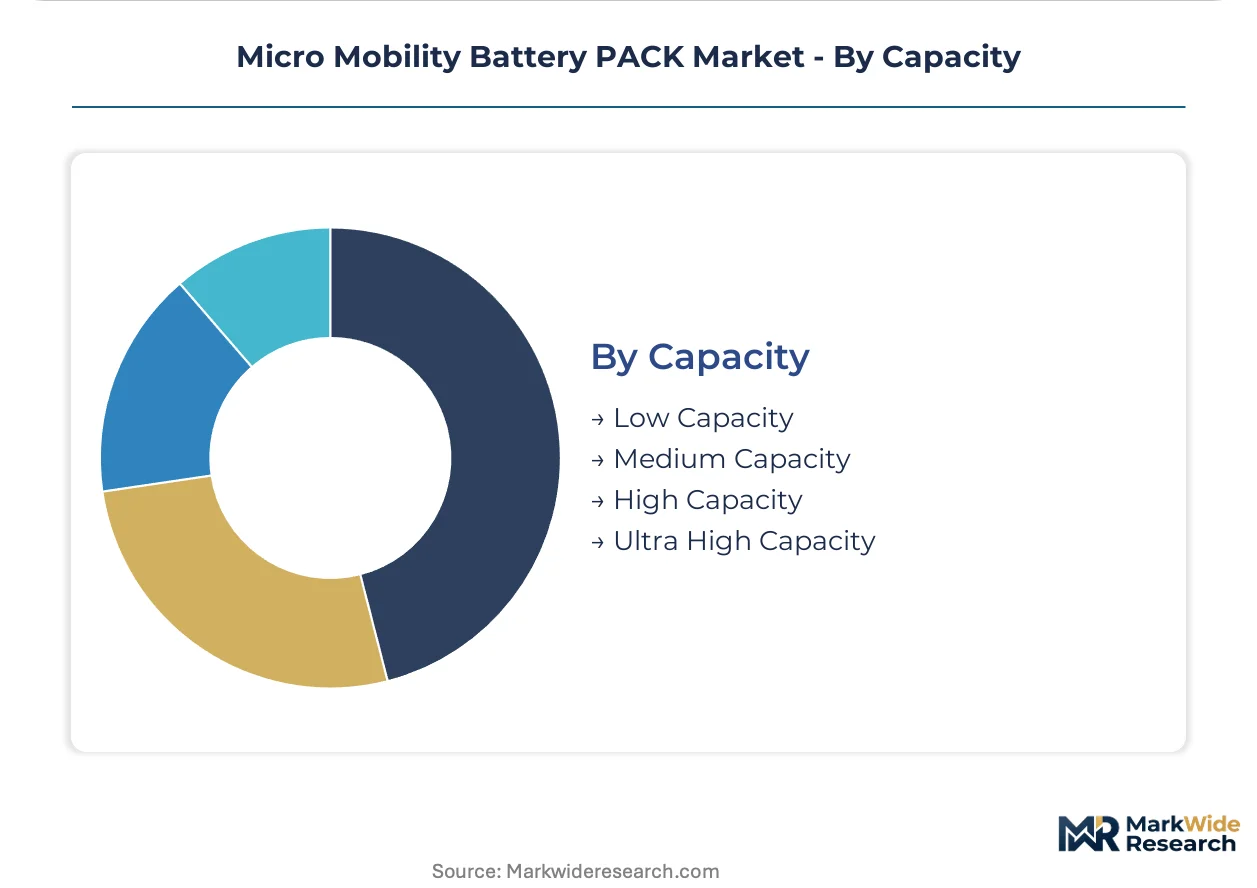
- High Capacity:1000-2000Wh configurations enable 80-120 km range in Class L3e electric motorcycles and cargo e-bikes, requiring reinforced chassis mounting and crash-resistant enclosure designs. Demand clusters in Germany's commercial delivery sector and China's premium consumer e-motorcycle replacement market.
- Medium Capacity:500-1000Wh balances range and weight for urban commuter e-bikes.
- Low Capacity:250-500Wh serves last-mile shared scooters and compact foldable bikes.
- Ultra High Capacity:Exceeds 2000Wh for heavy cargo applications and extended-range touring motorcycles.
High Capacity segments capture the steepest value growth; Medium Capacity maintains the broadest addressable volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA and SAMR enforce GB standards that mandate thermal runaway propagation resistance, anchoring the dominant geography where cell certification requirements are tightening fastest.
Germany
Corporate fleet procurement channels for premium e-bikes concentrate demand in Baden-Württemberg and Bavaria. The EU Green Deal and F-Gas Regulation embed carbon footprint disclosure into battery passport frameworks. Stuttgart-based OEMs are fastest to adopt dielectric fluid immersion cooling for sustainability scorecards.
China
Yangtze River Delta cell production clusters supply cylindrical and prismatic configurations for domestic pack integrators. GB/T functional safety certification elevates technical barriers favoring established BMS platforms. Shenzhen and Dongguan manufacturing corridors dominate low-cost pack assembly for Southeast Asian export markets.
Vietnam
Last-mile delivery operators in Ho Chi Minh City and Hanoi consolidate procurement around 48V-60V swappable systems. Binh Duong and Dong Nai provinces capture contract manufacturing demand seeking tariff-advantaged sourcing. Regional logistics platforms negotiate power-as-a-service contracts bundling hardware and swap infrastructure.
South Korea
Gyeonggi corridor cell output exposes downstream pack makers to geographic supply concentration risks. MFDS-equivalent safety standards and automotive-tier BMS expertise constrain hiring pipelines for functional safety engineers. Seoul Capital Area battery makers compete with vehicle OEMs for pack assembly dominance.
France
Shared mobility operators in Paris negotiate battery-as-a-service contracts transferring degradation risk to pack suppliers. ANSM-aligned product safety frameworks intersect with EU Battery Passport traceability investments. Île-de-France rental platforms prioritize captive swap networks that marginalize pure hardware vendors.
Micro Mobility Battery PACK Market Competitive Landscape
Established cell suppliers and captive fleet integrators split the market between component-scale efficiency and service-network control. The vendor base concentrates around three strategic archetypes: legacy lead-acid converters leveraging distribution footprints, automotive-tier electronics specialists commanding BMS functional safety certification, and mobility-platform operators with captive battery specifications. Dominant competitive moves include backward integration into cell supply partnerships and geographic expansion of swap-network infrastructure to capture power-as-a-service subscriptions.
Within the legacy converter archetype, Tian Neng anchors lithium-ion transitions through established Asian distribution channels. Among platform-captive integrators, Segway-Ninebot occupies a position controlling shared mobility deployment volumes through rental fleet specifications. On the automotive-electronics tier, Bosch eBike Systems exemplifies premium European positioning through drive-battery integration specialization.
| Leading Market Players |
|---|
| Tian Neng |
| PHYLION |
| Simplo |
| Bosch eBike Systems |
| Yadea Technology Group |
| Segway-Ninebot |
| Xiaomi |
| Giant Manufacturing |
| Gogoro |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Rotterdam freight corridors transmit lithium carbonate volatility directly into European pack landed costs, compressing margins for assemblers without Yangtze River Delta cell partnerships while amplifying price spreads between certified and uncertified suppliers.
Pricing Analysis
Asian-European price spreads of 15-25% separate GB/T-certified packs from CE/MDR-compliant equivalents, with EU Battery Passport traceability investments and F-Gas Regulation thermal management compliance driving premium tiers. Cost compression in Southeast Asian contract manufacturing runs through lithium carbonate spot exposure and informal lead-acid replacement networks. Delivery service operators in Vietnam and Indonesia exhibit highest price sensitivity due to thin per-route economics, while German corporate fleet buyers accept sustainability premiums for carbon-disclosed supply chains.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates pack assembly relocation decisions as Binh Duong and Dong Nai provinces capture contract manufacturing seeking duty-advantaged export channels. Cell output clusters in China's Yangtze River Delta and South Korea's Gyeonggi corridor anchor cathode material dependencies on Indonesian nickel and Chilean lithium. Single-source vulnerability concentrates in cylindrical cell supply from Korean tier-one producers. Distribution runs through captive swap-network operators in European shared mobility and platform-negotiated power-as-a-service contracts in Southeast Asian logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service subscriptions and swap-network availability guarantees are expanding faster than hardware unit sales, redefing pack economics around recurring revenue capture rather than transactional margin extraction.
For Market Incumbents: Entrench swap-infrastructure control in European shared mobility corridors where Segway-Ninebot and Gogoro have established captive specifications, while securing long-term offtake agreements with Yangtze River Delta cell producers to defend against lithium carbonate volatility. ISO 26262 BMS certification investment is the critical lever for automotive-tier expansion. For New Entrants and Emerging Players: South Asian lead-acid replacement markets present the most penetrable white-space opportunity, particularly informal repair networks in Bangladesh and Pakistan where lithium-ion penetration lags due to price sensitivity and certification gaps. A localized assembly partnership with Binh Duong contract manufacturers enables tariff-advantaged positioning without upstream cell supply commitments. For Investors and Strategic Acquirers: Pack integrators with captive BMS firmware capabilities and established GB/T-CE dual certification tracks represent the priority acquisition archetype, as multi-certification parallel tracks extend launch timelines and constrain functional safety talent pipelines. Watch for consolidation signals when swap-network operators in Paris and Berlin begin bundling hardware procurement with infrastructure availability guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Swap-Network Infrastructure Expansion | Captive battery-as-a-service contracts in European shared mobility transfer degradation risk to suppliers. |
| Dual Certification Investment | GB/T and CE/MDR parallel tracks accelerate cross-border pack interoperability for Southeast Asian exporters. |
| Cell Supply Partnership | Yangtze River Delta offtake agreements insulate pack assemblers from lithium carbonate spot volatility. |
| Second-Life Storage Integration | Retired 70-80% capacity packs extend value extraction into telecom backup and residential solar buffering. |
| Dielectric Thermal Management | F-Gas Regulation compliance opens premium European e-bike segments for sustainability-scorecard-driven procurement. |
Research Methodology
A spread of perspectives from fleet operations directors, pack assembly plant managers, BMS firmware engineers, and cell procurement leads converged on the working assumptions, validated against customs trade data, GB/T and CE certification registries, EU Battery Passport framework documents, and shared mobility operator procurement disclosures. Bottom-up volume triangulation across chemistry, capacity, and charging architecture segments was cross-checked with top-down market sizing.
Demand-supply balance modeling across the projection horizon incorporated vehicle deployment forecasts, swap-network penetration curves, and cell capacity expansion announcements. Segmentation dimensions included chemistry type, charging technology, end-use application, capacity tier, and regional regulatory cluster. CAGRs were derived from installed base growth, replacement cycle compression, and fleet electrification acceleration. Industry-specific inputs captured thermal runaway certification timelines and F-Gas Regulation compliance transitions.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, freight corridor rates, or EU carbon border adjustment mechanisms would shift the trajectory. Forecasts reflect documented assumptions about cell supply concentration, certification harmonization progress, and swap-network operator consolidation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Japan Mobile Battery Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Zinc Carbon Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
VRLA Batteries Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Utility Battery Market
Batteries
East Africa Battery Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Power Tool Batteries Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Primary Battery Market