
 Middle-East Smart Transformer Market | 2026-2036
Middle-East Smart Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Smart Transformer Market Foresight
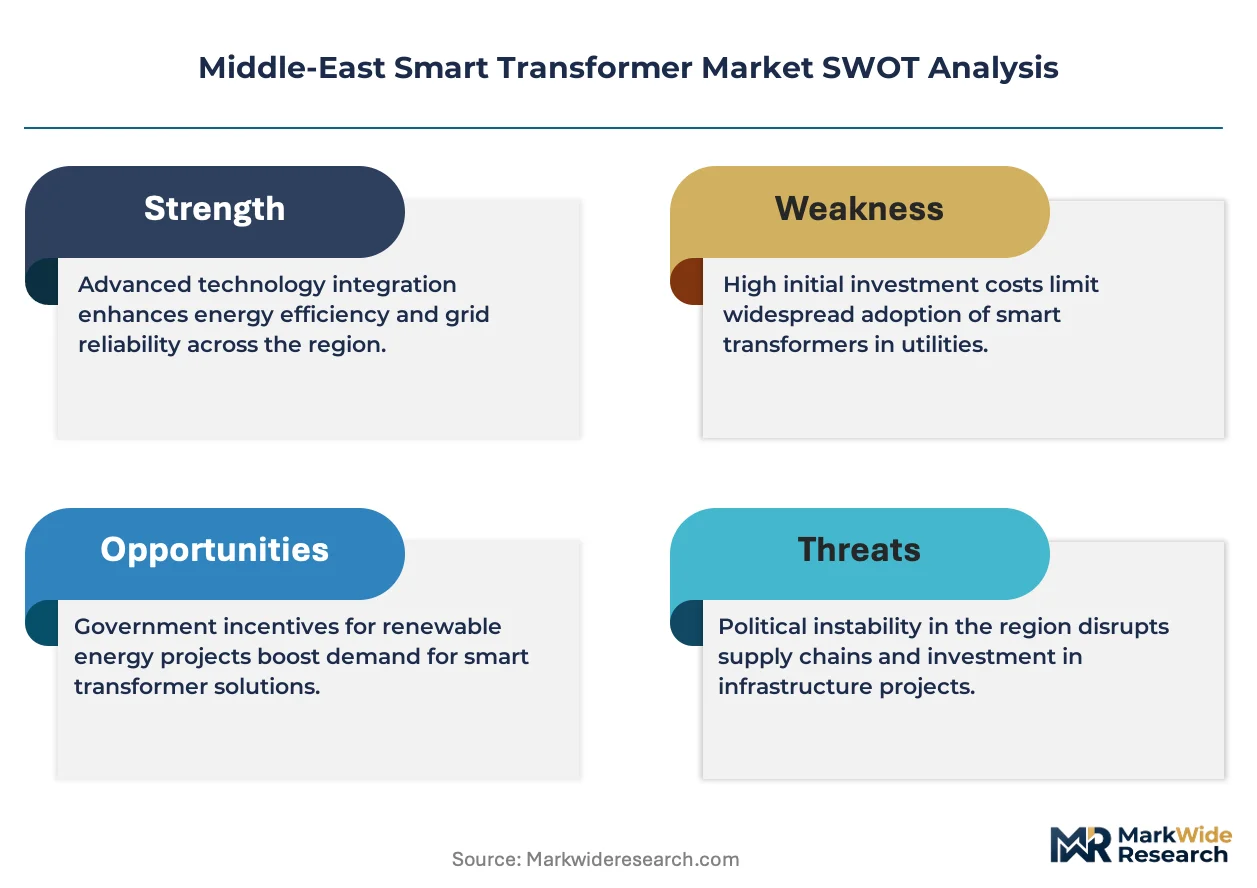
Utility buyers are reorganizing procurement priorities as renewable integration reshapes Middle-East grid architectures. Siemens Energy leverages its digital monitoring portfolio to anchor large-scale utility contracts across the Gulf Cooperation Council states. ABB competes through advanced cooling systems designed for desert-climate thermal stress. Schneider Electric extends its IoT integration capabilities to industrial automation segments seeking real-time load balancing.
Smart transformers incorporate solid-state power electronics, embedded sensors, and bidirectional communication interfaces to enable autonomous voltage regulation and fault isolation. These devices serve critical functions in stabilizing variable renewable output and protecting downstream infrastructure from harmonic distortion. Multi-functional units command premium positioning due to their combined step-up and conditioning capabilities in solar farm interconnections. Modular designs represent the fastest-growing product configuration, allowing Gulf utilities to scale capacity incrementally alongside phased renewable buildouts.
Saudi Arabia's national regulator enforces grid codes requiring distributed intelligence at substation level, while the UAE's central electricity authority mandates IoT-ready equipment for new transmission assets. CE marking alignment remains essential for European-origin suppliers serving Gulf markets. Stakeholders must weigh technology transfer requirements against intellectual property exposure as local content rules tighten across the region.
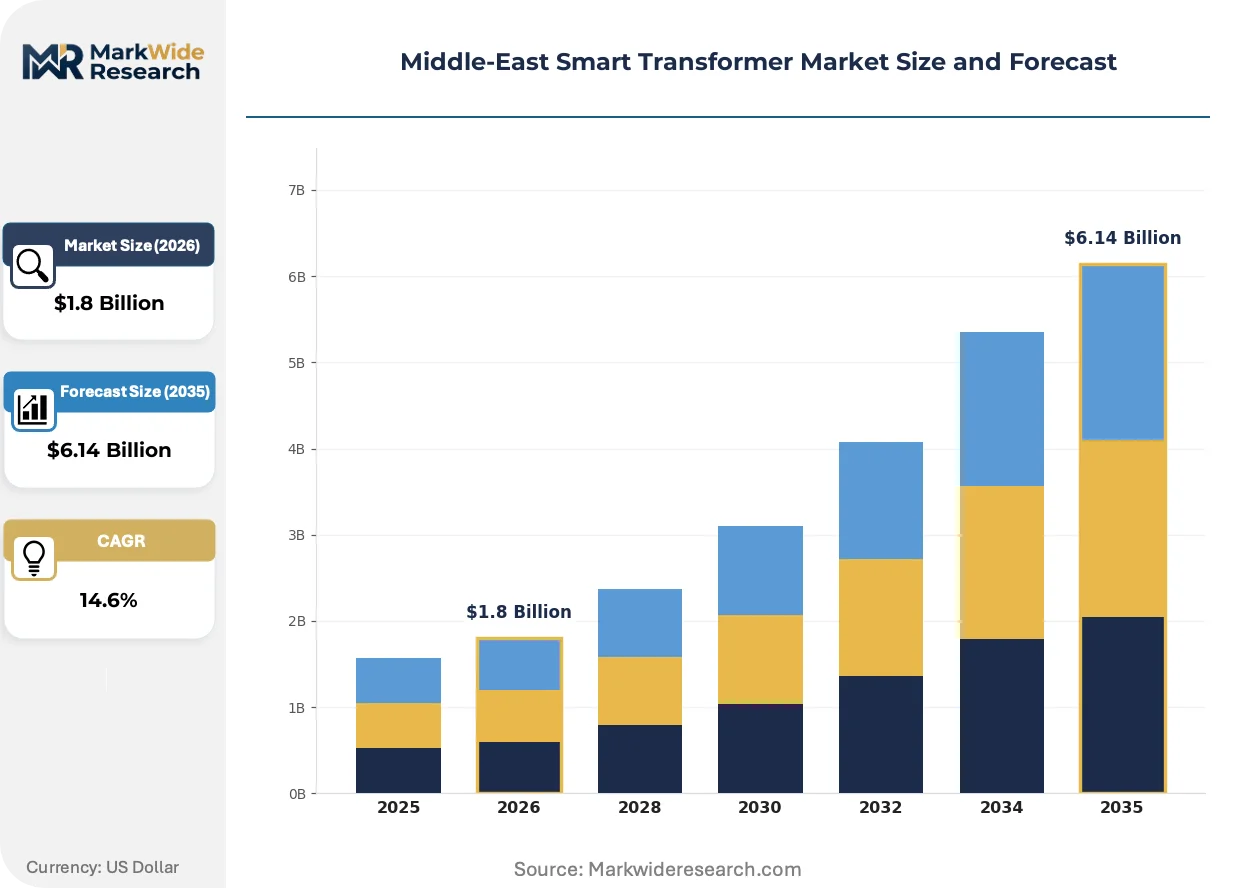
Market Dynamics
Utility-scale solar and wind buildouts across the Gulf Cooperation Council states are forcing distribution utilities to replace passive transformers with intelligent, sensor-equipped units capable of autonomous voltage regulation and bidirectional power flow management.
Growth Catalysts
- Saudi Arabia's Grid Code Mandates:The national electricity regulator requires distributed intelligence at substation level, compelling utilities to procure IoT-ready transformers for all new transmission assets.
- Desert-Climate Thermal Stress:Advanced liquid-immersed and dry-type cooling systems designed for ambient temperatures exceeding 50°C unlock reliable operation in Gulf solar farm interconnections.
- Modular Capacity Scaling:Phased renewable buildouts favor incremental deployment configurations that match transformer capacity to generation commissioning schedules without stranding capital.
Market Restraints
- Silicon Carbide Semiconductor Costs:Solid-state power electronics depend on SiC substrates where supply concentrates among Japanese and US wafer manufacturers, creating input price volatility.
- Local Content Requirements:Technology transfer mandates across Gulf states expose foreign suppliers to intellectual property leakage risks in exchange for project eligibility.
- CE Marking Alignment Costs:European-origin equipment must undergo redundant conformity assessment for Gulf-specific environmental and electromagnetic compatibility standards.
Strategic Opportunities
- Industrial Automation Integration:Real-time load balancing capabilities converge with Schneider Electric's IoT platforms to capture petrochemical and desalination plant retrofits.
- Kuwait and Oman Expansion:Underpenetrated markets with nascent renewable targets present first-mover advantages for suppliers establishing local assembly partnerships.
- Harmonic Conditioning Bundles:Multi-functional units combining step-up transformation with active filtering command premium positioning in solar farm interconnection tenders.
Industry Challenges
- Power Electronics Expertise Scarcity:Gulf utilities lack sufficient field engineers trained in solid-state transformer maintenance and firmware diagnostics.
- Legacy SCADA Integration:Brownfield substations require protocol translation layers to connect embedded sensor networks with existing control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Smart Transformer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-up, Step-down, Multi-functional, Modular Application: Renewable Energy, Smart Grid, Industrial Automation, Power Distribution End User: Utilities, Industrial Sector, Commercial Establishments, Residential Users Technology: Digital Monitoring, IoT Integration, Advanced Cooling, Smart Controls |
| Companies Covered | Siemens Energy, ABB, Schneider Electric, GE Vernova, alfanar Group, Eaton Corporation, General Electric, SGB-SMIT, Abaft Middle East Transformer Ind. LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Smart Transformer Market Shifts & Advancements
Digital monitoring platforms and solid-state power electronics are reconfiguring how Gulf utilities specify transformer procurement, shifting evaluation criteria from nameplate efficiency to real-time operational visibility and predictive maintenance integration.
Solid-state transformer architectures employing silicon carbide power electronics are fragmenting the traditional electromagnetic transformer market by enabling autonomous voltage regulation without mechanical tap changers. Saudi Aramco and ACWA Power are piloting these units in solar farm interconnections where rapid response to irradiance fluctuations protects downstream inverters. The technology is compressing maintenance intervals and enabling bidirectional power flow that passive designs cannot achieve.
The UAE's central electricity authority now mandates IoT-ready equipment specifications for all new transmission assets, accelerating embedded sensor and communication module adoption. This policy compresses procurement timelines for suppliers lacking pre-certified digital platforms while creating compliance barriers for legacy manufacturers. Distribution utilities in Dubai and Abu Dhabi are restructuring tender evaluations to weight connectivity and remote diagnostics above capital cost alone.
Service contract unbundling is separating hardware supply from predictive analytics and firmware update subscriptions. EPC contractors and independent power producers now specify multi-year performance guarantees with embedded remote monitoring rather than traditional warranty terms. This shift is most visible in Saudi Arabia's renewable energy project company tenders, where bidders must demonstrate integrated digital service capabilities alongside equipment delivery.
Middle-East Smart Transformer Market Segmentation
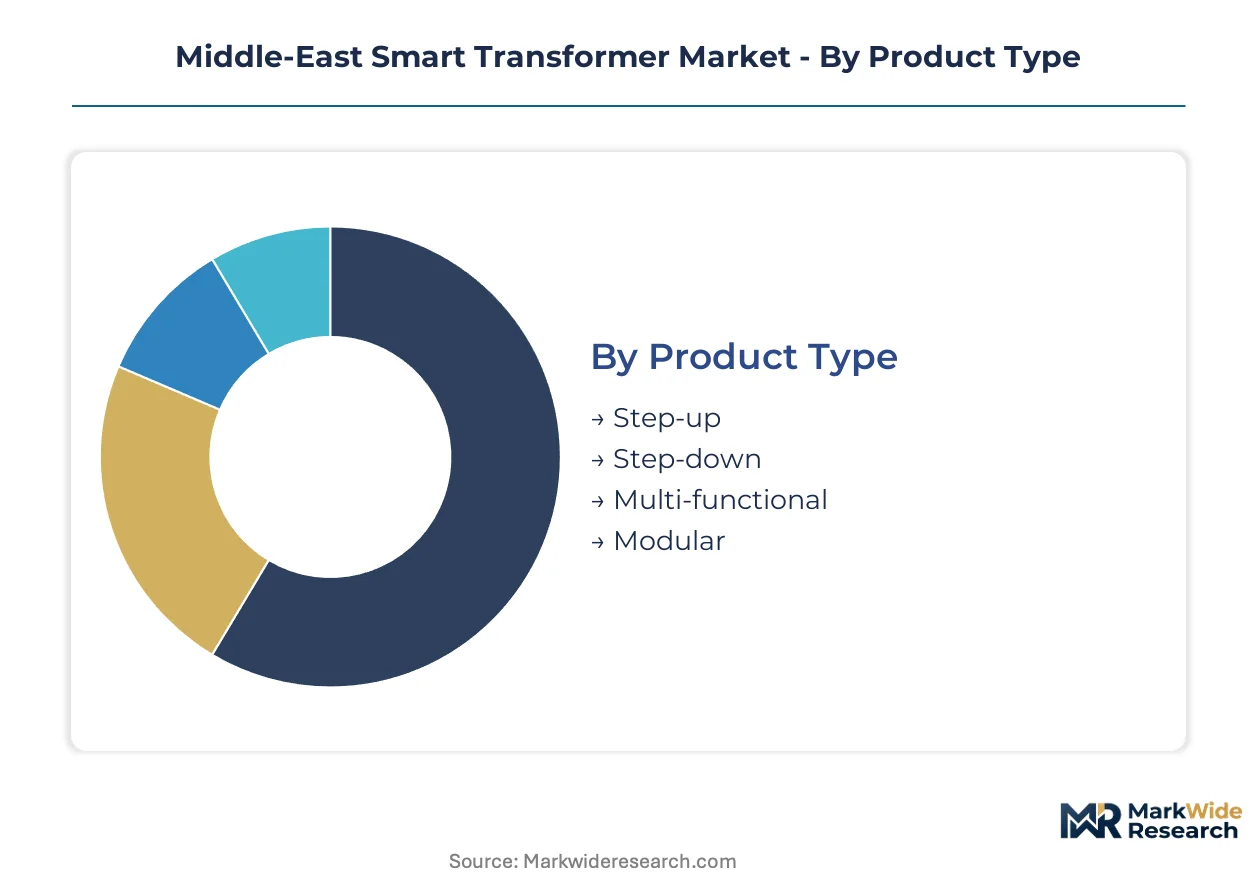
Smart transformer procurement across the Middle-East fragments across technical specifications, deployment contexts, and buyer sophistication. Saudi Arabia's grid code mandates and the UAE's IoT equipment standards reshape how each segment commands premium positioning versus commodity treatment.
Product Type:
Saudi Arabia's national electricity regulator mandates distributed intelligence at substation level, creating tiered compliance burdens that favor certain configurations over others.
- Step-up:Voltage elevation units for solar farm interconnections incorporate embedded sensors to stabilize fluctuating renewable output. Saudi Aramco and ACWA Power concentrate procurement in gigawatt-scale solar projects where rapid response to irradiance variations protects downstream inverters from harmonic distortion.
- Modular:Incremental capacity configurations allow Gulf utilities to scale transformer deployment alongside phased renewable commissioning schedules without capital stranding. Dubai and Abu Dhabi distribution utilities favor these units as they match equipment deployment to actual generation coming online.
- Step-down:Voltage reduction units for industrial feed and distribution endpoints.
- Multi-functional:Combined transformation and conditioning capabilities in single enclosures.
Established volume favors Step-up; emerging adoption favors Modular.
Application:
Cost tier differentiation separates mission-critical infrastructure from discretionary upgrades across Gulf Cooperation Council states.
- Renewable Energy:Solar and wind farm interconnections demand bidirectional power flow management and autonomous voltage regulation that passive transformers cannot provide. Gigawatt-scale projects in Saudi Arabia and the UAE command the highest specification tiers and longest performance guarantee terms.
- Smart Grid:Distribution network modernization incorporates real-time operational visibility and predictive maintenance integration. The UAE's central electricity authority mandates IoT-ready specifications that compress procurement timelines for certified suppliers.
- Industrial Automation:Petrochemical and desalination plant retrofits seek real-time load balancing converged with broader automation platforms.
- Power Distribution:Legacy grid infrastructure replacement with intelligent sensor-equipped units.
Capital deployment concentrates in Renewable Energy; regulatory compliance accelerates Smart Grid fastest.
End User:
Customer type determines procurement sophistication and service contract structure across the region.
- Utilities:State-owned distribution companies under Saudi Arabia's national regulator and the UAE's central electricity authority specify multi-year performance guarantees with embedded remote monitoring rather than traditional warranty terms. Tender evaluations now weight connectivity and remote diagnostics above capital cost alone.
- Industrial Sector:Petrochemical complexes and desalination facilities prioritize real-time load balancing integrated with existing automation architectures. Brownfield substations require protocol translation layers to connect embedded sensor networks with legacy SCADA systems.
- Commercial Establishments:Large-scale commercial developments seeking power quality management.
- Residential Users:Limited direct procurement; typically served through utility-managed distribution.
Procurement volume concentrates with Utilities; Industrial Sector shows steepest expansion trajectory as retrofit cycles accelerate.
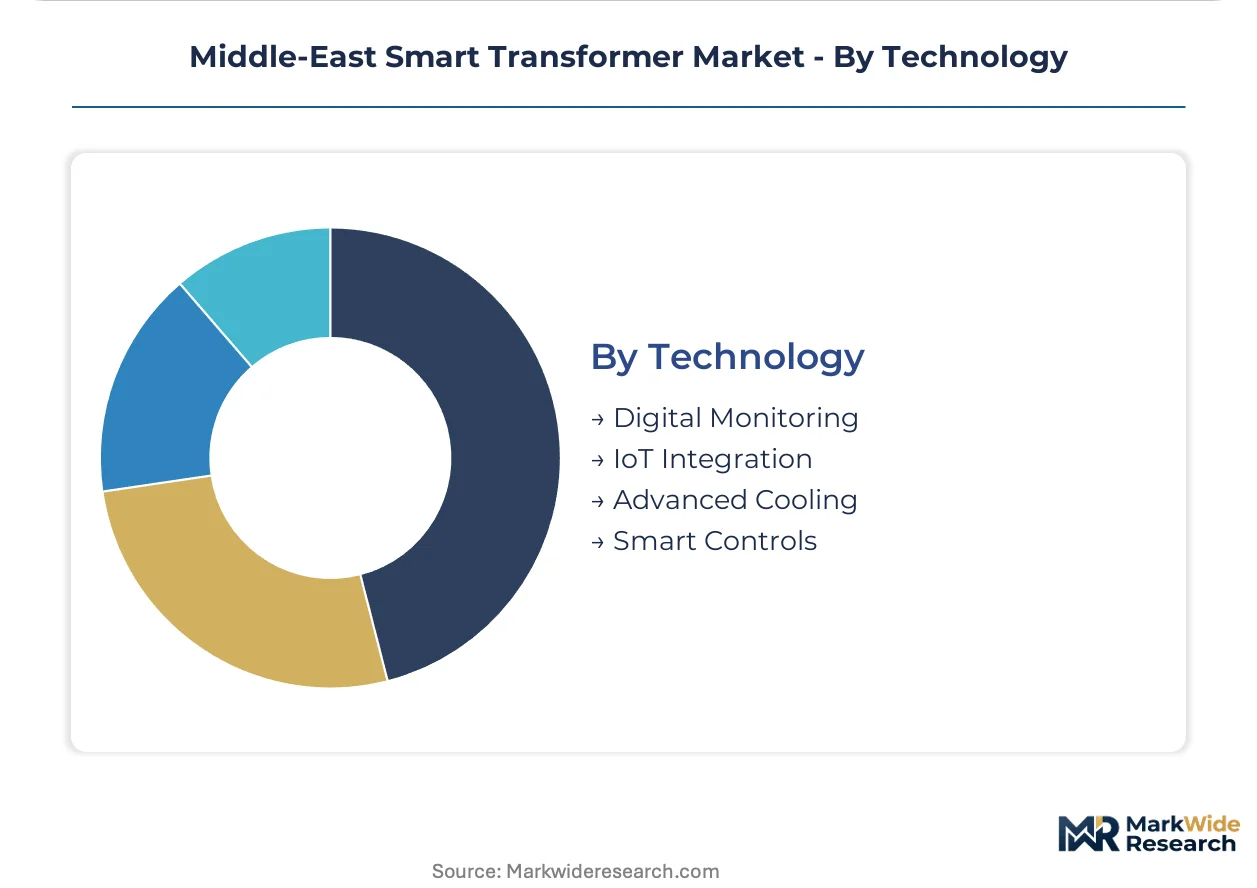
Technology:
Supply concentration in semiconductor substrates creates input cost volatility that reshapes technology adoption priorities.
- Digital Monitoring:Embedded sensor networks and communication modules enable autonomous fault isolation and predictive maintenance. Service contract unbundling now separates hardware supply from analytics subscriptions, visible in Saudi renewable energy tenders requiring integrated digital capabilities.
- Advanced Cooling:Liquid-immersed and dry-type systems engineered for ambient temperatures exceeding 50°C unlock reliable operation in Gulf desert climates. ABB competes through thermal stress designs purpose-built for solar farm interconnection environments.
- IoT Integration:Bidirectional communication interfaces connecting transformer assets to centralized control platforms.
- Smart Controls:Solid-state power electronics employing silicon carbide substrates for autonomous voltage regulation without mechanical tap changers.
Deployment maturity favors Digital Monitoring; climate necessity drives Advanced Cooling adoption fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss equipment suppliers dominate Gulf procurement corridors, shipping solid-state transformer assemblies through Dubai's Jebel Ali port for redistribution across Saudi Arabia, Kuwait, and Oman renewable project sites.
Saudi Arabia
Gigawatt-scale solar buildouts at Al Shuaibah and Sudair drive transformer demand. The national electricity regulator mandates distributed intelligence at substation level under revised grid codes. NEOM's northwest corridor hosts pilot solid-state installations for autonomous voltage regulation.
United Arab Emirates
Dubai and Abu Dhabi distribution utilities restructure tender evaluations to weight connectivity above capital cost. The central electricity authority mandates IoT-ready equipment specifications for new transmission assets. Mohammed bin Rashid Al Maktoum Solar Park interconnections concentrate step-up transformer procurement.
Kuwait
Nascent renewable targets at Shagaya Renewable Energy Park create first-mover positioning for modular transformer suppliers. The Ministry of Electricity and Water enforces thermal performance standards for desert-climate operation. Local assembly partnerships are forming to satisfy emerging local content rules.
Oman
Manah Solar Project and Dhofar wind farms require bidirectional power flow management. The Authority for Public Services regulates equipment certification for grid-connected assets. Port of Duqm industrial zone attracts transformer manufacturers seeking Gulf hub positioning.
Qatar
Al Kharsaah solar power plant expansion sustains utility-scale procurement. Kahramaa's technical standards specify embedded sensor networks for predictive maintenance integration. Ras Laffan Industrial City petrochemical complexes seek real-time load balancing retrofits.
Middle-East Smart Transformer Market Competitive Landscape
Listed European energy majors compete with private Gulf specialists across utility-scale tendering channels. The vendor base consolidates around three tiers: integrated power electronics conglomerates, regional fabrication joint ventures, and modular technology specialists. Siemens Energy and ABB anchor the premium tier through digital monitoring portfolios. Strategic moves concentrate on technology licensing partnerships and local assembly joint ventures to satisfy tightening content requirements.
Within the integrated tier, Siemens Energy, ABB, and Schneider Electric occupy positions defined by digital service bundling rather than hardware supply alone. Siemens Energy represents the German-listed archetype with pre-certified monitoring platforms. ABB exemplifies Swiss-Swedish engineering heritage through thermal stress specialization. Schneider Electric anchors French industrial automation convergence. These three names surface repeatedly in Saudi renewable energy tenders requiring multi-year performance guarantees with embedded remote diagnostics.
| Leading Market Players |
|---|
| Siemens Energy |
| ABB |
| Schneider Electric |
| GE Vernova |
| alfanar Group |
| Eaton Corporation |
| General Electric |
| SGB-SMIT |
| Abaft Middle East Transformer Ind. LLC |
| Others |
Supply & Pricing Matrix
Long-term performance-based offtake contracts lock in supply access for silicon carbide power electronics while anchoring price visibility for Gulf utilities commissioning gigawatt-scale solar interconnections. These structures bundle hardware delivery with multi-year remote monitoring subscriptions, compressing upfront capital outlays into operational expenditure profiles that align with Saudi Arabia's renewable energy project company tender requirements.
Pricing Analysis
Next-generation solid-state transformer architectures command substantial premiums over conventional electromagnetic units due to autonomous voltage regulation capabilities without mechanical tap changers. Three-tier pricing structure across premium, standard, and economy levels stratifies by digital service bundling intensity and cooling system specification. Cost compression in standard-tier units is intensifying because Japanese and US wafer manufacturers concentrate silicon carbide substrate supply. State-owned Gulf utilities show lowest price sensitivity as regulatory mandates override capital cost considerations, while independent power producers negotiate hardest on upfront equipment pricing.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates and advanced cooling components dominates inventory strategy as lead times from Japanese wafer manufacturers extend unpredictably. Manufacturing concentration centers on Germany, Switzerland, and Japan for power electronics assemblies, with China supplying commodity-grade sensor networks and communication modules. Raw material dependencies rest on silicon carbide wafers, high-temperature insulation materials, and liquid-immersed cooling fluids. Single-source vulnerability in semiconductor substrates creates supply chain risk as geopolitical tensions constrain technology transfer. Distribution runs through Dubai's Jebel Ali port for redistribution across Saudi Arabia, Kuwait, and Oman project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as renewable buildouts diversify beyond Saudi Arabia and the UAE, creating specialized niches for modular configurations and harmonic conditioning bundles that incumbent conglomerates under-serve.
For Market Incumbents: Secure technology licensing partnerships with Gulf fabrication joint ventures to satisfy tightening local content rules without exposing core intellectual property. Anchor premium positioning through predictive analytics subscriptions that independent power producers now mandate in Saudi renewable tenders. Capacity addition in Saudi Arabia's industrial zones defends against emerging regional specialists capturing modular deployment contracts. For New Entrants and Emerging Players: Firmware update and remote diagnostics service layers represent white-space where Siemens Energy and ABB concentrate on hardware supply. Kuwait and Oman present most penetrable geographies as renewable targets mature without established supplier relationships. Target industrial automation retrofits in Qatar's Ras Laffan petrochemical complexes through Schneider Electric-compatible IoT integration protocols. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors vertically integrated power electronics specialists with captive semiconductor sourcing. Long-term viability hinges on positioning ahead of solid-state transformer commoditization as manufacturing scales. Acquisition target archetype includes modular technology specialists with certified Gulf grid code compliance. Watch silicon carbide substrate price stabilization as inflection indicator for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Joint Venture | Satisfies Saudi and UAE local content rules while protecting core power electronics IP. |
| Digital Service Platform Certification | Compresses procurement timelines under UAE central electricity authority IoT mandates. |
| Solid-State Transformer Pilot Deployment | Captures autonomous voltage regulation demand at NEOM and Saudi Aramco solar sites. |
| Advanced Cooling System Specialization | Addresses desert-climate thermal stress exceeding 50°C ambient in Gulf solar farm environments. |
| Modular Capacity Scaling Partnership | Aligns transformer deployment with phased renewable commissioning schedules without capital stranding. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, EPC contractors, IPP project developers, and grid operators at Saudi Arabia's national regulator and UAE's central electricity authority. Secondary validation drew from FERC-style regulatory filings, IEA renewable deployment databases, project development registries, and customs import records. Bottom-up equipment procurement tracking and top-down grid investment forecasts were triangulated to anchor volume estimates.
Across the analysis window, the forecasting framework modeled product type segmentation by step-up, modular, and multi-functional configurations alongside application splits across renewable energy, smart grid, and industrial automation. CAGRs were derived from utility-scale renewable commissioning schedules and regulatory mandate implementation timelines. Forecast inputs incorporated silicon carbide substrate supply constraints and Gulf grid code revision cycles.
Underlying assumptions cover sustained renewable energy auction activity and stable technology transfer policy, with deviation risk concentrated in semiconductor supply disruptions and local content rule tightening. Revision becomes warranted when silicon carbide wafer pricing or Gulf regulatory compliance timelines cross material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Transformer Bobbin Market
Transformers
United States Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
India Distribution Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Amorphous Core Transformers Market
Transformers
Rectifier Transformers Market
Transformers
North America Smart Transformers Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Industrial Control Transformers Market
Transformers
High Frequency Transformer Market
Transformers
Oil Filled Transformer Market
Transformers
United States Large Power Transformer Market
Transformers
Latin America Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
Distribution Transformer Market