
 Lunch Box Market | 2026-2036
Lunch Box Market Size, Share, and Industry Trends Forecast 2026-2036
Lunch Box Market Outlook
Online direct-to-consumer distribution is fragmenting as Amazon, brand websites, and specialty kitchen retailers compete for lunch box shoppers with divergent fulfillment models and loyalty mechanics. YETI leverages its premium outdoor heritage to command pricing power in stainless-steel insulated segments. Bentgo specializes in compartmentalized bento formats for school-age consumers, sustaining repeat purchases through interchangeable tray accessories. Zojirushi dominates vacuum-insulation engineering, extending its thermal retention reputation from rice cookers into portable food storage.
A lunch box is a portable food container engineered for thermal retention, portion organization, or both, typically constructed from polypropylene, stainless steel, borosilicate glass, or multi-layer fabric with closed-cell foam insulation, and manufactured through injection molding, deep drawing, or sewn assembly to preserve food temperature and prevent leakage during transit. Thermal and insulated product types lead value contribution where margin pools concentrate around double-wall vacuum construction and extended heat retention claims. Bento and stackable formats anchor volume in Asia-Pacific markets where multi-compartment meal organization aligns with established dietary customs. Plastic and metal materials split the mass-market landscape, with metal gaining ground in premium positioning due to durability perceptions and dishwasher compatibility.
The US Consumer Product Safety Commission enforces material safety standards for food-contact plastics, while the EU REACH regulation restricts phthalate and bisphenol migration into food-contact articles, effectively filtering non-compliant suppliers from transatlantic distribution channels. China's SAMR administers GB standards for food-contact materials, creating a separate compliance gateway for domestic and export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and state-level packaging mandates in California and New York, as these will determine which material platforms and reuse models retain channel access.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing demand for disposable food containers and redirecting procurement toward reusable, multi-cycle lunch box platforms across European retail channels.
Growth Catalysts
- REACH chemical compliance:European food-contact material standards filter non-compliant Asian suppliers, creating shelf space for certified reusable container manufacturers in EU distribution networks.
- Urban commuting density:China's tier-one cities generate concentrated demand for thermal retention containers as white-collar workers prioritize home-prepared meals over food delivery platforms.
- Vacuum-insulation engineering:Double-wall stainless steel construction extends heat retention duration beyond six hours, unlocking premium pricing in professional and outdoor recreation segments.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin predictability for metal-dominant manufacturers locked into annual retail pricing contracts.
- Injection molding equipment concentration:Polypropylene container production clusters in Zhejiang and Guangdong provinces, exposing supply chains to regional power rationing and port congestion.
- Glass fragility threshold:Borosilicate formats face breakage-rate ceilings that limit adoption in K-12 and construction site end-uses despite superior chemical inertness.
Strategic Opportunities
- Extended producer responsibility frameworks:France's AGEC law and similar EU national implementations create compliance-driven replacement cycles for non-recyclable legacy containers.
- Smart temperature monitoring:Integration of Bluetooth-enabled sensors with vacuum-insulated shells addresses food safety liability concerns in healthcare and childcare institutional procurement.
- Specialty kitchen retail expansion:Williams Sonoma and Sur La Table channels reward design differentiation with margin structures unavailable through mass-market big-box distribution.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and SAMR food-contact approvals require 18-24 month validation cycles that delay product launches.
- Legacy ERP integration:Direct-to-consumer fulfillment platforms demand real-time inventory visibility that conflicts with established wholesale-distributor data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lunch Box Market |
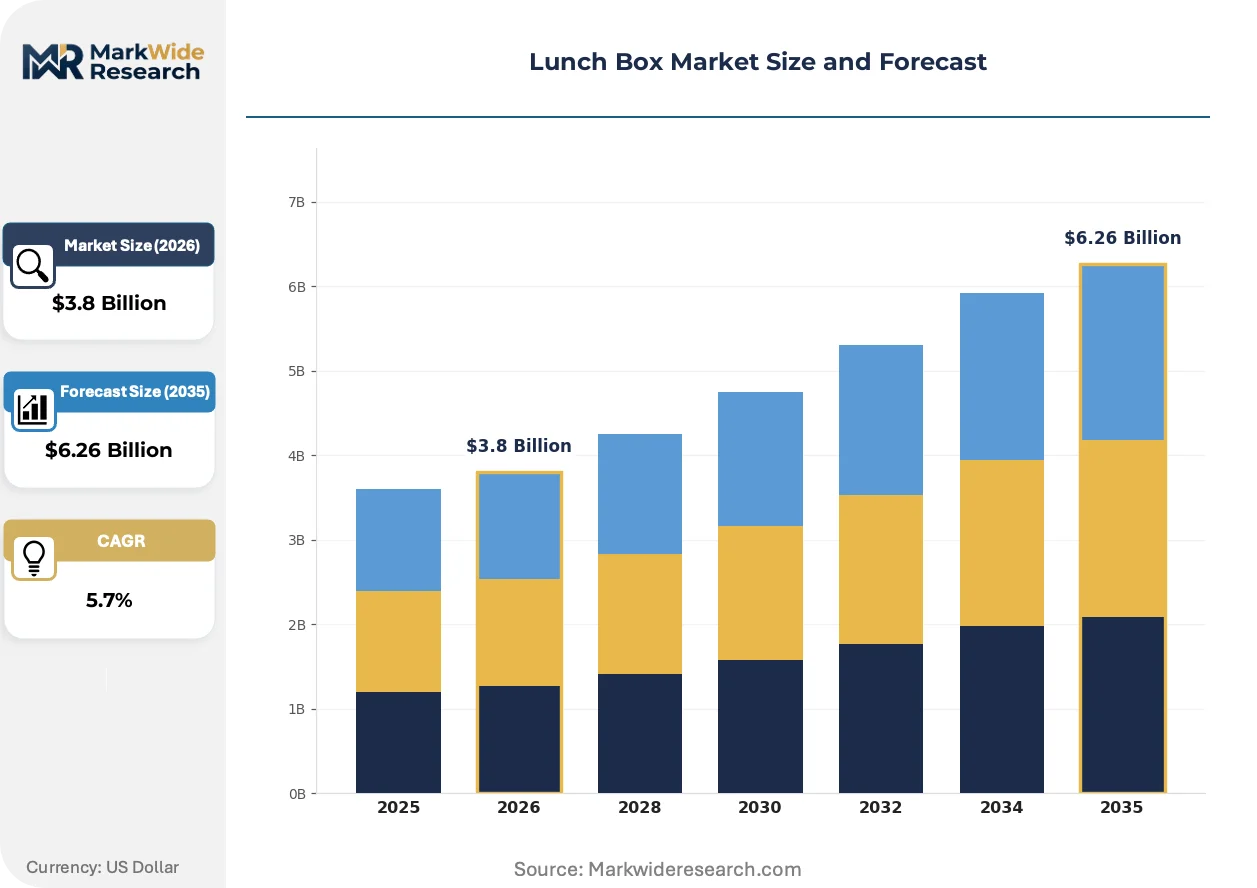
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Insulated, Bento, Stackable Material: Plastic, Metal, Fabric, Glass Design: Classic, Modern, Fun, Eco-Friendly End User: Kids, Adults, Professionals, Students |
| Companies Covered | Lock&Lock, YETI, Thermos, Contigo, Bentgo, Zojirushi, Rubbermaid, Stanley, Sistema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lunch Box Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning around thermal performance, circular design, and connected functionality.
Phase-change material integration is migrating from medical cold-chain applications into consumer lunch boxes. Gel-based thermal mass inserts extend passive cooling duration without electrical dependency. Outdoor recreation buyers and healthcare field workers are adopting these inserts fastest. This technology is migrating from niche medical supply into mainstream consumer channels, compressing the performance gap between passive and active cooling systems.
California's SB 54 packaging waste reduction mandate imposes rigid recycling-content thresholds on food-contact plastics sold after 2030. Manufacturers must requalify polypropylene formulations or pivot to alternative substrates. The standard-economy plastic segment faces the steepest compliance burden, with several suppliers accelerating metal and silicone hybrid development to maintain California market access.
Corporate procurement departments are consolidating vendor relationships for employee meal programs. Food service management companies like Aramark and Compass Group now specify thermal retention performance in RFP technical appendices rather than accepting generic product claims. This concentration is most visible in North American tech campus and healthcare facility contracts, where sustainability scorecards weight reusable container deployment metrics.
Lunch Box Market Segmentation
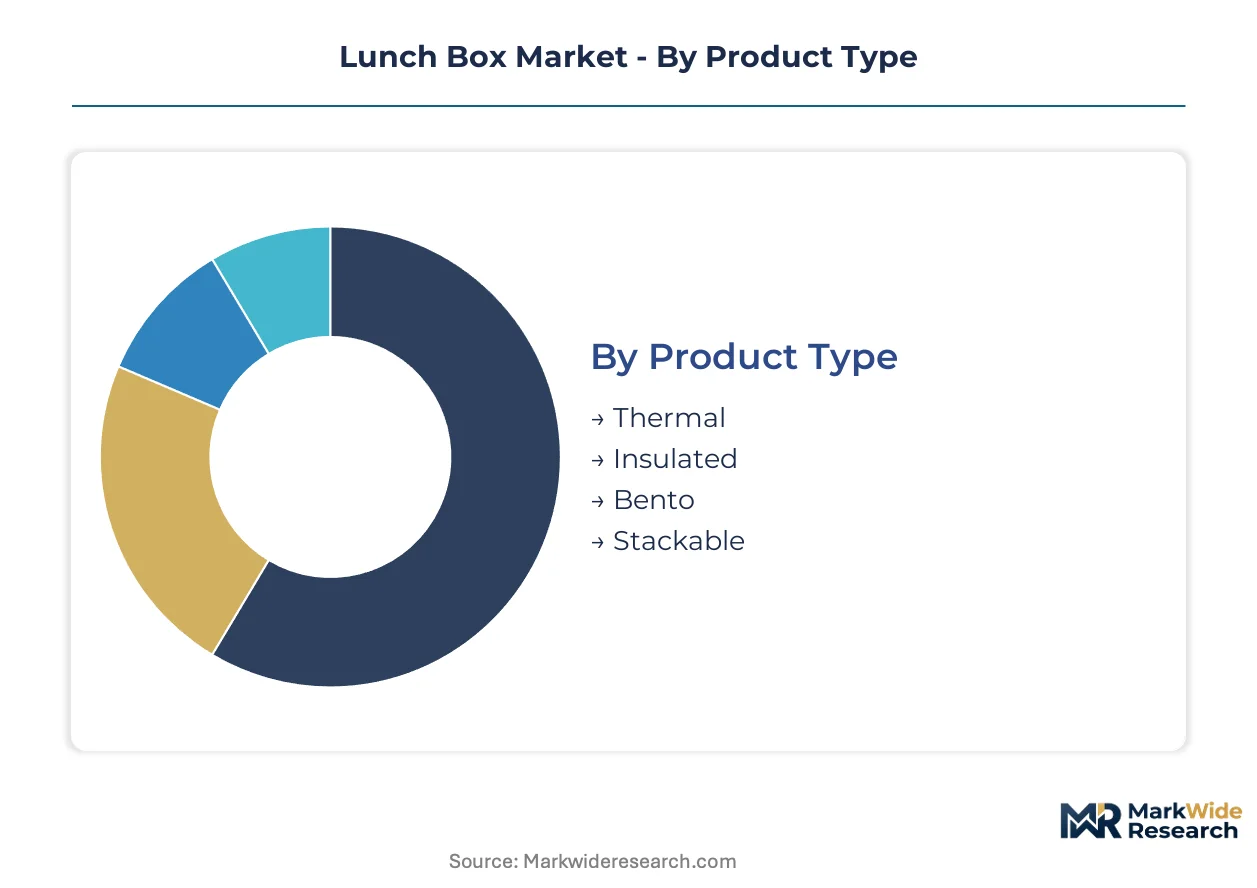
Lunch box segmentation reflects divergent performance requirements across thermal engineering, material compliance, and lifestyle positioning. Manufacturers must align product architecture with specific end-use constraints rather than pursuing universal designs.
Product Type:
Performance tier separates passive insulation from active thermal retention systems, with construction complexity determining price positioning and channel access.
- Thermal:Double-wall vacuum construction utilizing stainless steel substrates delivers heat retention beyond six hours. Professional commuters in China's tier-one cities drive procurement for home-prepared meal preservation over food delivery alternatives.
- Insulated:Multi-layer fabric shells with closed-cell foam cores balance weight and moderate thermal performance. Outdoor recreation segments favor these formats for hiking and fieldwork where electrical cooling is unavailable.
- Bento:Compartmentalized tray systems align with established Asian dietary customs for multi-dish meal organization.
- Stackable:Modular vertical nesting designs optimize storage density for institutional food service and compact urban kitchens.
Thermal formats command the established base. The steepest expansion runs through Bento configurations.
Material:
Application context dictates substrate selection, with regulatory chemistry restrictions and durability requirements filtering viable options across end-use segments.
- Metal:18/8 stainless steel grades satisfy FDA and EFSA food-contact standards while offering dishwasher compatibility and dent resistance. Premium positioning in professional and outdoor segments reflects durability perceptions and thermal conductivity advantages.
- Plastic:Injection-molded polypropylene dominates volume production through Zhejiang and Guangdong manufacturing clusters. REACH and California SB 54 compliance pressures are accelerating formulation requalification toward recycled-content thresholds.
- Fabric:Woven polyester or canvas exteriors with insulated liners serve cost-sensitive casual use cases.
- Glass:Borosilicate substrates provide chemical inertness for acidic foods but face breakage-rate limitations in K-12 and construction environments.
Metal substrates anchor premium positioning. The steepest volume trajectory climbs through plastic formats navigating regulatory transition.
Design:
Customer type and purchase occasion determine aesthetic positioning, with retail channel selection reinforcing design differentiation.
- Classic:Traditional form factors with neutral palettes target established consumer preferences in mature markets.
- Modern:Minimalist geometries and matte finishes align with urban professional demographics and specialty kitchen retail channels like Williams Sonoma.
- Fun:Character licensing and bright colorways drive replacement cycles in school-age segments through interchangeable accessories.
- Eco-Friendly:Recycled-content certification and biodegradable components respond to EU extended producer responsibility mandates and corporate sustainability procurement scorecards.
Modern designs capture professional wallet share. The steepest expansion trajectory flows through Eco-Friendly formats.
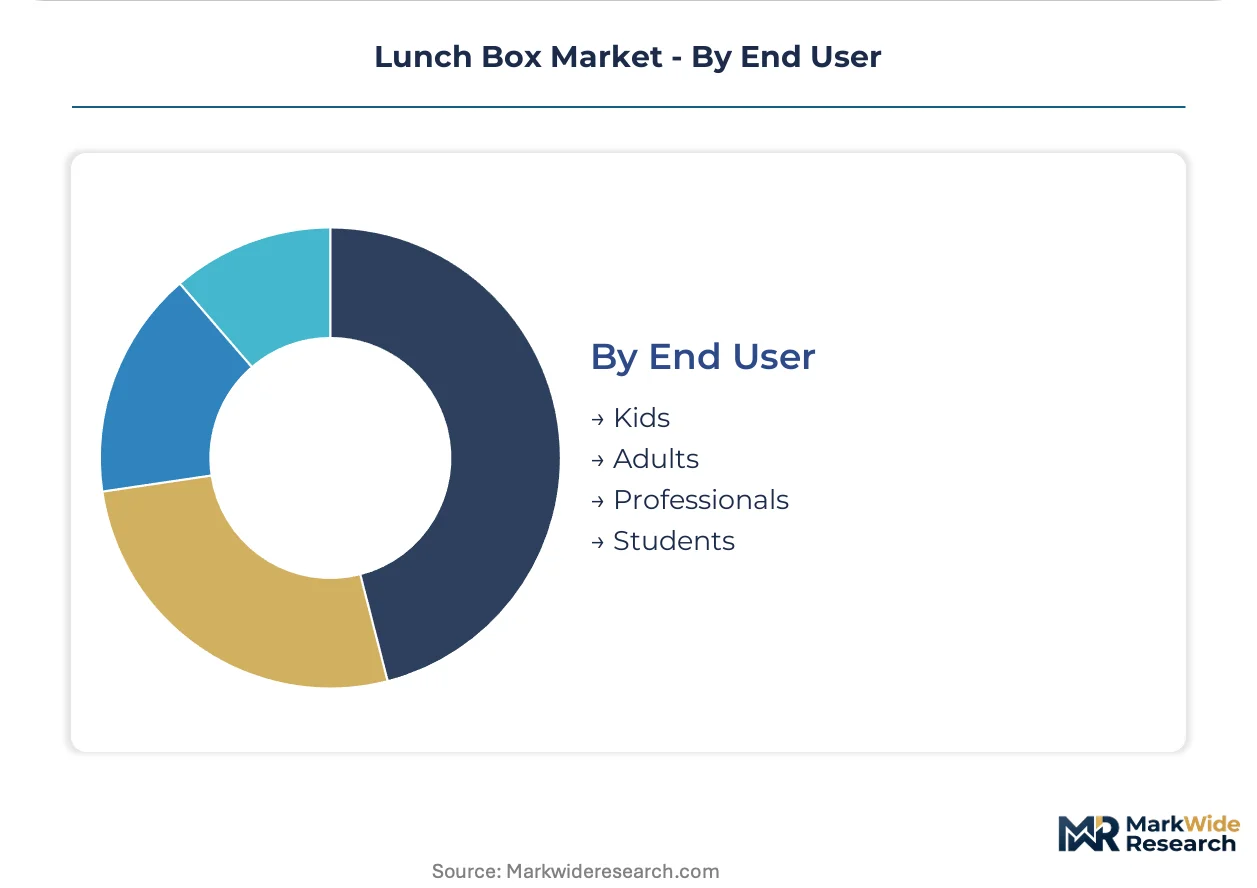
End User:
Volume scale and margin structure diverge sharply across age demographics and institutional versus individual purchase patterns.
- Professionals:White-collar urban commuters prioritize thermal retention duration and leak-proof sealing for public transit meal transport. Corporate procurement consolidation at tech campuses and healthcare facilities is embedding sustainability metrics into vendor selection.
- Kids:Parental purchase decisions weigh portion control, ease of opening, and dishwasher safety. Interchangeable tray accessories sustain repeat purchase frequency.
- Adults:General household use spans casual and committed meal-preparation behaviors with broad price elasticity.
- Students:University demographics balance cost constraints with portability requirements for campus dining alternatives.
Professionals command margin concentration. The steepest volume expansion runs through Kids segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in lunch box manufacturing and procurement, while Rotterdam's status as Europe's largest seaport enables REACH-compliant material flows across the continent. Distribution corridors through the Suez Canal and transpacific lanes connect these hubs to North American consumer markets.
China
Urban commuting density in Shanghai, Beijing, and Shenzhen generates concentrated demand for vacuum-insulated stainless steel containers among white-collar professionals. SAMR administers GB standards for food-contact materials that filter non-compliant domestic suppliers from export channels. Manufacturing clusters in Zhejiang and Guangdong provinces concentrate injection-molded polypropylene production, though regional power rationing periodically disrupts output.
United States
Corporate procurement consolidation at tech campuses and healthcare facilities embeds sustainability metrics into vendor selection for reusable meal programs. The FDA enforces material safety standards for food-contact plastics under 21 CFR regulations. California's SB 54 packaging waste reduction mandate imposes recycling-content thresholds that accelerate formulation requalification efforts among polypropylene suppliers.
Germany
REACH chemical compliance filters Asian suppliers from EU distribution networks, creating shelf space for certified reusable container manufacturers. ECHA restrictions on phthalate and bisphenol migration shape material platform decisions across the value chain. Industrial concentration in North Rhine-Westphalia and Bavaria supports precision metalworking capabilities for vacuum-insulation engineering.
Japan
Established dietary customs sustain demand for compartmentalized bento formats across consumer and institutional segments. METI oversees JIS standards for food-contact articles that align with domestic quality expectations. Manufacturing heritage in the Kansai region, particularly Osaka-based metalworking traditions, anchors thermal retention engineering expertise.
France
AGEC law implementation creates compliance-driven replacement cycles for non-recyclable legacy containers across retail and food service channels. ANSM monitors food-contact material safety alongside EU-wide EFSA frameworks. Design differentiation in Paris-based specialty kitchen retail channels rewards premium positioning unavailable through mass-market distribution.
Lunch Box Market Competitive Environment
On the supply side, the industry is structured around three distinct tiers: premium outdoor heritage brands commanding stainless steel insulated segments, compartmentalization specialists capturing school-age replacement cycles, and volume manufacturers serving price-sensitive institutional procurement. Strategic archetypes include vacuum-insulation engineering leaders, bento-format compartmentalization experts, and injection-molded plastic scale players. Competitive moves concentrate on portfolio diversification into adjacent thermal retention categories and geographic expansion through direct-to-consumer fulfillment platforms.
Among heritage outdoor equipment manufacturers, YETI and Stanley occupy positions exemplifying premium thermal retention positioning. Zojirushi represents the vacuum-insulation engineering archetype, extending manufacturing expertise from adjacent appliance categories. Bentgo sits within the compartmentalization specialist tier, sustaining repeat purchase frequency through accessory-driven ecosystem approaches.
| Leading Market Players |
|---|
| Lock&Lock |
| YETI |
| Thermos |
| Contigo |
| Bentgo |
| Zojirushi |
| Rubbermaid |
| Stanley |
| Sistema |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Guangdong injection-molding clusters concentrate polypropylene container production, tethering margin pools to regional power stability and port throughput efficiency. Nickel and chromium price volatility in stainless steel substrates compresses pricing predictability for vacuum-insulation manufacturers locked into annual retail contracts.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on thermal retention duration and certification grade. YETI and Zojirushi command brand premiums through vacuum-insulation engineering validated by FDA and EFSA food-contact standards. Pricing pressure stems from California SB 54 compliance costs forcing polypropylene reformulation. Institutional buyers at Aramark and Compass Group exhibit lowest price sensitivity, while university students and casual adult segments drive economy-tier volume.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for metal-dominant manufacturers. Production draws from Zhejiang and Guangdong provinces for injection-molded plastics, Osaka-Kansai region for precision metalworking, and North Rhine-Westphalia for REACH-compliant component finishing. Raw material dependencies center on nickel-chromium stainless steel grades, food-contact polypropylene resins, and borosilicate glass substrates. Distribution runs through Amazon direct-to-consumer, specialty kitchen retailers like Williams Sonoma, and consolidated corporate procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum-insulation engineering expertise represents the critical capability gap separating premium thermal retention positioning from commodity container production. Manufacturers lacking double-wall construction heritage face structural barriers to margin capture in professional and outdoor recreation segments.
For Market Incumbents: Insulate stainless steel supply positions through backward integration into nickel-chromium sourcing or long-term offtake agreements with Japanese metal refiners. Lock in SAMR and FDA certification pipelines ahead of competitor product launches. Defend against Bentgo-style compartmentalization specialists by accelerating interchangeable accessory ecosystems for bento formats. For New Entrants and Emerging Players: Pursue white-space opportunities in smart temperature monitoring integration for healthcare and childcare institutional procurement. Target France's AGEC law-driven replacement cycles with recyclable-content certification. Establish direct-to-consumer fulfillment capabilities before attempting mass retail shelf placement. For Investors and Strategic Acquirers: Capital is best deployed toward vacuum-insulation engineering specialists with established JIS or GB standard compliance and dormant brand equity in adjacent appliance categories. Long-term viability hinges on regulatory chemistry adaptation capacity rather than volume scale. Watch for ECHA restrictions on phthalate migration tightening as the inflection signal for material platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Chromium Supply | Reduces margin volatility from London Metal Exchange price swings for stainless steel substrate producers. |
| Smart Temperature Monitoring Integration | Unlocks healthcare and childcare procurement specifications requiring Bluetooth-enabled food safety compliance. |
| Direct-to-Consumer Channel Launch | Bypasses Amazon commission structures and captures first-party data for accessory-driven repeat purchase cycles. |
| Extended Producer Responsibility Certification | Secures California SB 54 and EU AGEC law compliance for retail channel access post-2030. |
| Corporate Procurement Consolidation | Captures Aramark and Compass Group sustainability scorecard weighting for reusable container deployment metrics. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with vacuum-insulation engineers, specialty kitchen retail buyers, corporate food service procurement managers, and SAMR compliance consultants; and secondary validation through FDA 21 CFR filings, ECHA REACH substance restrictions, customs trade records, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Forecast inputs considered thermal retention performance tiers, material substrate categories, end-user demographics, and regional regulatory clusters across the analysis window. CAGRs derived from segment-level growth trajectory modeling incorporating urban commuting density indices and extended producer responsibility implementation timelines. Phase-change material adoption curves and smart sensor integration rates supplied industry-specific forecast parameters.
Sensitivities concentrate around nickel price volatility, China power rationing frequency, and ECHA chemical restriction expansion. Forecasts reflect documented assumptions on regulatory enforcement intensity and consumer willingness-to-pay for thermal retention duration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Disposable Napkins Market
Household Items
Ceramic Travel Mug Market
Household Items
Pocket Tissues Market
Household Items
Automatic Dishwashing Products Market
Household Items
Gel Warmers Market
Household Items
Smart Toilet Market
Household Items
Bladeless Neck Fan Market
Household Items
Global Electric Scissors Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Home Scales Market
Household Items
Laundry Detergent Sheets Market
Household Items
Ultrasonic Diffusers Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Robotic Pool Cleaner Market
Household Items
Japan Cookware Market
Household Items
Middle East Handheld Vacuum Cleaner Market