
 Smart Kitchen Faucet Market | 2026-2036
Smart Kitchen Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Kitchen Faucet Market Insights
A capital-intensity divergence between sensor-integrated specialists and traditional brassware manufacturers is reorganizing competitive dynamics in smart kitchen fixtures. Kohler Co. leverages captive semiconductor sourcing to control touchless module costs. Moen Incorporated anchors its position through proprietary voice-activation patents that limit downstream compatibility.
Smart kitchen faucets combine solenoid-actuated water control, infrared or capacitive proximity sensing, and wireless connectivity protocols to deliver hands-free flow management with temperature precision and usage telemetry. Touchless faucets dominate current volume, while Wi-Fi-enabled units capture expanding margin pools through subscription-compatible water monitoring services. Residential end users represent the mature demand base, though hospitality procurement is accelerating fastest as hotel chains standardize on connected hygiene infrastructure.
EPA WaterSense specifications and EU Ecodesign requirements constrain flow-rate parameters, while FCC Part 15 governs radio-frequency emissions from Bluetooth and Wi-Fi modules in US-sold units. CE marking and REACH compliance create dual certification burdens for suppliers serving both North American and European channels. Stakeholders must monitor evolving interoperability standards between proprietary home automation ecosystems and open-source protocols.
Market Dynamics
Semiconductor supply concentration in Taiwan and South Korea is forcing smart faucet manufacturers to redesign touchless modules around domestically available microcontrollers, altering cost structures and supplier relationships across the fixture industry.
Growth Catalysts
- EPA WaterSense mandates:US federal procurement rules now require WaterSense-labeled fixtures in all new federal housing, creating guaranteed demand for certified smart faucets.
- Voice-activation convergence:Integration with Alexa and Google Home ecosystems is driving replacement cycles among tech-forward residential buyers seeking whole-home automation.
- Hospitality hygiene standardization:Marriott and Hilton procurement specifications now mandate touchless fixtures for all new property construction and major renovations.
Market Restraints
- MEMS sensor cost volatility:Piezoelectric and infrared proximity sensors face 15-25% price swings tied to rare earth processing capacity in China.
- Brass billet supply concentration:Over 60% of lead-free brass feedstock for North American production originates from a single Chilean mining consortium.
- Wi-Fi 6E spectrum fragmentation:Incompatible regional frequency allocations force manufacturers to maintain multiple radio hardware variants, inflating inventory carrying costs.
Strategic Opportunities
- India residential penetration:Smart home adoption in Mumbai and Bangalore luxury developments remains under 8%, creating first-mover positioning for WaterSense-equivalent certified products.
- Commercial foodservice integration:HACCP-compliant touchless faucets with temperature logging are displacing manual valves in QSR kitchen buildouts.
- EU Ecodesign revision:Pending 2027 flow-rate restrictions will obsolete non-smart thermostatic models, mandating upgrade cycles across German and French renovation markets.
Industry Challenges
- Firmware security certification:UL 2900-2-3 cybersecurity validation for connected plumbing fixtures adds 8-14 months to product launch timelines.
- Plumber training deficits:North American trade schools lack curricula covering solenoid valve troubleshooting and wireless pairing protocols, slowing post-install support quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Kitchen Faucet Market |
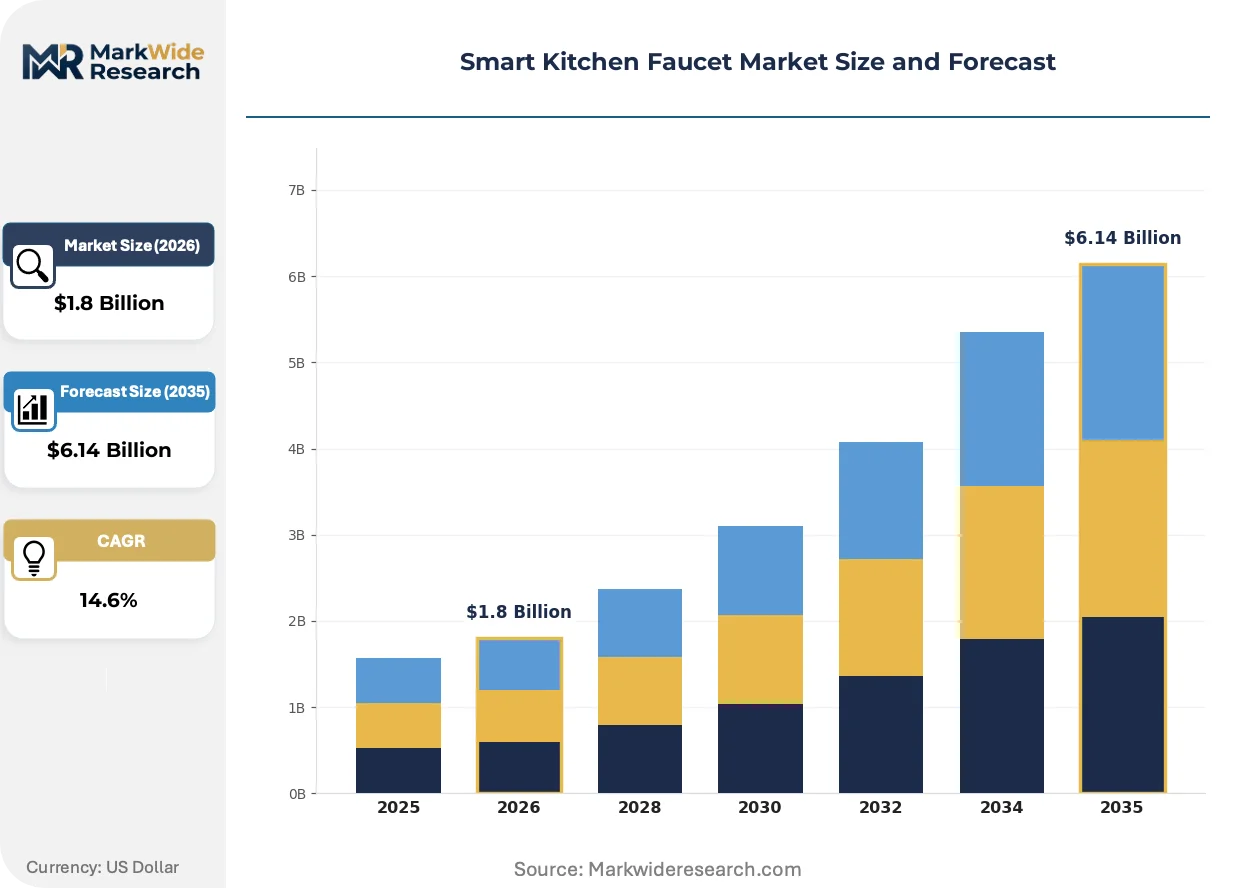
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchless Faucets, Sensor-Activated Faucets, Bluetooth Faucets, Wi-Fi Faucets Design Style: Modern, Traditional, Minimalist, Industrial Connectivity: Wi-Fi, Bluetooth, Zigbee, Proprietary Networks End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Kohler Co., Moen Incorporated, Delta Faucet Company, LIXIL Group, Hansgrohe SE, TOTO Ltd., Roca Sanitario, S.A., Masco Corporation, GROHE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Kitchen Faucet Market Trends and Innovations
Capacitive sensing architectures are overtaking infrared in premium installations, while subscription-based water monitoring services are restructuring manufacturer revenue models away from one-time hardware sales.
Ultrasonic flow measurement is supplanting turbine-based volume sensors in high-end residential and commercial units. Luxury home builders in California and Texas specify ultrasonic modules for their immunity to hard-water scaling. This shift is compressing margins for legacy turbine sensor suppliers while enabling tiered service pricing based on real-time leak detection accuracy.
EU Ecodesign Directive 2023/814 imposes strict standby power limits on networked kitchen appliances. Manufacturers serving European channels must redesign control boards to sub-0.5W idle consumption or forfeit CE marking eligibility. German retailers now demand proof of Ecodesign compliance before listing Wi-Fi-enabled faucets, filtering out smaller import brands.
Builder procurement contracts increasingly bundle fixture specification with long-term maintenance agreements. Toll Brothers and Lennar negotiate 7-10 year service contracts covering sensor recalibration and valve replacement, displacing traditional distributor-wholesaler relationships. This consolidation is most pronounced in Arizona and Florida master-planned communities where single-source vendor agreements dominate new construction.
Smart Kitchen Faucet Market Segmentation
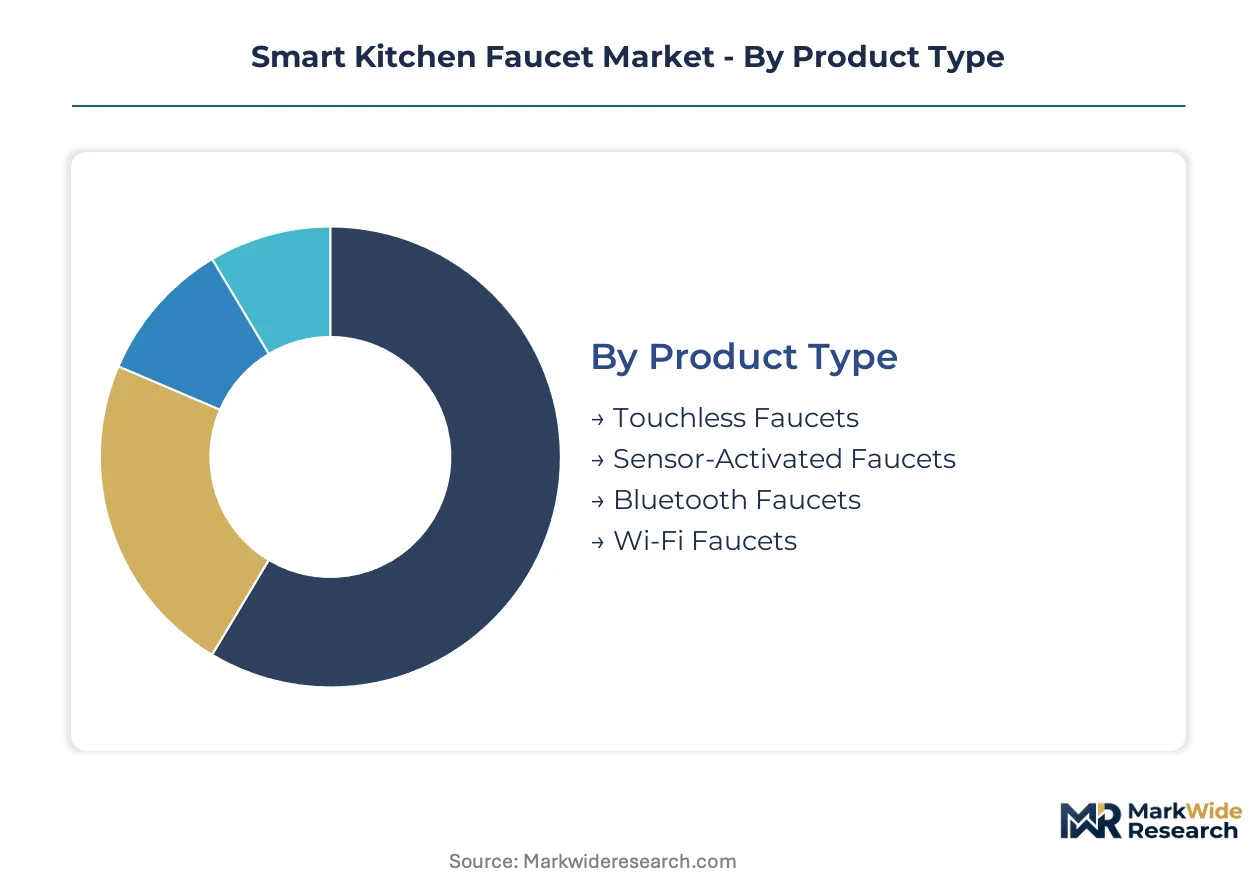
Smart kitchen faucet segmentation reveals how hardware specifications, aesthetic positioning, and connectivity protocols map to distinct procurement channels and price tiers. Manufacturers optimize sensor calibration, valve engineering, and radio modules differently for each segment cluster.
Product Type:
Touchless and sensor-activated variants dominate domestic renovation demand in the United States and Germany, while Wi-Fi-enabled units concentrate in export-led smart home integration projects.
- Touchless Faucets:Infrared or capacitive proximity sensors trigger solenoid valves without physical contact. Demand concentrates in United States federal housing projects where EPA WaterSense certification is mandatory for new construction.
- Sensor-Activated Faucets:Hybrid systems combine manual override with automated flow initiation. German kitchen renovation contractors specify these for Ecodesign-compliant retrofits where standby power limits apply.
- Bluetooth Faucets:Short-range pairing enables smartphone temperature control without home network dependency.
- Wi-Fi Faucets:Cloud-connected units support usage telemetry and leak alerts through residential gateway integration.
Touchless faucets command the established base. The steepest expansion runs through Wi-Fi faucets.
Design Style:
Cost tiers stratify sharply across aesthetic positioning, with premium architectural specifications carrying 3-4x material overhead versus economy contractor-grade lines.
- Modern:Clean geometric lines with matte black or brushed nickel finishes dominate California and Texas luxury residential specifications. Architects specify these for LEED-certified kitchen renovations where fixture aesthetics contribute to material transparency scoring.
- Traditional:Cross-handle silhouettes with oil-rubbed bronze or polished chrome bridge Victorian and transitional kitchen designs. These concentrate in Northeast United States historic district renovations where local preservation boards review exterior-visible kitchen elements.
- Minimalist:Single-plane spouts with hidden sensor integration target Scandinavian-influenced German and Danish residential markets.
- Industrial:Exposed spring-neck and lever-handle configurations serve commercial foodservice and brewery tasting room installations.
Modern styling captures the highest-margin specification channel. Industrial applications show the steepest volume climb in commercial foodservice.
Connectivity:
Application requirements determine protocol selection, with whole-home automation driving Wi-Fi adoption while point-control scenarios favor Bluetooth or Zigbee mesh architectures.
- Wi-Fi:Direct cloud connectivity enables firmware updates and usage dashboards without hub intermediation. Hospitality chains in the United States standardize on Wi-Fi modules for centralized property management system integration across Marriott and Hilton portfolios.
- Bluetooth:Low-energy pairing suits rental property installations where tenants lack network administrator access. German multi-family housing developers specify Bluetooth to avoid shared infrastructure liability.
- Zigbee:Mesh networking extends range in large-footprint commercial kitchens without Wi-Fi congestion.
- Proprietary Networks:Manufacturer-locked protocols lock users into branded ecosystem accessories and service subscriptions.
Wi-Fi protocols anchor the revenue base. Zigbee deployments are gaining share fastest in commercial kitchen network densification.
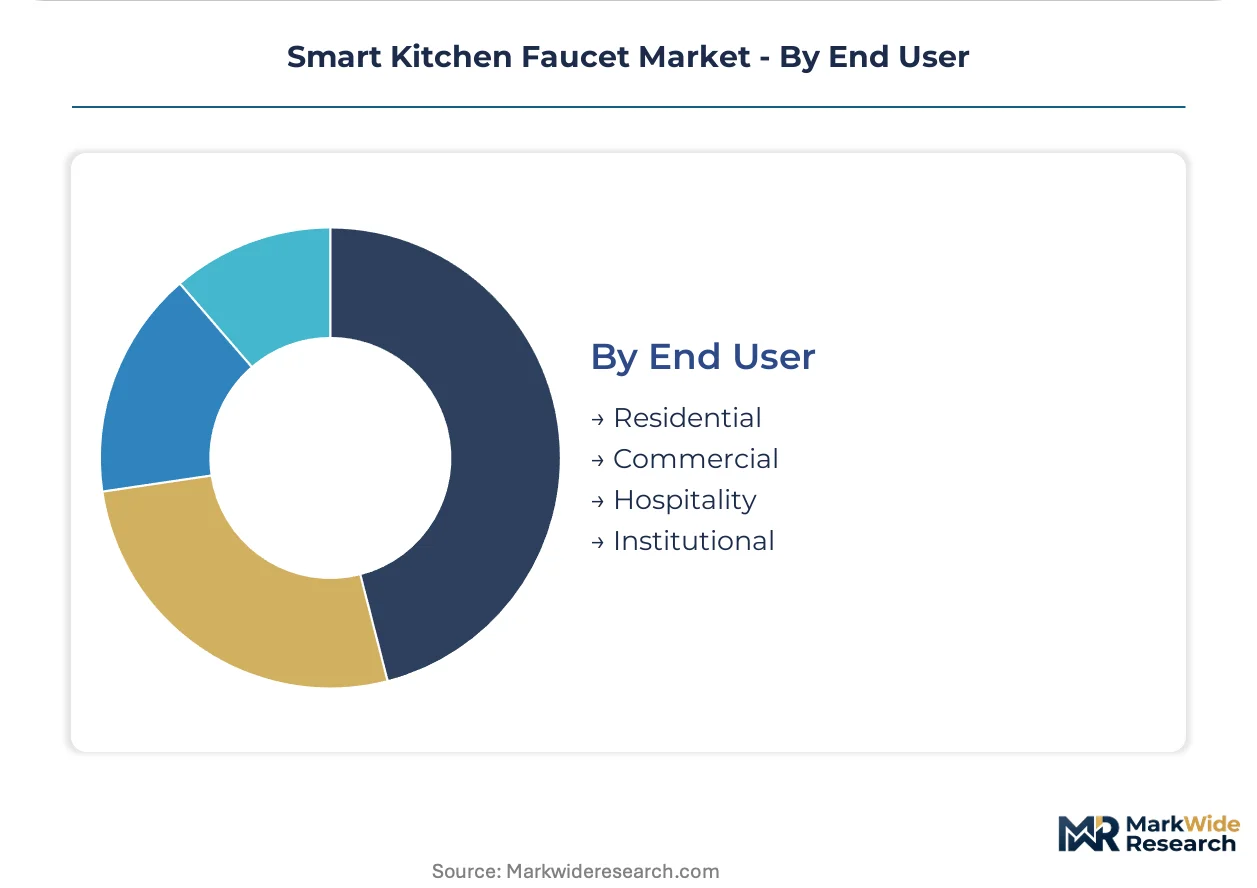
End User:
Customer type dictates warranty terms, installation support depth, and sensor calibration protocols across residential, commercial, hospitality, and institutional procurement channels.
- Residential:Single-family and multi-family homeowners prioritize voice activation compatibility and DIY installation. United States big-box retail channels move the highest unit volumes through kitchen renovation seasonality.
- Commercial:Office building facility managers specify touchless fixtures for ADA compliance and reduced maintenance cycles. These concentrate in Class A United States urban core properties where tenant amenity competition drives specification.
- Hospitality:Hotel chains mandate connected hygiene infrastructure with centralized monitoring. Marriott procurement specifications now require touchless fixtures for all new United States property construction.
- Institutional:Healthcare and educational facilities specify antimicrobial finishes and HACCP-compliant temperature logging for infection control.
Residential channels command the established base. Hospitality procurement shows the steepest expansion trajectory as chains standardize on connected hygiene infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands 40% premiums over comparable German specifications, while Chinese export channels compress margins through standardized sensor module sourcing. This asymmetry reshapes where manufacturers prioritize certification investments and localized production.
United States
Federal housing procurement and hospitality chain standardization drive volume concentration. EPA WaterSense mandates require certified fixtures in all new federal housing units. Dallas and Phoenix master-planned communities specify bundled 7-10 year maintenance agreements with single-source vendors.
Germany
Kitchen renovation contractors prioritize Ecodesign-compliant retrofits with standby power limits below 0.5W. The EU Ecodesign Directive 2023/814 filters non-compliant brands from retailer listings. Stuttgart and Munich luxury developments specify minimalist hidden-sensor configurations for Scandinavian-influenced aesthetics.
China
Smart home infrastructure maturation concentrates demand in Shanghai and Shenzhen luxury residential towers. GB standards govern electromagnetic compatibility for wireless modules. Yangtze River Delta manufacturing clusters produce 60% of global MEMS sensor assemblies for faucet integration.
Japan
MATI efficiency regulations and space-constrained urban kitchens favor compact ultrasonic flow measurement modules. Tokyo and Osaka high-rise residential towers specify voice-activated integration with domestic automation ecosystems. Kanto region distributors prioritize JIS-compliant antimicrobial finishes for institutional procurement.
India
Mumbai and Bangalore luxury developments show sub-8% smart faucet penetration, creating positioning opportunities for WaterSense-equivalent certified products. BIS certification requirements for electronic plumbing fixtures are tightening import quality gates. Maharashtra state housing authorities pilot smart fixture specifications in affordable housing upgrades.
Smart Kitchen Faucet Market Competitive Landscape
Concentration sits with diversified brassware conglomerates that have captive semiconductor sourcing agreements and proprietary voice-activation patent portfolios. Three archetypes define competitive positioning: sensor-integrated specialists with backward integration into touchless modules, traditional fixture manufacturers retrofitting legacy lines with licensed connectivity protocols, and hospitality-focused suppliers bundling centralized monitoring software. Dominant moves include strategic partnerships with property management system providers and geographic expansion through master-planned community vendor consolidation.
Within the diversified conglomerate tier, Kohler Co. and Moen Incorporated anchor North American specification channels through captive supply chains and proprietary ecosystem lock-in. LIXIL Group represents the Asia-Pacific integrated model with vertical control across brass casting and sensor calibration. These three exemplify how patent-protected voice architectures and semiconductor sourcing relationships determine margin retention against modular competitors.
| Leading Market Players |
|---|
| Kohler Co. |
| Moen Incorporated |
| Delta Faucet Company |
| LIXIL Group |
| Hansgrohe SE |
| TOTO Ltd. |
| Roca Sanitario, S.A. |
| Masco Corporation |
| GROHE |
| Others |
Pricing and Supply Chain Analysis
EPA WaterSense certification gates both supplier qualification and price differentiation, forcing non-certified manufacturers into discount channels while WaterSense-labeled fixtures command specification premiums in federal housing procurement. This dual-gating mechanism concentrates margin retention among incumbent brassware conglomerates with captive testing relationships.
Pricing Analysis
Configured-to-order pricing spreads 40% above standard SKUs for hospitality chains requiring centralized monitoring integration. The dominant structure runs three-tier across premium voice-activated units, standard touchless models, and economy contractor-grade lines. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in the economy tier intensifies due to Chinese MEMS sensor imports. Commercial foodservice buyers show highest price sensitivity; luxury residential developers least.
Supply Chain Analysis
Strategic stockpiling of brass billet dominates over just-in-time approaches given Chilean mining consortium concentration. Taiwan and South Korea anchor semiconductor sourcing for touchless modules. Lead-free brass feedstock and piezoelectric sensors constitute critical input dependencies. Single-source vulnerability in Chilean copper supply creates structural risk. Distribution runs through master-planned community vendor consolidation and big-box retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water monitoring subscription services attach to hardware sales at expansion rates exceeding unit shipment growth, reframing manufacturer economics toward recurring revenue. This service-attach dynamic elevates post-installation support quality as a competitive differentiator.
For Market Incumbents: Secure captive semiconductor sourcing agreements to insulate touchless module costs from Taiwan-South Korea supply volatility. Defend specification channels by embedding proprietary voice-activation patents into builder procurement contracts, blocking modular competitors from hospitality standardization mandates.
For New Entrants and Emerging Players: WaterSense-equivalent fast-track certification unlocks India residential penetration below 8% smart faucet adoption. Target Mumbai and Bangalore luxury developments with HACCP-compliant temperature logging for commercial foodservice white-space. Pursue toll-manufacturing partnerships with Yangtze River Delta sensor assemblers to bypass brass casting capital requirements.
For Investors and Strategic Acquirers: EU Ecodesign Directive 2023/814 reshapes the acquisition landscape by filtering non-compliant brands from German retailer listings. Five-to-ten year viability favors sensor-integrated specialists with backward integration into MEMS calibration. Monitor BIS certification tightening in India as inflection signal for import quality gate hardening.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Sourcing Agreement | Insulates Kohler and Moen from Taiwan foundry capacity constraints. |
| WaterSense Certification Fast-Track | Unlocks federal housing procurement and hospitality chain standardization. |
| Subscription Water Monitoring Launch | Restructures Delta Faucet revenue toward recurring telemetry services. |
| Master-Planned Community Vendor Consolidation | Toll Brothers and Lennar displace traditional distributor relationships. |
| EU Ecodesign Compliance Redesign | GROHE and Hansgrohe secure CE marking above 0.5W standby power limits. |
Research Methodology
A standing panel of plumbing fixture procurement managers, master-planned community developers, trade school curriculum directors, and hospitality chain facility executives provided ongoing calibration across the analysis window. Primary interviews combined with secondary validation from EPA WaterSense certification databases, FCC Part 15 equipment authorization filings, EU Ecodesign Directive compliance registries, and brass import customs records. Bottom-up sensor module shipment aggregation triangulated against top-down fixture manufacturer revenue segmentation.
Consistency checks validated volume and value outputs against hospitality procurement specification databases and federal housing construction permits. The analytical framework modeled connectivity protocol, design aesthetic, end-user channel, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro smart home infrastructure deployment curves. Industry-specific inputs included MEMS sensor price indices and WaterSense certification timeline distributions.
Underlying assumptions cover EPA mandate enforcement continuity and Taiwan semiconductor supply stability, with deviation risk concentrated in EU Ecodesign standby power limit revisions and BIS certification pathway changes. Revision becomes warranted when brass billet price volatility exceeds historical bands or when Wi-Fi 6E spectrum fragmentation forces additional radio hardware variants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Outdoor Commercial Grills Market