
 Europe Kitchen Appliances Market | 2026-2036
Europe Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kitchen Appliances Market Foresight
Premium kitchen appliances is decoupling from commodity tiers across Europe as energy ratings and smart connectivity become non-negotiable at the high end while price sensitivity hardens in mass-market channels. Groupe SEB leverages its multi-brand architecture to span both tiers without internal cannibalization. Miele & Cie. KG anchors its position through captive manufacturing of core components and extended warranty programs that competitors struggle to match.
Europe kitchen appliances encompass electrically or gas-powered equipment designed for food storage, preparation, cooking, and cleaning, typically operating at 220-240V/50Hz with energy efficiency classes spanning A to G under EU labeling rules. Their primary commercial purpose is reducing household labor time while meeting tightening carbon budgets in residential and foodservice environments. Refrigerators and dishwashers command the largest installed base renewals, with smart appliances representing the fastest structural expansion as Wi-Fi module costs drop below the threshold for mid-range inclusion. Energy efficient technology dominates regulatory compliance investments, while induction systems capture share from radiant electric cooktops in Western European replacement cycles.
EMA, ECHA, and the EU Ecodesign Framework collectively shape product compliance pathways, with REACH restricting certain flame retardants in plastic housings and Ecodesign mandating repairability scoring that alters design priorities. The EU Green Deal's embedded carbon tracking requirements are pushing manufacturers to document supply chain emissions for market access. Stakeholders must monitor how the EU AI Act's risk classification applies to autonomous cooking algorithms and whether national transpositions create divergent certification burdens across member states.
Market Dynamics
The EU Ecodesign Framework is forcing redesign cycles across European manufacturers as minimum efficiency thresholds tighten and repairability scoring becomes mandatory for market access.
Growth Catalysts
- Residential retrofit demand:German households are replacing aging units with connected models, accelerating replacement cycles in Western Europe's largest installed base.
- REACH compliance investments:Restrictions on flame retardants in plastic housings are pushing manufacturers toward alternative materials that command premium positioning.
- Induction technology:Induction systems are capturing share from radiant electric cooktops across French and Italian replacement markets.
Market Restraints
- Component supply concentration:Wi-Fi module sourcing remains concentrated among Asian semiconductor fabricators, exposing European OEMs to logistics volatility.
- Copper and steel input costs:Raw material price swings compress margin predictability for mid-range product lines.
- Gas infrastructure lock-in:Existing residential gas connections in Southern Europe slow electrification transitions despite efficiency advantages.
Strategic Opportunities
- Polish and Romanian underpenetration:Eastern European markets show lower smart appliance penetration rates relative to Western benchmarks.
- EU Green Deal carbon tracking:Embedded emissions documentation requirements favor early movers with supply chain visibility infrastructure.
- Autonomous cooking algorithms:The EU AI Act's risk classification framework creates first-mover advantages for compliant algorithm developers.
Industry Challenges
- Repairability scoring compliance:Ecodesign mandates require redesign of disassembly protocols and spare parts logistics.
- Legacy system integration:Smart appliance connectivity protocols must interoperate with heterogeneous home automation ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kitchen Appliances Market |
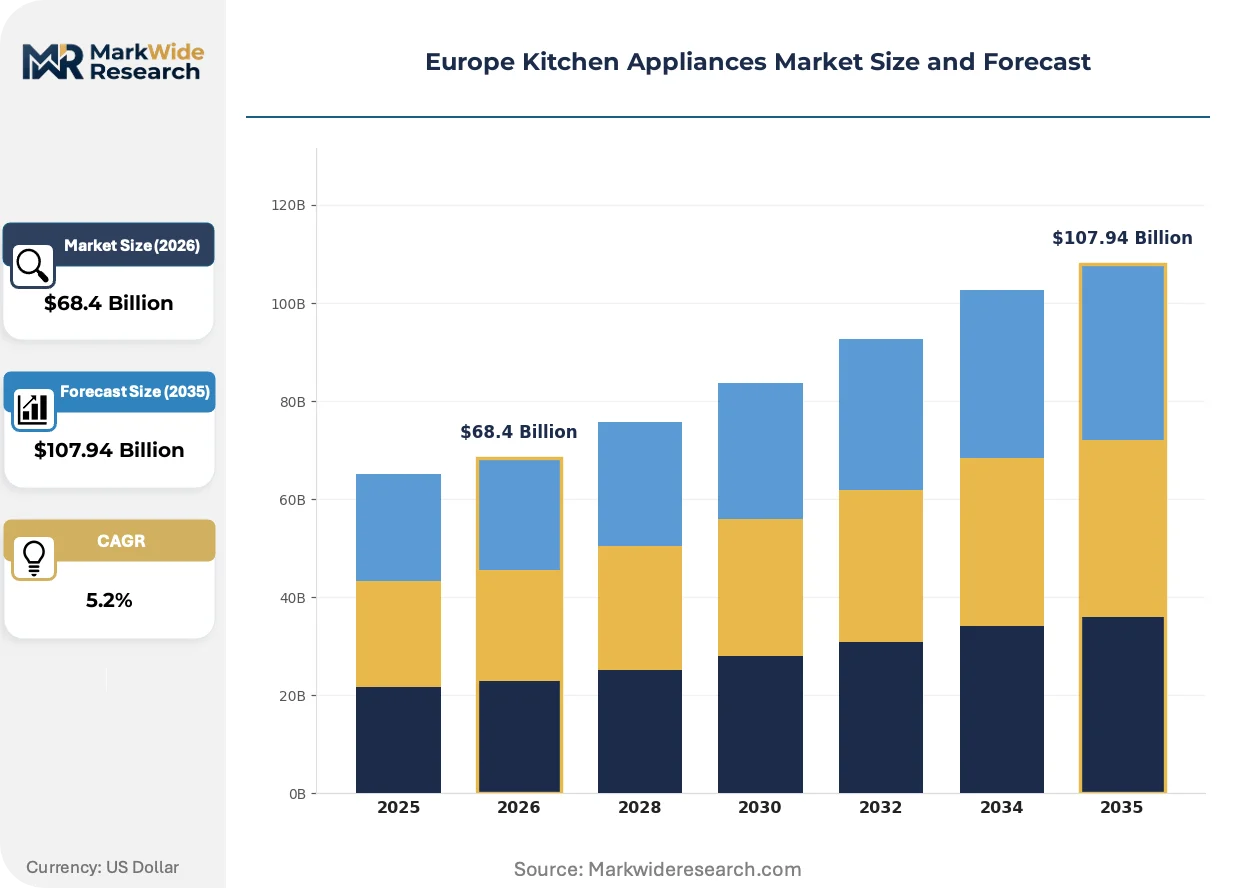
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Microwaves, Dishwashers End User: Residential, Commercial, Hospitality, Institutions Technology: Smart Appliances, Energy Efficient, Induction, Non-electric Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | Groupe SEB, Arcelik AS, BSH Home Appliances Group, De'Longhi S.p.A., Liebherr Group, Electrolux Group, Miele & Cie. KG, Haier Europe, Whirlpool Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kitchen Appliances Market Shifts & Advancements
Wi-Fi module cost compression is reshaping product architecture across mid-range tiers, while regulatory compliance investments increasingly determine competitive positioning.
Induction cooking technology is absorbing market share from conventional radiant electric systems as efficiency advantages align with tightening EU energy labels. Italian and French kitchen renovators are specifying induction surfaces at accelerating rates. The technology is absorbing what had been stable replacement demand for legacy electric cooktops.
The EU Ecodesign Framework's repairability index is mandating design-for-disassembly protocols that alter component selection and fastening methodologies. Manufacturers must now score products on spare parts availability and documentation accessibility. Dishwasher and refrigerator categories face the most stringent scoring thresholds, forcing supply chain reconfigurations.
Channel consolidation among European kitchen retailers is compressing manufacturer negotiation leverage and reshaping go-to-market economics. Specialist chains in Germany and France are demanding exclusive product configurations and extended payment terms. This concentration is most visible in premium segment distribution, where assortment control determines brand visibility.
Europe Kitchen Appliances Market Segmentation
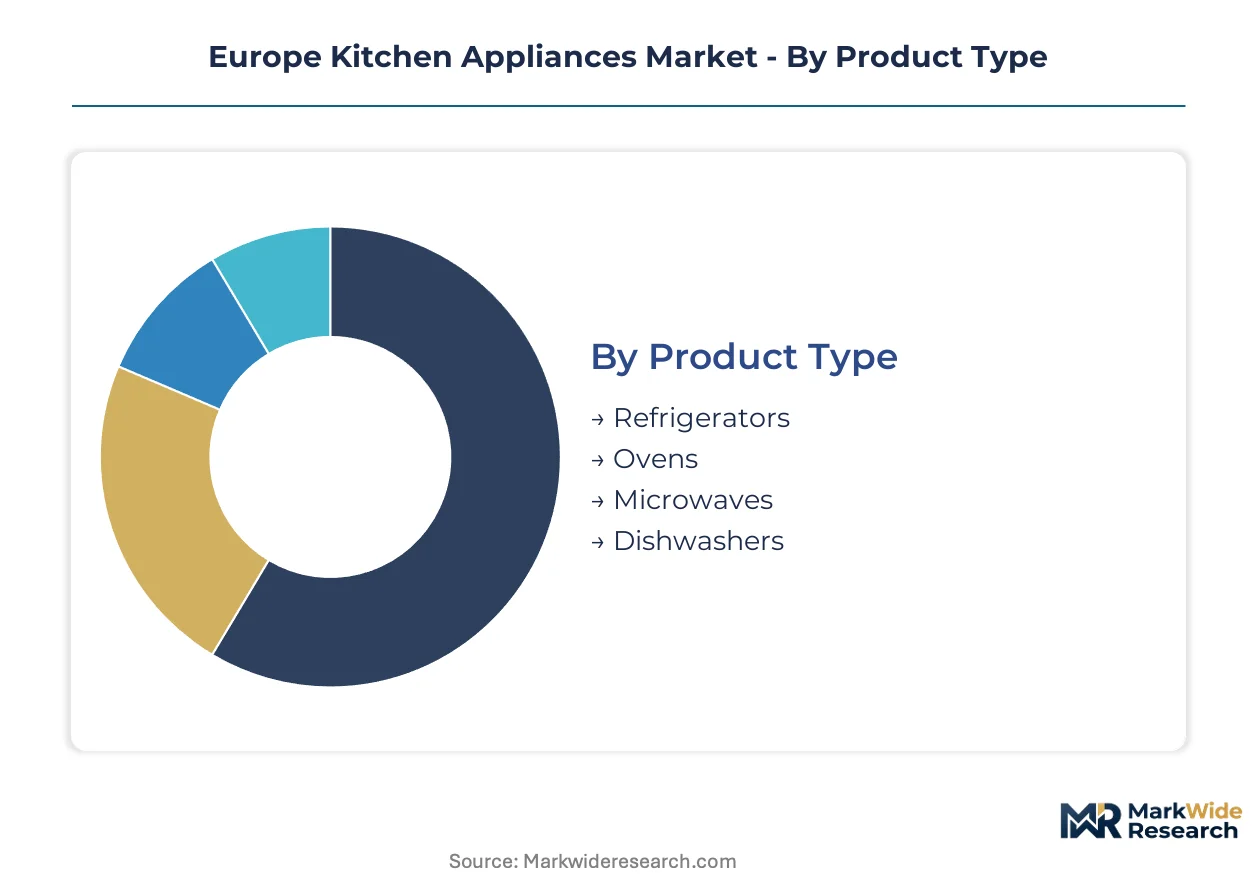
Segmentation in the Europe Kitchen Appliances Market reveals how regulatory compliance costs, channel economics, and technology transitions concentrate profit pools differently across product tiers. Manufacturers must align certification investments with segment-specific margin structures.
Product Type:
Refrigerators and dishwashers face the most stringent Ecodesign repairability scoring under EU regulations, while ovens and microwaves navigate varying energy label thresholds that reshape R&D allocation.
- Refrigerators:Compressor-based cooling systems with variable-speed drives dominate efficiency upgrades. German and Italian residential retrofits drive demand for connected models with embedded carbon tracking compliance.
- Ovens:Convection and steam-assist configurations span gas and electric fuel types. French kitchen renovation cycles favor pyrolytic self-cleaning variants that command premium positioning in specialist retail channels.
- Microwaves:Inverter technology variants replace magnetron-based systems across mid-range tiers. REACH compliance for plastic housings adds material cost pressure without commensurate price recovery in mass-market channels.
- Dishwashers:Heat pump and condensation drying systems reduce water consumption per cycle. Ecodesign mandates on spare parts availability force redesign of pump and seal architectures.
Refrigerators sit at the top of the volume ranking, with dishwashers climbing the fastest.
End User:
Customer procurement patterns diverge sharply between price-sensitive residential replacement cycles and specification-driven commercial tenders that demand extended warranty terms.
- Residential:Individual households purchasing through retail channels with financing options. German replacement demand accelerates as aging installed base hits end-of-life thresholds.
- Commercial:Restaurants and catering operations prioritizing throughput and durability over efficiency ratings. CE marking and national food safety certifications create multi-layer approval requirements.
- Hospitality:Hotel chains and serviced accommodation specifying uniform room configurations. Procurement concentrates through group purchasing organizations with volume rebate structures.
- Institutions:Hospitals, schools, and military facilities operating under public tender rules. EU Green Deal carbon disclosure requirements add documentation burden to contract eligibility.
Residential captures the dominant revenue share, though hospitality procurement is expanding most quickly as chain consolidation accelerates.
Technology:
Module cost curves and regulatory thresholds determine which technology tiers achieve viable price positioning in mid-range versus premium channels.
- Smart Appliances:Wi-Fi-enabled units with app control and usage analytics. Wi-Fi module cost compression below mid-range inclusion thresholds is reshaping product architecture across Polish and Romanian markets.
- Energy Efficient:A-rated and above appliances meeting tightened EU energy label minimums. Ecodesign Framework redesign cycles force component upgrades that compress margins in price-sensitive segments.
- Induction:Electromagnetic cooking surfaces displacing radiant electric and gas systems. Italian and French kitchen renovators specify induction at accelerating rates due to efficiency advantages.
- Non-electric:Gas and solid-fuel appliances retaining share in Southern European markets with existing infrastructure. Gas infrastructure lock-in slows electrification transitions despite regulatory pressure.
Energy Efficient technology holds the largest installed base, while Smart Appliances are gaining share fastest as connectivity becomes standard above entry tiers.
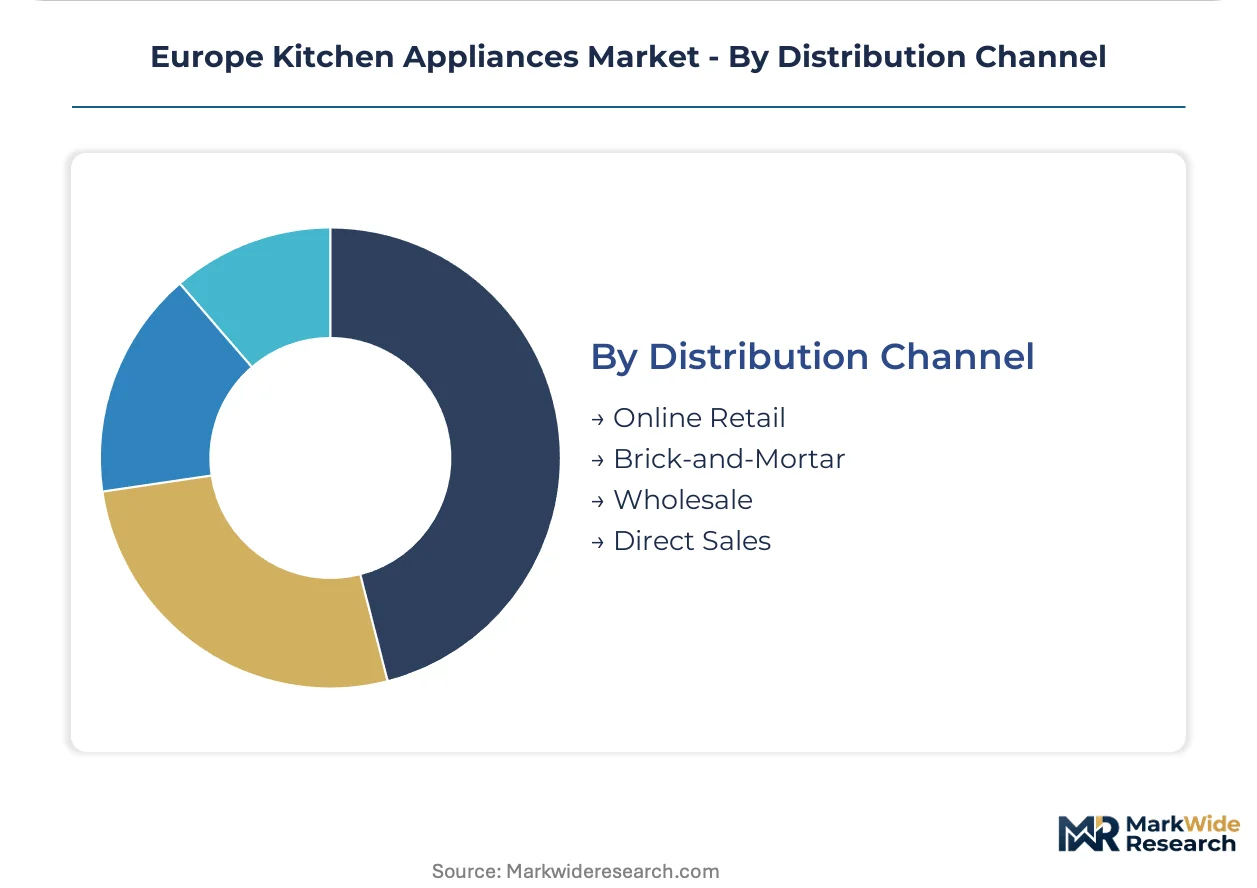
Distribution Channel:
Channel concentration among specialist retailers is compressing manufacturer negotiation leverage and reshaping go-to-market economics across premium and mass-market tiers.
- Online Retail:Platform-based sales with comparison tools and delivery logistics. Price transparency intensifies margin pressure on mid-range product lines.
- Brick-and-Mortar:Specialist kitchen retailers and electronics chains with showroom displays. German and French specialist chains demand exclusive configurations and extended payment terms.
- Wholesale:Builder merchants and trade distributors serving renovation contractors. Volume flows concentrate through consolidated regional players with private label development capabilities.
- Direct Sales:Manufacturer-owned stores and B2B account teams for institutional tenders. Extended warranty and service bundling differentiates positioning in commercial segments.
Brick-and-Mortar maintains the highest transaction value per unit, with Online Retail showing the steepest expansion trajectory as logistics networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled appliance engineering talent clusters in Germany's industrial belt, anchoring European manufacturing expertise for premium kitchen equipment. French and Italian design heritage sustains distinct regional specializations in aesthetic-forward product development. Eastern European assembly operations leverage proximity to Western consumer markets with lower operational overhead.
Germany
Residential retrofit demand accelerates as aging installed base reaches end-of-life thresholds. The EU Ecodesign Framework mandates repairability scoring that forces redesign of disassembly protocols. Bavaria's industrial corridor hosts captive manufacturing operations where core component production sustains extended warranty programs.
France
Kitchen renovation rates remain structurally elevated with premium brand loyalty concentrated in specialist retail channels. REACH restrictions on flame retardants push manufacturers toward alternative plastic housing materials. The Île-de-France region anchors distribution infrastructure serving high-end Parisian renovation contractors.
Italy
Induction cooking surfaces displace radiant electric systems at accelerating rates among kitchen renovators. CE marking requirements layer with national food safety certifications for commercial segment access. Lombardy's manufacturing base supplies pyrolytic self-cleaning oven variants to specialist chains demanding exclusive configurations.
Poland
Smart appliance penetration rates trail Western European benchmarks, creating expansion headroom for connectivity-enabled mid-range products. The EU Green Deal's embedded carbon tracking requirements favor early movers with supply chain visibility infrastructure. Warsaw's logistics networks consolidate distribution for Eastern European retail expansion.
Netherlands
Online retail penetration intensifies price transparency pressure across mid-range product lines. ECHA compliance investments for alternative materials command premium positioning without full cost recovery. The Randstad's dense urban housing stock drives compact appliance specifications for space-constrained installations.
Europe Kitchen Appliances Market Competitive Landscape
Top-tier vendors anchor premium positioning through captive manufacturing and extended warranty bundling, while mid-scale players compete on module cost compression and channel reach. The vendor base spans multi-brand conglomerates, family-owned specialists, and Asian-backed European operations. Strategic archetypes include vertical integration specialists, multi-brand portfolio managers, and scale-driven mass-market suppliers. Competitive moves concentrate on exclusive retail configurations and supply chain carbon documentation infrastructure.
Within the multi-brand tier, Groupe SEB and Electrolux Group exemplify portfolio architectures that span price segments without internal cannibalization. Miele & Cie. KG anchors family-owned positioning through in-house production of core components. Among Asian-backed operations, Haier Europe occupies a position leveraging manufacturing scale for mid-range connectivity inclusion.
| Leading Market Players |
|---|
| Groupe SEB |
| Arcelik AS |
| BSH Home Appliances Group |
| De'Longhi S.p.A. |
| Liebherr Group |
| Electrolux Group |
| Miele & Cie. KG |
| Haier Europe |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
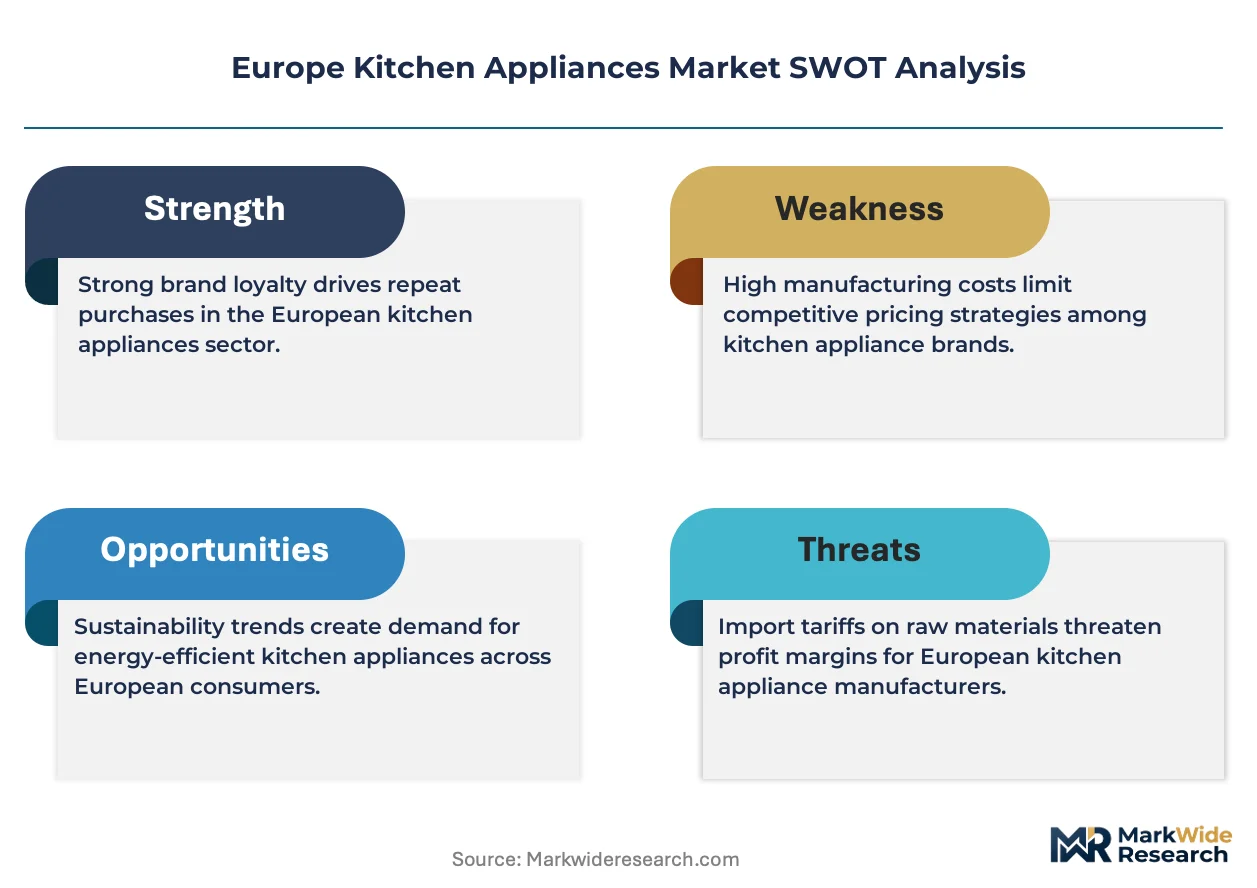
German specialist retailers demanding exclusive product configurations and extended payment terms are forcing manufacturers to absorb financing costs while redesigning channel economics. This buyer consolidation concentrates negotiation leverage among fewer retail gatekeepers, compressing margin recovery in mid-range tiers and accelerating unbundling of after-sales services.
Pricing Analysis
Extended warranty bundling versus unbundled transactional sales separates premium positioning from mass-market penetration. Three-tier pricing structure across premium, standard, and economy levels reflects energy label certification tiers and smart connectivity inclusion. Pricing pressure stems from online retail price transparency that strips margin buffers from mid-range refrigerator and dishwasher lines. Residential replacement buyers exhibit highest price sensitivity, while hospitality procurement tolerates premium positioning for uniform fleet specifications.
Supply Chain Analysis
Direct-to-specialist-retail channels handle premium buyer demand while wholesale builder merchants serve renovation contractors across Germany and France. Component sourcing concentrates in China, South Korea, and Taiwan for Wi-Fi modules and semiconductor controls. Steel, copper, and rare-earth magnet dependencies expose margin predictability to commodity price swings. Single-source vulnerability in Asian semiconductor fabricators creates logistics volatility that European OEMs cannot easily diversify.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Kitchen Appliances Market functions as a stable compounder anchored by mandatory Ecodesign redesign cycles that perpetuate replacement demand. Regulatory compliance investments create recurring revenue streams for component suppliers and certified manufacturers.
For Market Incumbents: Cement captive manufacturing of compressor and induction coil components to defend against Asian-backed scale entrants. Prioritize repairability scoring compliance ahead of Ecodesign enforcement deadlines to lock in specialist retail shelf space. Extend warranty programs beyond competitor matching thresholds to capture hospitality procurement contracts. For New Entrants and Emerging Players: Platform-based direct sales routes offer lowest-friction entry for smart appliance penetration in Polish and Romanian markets. Target underpenetrated Eastern European connectivity adoption with mid-range Wi-Fi-enabled refrigeration. Partner with Warsaw logistics consolidators to bypass established German retail gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with supply chain visibility infrastructure providers serving EU Green Deal carbon documentation mandates. Five-to-ten year viability favors manufacturers with backward integration into core components and repairability scoring capabilities. Monitor Wi-Fi module cost compression velocity as inflection indicator for smart appliance mass-market viability.| Strategic Initiative | Industry Significance |
|---|---|
| Repairability Scoring Compliance | Ecodesign mandates force redesign of disassembly protocols for dishwasher and refrigerator architectures. |
| Supply Chain Carbon Documentation | EU Green Deal embedded emissions tracking favors early movers with supplier visibility infrastructure. |
| Smart Connectivity Inclusion | Wi-Fi module cost compression enables mid-range product architecture across Eastern European markets. |
| Exclusive Retail Configuration | German and French specialist chains demand unique SKUs that compress manufacturer negotiation leverage. |
| Extended Warranty Bundling | Miele-style service programs differentiate premium positioning where competitors struggle to match terms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume flows and channel dynamics. Primary discussions with appliance engineering directors, category buyers at German specialist retailers, procurement leads at hospitality group purchasing organizations, and Ecodesign compliance officers informed demand-side assumptions. Secondary validation drew from EU Ecodesign implementing measures, REACH restriction updates, customs trade data for component imports, and SEC filings of listed appliance manufacturers. Bottom-up SKU-level modeling and top-down category spend estimates were cross-referenced for triangulation.
Segment-weighting approaches allocated revenue across product type, end user, technology tier, and distribution channel dimensions. Growth projections across the analysis window applied category-specific replacement cycle assumptions and regulatory compliance cost pass-through rates. CAGRs were derived from installed base renewal modeling and penetration curve analysis for smart appliances. Energy label threshold tightening and Wi-Fi module cost trajectories served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for induction cooking displacement of gas systems would alter the outlook. Forecasts reflect documented assumptions regarding Ecodesign enforcement timing and carbon tracking implementation scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Cookware Accessories Market