
 United States Microwave Oven Market | 2026-2036
United States Microwave Oven Market Size, Share, and Industry Trends Forecast 2026-2036
United States Microwave Oven Market Analytics
Appliance procurement among multi-family housing developers is broadening across mid-market rental construction, pulling volume from traditional single-family channels. Whirlpool Corporation leverages its builder-direct program to sustain contract relationships with national developers. Samsung Electronics America competes through smart-kitchen ecosystem integration that anchors premium specification tiers. LG Electronics USA differentiates via inverter technology leadership that commands higher average selling prices in new-build installations.
A microwave oven is an electric appliance that generates electromagnetic radiation at frequencies near 2.45 GHz to excite water molecules and produce thermal energy for cooking or reheating food, with cavity sizes typically ranging from 0.5 to 2.2 cubic feet and power ratings from 600 to 1,200 watts for residential units. Its primary commercial purpose spans rapid food preparation in constrained spaces across residential kitchens, quick-service restaurants, and institutional cafeterias. Countertop units dominate unit shipments though built-in and over-the-range configurations capture disproportionate margin pools through kitchen-design integration. Smart technology segments are expanding fastest as Wi-Fi connectivity and voice-assistant compatibility shift replacement cycles, while traditional control-panel models occupy value-tier positions in mass retail.
The DOE maintains federal minimum efficiency standards under 10 CFR Part 430 that constrain standby power and cooking efficiency test procedures for microwave ovens sold in the United States. OSHA workplace safety guidelines affect commercial installation requirements in restaurant and food-service environments. Stakeholders must monitor DOE rulemaking dockets for potential test procedure revisions that could alter product design requirements and compliance costs.
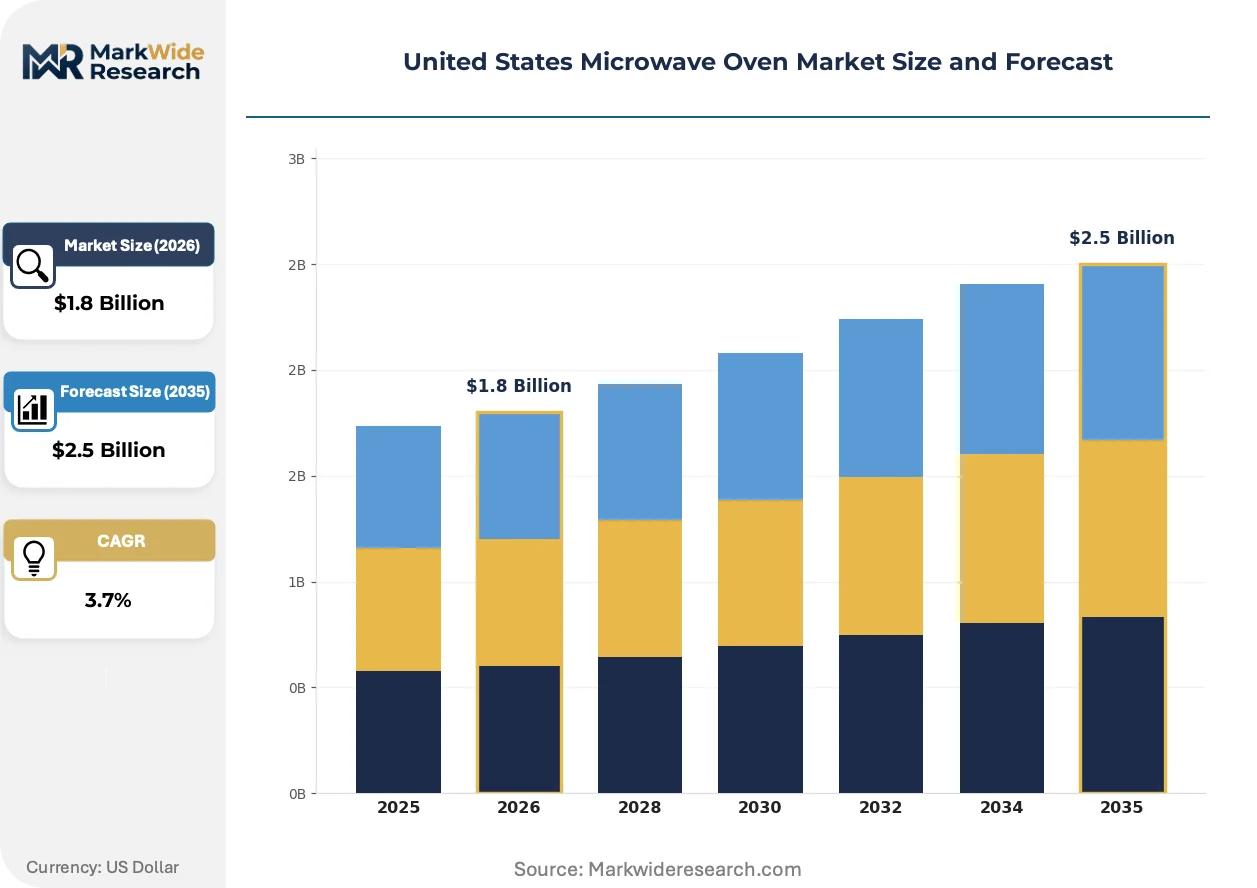
Market Dynamics
Multi-family residential construction corridors in Texas and Florida are pulling procurement volume from single-family channels, while DOE efficiency standards under 10 CFR Part 430 force magnetron redesigns that compress supplier margins.
Growth Catalysts
- Multi-family housing construction:Developers in Houston, Dallas, Miami, and Orlando are expanding appliance procurement budgets for mid-market rental units. This pulls volume from traditional single-family distribution channels.
- Smart-kitchen ecosystem integration:Wi-Fi connectivity and voice-assistant compatibility are compressing replacement cycles. Premium specification tiers now require connected functionality as standard.
- 10 CFR Part 430 compliance:Federal minimum efficiency standards for standby power and cooking efficiency create design barriers that favor suppliers with R&D scale.
Market Restraints
- Magnetron supply concentration:Power tube manufacturing concentrates among a limited supplier base in Asia. This creates input vulnerability for domestic oven assemblers.
- Substitution by combi-ovens:Convection-microwave hybrid units and air-fryer configurations are displacing standalone microwave demand in premium kitchen renovations.
- OSHA commercial installation requirements:Workplace safety guidelines for restaurant and food-service environments add compliance friction and installation cost.
Strategic Opportunities
- Inverter technology premiumization:Variable power control enables gentler heating and defrosting. This commands higher average selling prices in new-build installations.
- Builder-direct channel expansion:National multi-family developers seek consolidated procurement relationships. Direct contracting bypasses retail margin stacking.
- Voice-assistant platform convergence:Integration with Amazon Alexa and Google Home ecosystems creates specification lock-in. Smart kitchen platforms anchor replacement demand.
Industry Challenges
- DOE test procedure revision timeline:Pending rulemaking dockets could alter cooking efficiency measurement protocols. Product development cycles must anticipate compliance shifts.
- Magnetron power-draw threshold engineering:Tightening standby power standards require fundamental redesign of power supply architectures. Legacy platforms face obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Microwave Oven Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Over-the-Range, Convection Technology: Traditional, Inverter, Smart, Sensor Cooking End User: Residential, Commercial, Restaurants, Cafes Distribution Channel: Online, Offline, Retail Stores, Specialty Stores |
| Companies Covered | Whirlpool Corporation, Samsung Electronics America, LG Electronics USA, GE Appliances, Electrolux Home Products, Panasonic Corporation of North America, BSH Home Appliances Corporation, Sharp Electronics Corporation, Breville USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Microwave Oven Market Evolving Landscape
Smart connectivity and inverter-based power control are fragmenting the traditional value-tier market. Specification requirements now diverge sharply between mass retail and builder-direct channels.
Inverter power supply technology is decentralizing thermal control across residential and commercial segments. Traditional magnetron-on/off cycling produces uneven heating that degrades food texture. Variable power inverters enable continuous low-power operation that improves defrosting and reheating outcomes. Multi-family developers and premium kitchen designers are specifying inverter platforms for new construction at accelerating rates. This is decentralizing purchasing authority from retail consumers toward specification professionals.
The DOE maintains active rulemaking under 10 CFR Part 430 that revises microwave oven test procedures. Proposed amendments would modify cooking efficiency measurement protocols and standby power thresholds. Domestic manufacturers face compliance cost escalation if test procedure changes require platform redesign. The built-in and over-the-range configuration segments are most exposed, as these higher-margin products carry greater redesign investment per SKU.
Builder-direct procurement is consolidating volume among national multi-family developers. Traditional retail distribution through big-box and appliance specialty channels faces margin compression as developers negotiate enterprise pricing. Volume concentration in Texas and Florida metro corridors is shifting regional demand patterns. This channel rotation is most visible in Houston, Dallas, Miami, and Orlando construction markets where multi-family permit activity exceeds national averages.
United States Microwave Oven Market Segmentation
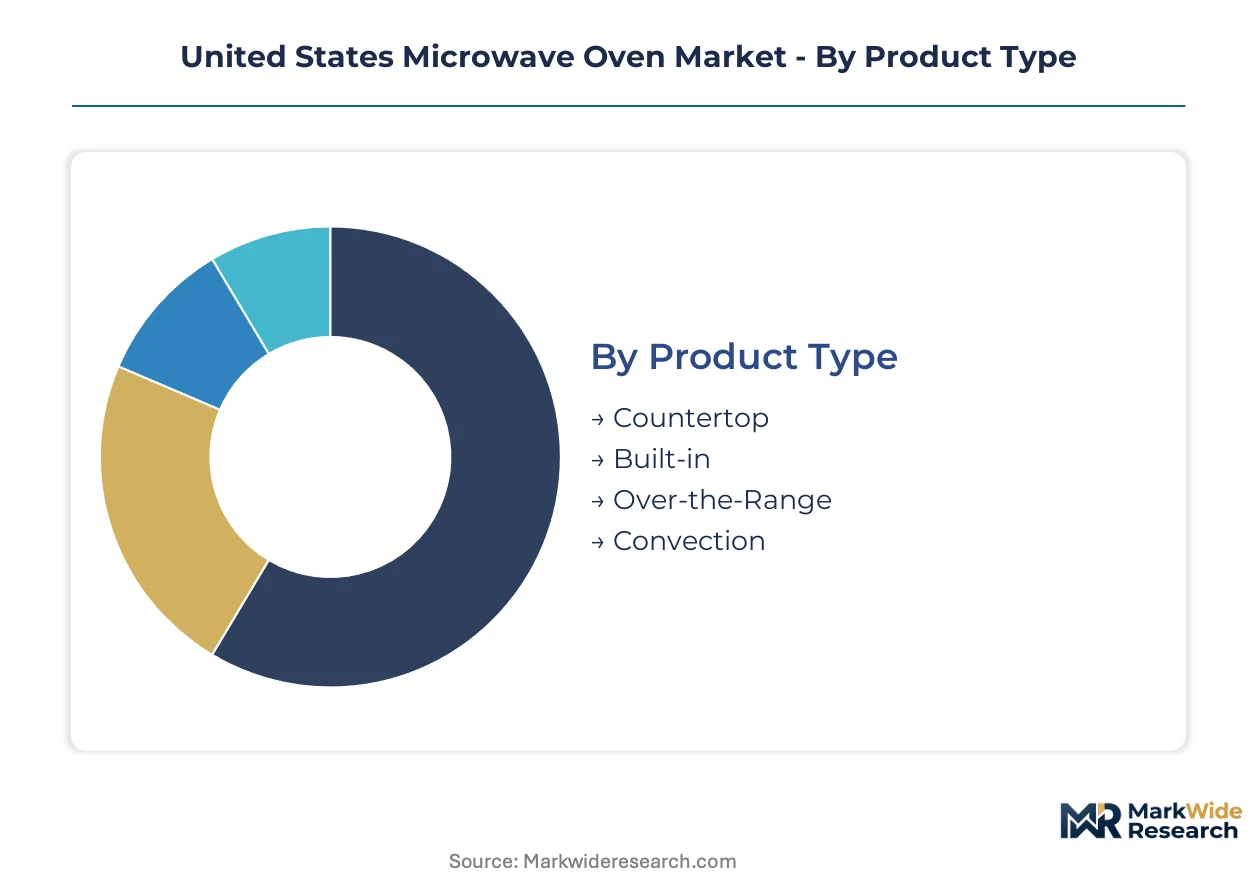
Microwave oven segmentation in the United States reflects divergent channel economics. Product configuration determines margin structure, while technology tier separates replacement-cycle velocity. End-user concentration in multi-family housing and distribution-channel consolidation reshape competitive access points.
Product Type:
Countertop units dominate unit shipments while built-in and over-the-range configurations capture disproportionate margin pools through kitchen-design integration.
- Countertop:Freestanding units with 0.5 to 2.2 cubic foot cavities and 600-1,200 watt ratings. Mass retail channels in Texas and Florida metro corridors move highest volumes for apartment turnover and rental replacement cycles.
- Built-in:Cabinet-integrated designs requiring custom trim kits and professional installation. Premium kitchen renovations in Dallas and Miami specify these for aesthetic continuity, though combi-oven substitution erodes standalone demand.
- Over-the-Range:Combined ventilation-cooking units mounted above cooktops. New-build multi-family installations in Houston and Orlando favor these for space efficiency in constrained floor plans.
- Convection:Hybrid thermal systems adding forced-air circulation to microwave energy. Food-service operators in quick-service restaurants specify these for menu flexibility despite higher capital cost.
Today's leader: Countertop. Tomorrow's challenger: Over-the-Range.
Technology:
Smart connectivity and inverter-based power control fragment the traditional value-tier market, with DOE efficiency standards under 10 CFR Part 430 accelerating platform turnover.
- Traditional:Magnetron-on/off cycling with fixed power levels. Mass retail channels in value-tier positions rely on these for price-sensitive replacement demand, though uneven heating degrades food texture.
- Inverter:Variable power supply enabling continuous low-wattage operation. LG Electronics USA leverages this technology to command higher average selling prices in new-build installations across Florida and Texas.
- Smart:Wi-Fi connectivity and voice-assistant compatibility. Samsung Electronics America anchors premium specification tiers through ecosystem integration with Amazon Alexa and Google Home platforms.
- Sensor Cooking:Humidity-detection algorithms adjusting cycle time and power. Residential users in Orlando and Miami metro areas specify these for convenience in high-turnover rental units.
Traditional platforms anchor current volume. Smart segments gain share fastest through compressed replacement cycles.
End User:
Multi-family residential developers concentrate procurement authority, pulling volume from single-family channels and fragmenting demand across commercial sub-segments.
- Residential:Single-family homeowners and apartment dwellers. Replacement cycles in Texas and Florida metro construction corridors drive consistent demand through retail and builder-direct channels.
- Commercial:Institutional cafeterias and non-restaurant food-service operations. OSHA workplace safety guidelines add compliance friction for installation requirements.
- Restaurants:Quick-service and fast-casual operators. Convection-microwave hybrid configurations displace standalone units in back-of-house equipment specifications.
- Cafes:Limited-service beverage and light-food outlets. Smaller cavity sizes and lower wattage ratings match constrained counter space and intermittent heating needs.
Residential commands absolute volume. Commercial segments offer margin expansion through specification lock-in.
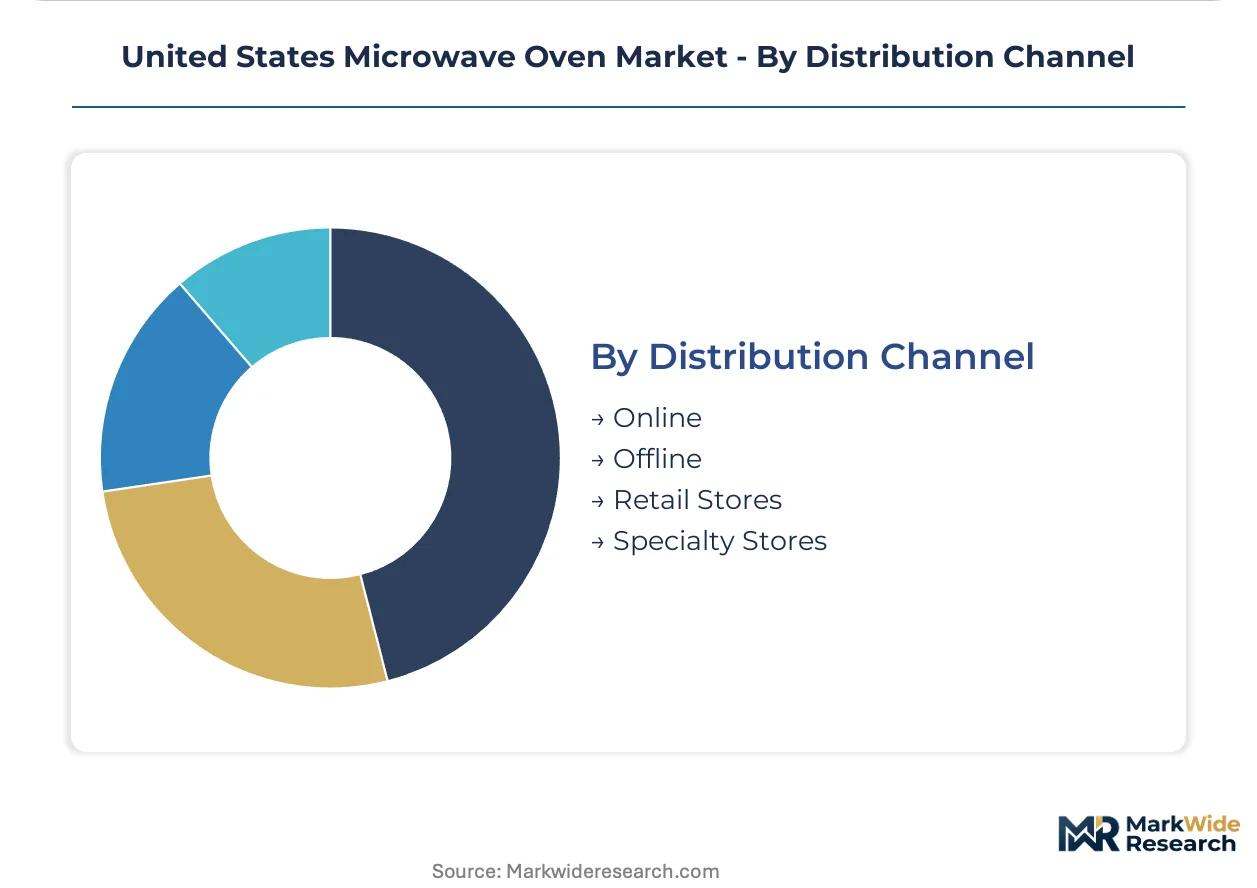
Distribution Channel:
Builder-direct contracting consolidates volume among national developers, bypassing traditional retail margin stacking in Texas and Florida construction corridors.
- Online:E-commerce platforms with direct-to-consumer fulfillment. Smart-technology segments expand fastest here as Wi-Fi connectivity and voice-assistant compatibility shift replacement cycles.
- Offline:Big-box and appliance specialty stores with in-person consultation. Value-tier traditional models occupy these channels for price-sensitive replacement demand.
- Retail Stores:Mass merchants with broad household appliance assortments. Countertop units dominate shelf space in Houston, Dallas, Miami, and Orlando metro markets.
- Specialty Stores:Kitchen-design showrooms and contractor supply houses. Built-in and over-the-range configurations capture disproportionate attention through design-integration services.
Offline retail maintains volume leadership. Builder-direct channels are climbing the fastest as multi-family procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled appliance manufacturing labor and multi-family construction trades concentrate in the Sun Belt and industrial Midwest, anchoring regional demand patterns for microwave oven procurement.
Texas
Houston and Dallas metro construction corridors drive multi-family residential permit activity that pulls appliance volume from traditional single-family channels. The DOE maintains active rulemaking under 10 CFR Part 430 that revises efficiency test procedures affecting products sold statewide. San Antonio and Austin developers specify inverter-equipped units for mid-market rental installations at accelerating rates.
Florida
Miami and Orlando metro areas concentrate demand for over-the-range configurations in space-constrained apartment floor plans. OSHA workplace safety guidelines affect commercial installation requirements in restaurant and food-service environments across the state. Tampa-St. Petersburg corridor developers negotiate enterprise pricing through builder-direct channels that bypass retail margin stacking.
California
Los Angeles and San Francisco Bay Area housing markets prioritize smart-kitchen ecosystem integration with Wi-Fi connectivity and voice-assistant compatibility. The California Energy Commission maintains appliance efficiency regulations that exceed federal minimums under 10 CFR Part 430. San Diego and Sacramento metro construction shows preference for built-in configurations in premium kitchen renovations.
Illinois
Chicago metro multi-family development sustains consistent procurement volume for countertop replacement cycles in rental turnover. The DOE appliance efficiency standards constrain magnetron power-draw thresholds for units distributed through Midwest retail channels. Rockford and Peoria industrial clusters support regional distribution logistics for builder-direct contracting.
New York
New York City metro area housing stock favors compact countertop units for apartment dwellers with constrained kitchen spaces. The state's building energy codes incorporate federal appliance standards that affect specification requirements. Buffalo and Rochester construction markets show emerging demand for convection-microwave hybrid configurations in renovation projects.
United States Microwave Oven Market Competitive Landscape
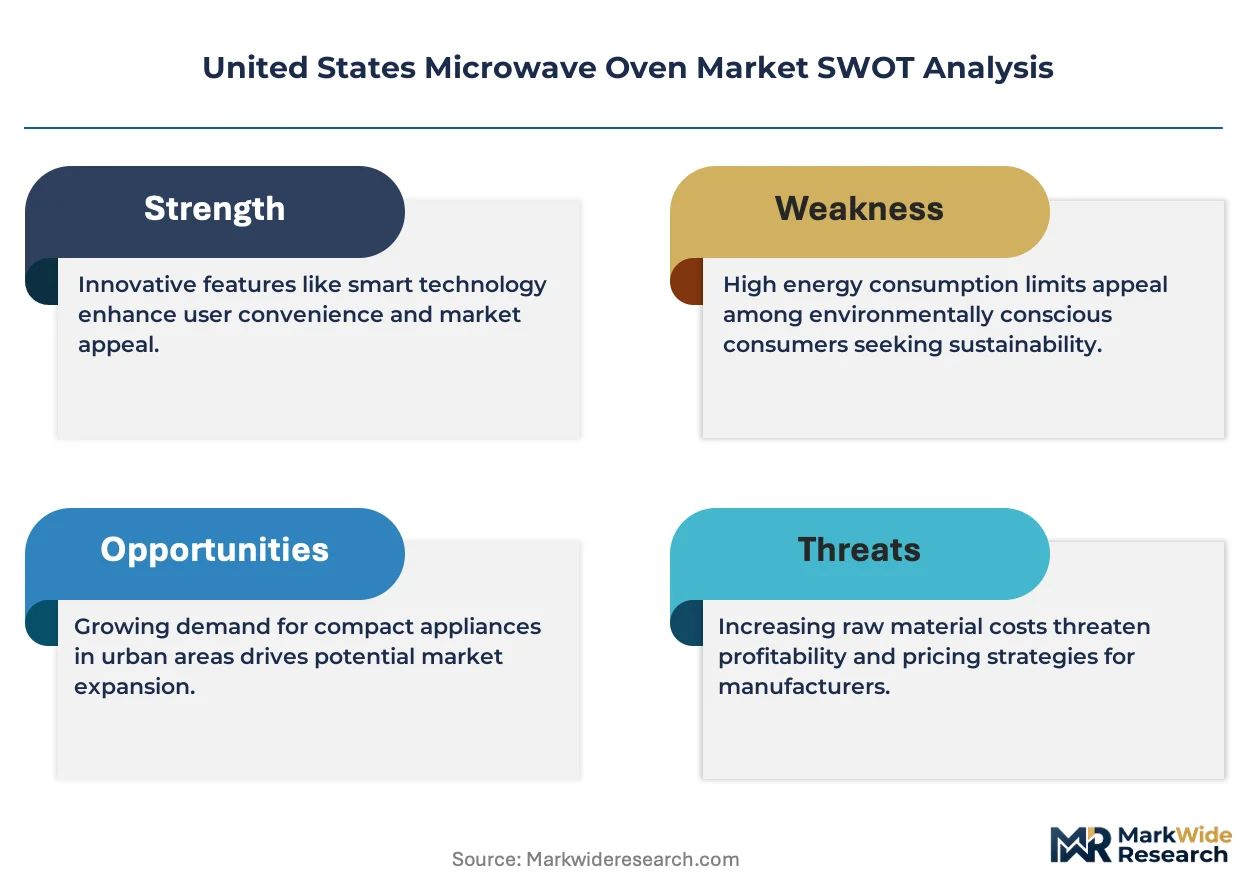
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans three strategic archetypes: diversified home appliance conglomerates with full kitchen portfolios, electronics specialists leveraging semiconductor and display expertise, and premium small-appliance specialists commanding design-tier positioning. Competitive moves concentrate on builder-direct channel expansion and smart-kitchen ecosystem integration rather than manufacturing capacity expansion.
Within the diversified conglomerate tier, Whirlpool Corporation and GE Appliances exemplify full-portfolio home appliance manufacturers with established builder-direct programs. Samsung Electronics America and LG Electronics USA represent electronics specialists translating display and semiconductor capabilities into smart-kitchen platform integration. Breville USA occupies the premium specialist position with design-forward positioning in countertop configurations. These three archetypes anchor competitive dynamics as procurement authority shifts from retail consumers toward specification professionals in multi-family development.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics America |
| LG Electronics USA |
| GE Appliances |
| Electrolux Home Products |
| Panasonic Corporation of North America |
| BSH Home Appliances Corporation |
| Sharp Electronics Corporation |
| Breville USA |
| Others |
Value Network & Pricing Analysis
Multi-family residential developers consolidating procurement authority in Texas and Florida metros operate on enterprise contract pricing that compresses retail margin structures. This buyer concentration shifts pricing power toward volume-tier negotiations and away from traditional shelf-price positioning.
Pricing Analysis
Installation bundling separates the market into unbundled countertop units and fully integrated built-in configurations with professional trim-kit fitting. Three-tier pricing structure across premium, standard, and economy levels reflects inverter technology certification and smart connectivity integration as primary differentiation drivers. Pricing pressure stems from magnetron supply constraints and DOE efficiency compliance costs that squeeze mid-tier supplier margins. Value-tier traditional models face acute buyer price sensitivity in mass retail channels, while premium inverter-equipped platforms command pricing resilience in builder-direct specifications.
Supply Chain Analysis
Domestic-content mandates under federal procurement guidelines reshape sourcing patterns for magnetron tubes and power supply components. Manufacturing concentration centers on China, South Korea, and Mexico for microwave oven assembly and component fabrication. Raw material dependencies include ferrite cores for magnetron construction, copper windings for transformer assemblies, and cold-rolled steel for cavity enclosures. Supply chain risk manifests through single-source vulnerability in high-voltage capacitor sourcing from Asian suppliers. Distribution runs through big-box retail networks, appliance specialty channels, and direct builder-contracting programs serving multi-family development corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification professionals in multi-family development increasingly prioritize inverter-based power control and smart-kitchen integration over entry-tier replacements.
For Market Incumbents: Cement builder-direct relationships with national developers in Houston, Dallas, Miami, and Orlando through dedicated account programs that bypass retail margin stacking. Secure captive supply agreements for magnetron tubes to mitigate Asian supplier concentration risk. Invest in DOE 10 CFR Part 430 pre-compliance engineering to avoid platform redesign costs when test procedure revisions finalize. For New Entrants and Emerging Players: Regional quick-service restaurant chains represent an underserved buyer archetype seeking convection-microwave hybrid configurations for menu flexibility. Target commercial food-service operators in Florida and Texas metros where OSHA installation requirements create specification friction that specialized vendors can navigate. Pursue white-glove installation bundling as the primary go-to-market angle to differentiate from mass retail competitors. For Investors and Strategic Acquirers: Diversified home appliance conglomerates are the most active acquirer in this space, seeking smart-kitchen platform capabilities and inverter technology IP. The five-to-ten year viability window favors targets with established builder-direct channels and DOE compliance infrastructure. Acquisition target archetypes include premium small-appliance specialists with design-tier positioning and regional distributors with multi-family developer relationships. Monitor DOE rulemaking docket activity as the signal to watch for inflection timing in compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Platform Expansion | Variable power control commands premium positioning in new-build multi-family specifications across Texas and Florida. |
| Builder-Direct Channel Development | National developer relationships bypass retail margin stacking and anchor replacement cycle visibility. |
| Smart-Kitchen Ecosystem Integration | Voice-assistant compatibility with Amazon Alexa and Google Home platforms creates specification lock-in. |
| DOE Pre-Compliance Engineering Investment | Anticipating 10 CFR Part 430 test procedure revisions avoids legacy platform obsolescence risk. |
| Magnetron Supply Diversification | Reducing Asian supplier concentration mitigates input vulnerability for domestic oven assemblers. |
Research Methodology
Direct dialogue with multi-family development procurement directors, appliance retail category managers, commercial food-service equipment specifiers, and DOE regulatory affairs consultants grounded the qualitative foundation. Secondary validation drew from DOE rulemaking dockets under 10 CFR Part 430, OSHA workplace safety guidelines, multi-family housing permit databases, and appliance manufacturer SEC filings. Bottom-up shipment modeling triangulated against top-down construction spending analysis across the projection horizon.
Segment-level outputs for product configuration, technology tier, end-user vertical, and distribution channel were generated through structured elasticity modeling. CAGRs were derived from regression analysis against housing starts, replacement cycle compression rates, and efficiency standard implementation timelines. Industry-specific forecast inputs included magnetron supply lead times and smart-appliance adoption curves in builder specifications.
Underlying measurement precision varies by segment; countertop unit forecasts carry tighter precision than emerging convection-hybrid categories where substitution patterns remain unstable. Forecasts reflect assumptions around DOE rulemaking timelines and multi-family construction permit trajectories that could shift with interest rate movements or regional zoning changes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
United Kingdom Compact Dishwasher Market
Appliances
United States Washing Machine Market
Appliances
Smart Connected Washing Machine Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Household Beauty Appliances Market
Appliances
Japan Laundry Appliances Market
Appliances
Toaster Ovens Market
Appliances
China Induction Hobs Market
Appliances
Global Electric Water Heaters Market
Appliances
Household Vacuum Cleaners Market
Appliances
UAE Dishwasher Market
Appliances
Minibar Refrigerators Market
Appliances
Electric Hand Dryer Market
Appliances
United States Electric Kettle Market
Appliances
GCC Dishwashers Market
Appliances
Large Cooking Appliance Market