
 Insulated Tumblers Market | 2026-2036
Insulated Tumblers Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Tumblers Market Foresight
Vacuum-insulated manufacturing is reconfiguring how thermal retention gets engineered into portable drinkware. YETI Holdings dominates premium positioning through controlled distribution and in-house production of rotomolded components. Hydro Flask leverages sustainability messaging and powder-coated finishes to differentiate within outdoor retail channels. Zojirushi anchors Asian market presence through precision-engineered sealing mechanisms and electropolished stainless steel interiors.
Insulated tumblers are double-walled vessels engineered to maintain beverage temperature through vacuum-sealed or foam-insulated barriers, typically constructed from 18/8 stainless steel with copper-coated inner walls achieving 6-12 hour thermal retention for commercial and consumer hydration applications. Stainless steel product types command the dominant margin pool due to durability premiums and recyclability credentials, while plastic variants face structural decline from BPA-phobia and regulatory pressure. The 20 oz and 30 oz capacity segments lead volume as commuter culture and fitness tracking normalize larger single-serve consumption formats.
The US FDA regulates food-contact surfaces under 21 CFR 175.300, compelling substrate and coating reformulations, while the EU REACH framework restricts certain nickel leaching thresholds in metallic vessels sold across European markets. California's Proposition 65 warning requirements shape labeling and material sourcing decisions for brands distributing through US retail. Stakeholders must monitor evolving state-level chemical disclosure mandates and circular economy packaging laws that will determine which manufacturing footprints and material specifications remain viable across priority markets.
Market Dynamics
Vacuum-insulated manufacturing is concentrating production in specialized stainless steel clusters where thermal engineering expertise and coating chemistry capabilities co-locate, locking in competitive advantages for integrated producers against fragmented assemblers.
Growth Catalysts
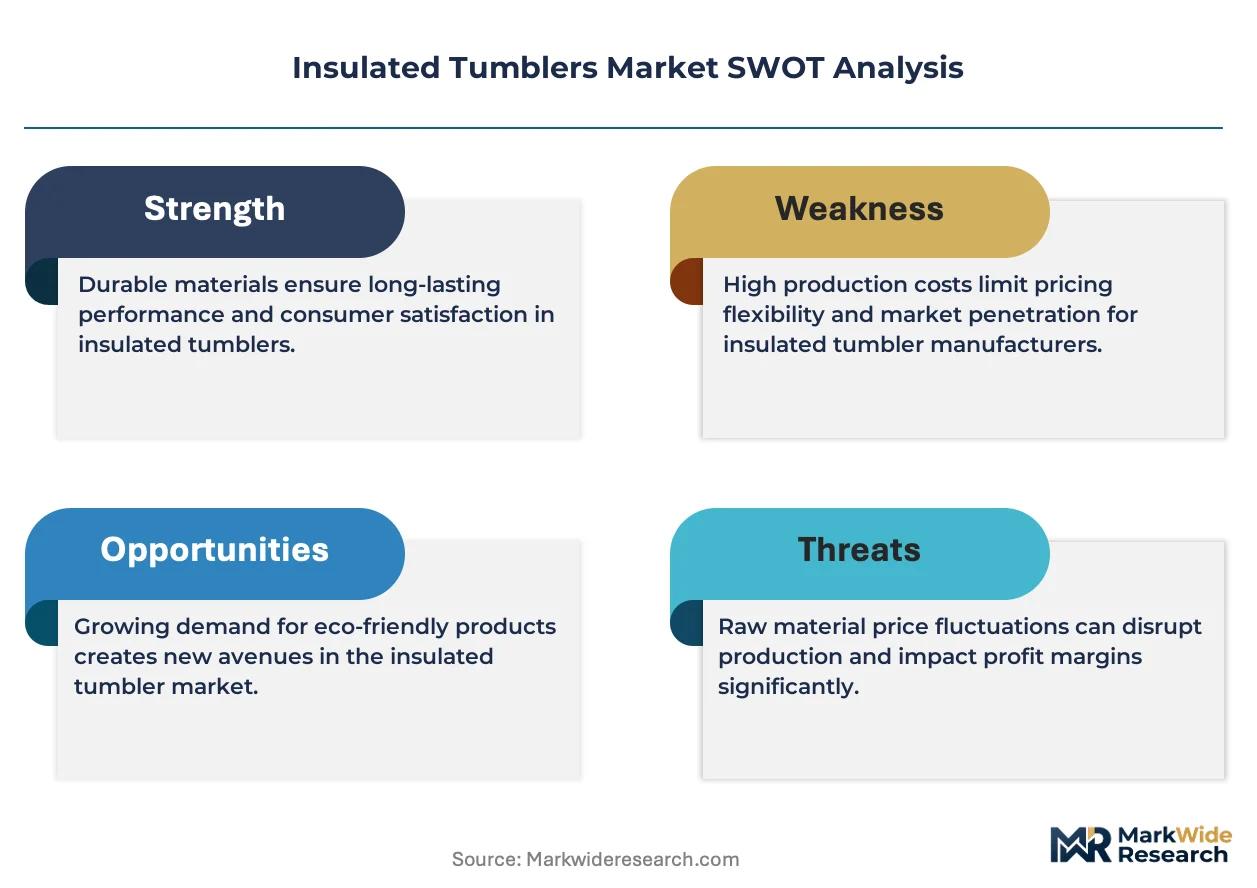
- 21 CFR 175.300 compliance:FDA food-contact material standards are forcing substrate reformulations toward safer powder coatings and electropolished interiors, creating premium upgrade cycles across replacement demand.
- Outdoor recreation participation:Trail running, overlanding, and vanlife subcultures are normalizing 30 oz+ capacity formats as standard hydration equipment, expanding addressable volume in specialty retail.
- Copper-coated inner walls:This thermal engineering technique is extending heat retention windows to 12+ hours, justifying durability premiums against single-use alternatives in commuter and fitness segments.
Market Restraints
- Nickel price volatility:18/8 stainless steel input costs fluctuate with Indonesian and Philippine ore export policies, compressing margin stability for non-integrated manufacturers.
- REACH nickel leaching thresholds:EU restrictions on metallic ion migration create formulation complexity for brands distributing across European markets, requiring dual-SKU strategies.
- Reusable bottle substitution:Narrow-mouth insulated bottles with integrated straws are capturing share in fitness and cycling applications where tumbler spill-risk limits adoption.
Strategic Opportunities
- India PLI scheme for specialty steel:Domestic production incentives are enabling localized manufacturing footprints for brands targeting South Asian outdoor and corporate gifting channels.
- Electropolishing automation:Convergence of robotic surface finishing and AI-driven quality inspection is collapsing unit economics for precision-sealed vessels in mid-tier price bands.
- Direct-to-worksite distribution:Bulk procurement platforms serving construction and logistics fleets are bypassing retail markup, capturing institutional hydration spend previously routed through big-box.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for BPA-free powder finishes that withstand dishwasher cycling remains concentrated among a handful of industrial coating houses, constraining new entrant quality parity.
- Prop 65 labeling timelines:California's chemical disclosure mandates require 6-12 month lead times for compliant packaging redesign, delaying product launches for brands without established West Coast regulatory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Tumblers Market |
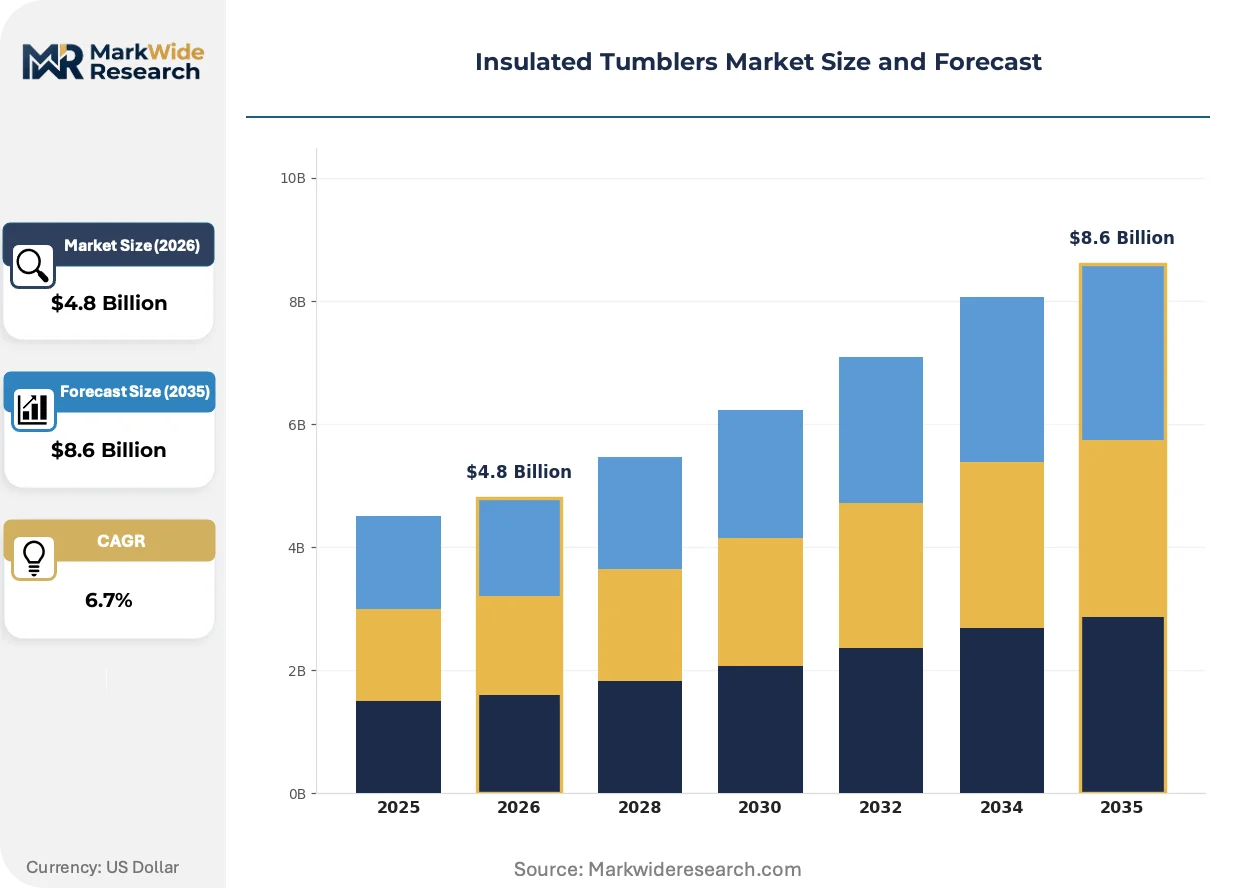
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Plastic, Glass, Ceramic End User: Retail Consumers, Outdoor Enthusiasts, Corporate Clients, Hospitality Sector Capacity: 12 oz, 16 oz, 20 oz, 30 oz Feature: Double-Wall Insulation, Leak-Proof, Customizable, Dishwasher Safe |
| Companies Covered | Contigo, Corkcicle, YETI Holdings, Stanley, S’well, Thermos, RTIC Outdoors, Zojirushi, Hydro Flask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Tumblers Market Shifts & Advancements
Active thermal engineering, regulatory chemistry reformulation, and procurement channel fragmentation are simultaneously reshaping how insulated drinkware gets designed, certified, and purchased across consumer and commercial segments.
Laser-welded vacuum chambers are collapsing the performance gap between automated production and hand-finished precision, enabling mid-tier manufacturers to achieve sub-0.001 atm pressure seals previously exclusive to premium tiers. Outdoor specialty retailers are accelerating adoption of these vessels as house-brand alternatives to licensed premium labels. The technology is collapsing traditional price-performance stratification across the 20-30 oz capacity range.
REACH candidate list expansions for endocrine-disrupting chemicals are compelling European distributors to demand full material disclosure down to sub-component suppliers. Stainless steel mills serving food-contact applications are investing in electropolishing line upgrades to preempt nickel migration testing failures. Brands with existing EU regulatory infrastructure are capturing shelf space from exporters facing compliance timeline compression.
Corporate procurement departments are consolidating hydration spend through centralized sustainability platforms that track carbon footprint per unit and circularity credentials. Facility managers in tech campuses and healthcare systems are displacing disposable cup programs with branded tumbler bulk orders tied to ESG reporting requirements. This pattern is most visible across Pacific Northwest and Northeast US metro corridors where municipal waste reduction mandates intersect with large employer sustainability commitments.
Insulated Tumblers Market Segmentation
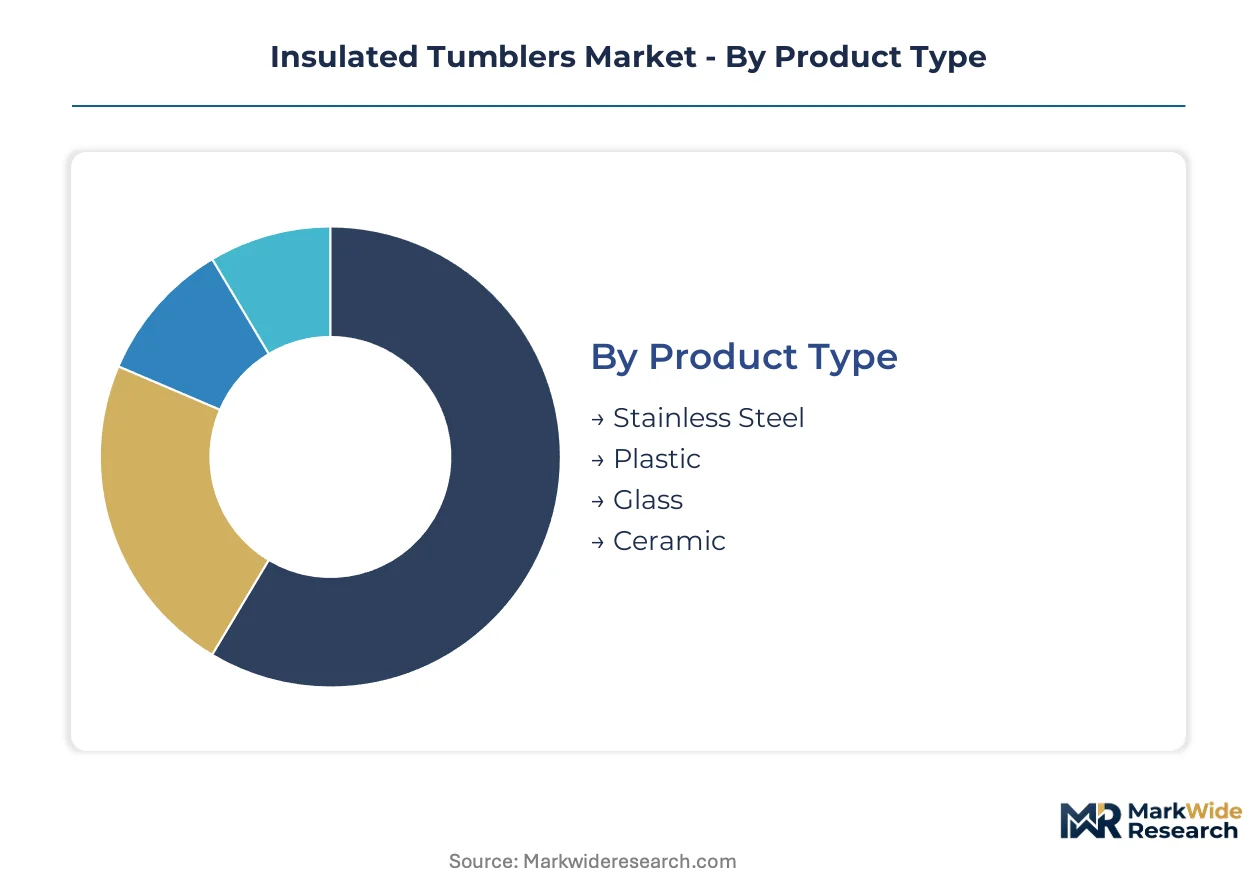
Segmentation in insulated tumblers reveals how thermal performance specifications, durability trade-offs, and use-case portability requirements fragment purchasing decisions across divergent price bands and replacement cycles.
Product Type:
Stainless steel variants command the longest replacement cycles due to corrosion resistance, while plastic and glass segments turn over faster as surface degradation and breakage accelerate refresh demand.
- Stainless Steel:Vacuum-sealed 18/8 construction with copper-coated inner walls delivers 6-12 hour thermal retention. Demand concentrates among Pacific Northwest outdoor enthusiasts and Sun Belt commuters where durability premiums justify higher price points against disposable alternatives.
- Plastic:Polypropylene and Tritan copolyester variants offer lighter weight at lower cost positions. BPA-phobia and FDA 21 CFR 175.300 compliance pressures are compressing addressable volume as retailers delist non-compliant substrates.
- Glass:Borosilicate double-wall construction provides taste neutrality for specialty coffee and tea consumption. Fragility limits adoption to stationary office and home environments with minimal transport stress.
- Ceramic:Glazed stoneware with silicone sleeves targets aesthetic-driven gifting and hospitality tableware. Thermal mass limits portability; demand clusters in boutique retail and restaurant service channels.
Stainless steel dominates installed base. Plastic is where expansion concentrates as price-sensitive volume shifts toward Tritan reformulations.
End User:
Corporate procurement operates on annual contract cycles with sustainability reporting requirements, while outdoor enthusiasts purchase on event-driven replacement schedules tied to gear upgrade patterns.
- Retail Consumers:Mass-market purchasers selecting on color, brand recognition, and price point through big-box and e-commerce channels. Commuter culture in US metro corridors normalizes 20-30 oz capacity as daily carry standard.
- Outdoor Enthusiasts:Trail runners, overlanders, and vanlife participants demand 30 oz+ formats with carabiner-compatible handles and powder-coated grip surfaces. Specialty retail in Colorado and Utah mountain towns anchors volume.
- Corporate Clients:Bulk procurement through sustainability platforms with ESG tracking requirements. Tech campuses and healthcare systems across Pacific Northwest and Northeast US displace disposable cup programs.
- Hospitality Sector:Hotels, resorts, and catering operations selecting for logo customization and stackability. Turnover accelerates with brand refresh cycles and seasonal promotional requirements.
Retail consumers represent the deepest installed base. Corporate clients are climbing the fastest as ESG mandates harden procurement criteria.
Capacity:
Larger formats amortize unit economics across extended use sessions, while 12 oz variants turn over fastest as single-serve coffee culture drives frequent replacement.
- 12 oz:Espresso and cortado formats for specialty coffee consumption. Urban café culture in Portland and Seattle sustains niche demand despite limited thermal mass.
- 16 oz:Standard coffee shop serving size with moderate portability. Commuter rail and bus systems in Chicago and Boston normalize this as minimum viable capacity.
- 20 oz:Fitness tracking and hydration app integration favor this midpoint. Gym chains and corporate wellness programs standardize on this format for branded distribution.
- 30 oz:All-day hydration for construction crews and outdoor workers. Direct-to-worksite distribution platforms capture this volume bypassing retail markup.
20 oz dominates installed base. 30 oz is gaining share fastest as fitness tracking and worksite hydration requirements expand.
Feature:
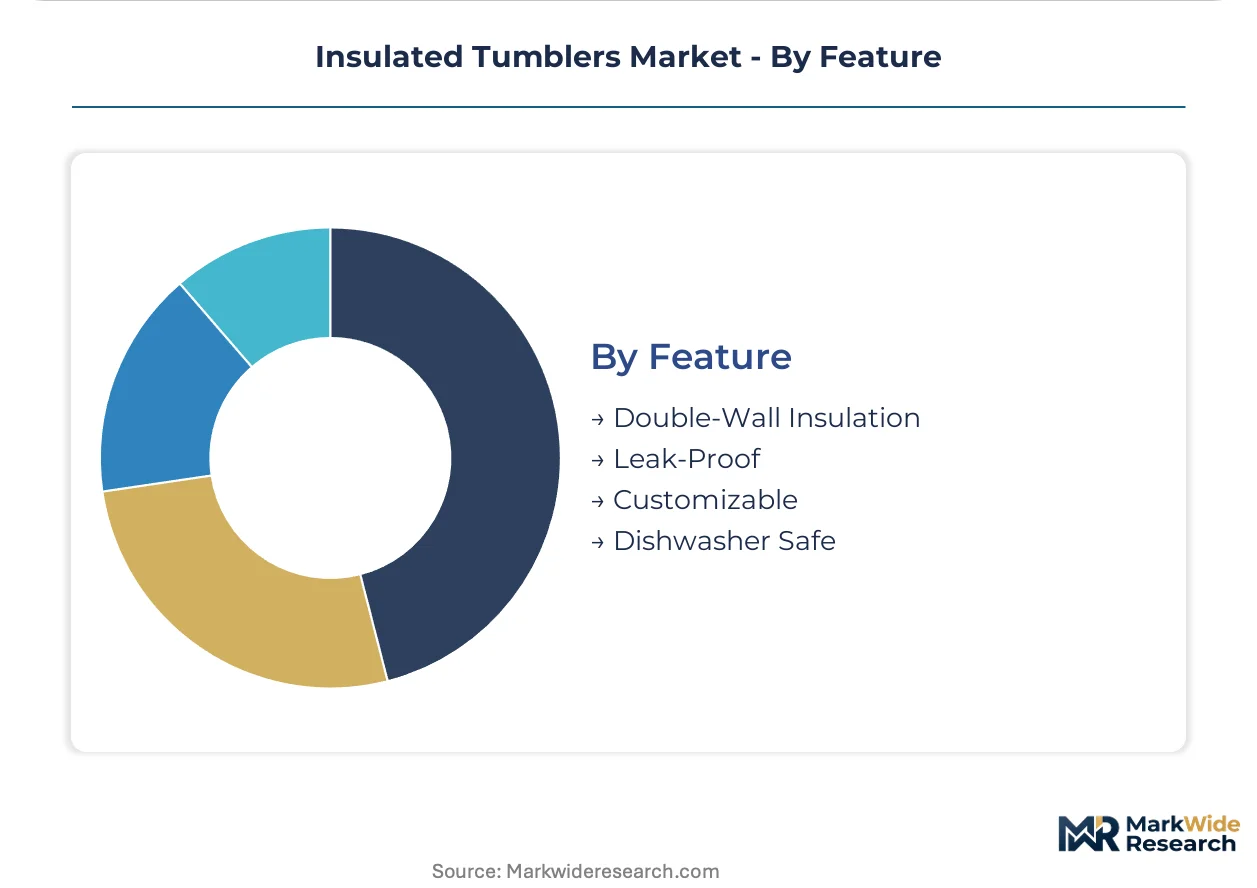
Dishwasher-safe certifications extend replacement intervals by reducing coating degradation, while leak-proof engineering commands premium positioning in mobile use cases.
- Double-Wall Insulation:Vacuum-sealed or foam-filled barriers creating thermal barriers. Laser-welded chamber production is collapsing price-performance gaps across mid-tier manufacturers.
- Leak-Proof:Precision-engineered gaskets and threaded sealing mechanisms. Cycling and running applications in Denver and Austin metro areas demand this as table stakes.
- Customizable:Laser engraving and pad-printing compatibility for corporate gifting and event merchandise. Hospitality procurement in Las Vegas and Orlando drives seasonal volume spikes.
- Dishwasher Safe:Powder coating and electropolished finishes surviving automated cleaning cycles. REACH nickel leaching thresholds and Prop 65 labeling requirements favor electropolished stainless variants.
Double-wall insulation dominates installed base. Leak-proof engineering is expanding most quickly as active mobility use cases multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese stainless steel fabricators supply vacuum-insulated components to North American and European brands, creating a trade corridor where thermal engineering expertise concentrates in Zhejiang and Guangdong provinces while consumption clusters in US Sun Belt metros and German industrial cities.
United States
Sun Belt commuters and Pacific Northwest outdoor enthusiasts drive 30 oz format adoption through fitness tracking and worksite hydration norms. FDA 21 CFR 175.300 compliance pressures force substrate reformulations toward electropolished interiors and BPA-free powder coatings. Seattle and Denver anchor specialty retail distribution for premium outdoor brands.
Germany
REACH nickel leaching thresholds and circular economy packaging laws shape procurement criteria for corporate hospitality and industrial canteen programs. ECHA regulatory expansions on endocrine-disrupting chemicals demand full material disclosure down to sub-component suppliers. Bavarian precision engineering clusters around Nuremberg supply sealing mechanism components to EU-facing brands.
China
Domestic consumption rises through urban commuter culture and corporate gifting programs in Shanghai and Shenzhen manufacturing zones. GB standards for food-contact materials align with export-market compliance requirements for US and EU-bound production. Zhejiang province hosts concentrated vacuum chamber welding and electropolishing capacity serving global OEM contracts.
Japan
Precision-engineered sealing mechanisms and electropolished stainless steel interiors anchor premium positioning in Tokyo and Osaka metro corridors. METI industrial standards for food-contact applications exceed baseline international requirements, creating export quality premiums. Nagoya-area metalworking clusters supply thermal retention componentry to domestic and Asian regional brands.
India
PLI scheme incentives for specialty steel production enable localized manufacturing footprints targeting South Asian outdoor and corporate gifting channels. FSSAI food-contact regulations accelerate substrate reformulations among domestic fabricators. Maharashtra and Gujarat industrial corridors concentrate powder coating and surface finishing capabilities for mid-tier price bands.
Insulated Tumblers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where premium positioning requires in-house thermal engineering and coating chemistry capabilities. The vendor base stratifies between integrated manufacturers with captive stainless steel supply and fragmented assemblers dependent on third-party component sourcing. Two archetypes dominate: vertically integrated premium brands with controlled distribution, and mid-tier specialists leveraging laser-welding automation to collapse price-performance gaps. Competitive moves concentrate on geographic expansion through direct-to-worksite procurement platforms and portfolio diversification into adjacent hydration formats.
Among US-based premium specialists, YETI Holdings and Hydro Flask occupy positions where controlled distribution and sustainability messaging respectively anchor differentiation. Zojirushi represents the precision-engineering archetype from Japanese metalworking traditions. These three exemplify how thermal retention performance, regulatory compliance infrastructure, and channel strategy separate viable competitors from price-commoditized assemblers in a market where coating chemist scarcity and Prop 65 labeling timelines create defensive moats.
| Leading Market Players |
|---|
| Contigo |
| Corkcicle |
| YETI Holdings |
| Stanley |
| S'well |
| Thermos |
| RTIC Outdoors |
| Zojirushi |
| Hydro Flask |
| Others |
Supply & Pricing Matrix
Overcapacity in Zhejiang province vacuum-chamber welding facilities is compressing contract manufacturer margins while enabling aggressive pricing postures among mid-tier brands sourcing from these clusters. Utilization rates below 70 percent at specialized electropolishing lines are forcing suppliers to absorb coating chemistry cost escalations rather than pass through to OEM customers, reshaping negotiation leverage across the stainless steel tumbler supply base.
Pricing Analysis
Laser-welded vacuum chamber technology is collapsing the prior-generation hand-finished premium against automated mid-tier production, compressing the technology-generation pricing gap to under 15 percent at equivalent thermal retention specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating durability certification and dishwasher-cycle warranty length. Pricing pressure stems from Indonesian nickel ore export policy volatility feeding 18/8 stainless steel input cost instability. Corporate procurement platforms exhibit lowest price sensitivity due to ESG reporting requirements, while mass-market retail consumers demonstrate highest elasticity to promotional discounting.
Supply Chain Analysis
Contract manufacturing concentration rests with Zhejiang and Guangdong province fabricators holding 60-plus percent of global vacuum-insulated vessel capacity. Raw material dependencies center on Indonesian and Philippine nickel ore, Chinese 18/8 stainless steel mill output, and German-imported powder coating chemistries. Single-source vulnerability concentrates at electropolishing line operators certified to FDA 21 CFR 175.300 and EU REACH nickel leaching thresholds. Distribution runs through outdoor specialty retail in Denver and Seattle, direct-to-worksite procurement platforms for construction and logistics fleets, and corporate sustainability program administrators at tech campuses and healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated tumblers market is cycling through a replacement-driven recovery as post-pandemic outdoor recreation participation and commuter culture normalization restock worn vessel inventories. Equipment upgrade cycles among trail runners and vanlife participants provide the cyclical impetus sustaining volume momentum.
For Market Incumbents: Harden coating chemistry supply security through captive relationships with industrial powder coating houses certified to FDA and REACH standards, as formulation expertise scarcity constrains new entrant quality parity. Defend shelf space at REI and specialty outdoor retailers by accelerating laser-welded vacuum chamber adoption to collapse mid-tier price competition. Channel control through exclusive distribution agreements remains the critical lever against private-label house brands.
For New Entrants and Emerging Players: South Asian corporate gifting channels present the most penetrable white-space opportunity, where India PLI scheme incentives enable localized manufacturing footprints without competing against established US and Japanese premium positioning. Target direct-to-worksite distribution platforms serving Maharashtra and Gujarat construction corridors with 30 oz capacity formats customized for all-day hydration requirements. Lead with electropolished stainless steel interiors exceeding FSSAI baseline requirements to signal export-grade quality credibility.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brands with established corporate procurement platform relationships and ESG tracking infrastructure embedded in customer contracts. Long-term viability favors acquisition targets possessing in-house thermal engineering capabilities and West Coast regulatory compliance infrastructure for Prop 65 labeling timelines. Monitor nickel price volatility indices and Indonesian export policy announcements as early inflection signals for margin compression or expansion across the stainless steel supply base.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Coating | Captive supply of FDA 21 CFR 175.300 certified finishes insulates against chemist scarcity constraints. |
| Direct-to-Worksite Distribution Launch | Bypasses REI and big-box retail markup to capture institutional hydration spend from construction fleets. |
| Electropolishing Automation Investment | Robotic surface finishing collapses unit economics for precision-sealed vessels in mid-tier price bands. |
| Corporate Sustainability Platform Integration | ESG tracking requirements at Pacific Northwest tech campuses lock in annual contract renewal cycles. |
| India PLI-Enabled Manufacturing Footprint | Domestic production incentives localize supply for South Asian outdoor and corporate gifting channels. |
Research Methodology
A standing panel of thermal engineering directors at vacuum-insulated vessel manufacturers, powder coating chemistry formulators, outdoor specialty retail category managers, and corporate sustainability procurement leads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from FDA 21 CFR 175.300 regulatory filings, ECHA REACH candidate list updates, US customs import records for stainless steel food-contact articles, and SEC 10-K disclosures from publicly traded drinkware brands. Bottom-up volume modeling across capacity segments triangulated against top-down category spend estimates from retail audit databases.
Scenario-bracketing framed the analytical approach, with base, upside, and downside cases reflecting divergent assumptions for nickel price trajectories, outdoor recreation participation rates, and regulatory timeline acceleration for state-level chemical disclosure mandates. Segmentation dimensions modeled include product type, end user archetype, capacity format, thermal engineering feature set, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical replacement cycle data and forward-looking procurement platform adoption rates. Forecast inputs incorporated stainless steel mill capacity utilization signals and specialty retail inventory-to-sales ratios.
Practitioners should monitor Indonesian nickel ore export policy shifts, ECHA endocrine-disrupting chemical list expansions, and corporate ESG reporting mandate adoption curves for early signals of forecast revision. Quarterly review of specialty retail sell-through data and contract manufacturing capacity utilization reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Water Purifier Bottle Market
Household Items
US Air Fresheners Market
Household Items
Global Electric Scissors Market
Household Items
Can Opener Market
Household Items
Hydralight Lanterns Market
Household Items
Global Humidifier Market
Household Items
Drinkware Accessories Market
Household Items
Infuser Water Bottles Market
Household Items
Sleeping Pillow Market
Household Items
Latex Mattress Market
Household Items
Folded Tissues Market
Household Items
Hand Wash Station Market
Household Items
South Africa Cookware Market
Household Items
Innerspring Mattresses Market
Household Items
Air Care Market
Household Items
Europe Handheld Fans Market