
 Germany Kitchen Appliances Market | 2026-2036
Germany Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Kitchen Appliances Market Foresight
Premium energy-efficient specification tiers is rotating demand toward connected, low-consumption product lines across German households. BSH Hausgeräte GmbH leverages its integrated manufacturing footprint in Baden-Württemberg to control distribution costs. Miele & Cie. KG differentiates through engineering-intensive domestic appliances with extended service lifecycles. Robert Bosch GmbH anchors the mid-premium segment with broad channel coverage through specialist retailers and direct digital platforms.
Germany kitchen appliances encompass electrically powered equipment designed for food storage, preparation, cooking, and cleaning, typically operating at 230V/50Hz with energy efficiency classifications from A to G under EU labeling frameworks. Their primary purpose spans residential convenience, commercial food service productivity, and institutional catering compliance. Refrigerators and dishwashers occupy mature volume positions where replacement cycles drive steady turnover, while smart connectivity and induction technologies capture expanding margin pools as homeowners prioritize interface integration and precision cooking control. Residential kitchens dominate absolute demand, though hospitality establishments and food service providers generate disproportionate premium uptake through durability specifications and warranty terms.
Germany's Federal Ministry for Economic Affairs and Climate Action enforces Ecodesign and energy labeling regulations that mandate minimum efficiency thresholds for ovens, refrigerators, and dishwashers sold domestically. The KBA does not regulate this sector, but the EU F-Gas Regulation governs refrigerant types in cooling appliances, constraining manufacturer choices and retrofit pathways. CE marking under the EU's Low Voltage Directive and EMC Directive governs electrical safety and electromagnetic compatibility for all products placed on the German market. Stakeholders must monitor pending EU Right to Repair legislation and Germany's national circular economy implementation, which will reshape spare parts availability obligations and design-for-disassembly requirements.
Market Dynamics
Induction technology adoption is compressing replacement cycles across German kitchens while the EU Ecodesign Directive tightens minimum efficiency thresholds for ovens and refrigerators, forcing manufacturers to redesign core heating and cooling systems.
Growth Catalysts
- Bavaria Renovation Activity:Elevated residential refurbishment rates in Munich and surrounding districts are accelerating dishwasher and built-in oven replacements as homeowners modernize aging kitchen infrastructure.
- F-Gas Regulation Phase-Down:The EU F-Gas Regulation's refrigerant constraints are pushing manufacturers toward alternative cooling technologies that reduce environmental impact while maintaining performance benchmarks.
- Smart Home Integration:Connected appliance ecosystems are gaining traction among urban households seeking centralized control over energy consumption and cooking workflows through unified platforms.
Market Restraints
- Copper and Steel Volatility:Input cost fluctuations for sheet metal and wiring components are compressing margins on mid-range refrigerator and dishwasher production lines.
- Baden-Württemberg Manufacturing Concentration:Heavy reliance on a single southwestern industrial cluster creates vulnerability to localized logistics disruptions and labor market tightness.
- Heat Pump Compatibility:Technical limitations in integrating high-wattage cooking appliances with residential heat pump systems constrain electrification pathways in retrofitted buildings.
Strategic Opportunities
- North Rhine-Westphalia New Construction:Sustained housing development in Cologne and Düsseldorf corridors offers volume expansion for integrated kitchen appliance packages specified by developers.
- Right to Repair Mandate:Pending EU legislation on spare parts availability and design-for-disassembly creates first-mover advantages for manufacturers restructuring service networks.
- Induction-Smart Convergence:The intersection of precision heating technology with AI-driven recipe guidance opens premium positioning for cooking appliances in affluent urban districts.
Industry Challenges
- Embedded Systems Engineering Talent:Scarce availability of firmware developers specializing in appliance connectivity stacks delays smart feature rollouts across product lines.
- CE Marking Timeline Compression:Accelerated compliance verification cycles for electromagnetic compatibility under the EU's Low Voltage Directive strain certification resources.
- Legacy Control Interface Integration:Retrofitting connected modules into existing mechanical appliance architectures without full platform redesigns creates reliability risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Kitchen Appliances Market |
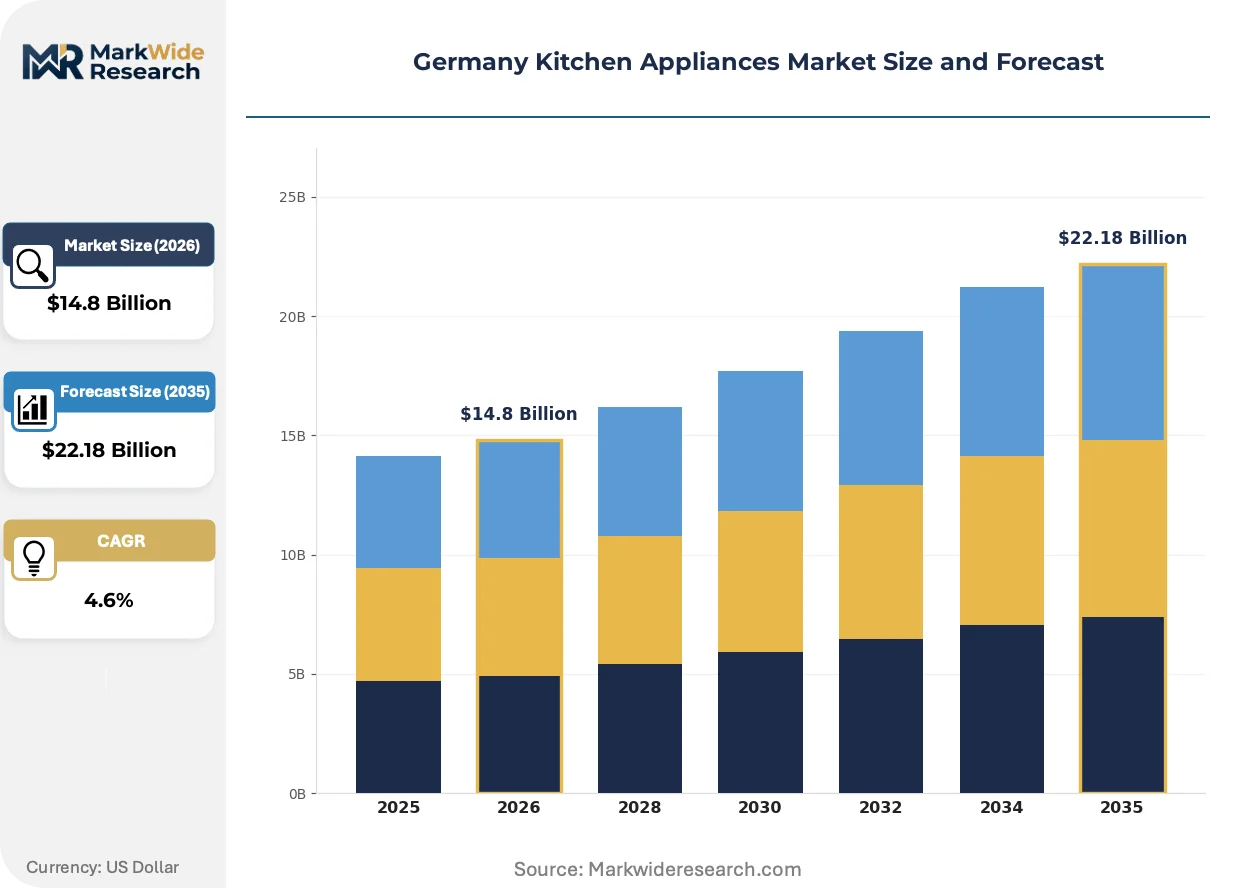
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Microwaves, Dishwashers, Ovens, Coffee Makers, Food Processors Technology: Smart Connectivity, Energy Efficient, Touch Control, Voice Activated, Infrared Heating, Induction Application: Residential Kitchens, Commercial Kitchens, Institutional Catering, Outdoor Cooking, Mobile Kitchens, Catering Events End User: Homeowners, Hospitality Establishments, Food Service Providers, Catering Companies, Property Developers, Renovators |
| Companies Covered | Electrolux AB, Samsung Electronics, BSH Hausgeräte GmbH, Liebherr Appliances, LG Electronics, Miele & Cie. KG, Robert Bosch GmbH, Gaggenau, Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Kitchen Appliances Market Shifts & Advancements
Connected cooking ecosystems and precision temperature management are redefining user expectations, while regulatory pressure on refrigerants and energy consumption forces hardware redesigns across refrigeration and cooking categories.
Induction coil technology is miniaturizing. Compact multi-zone heating elements now enable flexible cooktop configurations that adapt to vessel size and position. Premium kitchen renovators in Hamburg and Stuttgart are specifying these systems at accelerating rates. This compression of heating hardware footprint is enabling seamless integration with countertop surfaces and kitchen islands previously unsuitable for traditional cooktops.
The EU F-Gas Regulation's phasedown schedule is tightening refrigerant options for domestic cooling appliances. Manufacturers face forced migration toward hydrocarbon and CO2-based systems with lower global warming potential. This transition imposes redesign costs heaviest on mid-volume refrigerator producers serving the standard residential segment, who must retool assembly lines while maintaining price accessibility.
Direct-to-consumer digital channels are displacing traditional specialist retailer relationships for replacement purchases. Urban millennials in Berlin and Munich increasingly research and order dishwashers and compact appliances through manufacturer-owned platforms, bypassing brick-and-mortar showrooms. This channel shift concentrates margin capture with brands possessing robust logistics infrastructure and digital customer service capabilities.
Germany Kitchen Appliances Market Segmentation
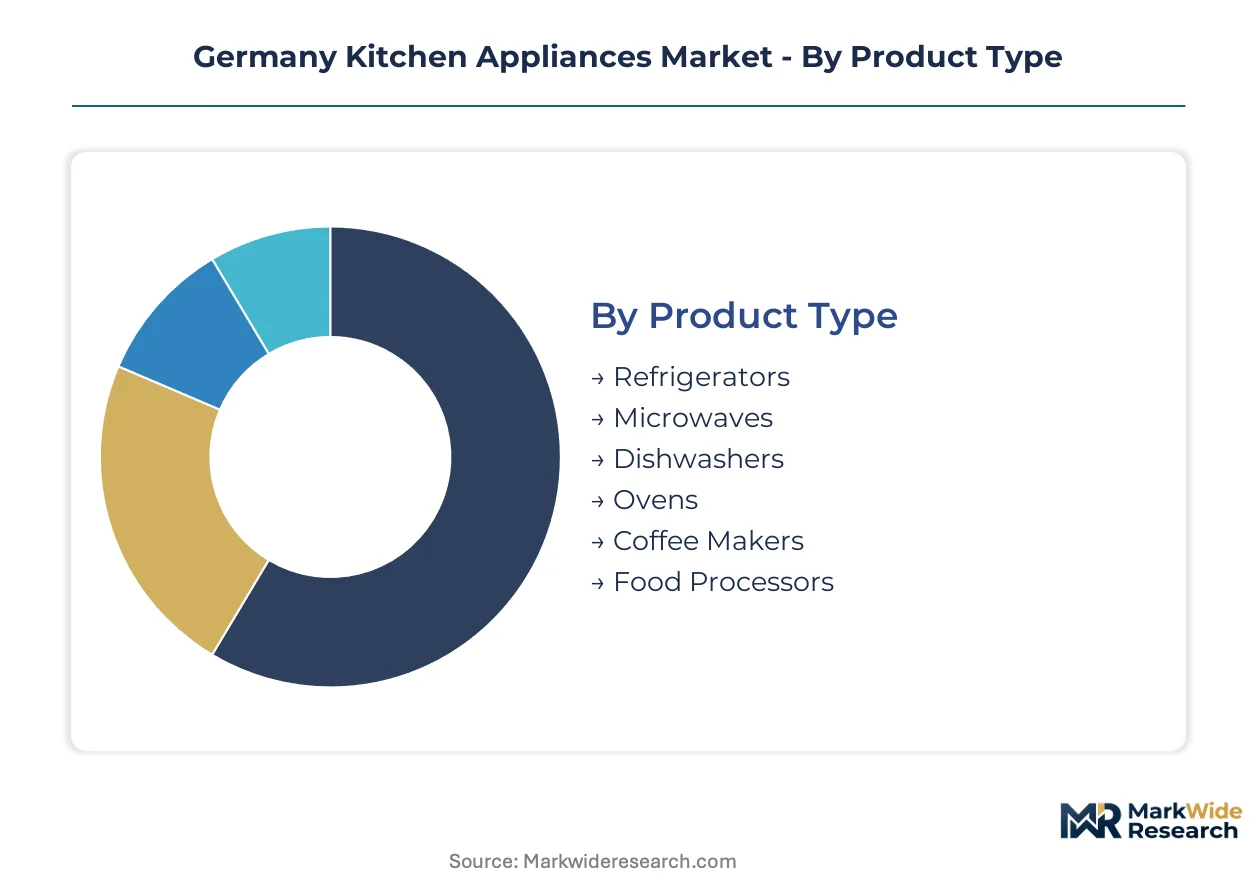
Germany's kitchen appliances market fragments across four critical dimensions that determine regulatory exposure, margin capture, and channel strategy. Product type and technology classifications dictate CE marking obligations under the EU's Low Voltage Directive, while application and end-user segments shape warranty terms and service network requirements.
Product Type:
CE marking timelines and energy labeling stringency vary sharply across appliance categories, with cooling and cooking equipment facing the most compressed compliance cycles.
- Refrigerators:Compression-based cooling systems operating on hydrocarbon or CO2 refrigerants under F-Gas Regulation constraints. Bavarian homeowners replacing aging units in Munich renovation corridors drive steady replacement demand amid efficiency mandate tightening.
- Ovens:Enclosed heating chambers with convection, steam, or pyrolytic cleaning configurations. North Rhine-Westphalia property developers specify built-in models for new construction in Cologne and Düsseldorf corridors.
- Dishwashers:Water-recirculating cleaning systems with EU Ecodesign Directive water consumption caps.
- Microwaves:Magnetron or inverter-based rapid heating appliances with electromagnetic compatibility verification requirements.
- Coffee Makers:Pressure-extraction or drip-brewing systems with standalone countertop positioning.
- Food Processors:Multi-function preparation equipment with blade safety interlocks under machinery directive scope.
Established volume favors refrigerators; emerging adoption favors ovens with induction-smart convergence.
Technology:
Margin structures diverge most dramatically across technology tiers, with connectivity stacks commanding premium positioning while basic efficiency compliance becomes table stakes.
- Smart Connectivity:Wi-Fi and Bluetooth-enabled appliances integrating with centralized home automation platforms. Berlin and Hamburg urban households seek unified energy monitoring and remote preheating control.
- Induction:Electromagnetic coil heating with precision temperature response and surface safety cooling. Stuttgart kitchen renovators specify flexible multi-zone configurations for island integration.
- Energy Efficient:A-rated or higher performance under EU labeling frameworks with reduced standby consumption.
- Touch Control:Capacitive interface panels replacing mechanical dials with programmable preset storage.
- Voice Activated:Natural language command processing through third-party assistant integration.
- Infrared Heating:Quartz or halogen element rapid response cooking with open-flame simulation.
Smart connectivity captures the steepest expansion trajectory; energy efficiency represents mandatory baseline specification.
Application:
Installation requirements and durability specifications scale sharply from residential convenience to commercial throughput demands.
- Residential Kitchens:Single-family and multi-unit dwelling installations with 230V/50Hz standard connection. Bavaria and North Rhine-Westphalia concentrate replacement and new construction demand.
- Commercial Kitchens:High-cycle hospitality and food service operations with stainless steel construction and extended warranty terms.
- Institutional Catering:School, hospital, and corporate cafeteria compliance with hygiene certification and volume throughput specifications.
- Outdoor Cooking:Weather-resistant portable or built-in installations for terrace and garden environments.
- Mobile Kitchens:Food truck and temporary event configurations with LP gas or generator power compatibility.
- Catering Events:Rental and lease-based temporary equipment deployment for wedding and conference service.
Residential kitchens anchor absolute volume; commercial kitchens generate disproportionate premium uptake.
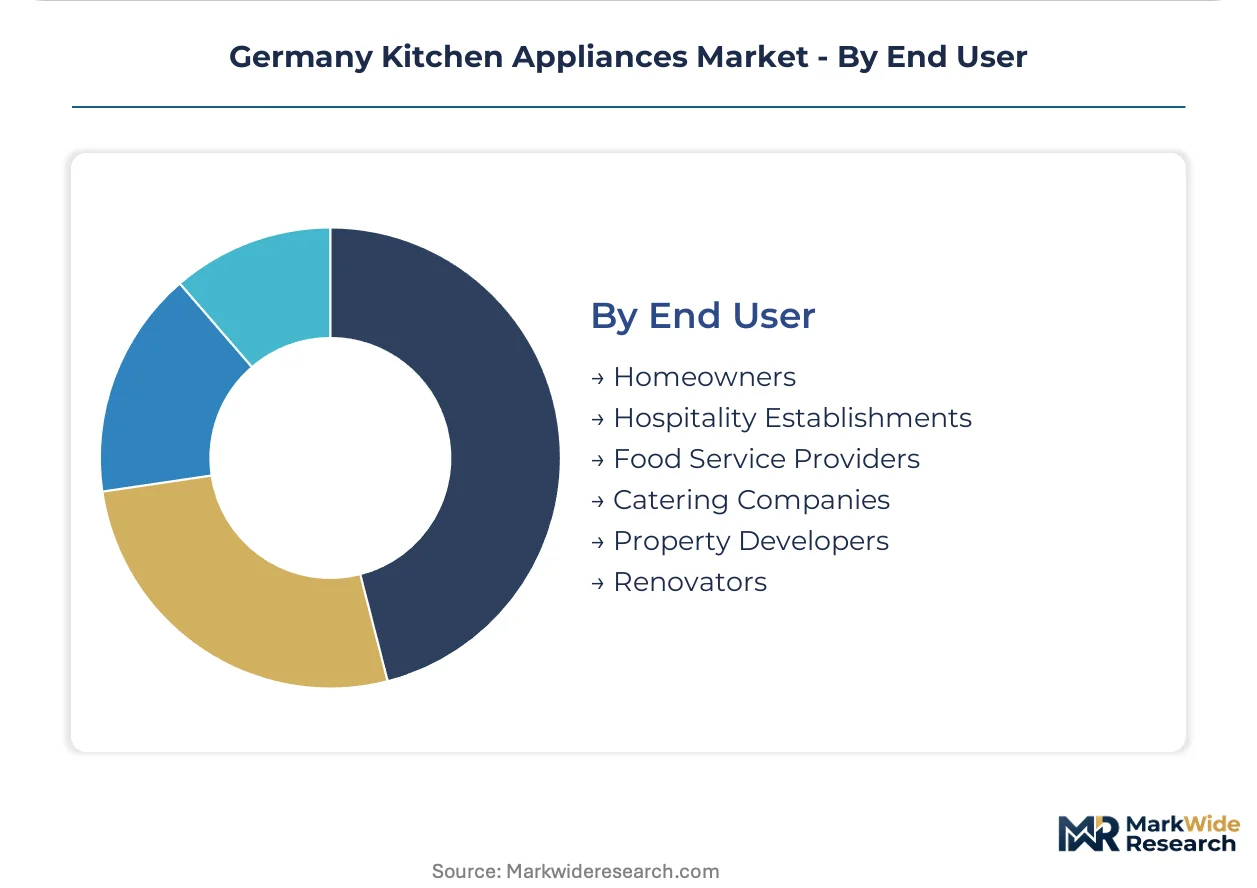
End User:
Procurement authority and decision criteria vary fundamentally between individual consumers and institutional specifiers.
- Homeowners:Individual purchasers prioritizing design integration, energy cost reduction, and smart feature accessibility. Urban millennials in Berlin and Munich increasingly favor direct-to-manufacturer digital channels.
- Property Developers:Volume purchasers specifying integrated kitchen packages for multi-unit residential projects in North Rhine-Westphalia construction corridors.
- Hospitality Establishments:Hotels and restaurants requiring durability certification, rapid service response, and brand consistency across properties.
- Food Service Providers:Contract catering and restaurant chain operators with standardized equipment specifications and national service network requirements.
- Catering Companies:Event-focused operators with rental flexibility needs and rapid deployment logistics.
- Renovators:Residential refurbishment contractors coordinating appliance replacement with kitchen infrastructure modernization in Bavaria's aging housing stock.
Homeowners dominate transaction volume; property developers concentrate margin through package specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's kitchen appliances sector maintains a modest export surplus in premium built-in equipment, though component sourcing from Eastern European suppliers and Asian electronics manufacturers creates persistent trade interdependence. Domestic production clusters in the southwest supply adjacent EU markets while import penetration concentrates in entry-level segments.
Bavaria
Munich's renovation corridors drive replacement demand for dishwashers and built-in ovens as homeowners modernize aging kitchen infrastructure. The Federal Ministry for Economic Affairs and Climate Action enforces Ecodesign regulations that mandate minimum efficiency thresholds for appliances sold statewide. Manufacturing activity concentrates in metropolitan Munich and Nuremberg, where specialist retailers coordinate installation services for premium specification tiers.
North Rhine-Westphalia
Sustained housing development in Cologne and Düsseldorf corridors generates volume demand for integrated kitchen appliance packages specified by property developers. CE marking under the EU's Low Voltage Directive governs electrical safety for all products placed on the market in this industrial heartland. The Rhine-Ruhr metropolitan region anchors distribution logistics, with warehousing clusters serving both domestic retail networks and cross-border EU shipments.
Baden-Württemberg
Integrated manufacturing footprints in this southwestern cluster control distribution costs through proximity to engineering-intensive production facilities. Germany's national circular economy implementation shapes spare parts availability obligations for appliances assembled in Stuttgart and surrounding districts. The region's precision engineering heritage supports advanced induction coil and smart connectivity module fabrication.
Lower Saxony
Hanover and Brunswick serve as logistics hubs connecting northern German retail networks to North Sea port facilities for component importation. The EU F-Gas Regulation governs refrigerant types in cooling appliances distributed through this corridor, constraining manufacturer choices for refrigerator lines. Warehouse automation investments in Wolfsburg-area distribution centers accelerate fulfillment velocity for direct-to-consumer digital channels.
Hesse
Frankfurt's financial services sector generates demand for premium kitchen specifications in high-end residential developments and corporate housing. The EU's pending Right to Repair legislation will reshape warranty service networks headquartered in this central German state. Rhein-Main logistics infrastructure supports just-in-time component delivery to assembly plants across southern Germany.
Germany Kitchen Appliances Market Competitive Landscape
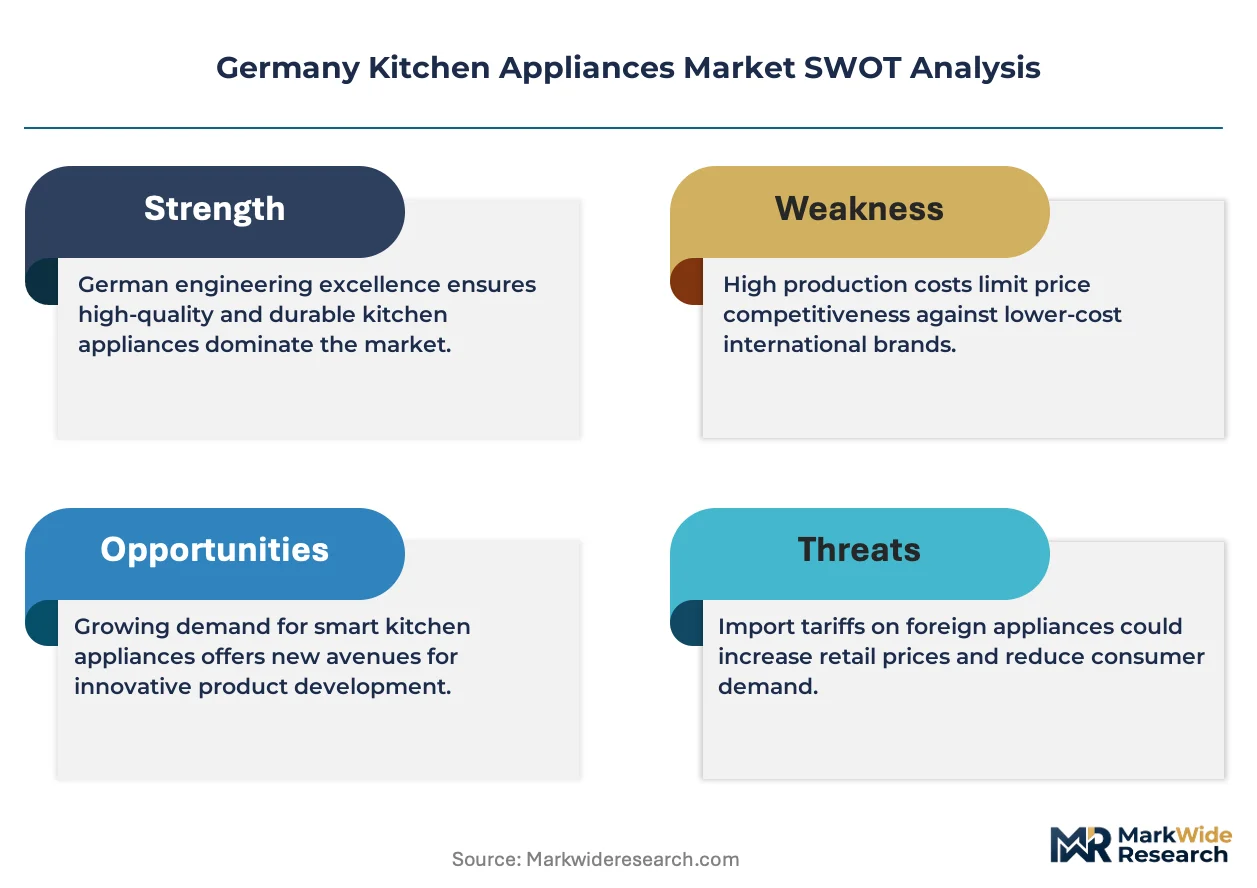
Listed leaders compete with private specialists across capital structure and strategic time horizons, creating a tiered competitive environment where publicly traded electronics conglomerates face off against family-owned engineering houses. The vendor base fragments across three strategic archetypes: diversified technology conglomerates with appliance divisions, dedicated domestic appliance specialists with integrated manufacturing, and luxury-positioned craftsmanship brands. Capacity expansion and portfolio diversification represent the dominant competitive moves, with players restructuring assembly footprints and adding connected product lines.
Within the private specialist tier, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify engineering-intensive domestic appliance production with extended service lifecycle positioning. Robert Bosch GmbH occupies a position bridging the mid-premium segment through broad channel coverage. These German-originated entities represent contrasting approaches to manufacturing integration and distribution control, with each anchoring distinct competitive positions within the southwestern industrial cluster.
| Leading Market Players |
|---|
| Electrolux AB |
| Samsung Electronics |
| BSH Hausgeräte GmbH |
| Liebherr Appliances |
| LG Electronics |
| Miele & Cie. KG |
| Robert Bosch GmbH |
| Gaggenau |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
Hydrocarbon refrigerant substitution for synthetic F-gases is redrawing procurement geography toward Eastern European component suppliers while compressing margin structures for mid-volume refrigerator producers unable to pass retooling costs downstream.
Pricing Analysis
Property developers anchor volume pricing through integrated kitchen package specifications for North Rhine-Westphalia new construction. Three-tier pricing structure across premium, standard, and economy levels separates Miele-grade engineering from BSH mid-premium positioning and entry-level Asian imports. Cost compression in standard-tier refrigeration intensifies because F-Gas Regulation compliance mandates hydrocarbon cooling system redesigns. Renovators in Bavaria exhibit highest price sensitivity, while Frankfurt corporate housing specifiers absorb premium positioning with minimal negotiation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for control modules and induction electronics sourced from South Korean and Chinese suppliers. Assembly draws from Baden-Württemberg manufacturing clusters, Polish metal stamping operations, and Czech Republic wiring harness facilities. Single-source vulnerability concentrates in semiconductor components for smart connectivity stacks. Distribution runs through Rhine-Ruhr warehousing hubs serving specialist retailer networks and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU Right to Repair legislation fragments service network economics, creating specialist niches for independent spare parts distributors and regional refurbishment operators.
For Market Incumbents: Shield installed base relationships by restructuring service networks ahead of Right to Repair spare parts availability mandates. Deepen backward integration into induction coil fabrication to defend margin position against copper volatility. Secure certification pre-approval for hydrocarbon refrigerant handling protocols before competitor compliance gaps emerge.
For New Entrants and Emerging Players: Lead with direct-to-consumer digital channels targeting Berlin and Munich urban millennials for compact appliance replacement cycles. White-space concentrates in smart connectivity retrofit modules for legacy mechanical architectures. Penetrate through subscription-based maintenance bundling that incumbent service networks cannot match.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive induction technology and established CE marking pathways. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch for inflection when EU Ecodesign Directive enforcement accelerates manufacturer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Connectivity Module Development | Wi-Fi stack integration enables remote diagnostics and energy monitoring for Berlin urban households. |
| Hydrocarbon Refrigerant Transition | CO2 cooling system retooling secures F-Gas Regulation compliance before 2025 phase-down deadlines. |
| Direct-to-Consumer Platform Launch | Manufacturer-owned digital channels capture margin displacement from specialist retailer relationships. |
| Right to Repair Service Network Expansion | Spare parts availability infrastructure creates first-mover positioning under pending EU legislation. |
| Induction-Smart Convergence R&D | AI-driven recipe guidance integration opens premium positioning in Stuttgart renovation corridors. |
Research Methodology
Initial hypotheses were tested against primary input from appliance manufacturing executives, specialist retailer category managers, property development procurement leads, and Federal Ministry regulatory affairs officers and refined through secondary validation against EU Ecodesign Directive filings, CE marking databases, German customs trade records, and F-Gas Regulation implementation guidance. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring.
Variance decomposition across product type, technology tier, application, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle modeling, new construction permitting data, and efficiency mandate compliance timelines. Smart connectivity adoption curves and induction technology penetration rates served as category-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained housing development in North Rhine-Westphalia and Bavaria renovation activity would require recalibration. Forecasts reflect assumptions on regulatory enforcement intensity and raw material cost stabilization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Commercial Induction Cooktops Market