
 France Cookware Market | 2026-2036
France Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
France Cookware Market Foresight
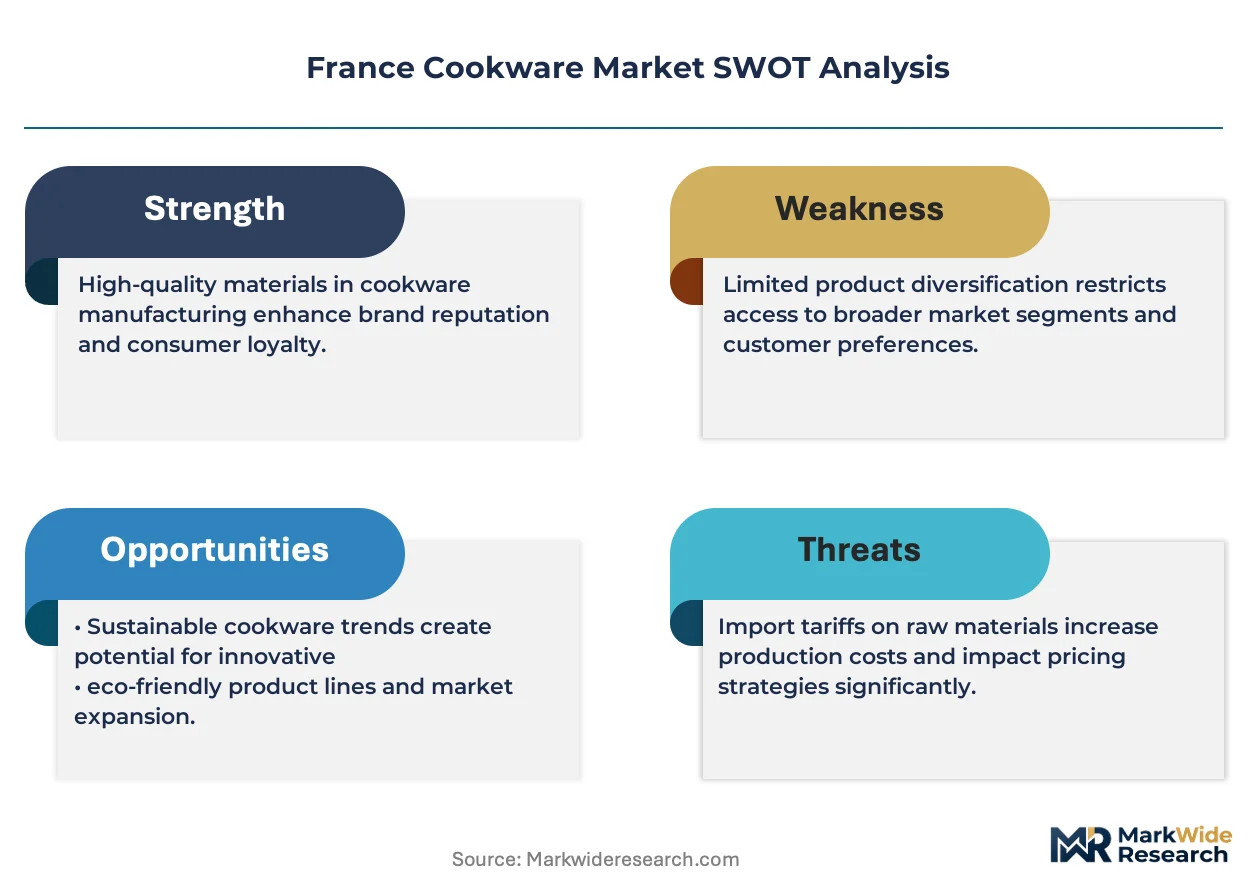
Ceramic-based coatings are repositioning product economics across the France cookware sector by displacing legacy polytetrafluoroethylene linings under tightening chemical restrictions. Mauviel leverages its Normandy manufacturing heritage to sustain artisan positioning in copper and stainless steel segments. Groupe SEB S.A. dominates mass-market distribution through multi-brand retail penetration and in-house production of aluminum and cast iron lines.
France cookware encompasses vessels and utensils engineered from aluminum, cast iron, stainless steel, copper, ceramic, or titanium, designed to withstand thermal cycling from 150°C to 300°C while meeting food-contact migration limits set by EFSA and EU framework regulation 1935/2004. Stainless steel pots and cast iron skillets anchor the premium tier, where margin pools concentrate around heritage brands and lifetime warranty positioning. Ceramic cookware represents the fastest-growing material segment as residential cooking buyers shift away from fluoropolymer surfaces.
France's cookware sector operates under REACH chemical registration, EU F-Gas Regulation for any foamed insulation in thermal cookware, and ANSM oversight on food-contact material compliance. These frameworks compel manufacturers to reformulate coatings and document supply chain substance flows, raising compliance costs but also creating barriers against unverified imports. Stakeholders must monitor the trajectory of EU-wide PFAS restrictions and their specific enforcement calibration by French regulators.
Market Dynamics
EU Green Deal mandates phasing out perfluorinated compounds are forcing coating reformulations across French cookware manufacturing, compressing legacy PTFE supply chains while elevating ceramic and mineral-based alternatives.
Growth Catalysts
- ANSM food-contact enforcement:French regulators are accelerating compliance timelines for migration testing, compelling domestic manufacturers to upgrade quality systems ahead of pan-European PFAS restrictions.
- Île-de-France apartment density:Concentrated urban households in Paris and surrounding departments drive higher replacement frequency for space-efficient, multi-functional cookware sets.
- Ceramic coating chemistry:Sol-gel and sand-derived formulations now achieve thermal stability rivaling fluoropolymers without REACH-registered hazardous substances.
Market Restraints
- Copper raw material volatility:Mauviel and artisan producers face margin pressure from LME copper price swings and limited European smelter capacity.
- Chinese aluminum forging concentration:Mid-market French brands remain dependent on Zhejiang and Guangdong suppliers for spun aluminum bodies, exposing logistics cost spikes.
- Thermal shock limitations:Ceramic-coated vessels cannot withstand the rapid temperature cycling that cast iron and carbon steel tolerate, restricting professional kitchen adoption.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur tourism retail:Culinary vacation traffic through Nice and Marseille creates direct-to-consumer channels for heritage copper and enameled cast iron.
- EU Ecodesign for Sustainable Products Regulation:Upcoming durability labeling requirements will advantage French manufacturers with established lifetime warranty programs.
- Induction compatibility retrofitting:Magnetic steel disc bonding technology opens replacement demand among households transitioning from gas to electric cooktops.
Industry Challenges
- Coating application technician scarcity:Sol-gel ceramic spraying requires precision calibration skills that traditional PTFE line operators lack, lengthening workforce retraining cycles.
- EFSA migration documentation:Each new ceramic formulation demands 18-24 month testing protocols before ANSM market authorization, compressing product development windows.
- Multi-material assembly complexity:Bonding dissimilar metals for induction bases with copper or aluminum cores creates delamination risks under thermal cycling stress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Cookware Market |
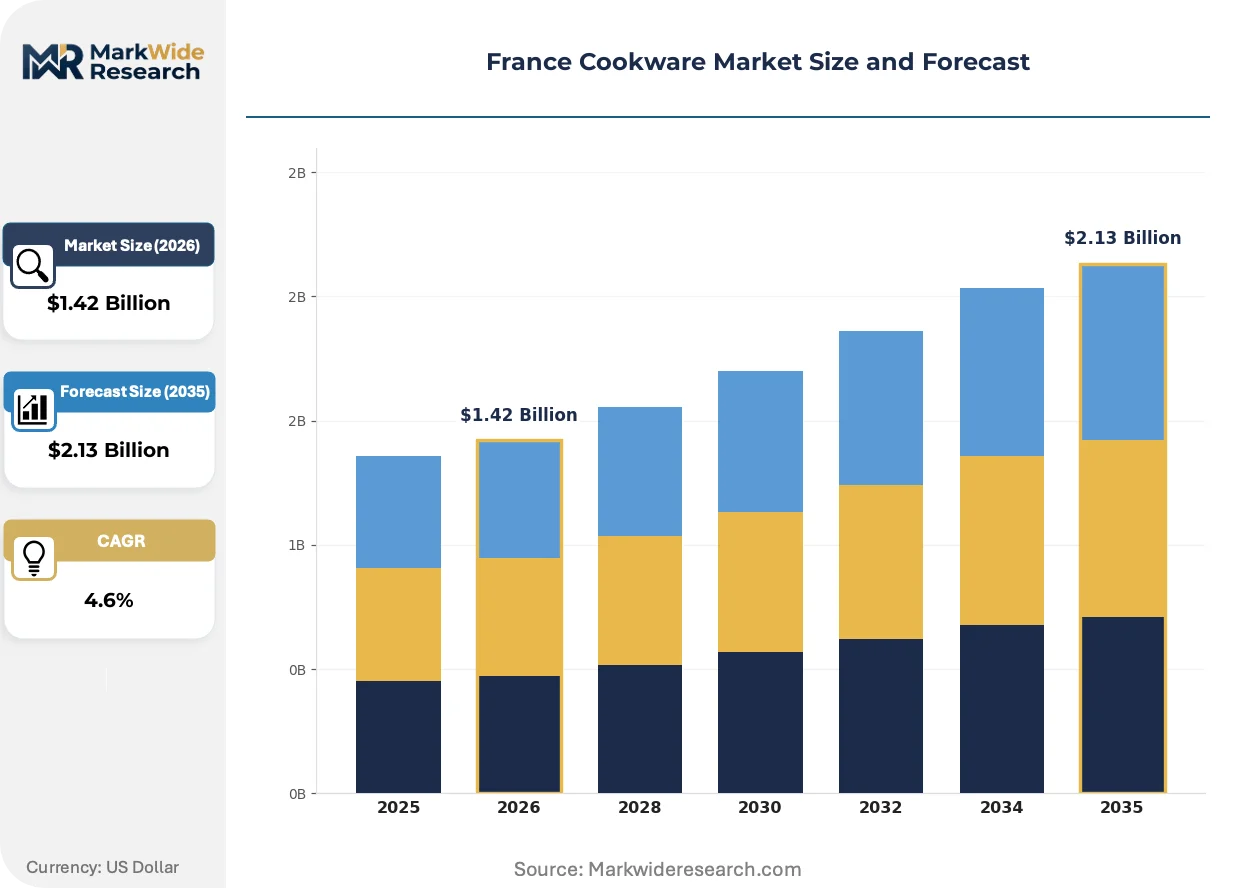
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Stick Pans, Stainless Steel Pots, Cast Iron Skillets, Copper Sauce Pans, Ceramic Cookware, Aluminum Frying Pans Material: Aluminum, Cast Iron, Stainless Steel, Copper, Ceramic, Titanium Application: Residential Cooking, Commercial Kitchens, Catering Services, Culinary Schools, Outdoor Grilling, Food Trucks Distribution Channel: Retail Stores, Online Marketplaces, Specialty Cookware Shops, Wholesale Suppliers, Department Stores, Direct Sales |
| Companies Covered | Matfer Bourgeat, Mauviel, Cristel, Pyrex, Staub, de Buyer, Le Creuset, Groupe SEB S.A., Emile Henry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Cookware Market Shifts & Advancements
Active coating chemistry transitions and retail channel restructuring are compressing traditional product lifecycles while elevating transparency requirements across French cookware supply chains.
Modular cookware systems featuring detachable handles and nesting vessel designs are modularizing kitchen storage economics for urban apartments. Younger households in Lyon and Bordeaux are adopting these configurations at twice the rate of conventional fixed-handle sets. This architecture is modularizing brand loyalty patterns by enabling mix-and-match purchasing across price tiers rather than locked set commitments.
REACH restriction proposals targeting the entire PFAS class are forcing coating suppliers to eliminate side-chain fluorinated polymers previously classified as safe alternatives. French manufacturers must now validate sand-derived ceramic and plasma-enhanced chemical vapor deposition finishes under accelerated ANSM review timelines. Premium stainless steel and bare cast iron segments are capturing buyers who reject any fluorinated surface chemistry regardless of regulatory status.
Direct-to-consumer test kitchen content is displacing traditional retail discovery for cookware purchases. Marseille-based culinary influencers and Paris chef-owned media properties now drive preference formation before store visits. This shift concentrates marketing spend on video production and recipe integration rather than slotting fees, favoring brands with in-house content capabilities over pure manufacturing operations.
France Cookware Market Segmentation
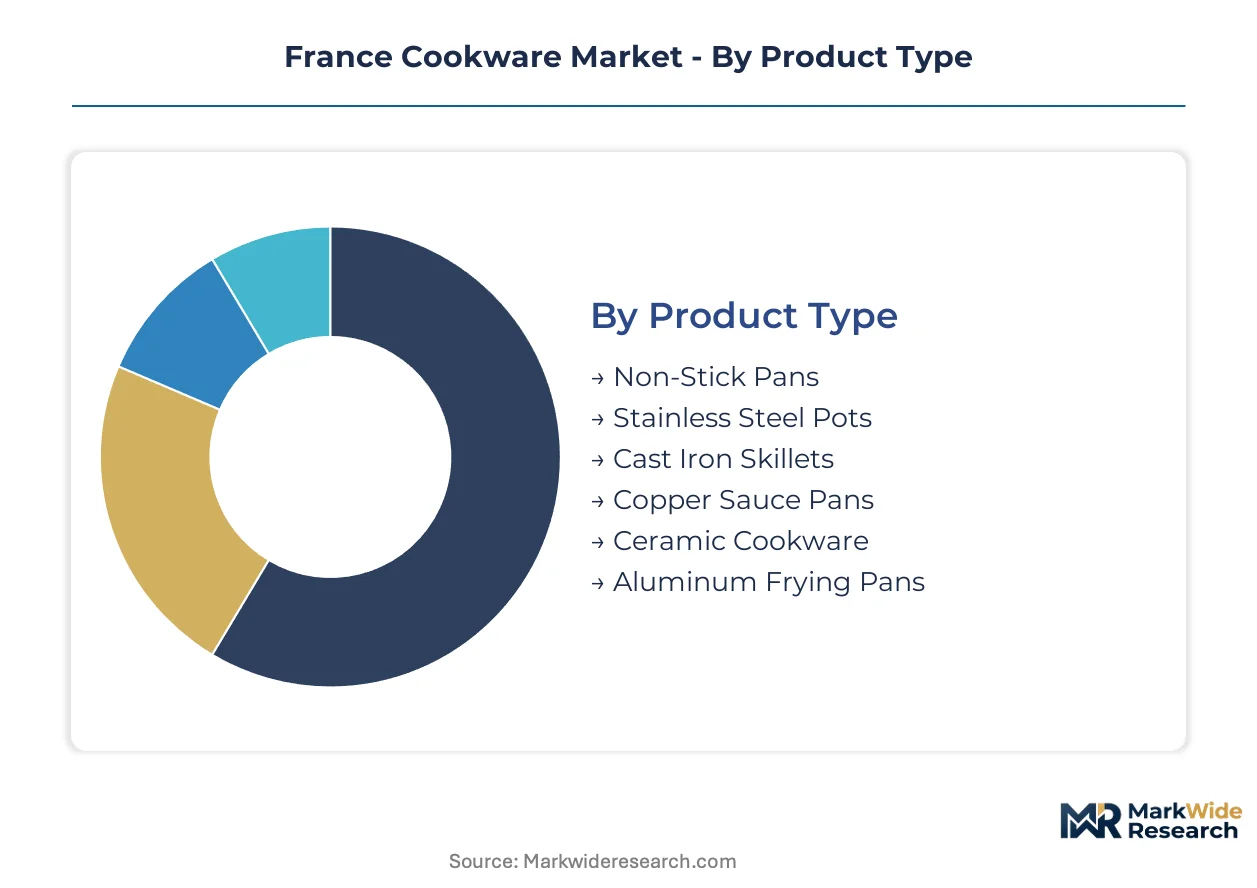
Segmentation in the France cookware market reveals how regulatory pressure and cooking technology shifts fragment demand across distinct compliance tiers. Each category exposes where ANSM testing burdens concentrate and which product configurations capture replacement cycles from fluoropolymer phase-outs.
Product Type:
ANSM food-contact certification requirements vary sharply across product types, with ceramic-coated vessels facing 18-24 month migration testing protocols while bare metal lines clear faster under existing stainless steel standards.
- Non-Stick Pans:Sol-gel ceramic and sand-derived coatings now dominate new launches as REACH restrictions eliminate side-chain fluorinated polymers. Île-de-France apartment households drive replacement demand for space-efficient diameters.
- Stainless Steel Pots:Multi-ply construction with aluminum or copper cores requires bonding precision under thermal cycling stress. These anchor premium tier positioning through lifetime warranty programs and induction compatibility retrofitting.
- Cast Iron Skillets:Bare enamel and seasoned surfaces bypass coating compliance entirely. Heritage brands leverage Normandy manufacturing heritage for artisan positioning.
- Copper Sauce Pans:LME price volatility compresses margins for artisan producers. Limited European smelter capacity creates supply bottlenecks.
- Ceramic Cookware:Sand-derived formulations achieve thermal stability rivaling legacy fluoropolymers without hazardous substance registration.
- Aluminum Frying Pans:Spun bodies remain dependent on Zhejiang and Guangdong suppliers, exposing logistics cost spikes.
Leading the category by volume: Stainless Steel Pots. Growing fastest: Ceramic Cookware.
Material:
Cost stratification across materials mirrors supply chain concentration, with domestic European sourcing commanding premium positioning against Asian-imported substrates.
- Aluminum:Mid-market French brands rely on Chinese forging for spun bodies, creating logistics vulnerability. Induction compatibility retrofitting drives magnetic steel disc bonding demand.
- Cast Iron:Foundry capacity concentrates in traditional manufacturing regions, supporting heritage brand positioning through enameled and bare surface lines.
- Stainless Steel:Multi-ply construction dominates premium tier with copper or aluminum cores. EFSA migration documentation requirements are streamlined for established alloy grades.
- Copper:Artisan segment faces raw material price swings and smelter capacity constraints. Thermal conductivity performance sustains professional kitchen demand despite cost pressure.
- Ceramic:Sol-gel spraying requires precision calibration skills scarce among traditional PTFE line operators. ANSM accelerated review timelines compress product development windows.
- Titanium:Lightweight properties target outdoor and professional mobility applications. Limited domestic processing capacity restricts volume expansion.
Dominating by margin contribution: Stainless Steel. Expanding most quickly: Ceramic.
Application:
End-use concentration determines coating durability requirements and replacement frequency, with professional environments demanding thermal shock tolerance that ceramic surfaces cannot yet deliver.
- Residential Cooking:Île-de-France urban density drives modular cookware adoption with detachable handles and nesting designs. Younger households in Lyon and Bordeaux purchase these configurations at elevated rates.
- Commercial Kitchens:Thermal shock limitations exclude ceramic-coated vessels from rapid temperature cycling applications. Cast iron and carbon steel sustain professional adoption.
- Catering Services:Mobility requirements favor lightweight aluminum and titanium constructions. Volume procurement runs through wholesale supplier relationships.
- Culinary Schools:Training environments demand durable multi-material assemblies. Induction compatibility retrofitting opens replacement demand from gas-to-electric transitions.
- Outdoor Grilling:Portability and thermal extremes favor cast iron and specialized coatings. Seasonal demand patterns concentrate in Provence-Alpes-Côte d'Azur tourism corridors.
- Food Trucks:Space constraints and mobility needs drive compact, multi-functional set configurations. Direct-to-consumer test kitchen content influences preference formation before purchase.
Generating highest unit volume: Residential Cooking. Steepest expansion trajectory: Food Trucks.
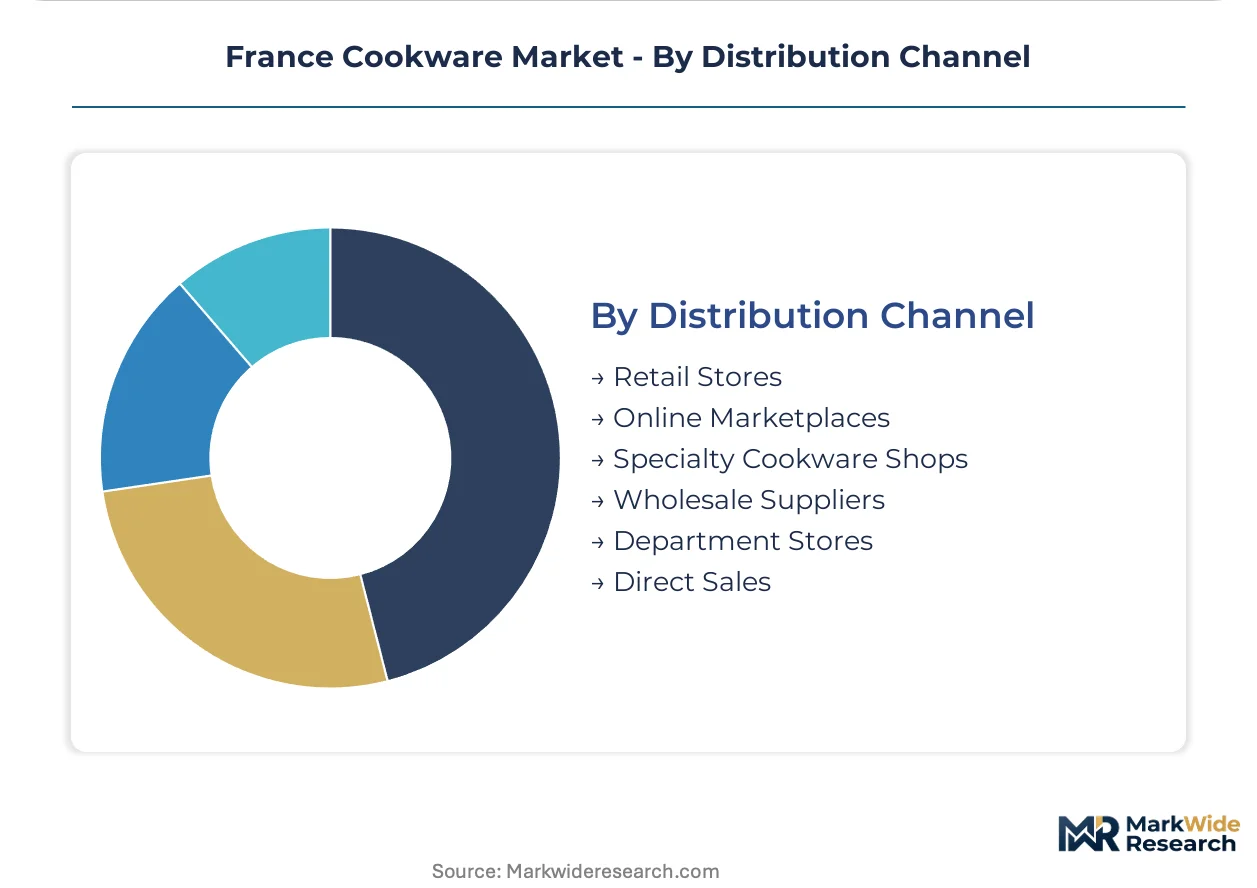
Distribution Channel:
Channel mix reflects generational purchasing behavior divergence, with content-driven discovery displacing traditional retail slotting economics.
- Retail Stores:Mass-market penetration concentrates multi-brand presence. Groupe SEB S.A. leverages in-house production scale for shelf positioning.
- Online Marketplaces:Direct-to-consumer test kitchen content from Marseille influencers and Paris chef-owned media properties now drives preference formation before transaction.
- Specialty Cookware Shops:Heritage copper and enameled cast iron lines sustain artisan margin pools through consultative selling and lifetime warranty positioning.
- Wholesale Suppliers:Commercial and institutional procurement channels favor volume pricing and standardized specifications.
- Department Stores:Premium positioning aligns with gift purchasing and tourism retail traffic through Nice and Marseille culinary vacation corridors.
- Direct Sales:Brand-owned content capabilities enable recipe integration and video production investment, favoring integrated manufacturers over pure production operations.
Capturing largest revenue share: Retail Stores. Gaining share fastest: Online Marketplaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's Qualité France certification zones concentrate premium cookware assembly and testing facilities near Paris logistics corridors. ANSM enforcement laboratories in Lyon and Marseille calibrate migration testing standards that suppliers across all French regions must meet.
Île-de-France
Paris apartment density drives replacement frequency for space-efficient, multi-functional cookware sets. EU Green Deal PFAS phase-out mandates accelerate coating reformulations among manufacturers headquartered in this region. Saint-Denis and Bobigny industrial zones host ceramic coating application facilities serving mass-market distribution channels.
Auvergne-Rhône-Alpes
Lyon's culinary school concentration generates institutional procurement demand for durable multi-material assemblies. REACH chemical registration requirements compel local stainless steel fabricators to document supply chain substance flows. Saint-Étienne retains foundry capacity for enameled cast iron production lines.
Provence-Alpes-Côte d'Azur
Tourism retail through Nice and Marseille creates direct-to-consumer channels for heritage copper and enameled cast iron. ANSM accelerated review timelines for ceramic formulations compress product development windows for regional coating suppliers. Aix-en-Provence hosts test kitchen content production studios influencing preference formation.
Hauts-de-France
Proximity to Belgian aluminum forging networks supports spun body sourcing for mid-market French brands. EU F-Gas Regulation compliance raises costs for any thermal cookware with foamed insulation components manufactured here. Lille logistics hubs coordinate Zhejiang and Guangdong supplier shipments.
Normandy
Mauviel leverages Villedieu-les-Poêles manufacturing heritage to sustain artisan positioning in copper and stainless steel segments. EFSA migration documentation requirements for new alloy grades streamline faster for established local producers. Bayeux and Caen retail corridors distribute heritage lines to culinary tourism circuits.
France Cookware Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage artisans commanding premium tier margins while mass-market volume concentrates through integrated production groups. The vendor base organizes around three strategic archetypes: Normandy-based heritage metalworkers, multi-brand conglomerates with in-house aluminum and cast iron lines, and ceramic coating technology specialists. Consolidation pressure favors manufacturers with captive foundry capacity or direct retail channel control. Competitive moves center on induction compatibility retrofitting investments and direct-to-consumer content capabilities that displace traditional slotting fee economics.
Within the heritage artisan tier, Mauviel and Le Creuset exemplify manufacturing-origin positioning that converts geographic provenance into pricing power. Groupe SEB S.A. anchors the scale-driven end through multi-brand retail penetration and in-house production breadth. Among ceramic-focused specialists, Emile Henry occupies a position bridging traditional terracotta craftsmanship with sol-gel coating transitions. These three archetypes—heritage metalworker, integrated conglomerate, and material specialist—capture distinct margin pools as ANSM compliance costs reshape competitive barriers.
| Leading Market Players |
|---|
| Matfer Bourgeat |
| Mauviel |
| Cristel |
| Pyrex |
| Staub |
| de Buyer |
| Le Creuset |
| Groupe SEB S.A. |
| Emile Henry |
| Others |
Supply & Pricing Matrix
LME copper price volatility cascades through French cookware supply chains, compressing margins for Normandy-based artisans while amplifying cost advantages for conglomerates with captive aluminum forging capacity and multi-brand retail leverage.
Pricing Analysis
Short lead-time premiums reward domestic ceramic coating facilities in Saint-Denis and Bobigny against Chinese-imported spot inventory carrying logistics risk. Three-tier pricing structure across heritage copper, multi-ply stainless steel, and spun aluminum economy lines differentiates by certification grade and induction compatibility. Cost compression in mid-market aluminum runs through Zhejiang supplier concentration and freight rate exposure. Price-sensitive mass-market buyers in Île-de-France apartment households trade warranty duration for unit cost, while commercial kitchens absorb premium tier pricing for thermal shock tolerance.
Supply Chain Analysis
EU Green Deal domestic-content calibration for PFAS-free coatings is reshaping sourcing toward ANSM-authorized ceramic application facilities in metropolitan France. Raw material feeds draw from Chinese aluminum forging clusters, Chilean copper cathode, and European stainless steel mills. Single-source vulnerability concentrates in sol-gel precursor chemicals where REACH registration limits qualified suppliers. Distribution runs through Groupe SEB's multi-brand retail penetration and direct-to-consumer test kitchen content from Marseille production studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France cookware market functions as a cost-of-compliance arena where ANSM migration testing timelines create a regulatory moat favoring incumbent manufacturers with established documentation systems and captive laboratory relationships.
For Market Incumbents: Cement artisan positioning through lifetime warranty programs that convert copper and enameled cast iron heritage into replacement-resistant installed bases. Deepen backward integration into Normandy foundry capacity to insulate margin pools from LME price swings and Chinese logistics disruption. Channel control through direct-to-consumer test kitchen content displaces slotting fee economics.
For New Entrants and Emerging Players: Capture food truck and outdoor grilling white space where compact multi-functional configurations meet mobility demand with lower certification burdens than commercial kitchen specifications. Provence-Alpes-Côte d'Azur tourism retail corridors offer penetrable direct-to-consumer channels bypassing mass-market shelf access barriers. Recipe-integrated video production from Aix-en-Provence studios enables preference formation before purchase.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ceramic coating technology specialists with ANSM pre-authorized formulations in Île-de-France industrial zones, as REACH PFAS restrictions compress legacy PTFE operator valuations. Long-term viability hinges on induction compatibility retrofitting capabilities and sol-gel spraying precision skills. Watch EFSA migration documentation backlogs as inflection signal for product development velocity gaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Certification Investment | ANSM pre-authorization compresses competitor product development windows by 18-24 months. |
| Induction Compatibility Retrofitting | Magnetic steel disc bonding technology captures gas-to-electric cooktop transition replacement cycles. |
| Direct-to-Consumer Content Production | Paris and Marseille test kitchen studios displace traditional retail discovery for preference formation. |
| Heritage Brand Warranty Extension | Lifetime coverage on copper and enameled cast iron converts manufacturing provenance into pricing power. |
| Backward Integration into Foundry Capacity | Captive enameled cast iron production in Saint-Étienne insulates margins from raw material volatility. |
Research Methodology
Document review covered ANSM food-contact compliance filings, EU REACH substance registration databases, and EFSA migration limit protocols, complemented by interviews with ceramic coating application technicians, stainless steel procurement leads at multi-brand retailers, and heritage brand manufacturing directors in Normandy. Secondary validation drew from customs trade records for aluminum forging imports, LME copper price series, and retail audit data tracking modular cookware adoption rates. Bottom-up demand modeling triangulated against top-down sector expenditure estimates.
Segmentation outputs across product type, material grade, application end-use, and distribution channel dimensions were projected across the analysis window using penetration rate trajectories and replacement cycle frequencies. CAGRs derived from regression against residential cooking equipment expenditure indices and commercial kitchen capital formation trends. Industry-specific inputs included ANSM enforcement acceleration timelines and EU Ecodesign durability labeling implementation schedules.
The model holds under stable REACH PFAS restriction trajectories and ANSM laboratory capacity expansion; deviation in ceramic coating precursor supply constraints or LME copper price spike duration would shift volume and value envelopes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Electric Pressure Cooker Market