
 US Cookware Market | 2026-2036
US Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
US Cookware Market Insights
The capital-intensity divergence between legacy foundries and digitally native brands is rotating competitive advantage toward direct-to-consumer infrastructure. Lodge Cast Iron leverages its Tennessee foundry and century-old brand equity to dominate cast iron segments. Made In competes through chef-backed credibility and transparent supply chain storytelling. Newell Brands Inc. sustains mass-market reach through diversified retail distribution and portfolio breadth.
US cookware encompasses metal vessels engineered for thermal conductivity, food safety, and repeated thermal cycling between ambient and cooking temperatures, typically constructed from stainless steel alloys, cast iron, aluminum cores, or ceramic-reinforced non-stick composites. Its primary commercial purpose centers on controlled heat transfer for residential food preparation and professional kitchen operations. Stainless steel fry pans and saucepans anchor margin pools due to premium pricing and replacement cycles, while non-stick Dutch ovens represent the fastest-growing material-format combination as home cooks seek versatile, low-maintenance vessels. Cast iron stock pots remain a mature, heritage-driven category with concentrated regional loyalty in the Southeast.
The FDA governs food-contact substance notifications under 21 CFR, while California Proposition 65 mandates chemical disclosure for per- and polyfluoroalkyl substances in non-stick coatings, pressuring reformulation across the supply chain. The Consumer Product Safety Commission monitors thermal hazard reporting, shaping product liability exposure for manufacturers. Stakeholders must monitor evolving state-level chemical bans and third-party certification requirements as purchase criteria harden.
Market Dynamics
California Proposition 65 enforcement is fragmenting non-stick coating supply chains as manufacturers scramble to eliminate per- and polyfluoroalkyl substances ahead of disclosure mandates. Home cooks in metropolitan Texas and California markets are accelerating replacement cycles, pressuring inventory planning across retail channels.
Growth Catalysts
- Chef-backed credibility models:Culinary professional endorsements are compressing consumer decision timelines for premium stainless steel collections. Home cooks seek provenance transparency before purchase.
- FDA food-contact substance notifications:Clear regulatory pathways under 21 CFR are enabling faster material innovation cycles for ceramic-reinforced composites. Compliance clarity reduces reformulation risk.
- Southeast regional heritage loyalty:Concentrated cast iron demand in Tennessee-adjacent markets sustains foundry utilization rates. Regional cooking traditions anchor replacement demand.
Market Restraints
- Aluminum core price volatility:Raw material input swings compress margin predictability for clad construction cookware. Multi-ply manufacturing requires hedging strategies.
- Chinese non-stick coating concentration:Supply chain vulnerability concentrates in foreign fluoropolymer substrate production. Domestic reformulation capacity remains limited.
- PFAS technical substitution ceiling:Ceramic alternatives currently fail to match thermal durability thresholds for professional kitchen thermal cycling. Performance gaps constrain category migration.
Strategic Opportunities
- Texas metropolitan market expansion:Underpenetrated Dallas-Fort Worth and Houston suburbs present whitespace for direct-to-consumer showroom concepts. Population inflows sustain addressable market growth.
- Induction cooktop convergence:Magnetic-responsive base technology integration opens compatibility with electrified residential kitchen retrofits. Federal electrification incentives accelerate appliance turnover.
- Third-party certification channels:Green Seal and Cradle to Cradle verification programs are emerging as retail gatekeepers for shelf placement. Early certification captures preferential merchandising.
Industry Challenges
- Artisan foundry skill attrition:Seasoned mold-making craft knowledge is concentrating among retiring Tennessee and Pennsylvania workforces. Knowledge transfer mechanisms remain underdeveloped.
- California Proposition 65 compliance timeline compression:Warning label requirements for legacy inventory create working capital strain. Retailers demand indemnification clauses for stocked goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cookware Market |
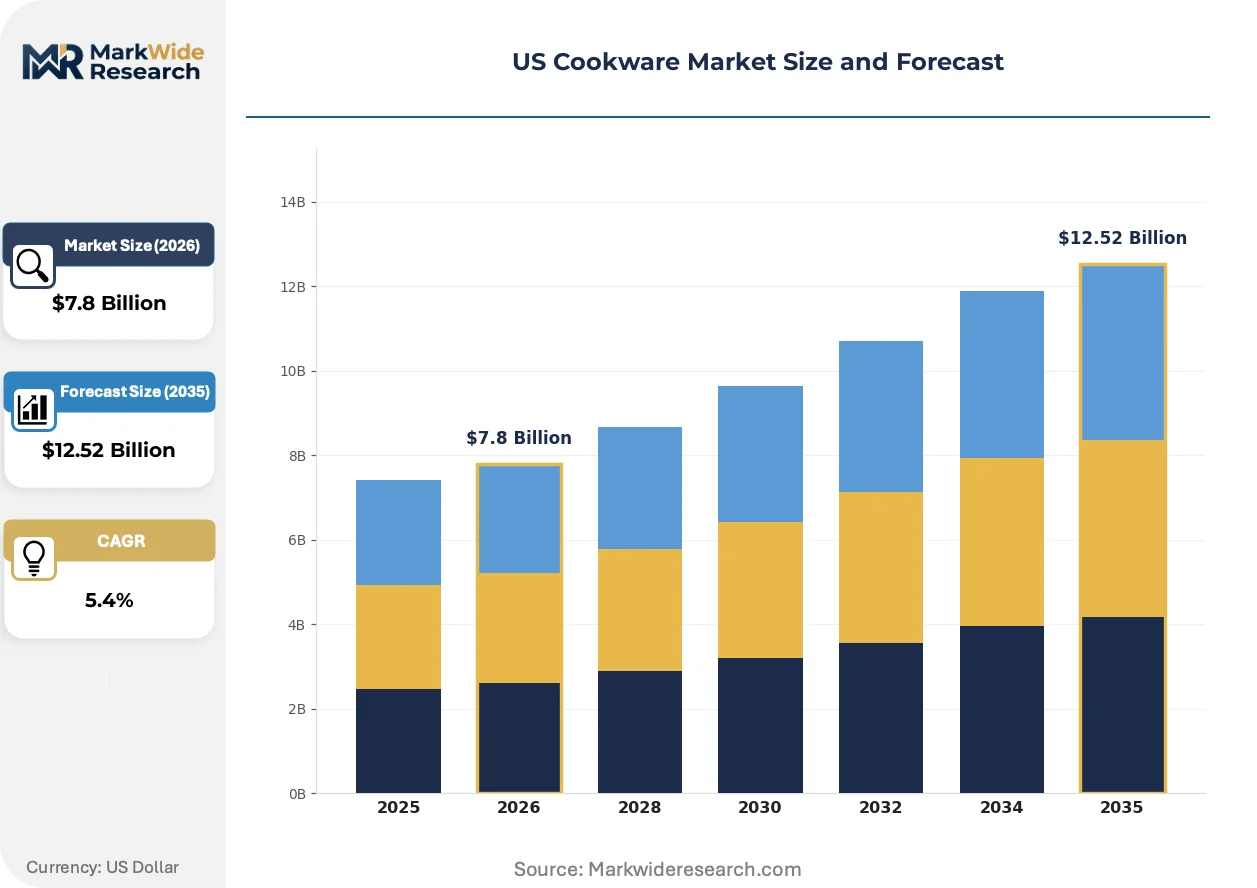
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fry Pans, Saucepans, Stock Pots, Dutch Ovens Material: Stainless Steel, Cast Iron, Non-Stick, Copper Customer Type: Home Cooks, Professional Chefs, Culinary Schools, Restaurants Distribution Channel: Online Retail, Department Stores, Specialty Stores, Wholesale |
| Companies Covered | Made In, Lodge Cast Iron, All-Clad, Crate & Barrel, Ninja, Newell Brands Inc., Heritage Steel Cookware, GreenPan, Meyer Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cookware Market Trends and Innovations
Material science breakthroughs and regulatory disclosure mandates are converging to reshape competitive advantage around verifiable supply chain transparency rather than performance claims alone.
Ceramic-reinforced non-stick composites are fragmenting the traditional fluoropolymer-dominated coating market as home cooks seek visible alternatives to PFAS-based surfaces. Premium segment buyers are adopting these materials at accelerated replacement cycles despite modest durability trade-offs. The technology is fragmenting supplier consolidation by enabling smaller formulation houses to compete on chemical simplicity rather than patent-protected polymer complexity.
FDA enforcement discretion letters regarding food-contact substance notifications are tightening evidentiary standards for new coating chemistries entering commercial distribution. Manufacturers must now submit comprehensive migration studies before market entry, extending development timelines. California-based brands face the steepest compliance burden as Proposition 65 private enforcement actions create parallel liability exposure.
Direct-to-consumer subscription models for cookware replacement are displacing traditional retail purchase patterns among millennial and Gen-Z household formations. Chef-influencer content channels are compressing consideration phases by embedding product demonstration within entertainment formats. This behavioral shift concentrates in coastal metropolitan markets where kitchen space constraints favor modular, multi-functional vessel acquisition over comprehensive set purchases.
US Cookware Market Segmentation
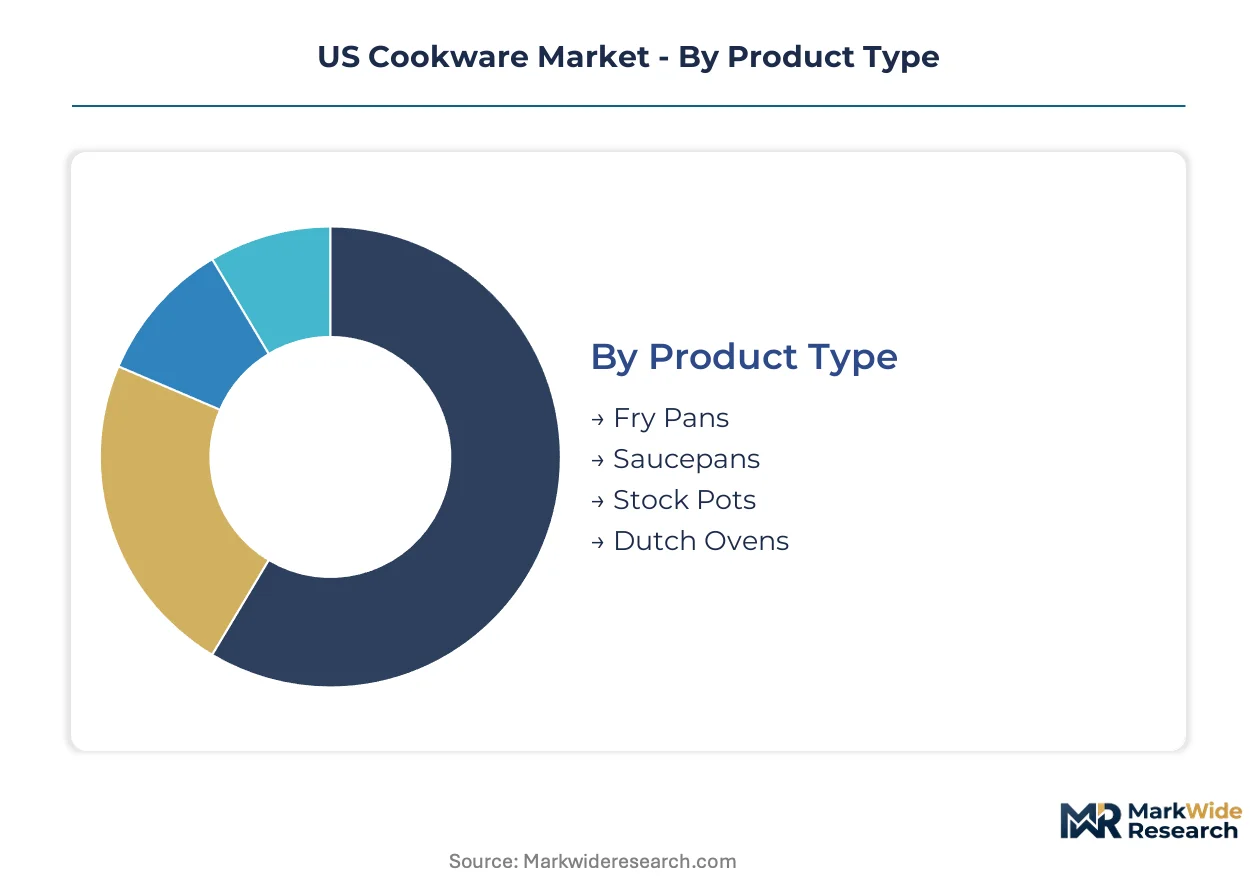
Cookware purchasing patterns diverge sharply across use cases and buyer sophistication. Material composition and distribution access determine margin capture and replacement frequency for manufacturers serving distinct kitchen environments.
Product Type:
Domestic residential demand anchors volume for most formats, while professional kitchen procurement concentrates in metropolitan Texas and California markets.
- Fry Pans:Flat-bottomed vessels with sloped sides engineered for rapid heat response and tossing motion. Demand concentrates in California metropolitan markets where home cooks prioritize multi-functional surface area. Chef-backed credibility models compress decision timelines for premium stainless steel variants.
- Dutch Ovens:Heavy-walled lidded vessels with enamel or raw cast iron construction for slow, even thermal distribution. Southeast regional heritage loyalty sustains replacement cycles in Tennessee-adjacent markets. The format gains traction as home cooks seek versatile, low-maintenance vessels for braising and baking.
- Saucepans:Medium-depth vessels with vertical walls and long handles for liquid reduction and sauce preparation.
- Stock Pots:Large-capacity vessels with fitted lids designed for boiling pasta, stocks, and batch cooking.
Fry pans command the established base. The steepest expansion runs through Dutch ovens.
Material:
Cost tier stratification separates premium metals from mass-market coatings, with regulatory pressure reshaping the non-stick segment.
- Stainless Steel:Chromium-nickel alloys offering corrosion resistance and thermal stability without reactive surface chemistry. Professional chefs in Dallas-Fort Worth and Houston drive specification for clad construction with aluminum cores. Margin pools concentrate here due to premium pricing and replacement cycles.
- Non-Stick:Ceramic-reinforced composites or legacy fluoropolymer coatings engineered for food release with minimal fat. California Proposition 65 enforcement fragments supply chains as manufacturers eliminate PFAS ahead of disclosure mandates. Home cooks seek visible alternatives despite modest durability trade-offs.
- Cast Iron:Ferrous carbon alloys requiring seasoning maintenance for natural non-stick properties.
- Copper:Pure or tin-lined metal delivering unmatched thermal conductivity for precise temperature control.
Stainless steel commands the established base. Ceramic-reinforced non-stick coatings are climbing the fastest.
Customer Type:
Volume concentration sits with residential buyers, while professional segments drive specification standards that cascade into consumer preferences.
- Home Cooks:Residential purchasers acquiring vessels for daily meal preparation and occasional entertaining. Direct-to-consumer subscription models displace traditional retail patterns among millennial and Gen-Z household formations in coastal metropolitan markets. Chef-influencer content compresses consideration phases.
- Restaurants:Commercial operators requiring thermal durability for high-cycle professional kitchen environments. Texas metropolitan market expansion presents whitespace for direct-to-consumer showroom concepts targeting independent operators. Induction cooktop convergence opens compatibility with electrified kitchen retrofits.
- Professional Chefs:Individual culinary practitioners purchasing personal collections or endorsing branded lines.
- Culinary Schools:Institutional training programs sourcing standardized equipment for student instruction.
Home cooks command the established base. Restaurant procurement is gaining share fastest.
Distribution Channel:
Supply concentration varies by channel control, with digital native brands capturing margin through bypassed wholesale layers.
- Online Retail:Direct-to-consumer and marketplace platforms enabling transparent supply chain storytelling and chef-backed credibility. Made In competes through this channel with chef partnerships. Third-party certification programs emerge as digital gatekeepers for preferential merchandising.
- Specialty Stores:Curated physical retail emphasizing tactile evaluation and staff expertise. Green Seal and Cradle to Cradle verification programs increasingly determine shelf placement. Regional concentration in California and Texas metropolitan markets.
- Department Stores:Mass-market retail relying on diversified portfolio breadth and promotional velocity.
- Wholesale:B2B supply to restaurants, culinary schools, and institutional foodservice operations.
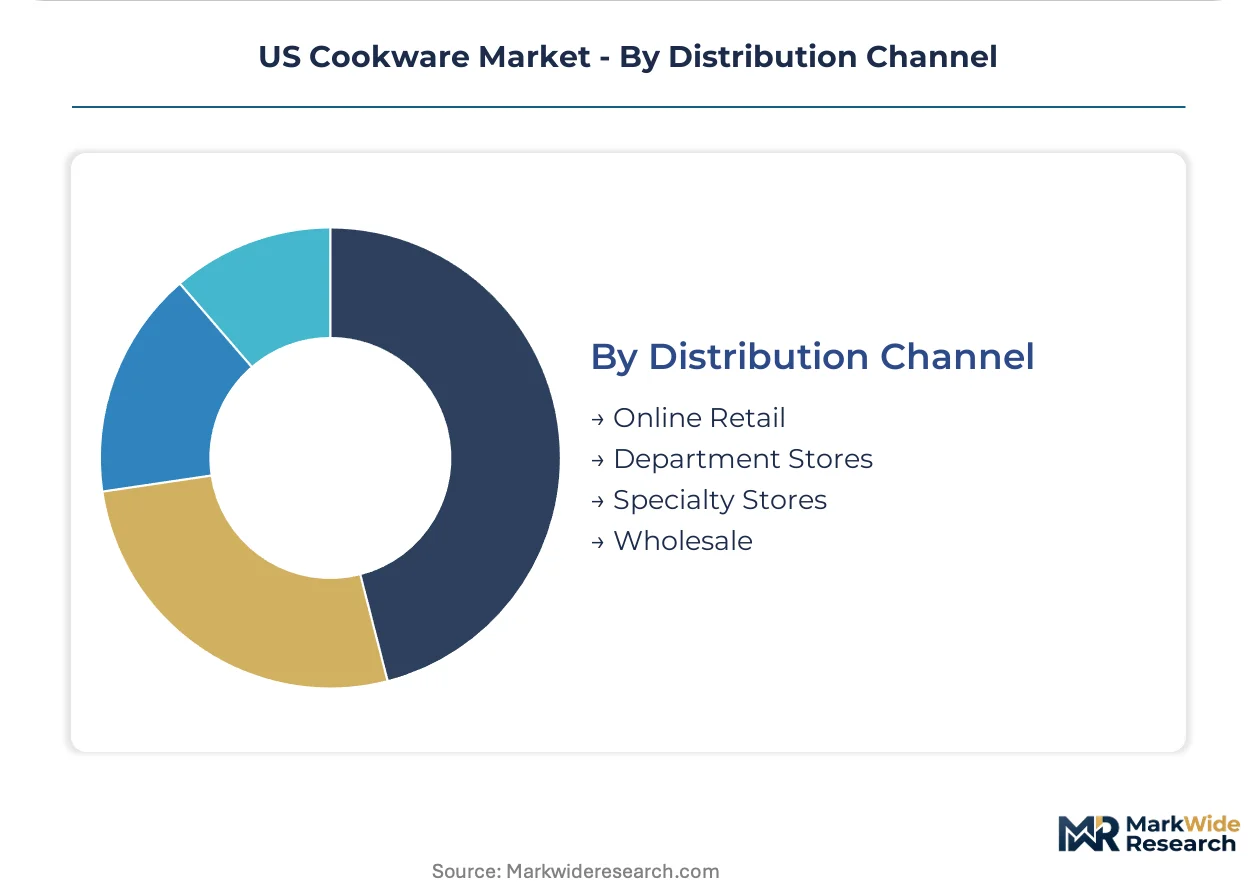
Department stores command the established base. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California metropolitan markets while Texas suburban corridors absorb volume at compressed margins. This asymmetry reflects divergent regulatory exposure and replacement cycle velocity across state boundaries.
California
Home cooks in Los Angeles and San Francisco metro areas accelerate replacement cycles for ceramic-reinforced non-stick formats. Proposition 65 enforcement against PFAS-containing legacy inventory creates working capital strain for distributors. Third-party certification programs like Green Seal operate as retail gatekeepers in San Diego specialty channels.
Texas
Dallas-Fort Worth and Houston suburbs present whitespace for direct-to-consumer showroom concepts targeting induction-compatible collections. Federal electrification incentives accelerate residential kitchen retrofits in Austin metropolitan corridors. Independent restaurant procurement in Houston drives specification for clad stainless steel construction.
Tennessee
Southeast regional heritage loyalty sustains cast iron foundry utilization rates in Appalachian-adjacent manufacturing clusters. Seasoned mold-making craft knowledge concentrates among retiring workforces in Chattanooga and Knoxville industrial zones. Lodge Cast Iron anchors regional supply chain employment through century-old Tennessee foundry operations.
New York Metro
Chef-influencer content production in Brooklyn and Manhattan compresses consumer consideration phases for premium stainless steel collections. FDA food-contact substance notification pathways enable faster material innovation cycles for ceramic-reinforced composites. Specialty retail concentration in SoHo and Williamsburg channels third-party certification requirements.
Illinois
Chicago metropolitan distribution hubs consolidate wholesale supply to Midwestern culinary schools and institutional foodservice operations. Aluminum core price volatility compresses margin predictability for regional clad construction manufacturers. Department store promotional velocity in suburban Cook County sustains mass-market volume.
US Cookware Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with digitally native brands capturing margin through direct-to-consumer infrastructure while legacy foundries defend position through manufacturing scale. The vendor base fragments across three strategic tiers: heritage foundry operators, chef-backed premium challengers, and diversified mass-market conglomerates. Consolidation pressure concentrates in the non-stick coating segment as Proposition 65 compliance costs squeeze mid-tier formulation houses. Competitive moves center on vertical integration into ceramic substrate production and geographic expansion into underpenetrated Texas metropolitan corridors.
Among heritage foundry operators, Lodge Cast Iron occupies a position exemplifying regional manufacturing concentration and brand equity accumulation. Made In and All-Clad represent the chef-backed premium tier, with Made In anchoring direct-to-consumer credibility models and All-Clad sitting within the established stainless steel specification hierarchy. Newell Brands Inc. exemplifies the diversified mass-market conglomerate archetype, sustaining reach through portfolio breadth and promotional velocity across retail channels.
| Leading Market Players |
|---|
| Made In |
| Lodge Cast Iron |
| All-Clad |
| Crate & Barrel |
| Ninja |
| Newell Brands Inc. |
| Heritage Steel Cookware |
| GreenPan |
| Meyer Corporation |
| Others |
Pricing and Supply Chain Analysis
Foundry scale economies in Tennessee and Pennsylvania anchor domestic cast iron production, creating price floors that smaller ceramic-coating competitors struggle to match while compressing margin recovery for mid-tier stainless steel fabricators. Capacity utilization at Lodge Cast Iron's South Pittsburg facility shapes regional employment patterns and sets thermal-cycling quality benchmarks that premium challengers must exceed to justify clad-construction premiums.
Pricing Analysis
Chef-configured premium spreads separate Made In's direct-to-consumer configured-to-order collections from mass-market standard SKUs stocked at Newell Brands retail partners. Three-tier pricing structure across premium chef-backed, standard clad construction, and economy aluminum-core levels stratifies buyer access. Price differentiation hinges on Proposition 65 compliance certification and induction-base magnetic responsiveness. Cost compression in non-stick tiers is intensifying because ceramic substrate reformulation extends development timelines. Home cooks in Texas metropolitan corridors show least price sensitivity for induction-compatible stainless steel, while mass-market department store buyers drive hardest bargain on promotional velocity.
Supply Chain Analysis
Port congestion at Long Beach and Savannah strains inbound logistics for Chinese fluoropolymer substrates and South Korean ceramic coating precursors. Raw material dependencies center on Appalachian pig iron, Australian bauxite for aluminum cores, and imported ceramic nanoparticle suspensions. Single-source vulnerability concentrates in Tennessee foundry mold-making craft knowledge as retiring workforces thin. Distribution runs through direct-to-consumer platforms, specialty retail in California and Texas metropolitan markets, and diversified wholesale to restaurant procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic-reinforced non-stick composites threaten legacy fluoropolymer incumbents as Proposition 65 enforcement accelerates substitution timelines. Incumbents must defend specification hierarchies while reformulating coating chemistry ahead of disclosure mandates.
For Market Incumbents: Secure Tennessee and Pennsylvania foundry capacity through knowledge-transfer apprenticeships before retiring mold-making expertise concentrates further. Backward integration into ceramic substrate production reduces Chinese fluoropolymer dependency. Lodge Cast Iron's century-old regional employment anchors defend against premium challengers seeking chef credibility shortcuts. For New Entrants and Emerging Players: Anchor in Dallas-Fort Worth and Houston showroom whitespace for induction-compatible collections targeting federal electrification retrofits. Target independent restaurant procurement in Texas metropolitan markets where clad stainless steel specification remains underpenetrated. Chef-influencer content partnerships compress consideration phases for digitally native brand launches. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic-coating formulation houses with FDA food-contact substance notification pathways already cleared. Long-term viability across the analysis window rests on Proposition 65 compliance infrastructure and induction-base magnetic responsiveness capabilities. Watch private enforcement action volume against legacy PFAS inventory as inflection indicator for working capital strain severity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Reformulation | Proposition 65 compliance eliminates PFAS liability exposure for California-facing brands. |
| Induction-Base Integration | Federal electrification incentives accelerate residential kitchen retrofit addressable market expansion. |
| Direct-to-Consumer Showroom Expansion | Texas metropolitan population inflows sustain underpenetrated Dallas-Fort Worth and Houston whitespace capture. |
| Chef Partnership Credibility Models | Made In's transparent supply chain storytelling compresses millennial and Gen-Z decision timelines. |
| Third-Party Certification Investment | Green Seal and Cradle to Cradle verification secures preferential specialty retail shelf placement. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with cookware brand managers, foundry operations directors, specialty retail category buyers, and restaurant procurement officers; and secondary validation through FDA food-contact substance notification filings, CPSC thermal hazard reports, California Proposition 65 enforcement databases, and customs records tracking aluminum and ceramic coating imports. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic consumption indicators anchored forecast robustness.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, material composition, customer sophistication tier, and distribution channel control. CAGRs derived from replacement cycle velocity analysis, regulatory compliance cost pass-through elasticity, and metropolitan market penetration saturation curves. Induction cooktop adoption rates and chef-influencer content engagement metrics served as category-specific demand shapers.
Material uncertainties — abrupt California Proposition 65 enforcement escalation, Chinese fluoropolymer export restriction, or aluminum core commodity price spikes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and ceramic alternative performance gap closure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market