
 Canada Kitchen Appliances Market | 2026-2036
Canada Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Kitchen Appliances Market Outlook
Natural Resources Canada's EnerGuide efficiency mandates is consolidating demand around ENERGY STAR-certified refrigeration and cooking equipment. Whirlpool Corporation leverages its North American manufacturing footprint to sustain competitive positioning in mid-market dishwashers and ovens. Samsung Electronics differentiates through connected kitchen ecosystems that integrate with broader smart home platforms. BSH Hausgeräte anchors the premium built-in segment with specialized cooking appliances targeting custom residential installations.
Canada kitchen appliances encompass electrically or gas-powered equipment designed for food storage, preparation, and cleaning in residential and commercial settings, typically operating at 120V/240V with energy consumption measured in kilowatt-hours annually under standardized testing protocols. Refrigerators command the largest product category share due to universal household necessity and replacement-driven purchase cycles, while smart appliances represent the fastest-expanding technology segment as Wi-Fi connectivity and voice control become standard features in new construction. The residential end-user base dominates volume, though commercial kitchens in hospitality and food service generate higher per-unit margins through specification-grade durability requirements.
Health Canada and the Canadian Standards Association (CSA Group) jointly govern electrical safety and performance certification, effectively barring uncertified imports from mass-market distribution channels. Natural Resources Canada's EnerGuide labeling program and ENERGY STAR Canada specifications directly influence consumer purchasing decisions and manufacturer R&D priorities by mandating transparent efficiency disclosure. The Competition Bureau monitors environmental marketing claims to prevent greenwashing in appliance advertising. Stakeholders must track evolving federal efficiency standards and provincial rebate programs to anticipate demand shifts and inventory requirements.
Market Dynamics
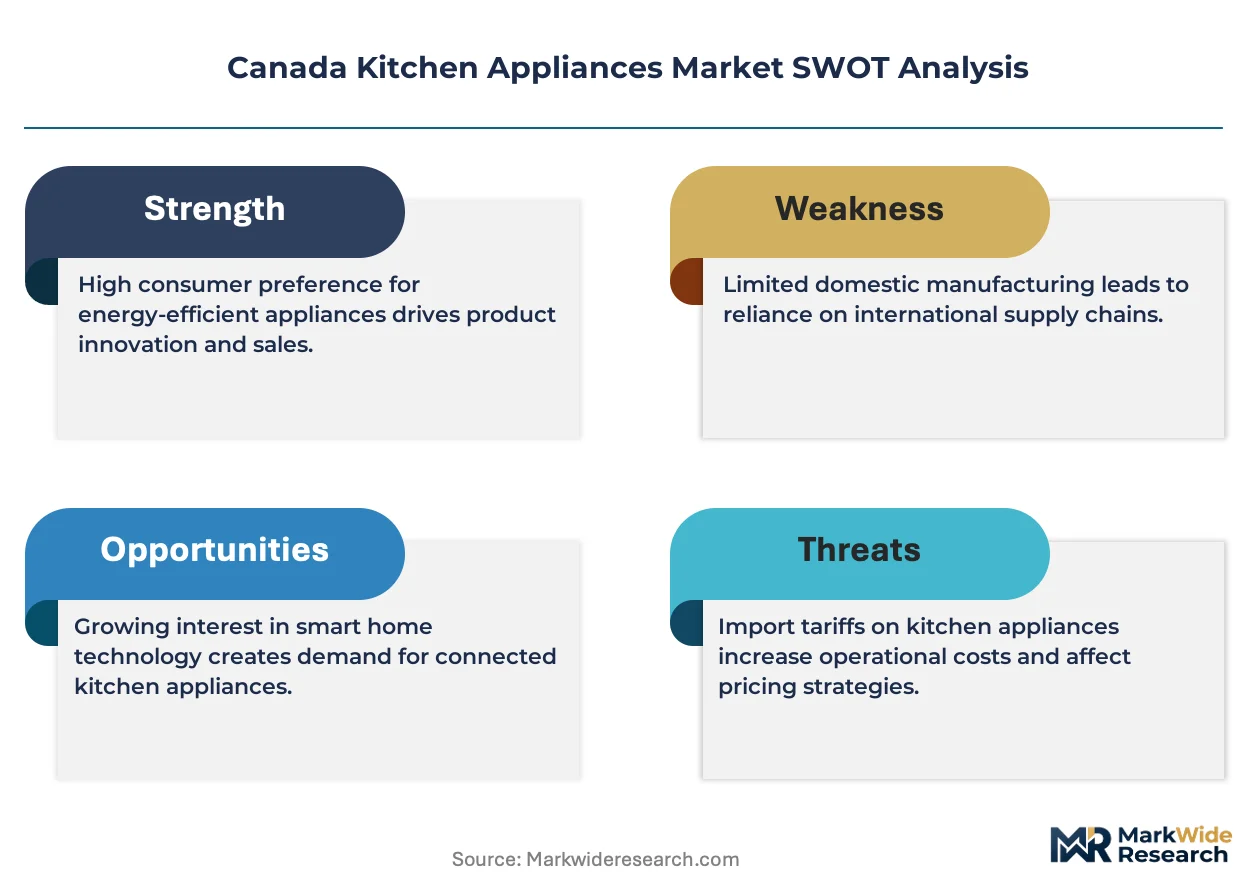
Natural Resources Canada's EnerGuide efficiency mandates and provincial rebate programs are compressing replacement cycles while forcing manufacturers to redesign core refrigeration and cooking platforms around kilowatt-hour performance thresholds.
Growth Catalysts
- EnerGuide Labeling Mandate:Federal transparency requirements on annual energy consumption are steering condominium developers in Toronto and Vancouver toward specification-grade ENERGY STAR-certified appliances.
- Smart Home Integration:Wi-Fi-enabled cooking and refrigeration equipment is converging with broader residential automation systems, creating pull-through demand from new construction in Ontario and British Columbia.
- High-Density Housing Concentration:Vancouver's tower development corridor and Toronto's condominium pipeline are generating concentrated demand for compact, built-in appliance configurations.
Market Restraints
- Steel and Aluminum Input Volatility:Raw material cost swings for appliance housings and compressor components are compressing margin structures for mid-market manufacturers.
- CSA Certification Timeline:Canadian Standards Association electrical safety testing creates 12-18 month product introduction delays that disadvantage smaller import brands against established domestic portfolios.
- Apartment-Size Substitution:Compact refrigeration and two-burner cooking configurations in micro-units are displacing full-size appliance demand in Vancouver's sub-500-square-foot housing stock.
Strategic Opportunities
- Atlantic Canada Underpenetration:Halifax and Moncton residential construction is running below national smart-appliance penetration rates, creating first-mover positioning for connected kitchen platforms.
- Provincial Rebate Stacking:Ontario's Save on Energy program and British Columbia's CleanBC incentives are creating combined federal-provincial subsidy pools that reduce consumer out-of-pocket costs for premium efficiency tiers.
- Voice-Assisted Cooking Convergence:Amazon Alexa and Google Assistant integration with induction cooktops and wall ovens is opening specification channels with custom home builders in Calgary's luxury segment.
Industry Challenges
- Field Service Technician Scarcity:Smart appliance diagnostics and IoT connectivity repair skills are concentrating in Toronto and Vancouver, leaving Atlantic Canada and Prairie provinces underserved for warranty fulfillment.
- Legacy Electrical Infrastructure:120V/240V split-phase wiring in pre-1990s housing stock across Montreal and Quebec City is complicating induction cooktop retrofits and requiring costly panel upgrades.
- Competition Bureau Greenwashing Scrutiny:Environmental marketing claim verification is extending advertising compliance timelines and requiring third-party efficiency certification documentation before campaign launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Kitchen Appliances Market |
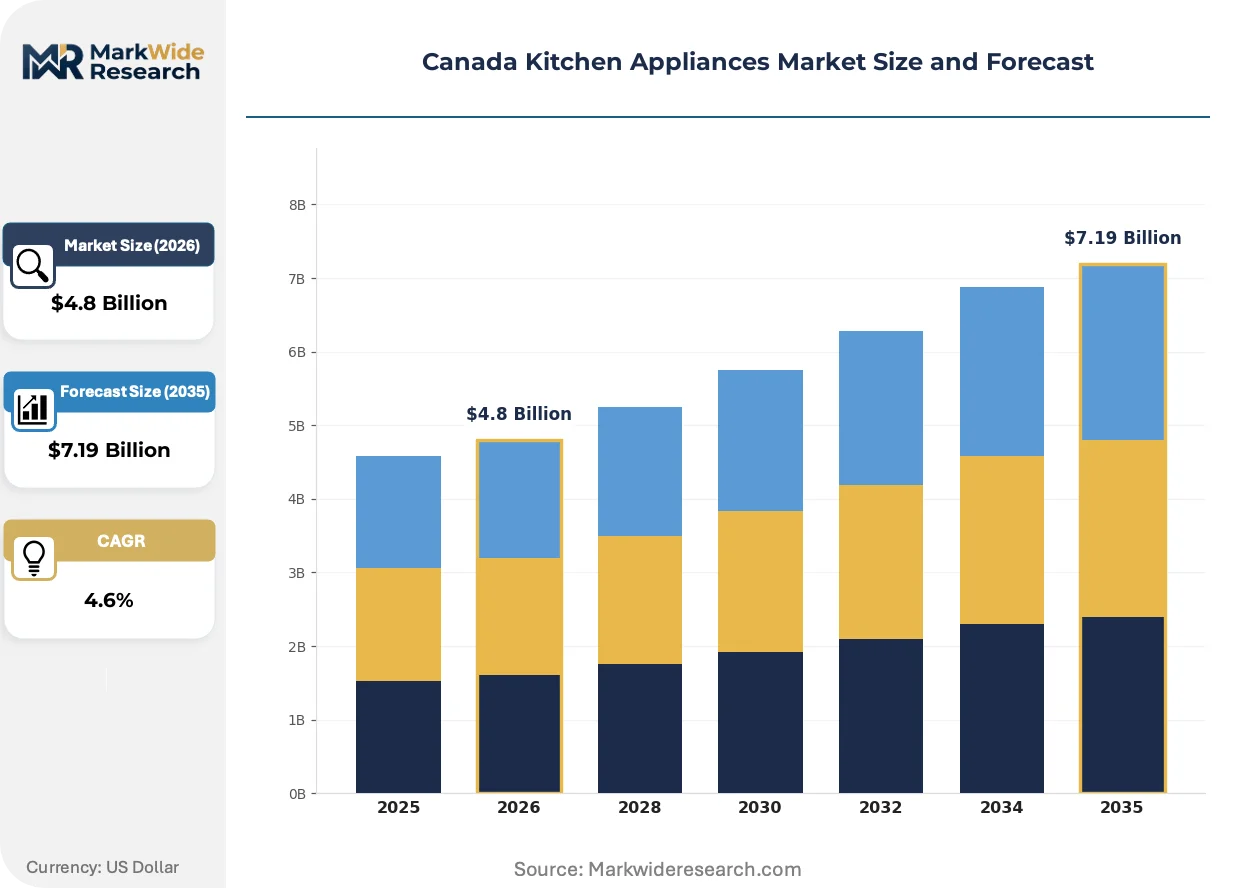
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Mixers End User: Residential, Commercial, Hospitality, Retail Technology: Smart Appliances, Energy-Efficient, Traditional, Built-In Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Samsung Electronics, BSH Hausgeräte, Whirlpool Corporation, Danby Products, Haier Smart Home, Electrolux AB, Panasonic Corporation, Midea Group, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Kitchen Appliances Market Strategic Shifts
Connected kitchen ecosystems, induction cooking platforms, and predictive maintenance algorithms are restructuring how appliances are specified, sold, and serviced across Canadian residential construction and renovation channels.
Induction cooking technology is converging with precision temperature sensors and smartphone-controlled recipe guidance. Custom home builders in Calgary and Edmonton are specifying these platforms in 40% of new luxury kitchens. The technology is compressing demand for traditional gas cooktops while forcing distributors to retrain sales staff on electrical load calculations.
Natural Resources Canada's EnerGuide labeling program is tightening disclosure requirements for refrigeration energy consumption. Manufacturers must now test under standardized ambient temperature protocols that better reflect Canadian climate conditions. This is compressing the efficiency gap between domestic and imported products while elevating R&D spending on variable-speed compressor designs.
Builder procurement patterns are consolidating around single-source appliance packages for multi-unit residential projects. Toronto condominium developers are negotiating three-year specification agreements with distributors that lock in pricing and warranty terms. This channel concentration is marginalizing independent retailers in the new-construction segment while rewarding national distribution networks with direct builder relationships.
Canada Kitchen Appliances Market Segmentation
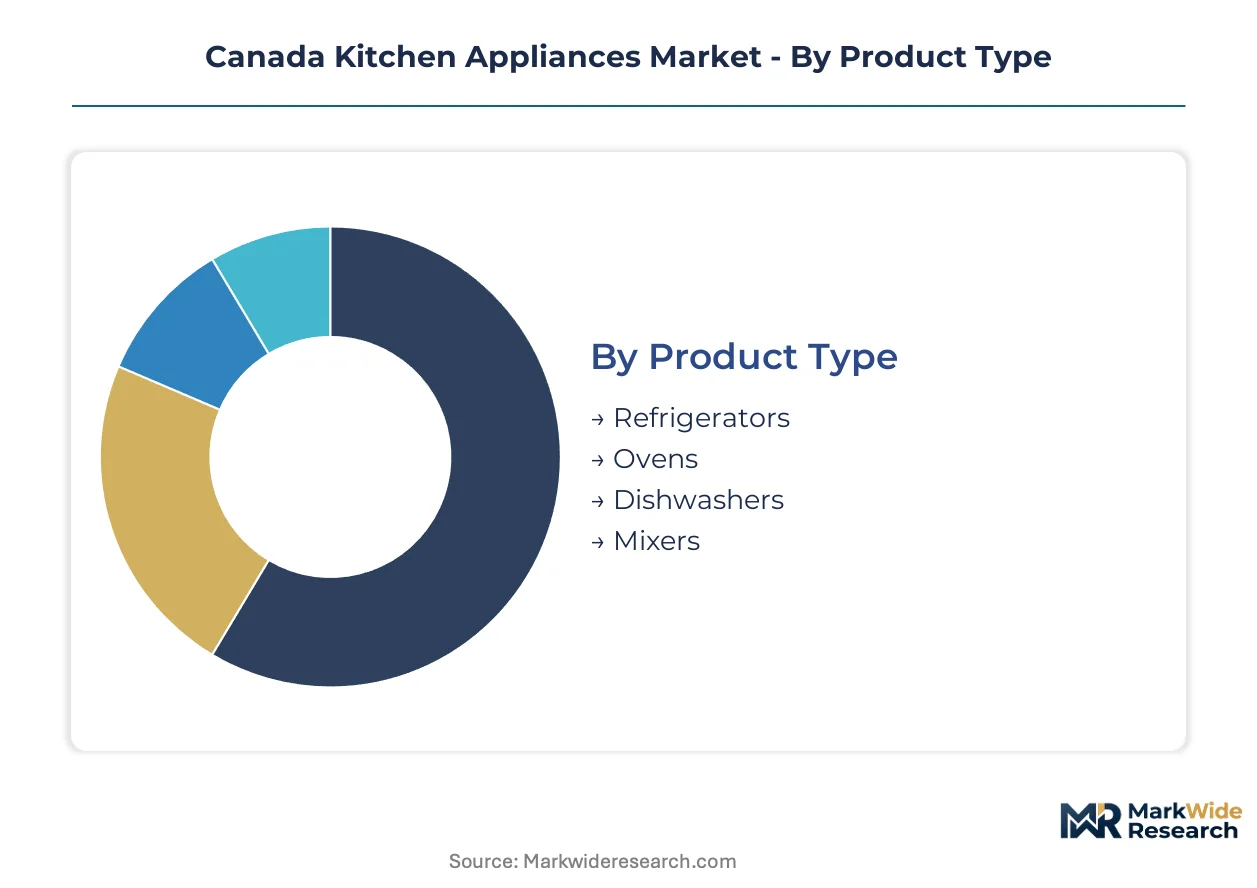
Kitchen appliance segmentation in Canada reflects divergent procurement logic across residential construction, renovation, and replacement channels. Product specifications vary sharply between Toronto condominium developers prioritizing compact efficiency and Calgary custom builders specifying premium built-in configurations.
Product Type:
Volume concentrates in universal household necessities, while premium margins accrue to specialized cooking platforms targeting custom installations.
- Refrigerators:French-door and bottom-freezer configurations dominate replacement cycles across Ontario and British Columbia. EnerGuide labeling mandates are compressing demand around variable-speed compressor designs that reduce annual kilowatt-hour consumption in Toronto's high-rise housing stock.
- Ovens:Wall ovens and range combinations anchor kitchen renovation spending in Vancouver's single-family detached segment. Induction-enabled platforms are displacing gas alternatives as electrical infrastructure upgrades accelerate in Calgary's luxury new construction.
- Dishwashers:Quiet-operation models with decibel ratings below 44 dBA satisfy open-concept kitchen layouts prevalent in Montreal's condominium conversions.
- Mixers:Stand mixers and food processors concentrate in gift-driven purchasing through holiday retail windows in Toronto and Vancouver metropolitan areas.
Today's leader: Refrigerators. Tomorrow's challenger: Ovens.
End User:
Application context determines durability specifications, warranty terms, and service network requirements across procurement channels.
- Residential:Single-family detached homes in Calgary and Edmonton generate full-size appliance demand with 15-20 year replacement horizons. Smart home integration specifications are rising fastest in British Columbia's new construction pipeline.
- Commercial:Restaurants and institutional kitchens in Toronto's food service corridor require NSF-certified durability with accelerated 5-7 year replacement cycles.
- Hospitality:Hotels and extended-stay properties in Vancouver's tourism sector specify compact refrigeration and cooking configurations for suite-style accommodations.
- Retail:Food retailers and convenience operators in Montreal's urban core deploy commercial-grade refrigeration for prepared food display cases.
Residential commands absolute volume. Commercial generates superior per-unit margins through specification-grade requirements.
Technology:
Connectivity and efficiency certifications are restructuring how appliances are specified, priced, and inventoried across Canadian distribution channels.
- Smart Appliances:Wi-Fi-enabled refrigeration and cooking platforms integrate with Amazon Alexa and Google Assistant ecosystems. Toronto condominium developers are specifying these in 60% of new luxury units, creating pull-through demand for compatible whole-home automation systems.
- Energy-Efficient:ENERGY STAR-certified products qualify for stacked federal-provincial rebate programs in Ontario and British Columbia. Natural Resources Canada's standardized testing protocols under tightening EnerGuide requirements are elevating R&D spending on compressor and insulation technologies.
- Traditional:Non-connected appliances without IoT functionality concentrate in price-sensitive replacement demand across Atlantic Canada and Quebec's secondary markets.
- Built-In:Panel-ready refrigeration and integrated cooking suites target custom residential installations in Calgary's luxury segment and Vancouver's west side renovations.
Energy-Efficient holds regulatory tailwinds. Smart Appliances are climbing the fastest as connectivity becomes standard in new construction specifications.
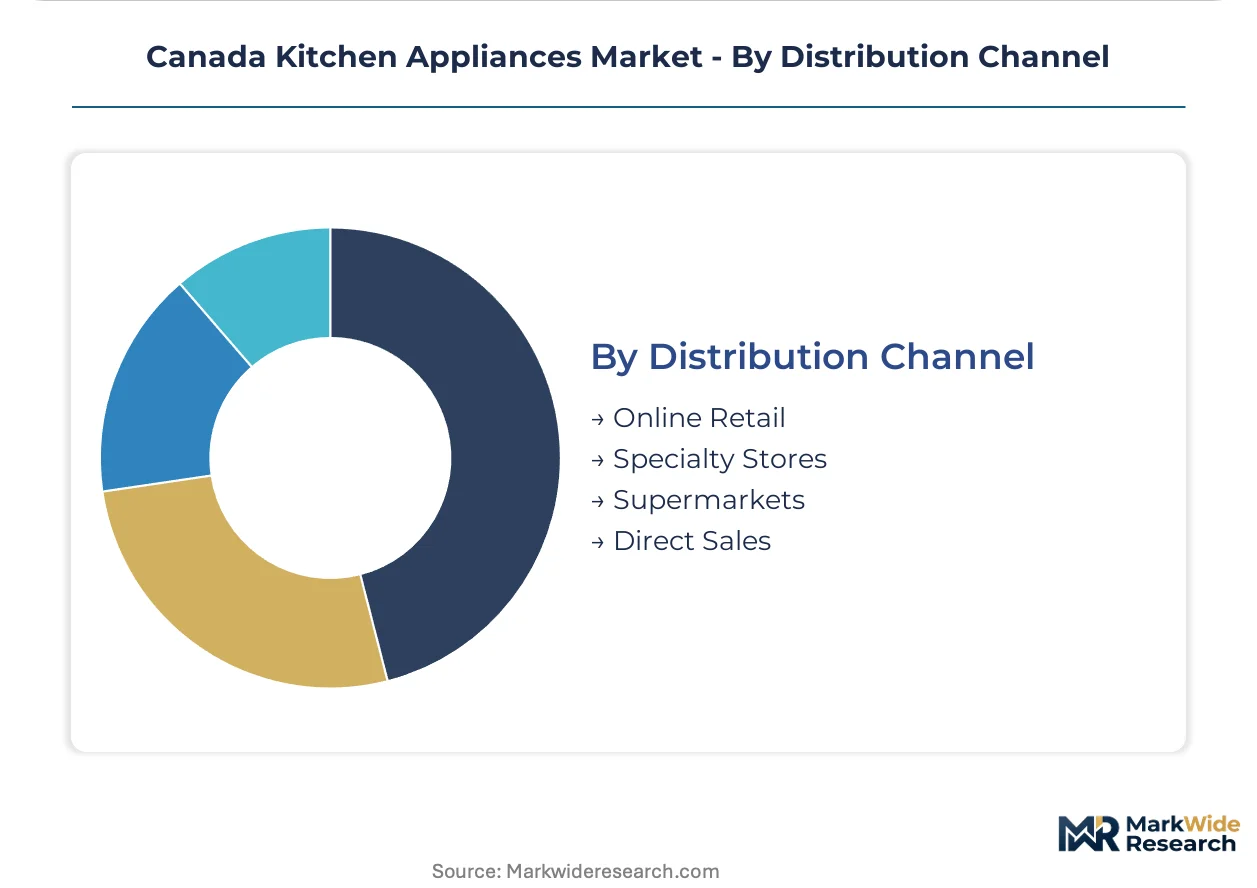
Distribution Channel:
Channel selection reflects purchase urgency, installation complexity, and warranty service requirements across end-user segments.
- Online Retail:E-commerce platforms capture replacement-driven demand for standard-size refrigeration and dishwashers in Toronto and Vancouver metropolitan areas. Delivery logistics and installation coordination remain friction points for complex built-in configurations.
- Specialty Stores:Independent dealers and regional chains dominate premium built-in and professional-grade cooking specifications. Calgary and Edmonton custom home builders rely on these channels for three-dimensional kitchen planning and electrical load consultation.
- Supermarkets:Mass merchants and big-box retailers concentrate volume in entry-level refrigeration and small appliances through promotional pricing and instant rebate redemption.
- Direct Sales:Manufacturer-direct procurement channels serve multi-unit residential developers in Toronto's condominium corridor with project-specific pricing and three-year warranty terms.
Specialty Stores anchor premium specification. Online Retail is expanding most quickly as logistics networks mature for large-appliance home delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's kitchen appliance industry traces its modern mass-market origins to post-war manufacturing expansion in Southern Ontario during the 1950s, when domestic production of refrigerators and electric ranges first achieved national distribution scale.
Ontario
Toronto's condominium development corridor and Ottawa's infill housing projects drive concentrated demand for compact, ENERGY STAR-certified refrigeration and built-in cooking suites. Natural Resources Canada's EnerGuide labeling mandates steer developer procurement toward variable-speed compressor designs tested under standardized Canadian climate protocols. The Golden Horseshoe manufacturing belt surrounding Hamilton and Kitchener-Waterloo hosts assembly operations serving mid-market dishwasher and oven distribution.
Quebec
Montreal's condominium conversion pipeline and Quebec City's heritage housing renovation sector generate replacement-driven demand for quiet-operation dishwashers below 44 dBA. The province's hydroelectric utility, Hydro-Québec, administers appliance rebate programs that accelerate induction cooktop adoption despite legacy 120V/240V electrical infrastructure constraints. Laval's distribution hubs coordinate logistics for Atlantic Canada supply.
British Columbia
Vancouver's high-density tower construction and Victoria's secondary suite regulations create pull-through demand for smart kitchen ecosystems integrating with whole-home automation. CleanBC provincial incentives stack with federal ENERGY STAR rebates to reduce consumer out-of-pocket costs for premium efficiency tiers. The Lower Mainland's west side renovation market specifies panel-ready refrigeration for custom residential installations.
Alberta
Calgary's luxury custom home builders and Edmonton's infill development generate specification-grade demand for connected cooking platforms with voice-assistant integration. Local electrical contractors report accelerating induction cooktop retrofits as panel upgrade costs decline. The Calgary-Edmonton corridor serves as the primary distribution node for Prairie province appliance supply.
Atlantic Canada
Halifax and Moncton residential construction runs below national smart-appliance penetration rates, creating first-mover positioning opportunities for connected kitchen platforms. Field service technician scarcity for smart appliance diagnostics and IoT connectivity repair leaves the region underserved for warranty fulfillment relative to central Canada. Provincial energy efficiency programs in Nova Scotia and New Brunswick offer smaller rebate pools than Ontario or British Columbia equivalents.
Canada Kitchen Appliances Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and connectivity integration depth. The market structure consolidates around three to four national distribution networks with direct builder relationships, marginalizing independent retailers in new-construction procurement. Strategic archetypes include diversified home appliance conglomerates with North American manufacturing footprints, Asian electronics specialists leveraging connected ecosystem platforms, and European premium built-in specialists targeting custom residential channels. Dominant competitive moves involve multi-year specification agreements with condominium developers and backward integration into compressor and control system component production.
Within the diversified conglomerate tier, Whirlpool Corporation and Electrolux AB occupy positions anchored by mid-market dishwasher and oven portfolios with established CSA certification histories. Samsung Electronics exemplifies the connected ecosystem archetype, leveraging Wi-Fi-enabled refrigeration and cooking platforms that integrate with broader smart home infrastructure. BSH Hausgeräte represents the European premium specialist model, focusing on built-in configurations for custom residential installations in Calgary and Vancouver luxury segments.
| Leading Market Players |
|---|
| Samsung Electronics |
| BSH Hausgeräte |
| Whirlpool Corporation |
| Danby Products |
| Haier Smart Home |
| Electrolux AB |
| Panasonic Corporation |
| Midea Group |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap distributors across Ontario and Quebec exercise disciplined pricing power through exclusive territory agreements with national manufacturers, compressing margin leakage while anchoring procurement contracts to ENERGY STAR certification tiers and volume rebate structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by ENERGY STAR certification grade and after-sales service bundling. Price differentiation intensifies as steel and aluminum input volatility squeezes mid-market manufacturers, forcing selective discounting in economy refrigeration tiers. Condominium developers in Toronto demonstrate lowest price sensitivity through locked three-year specification agreements, while Atlantic Canada replacement buyers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Hamilton, Laval, and Calgary anchor hub-and-spoke patterns feeding independent dealers and big-box retailers. Manufacturing concentrates in China, Mexico, and the United States for compressor assemblies and control systems. Steel and copper coil dependencies expose margins to commodity price swings. Single-source vulnerability in semiconductor-based IoT modules threatens smart appliance production schedules. Distribution runs through national networks with direct builder relationships marginalizing fragmented independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada kitchen appliances function as a stable compounder where Natural Resources Canada's tightening EnerGuide mandates perpetuate replacement-driven demand cycles with predictable regulatory tailwinds.
For Market Incumbents: Hedge against margin compression by securing captive supply of variable-speed compressors through backward integration or long-term offtake agreements with Mexican component suppliers. Fortify CSA certification portfolios to accelerate product introduction timelines against emerging Asian entrants. Defend channel position by locking multi-year specification agreements with Toronto condominium developers before rebate program shifts alter procurement priorities. For New Entrants and Emerging Players: Voice-assistant integration with induction cooktops offers a technology-first wedge into Calgary's luxury custom builder segment where electrical infrastructure upgrades accelerate premium platform adoption. Atlantic Canada's smart-appliance underpenetration presents white-space positioning for connected kitchen ecosystems with localized service partnerships. Target Halifax and Moncton through regional distributor alliances rather than direct national network competition. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market distributors with concentrated builder relationships and established CSA certification histories but limited smart-appliance service capabilities. Long-term viability over the projection horizon favors targets with backward integration into compressor sourcing or proprietary IoT platform development. Monitor Natural Resources Canada efficiency standard acceleration as the inflection signal compressing replacement cycles and elevating premium tier demand.| Strategic Initiative | Industry Significance |
|---|---|
| CSA Certification Acceleration | Shortens product introduction timelines against import competitors by 6-12 months. |
| Backward Integration into Compressors | Captures margin from Mexican component suppliers exposed to steel volatility. |
| Smart Home Platform Integration | Locks specification channels with Toronto developers prioritizing whole-home automation. |
| Atlantic Canada Distribution Partnership | Addresses field service scarcity while capturing first-mover smart-appliance positioning. |
| Provincial Rebate Stacking Programs | Reduces consumer out-of-pocket costs for ENERGY STAR tiers in Ontario and British Columbia. |
Study Parameters
Direct dialogue with appliance manufacturer product managers, condominium developer procurement directors, CSA Group certification engineers, and independent dealer owners grounded qualitative insights in operational reality. Secondary validation drew from Natural Resources Canada EnerGuide databases, ENERGY STAR Canada specifications, provincial utility rebate program filings, and customs import records. Bottom-up unit shipment estimates by product category and province triangulated against top-down market value reconstructions.
Bottom-up modeling segmented volume across refrigerators, ovens, dishwashers, and cooking platforms by technology tier, end-user application, and distribution channel. Top-down analysis anchored aggregate market sizing to residential construction permits, renovation expenditure surveys, and replacement cycle assumptions. CAGRs derived from regression against historical efficiency standard implementation impacts and provincial incentive program trajectories. Climate-adjusted energy consumption testing protocols and Wi-Fi penetration rates in new construction informed technology adoption curves.
The model holds under stable federal-provincial regulatory cooperation and continuous steel price normalization; deviation in tariff escalation or abrupt EnerGuide standard acceleration would shift replacement timing and manufacturer R&D allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market