
 Elbow Splints Market | 2026-2036
Elbow Splints Market Size, Share, and Industry Trends Forecast 2026-2036
Elbow Splints Market Analysis
Post-sale maintenance and fitting adjustment subscriptions is recalibrating how elbow splint vendors monetize hardware. DJO Global leverages its physical therapy clinic network to sustain recurring revenue streams. Bauerfeind anchors premium positioning through certified orthotist training programs that lock in provider loyalty.
An elbow splint is a medical device constructed from thermoplastic, aluminum, or composite materials that immobilizes or supports the elbow joint through adjustable strapping and rigid or semi-rigid structural elements. Its primary commercial purpose is to stabilize post-traumatic or post-surgical anatomy, control range of motion during tissue healing, and offload mechanical stress from injured tendons or ligaments. Rigid splints command the highest price tier due to custom fabrication requirements and orthotist labor intensity, while soft splints compete on volume through retail pharmacy and direct-to-consumer channels. Elastic splints occupy a narrowing mid-market position as athletes migrate toward sport-specific preventive designs and hospitals standardize on disposable soft alternatives.
The US FDA enforces quality system regulation and 510(k) premarket notification for elbow splints classed as medical devices, elevating compliance costs for new entrants. The EU Medical Device Regulation requires notified body certification and clinical evidence documentation, extending market access timelines for non-European manufacturers. Stakeholders must monitor reimbursement code consolidation across public and private payers, as coding density directly determines provider willingness to prescribe custom versus off-the-shelf configurations.
Market Dynamics
Orthopedic clinics are consolidating procurement authority into centralized supply chains, forcing splint vendors to restructure from product sales toward integrated service contracts that bundle fitting, adjustment, and maintenance.
Growth Catalysts
- Statutory reimbursement frameworks:Germany's statutory health insurance mandates coverage for custom-fabricated orthoses, eliminating out-of-pocket friction and accelerating prescription volume in orthopedic practices.
- Post-surgical stabilization protocols:Ambulatory surgery centers are expanding same-day discharge programs, creating demand for adjustable splints that patients can self-manage during early recovery phases.
- Thermoplastic material advances:Low-temperature thermoplastics now enable in-clinic molding without specialized heating equipment, reducing orthotist labor time and expanding point-of-care fabrication capacity.
Market Restraints
- Aluminum alloy supply concentration:Primary aluminum smelting capacity clusters in China and Russia, exposing splint manufacturers to tariff volatility and forced supply diversification into higher-cost European sources.
- EU MDR certification timelines:The EU Medical Device Regulation's clinical evidence requirements for Class IIa devices extend notified body review periods to 18-24 months, freezing market access for new product variants.
- Disposable soft splint substitution:Hospital systems are standardizing on single-use soft alternatives for short-term immobilization, compressing addressable volume for reusable rigid and semi-rigid configurations.
Strategic Opportunities
- Remote fitting platforms:Telehealth-integrated sizing apps using smartphone photogrammetry can unlock rural and homebound patient segments currently underserved by orthotist staffing shortages.
- Sport-specific preventive designs:Athletes in throwing sports represent an underpenetrated preventive application, with elbow stress loading patterns driving demand for motion-limiting training braces distinct from medical devices.
- Japan's aging demographic mandate:METI's Silver Innovation initiative subsidizes assistive device development, creating regulatory tailwinds for lightweight composite splints targeting osteoarthritis management in elderly populations.
Industry Challenges
- Certified orthotist scarcity:The American Board for Certification in Orthotics, Prosthetics and Pediatrics reports stagnant credentialing rates, constraining custom fabrication capacity even where demand exists.
- Legacy ERP integration friction:Clinic networks adopting centralized procurement platforms face data migration complexity with splint vendors operating on disparate inventory management systems.
- 510(k) predicate device limitations:FDA's narrowing acceptance of substantial equivalence claims for novel material compositions forces de novo pathway submissions with extended review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elbow Splints Market |
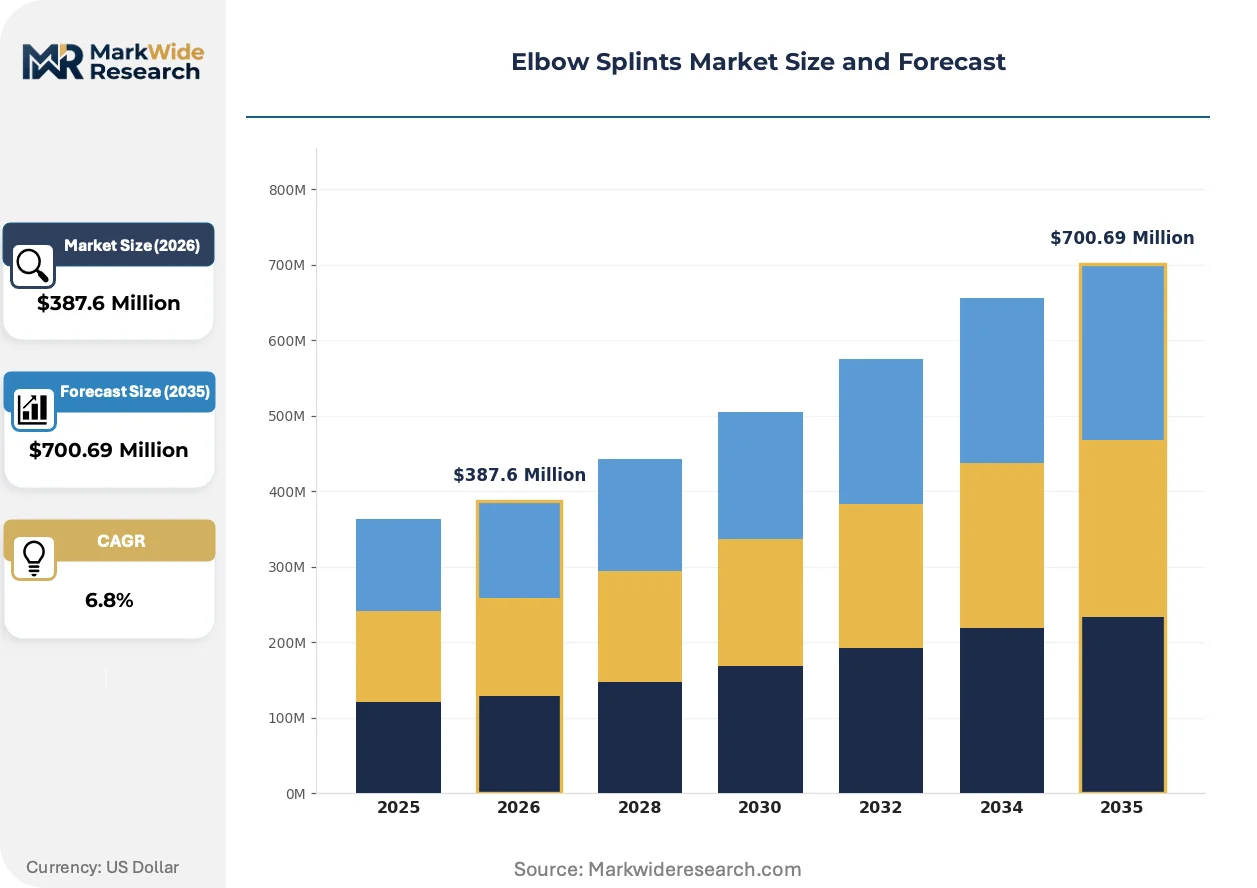
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Splints, Elastic Splints, Soft Splints, Custom Splints Material: Fabric, Thermoplastic, Aluminum, Neoprene End User: Athletes, Hospitals, Physiotherapy Clinics, Home Users Application: Injury Recovery, Post-Surgery Support, Rehabilitation, Preventive Care |
| Companies Covered | DJO Global, Breg, Össur, 3M, Stryker, Ottobock, Medi, Novamed, Bauerfeind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elbow Splints Market Emerging Trajectories
Digital fabrication workflows and sensor-embedded monitoring capabilities are redefining product architecture, shifting competitive advantage from material sourcing toward data-driven patient adherence platforms.
Carbon fiber reinforced thermoplastic composites are consolidating manufacturing economics across premium splint categories. These materials deliver strength-to-weight ratios exceeding aluminum at 40% lower mass, enabling longer wear compliance. Major orthopedic device distributors are consolidating supplier relationships around vendors with in-house composite layup capability, compressing margins for metal-dependent fabricators.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing serialization investments across the supply chain. Manufacturers must now maintain device history records traceable to individual patients, elevating quality management system costs. Small-to-mid fabricators without existing ERP infrastructure face disproportionate compliance burdens, accelerating consolidation toward vertically integrated producers with captive MDR expertise.
Subscription-based fitting adjustment services are displacing traditional hardware-only transactions in orthopedic clinic procurement. Hospital systems in the United States are unbundling splint provision from professional fitting fees, creating demand for vendors willing to assume ongoing patient interface responsibility. This model concentrates in integrated delivery networks with capitated reimbursement contracts, where outcome accountability drives preference for full-service partnerships over discrete product purchases.
Elbow Splints Market Segmentation
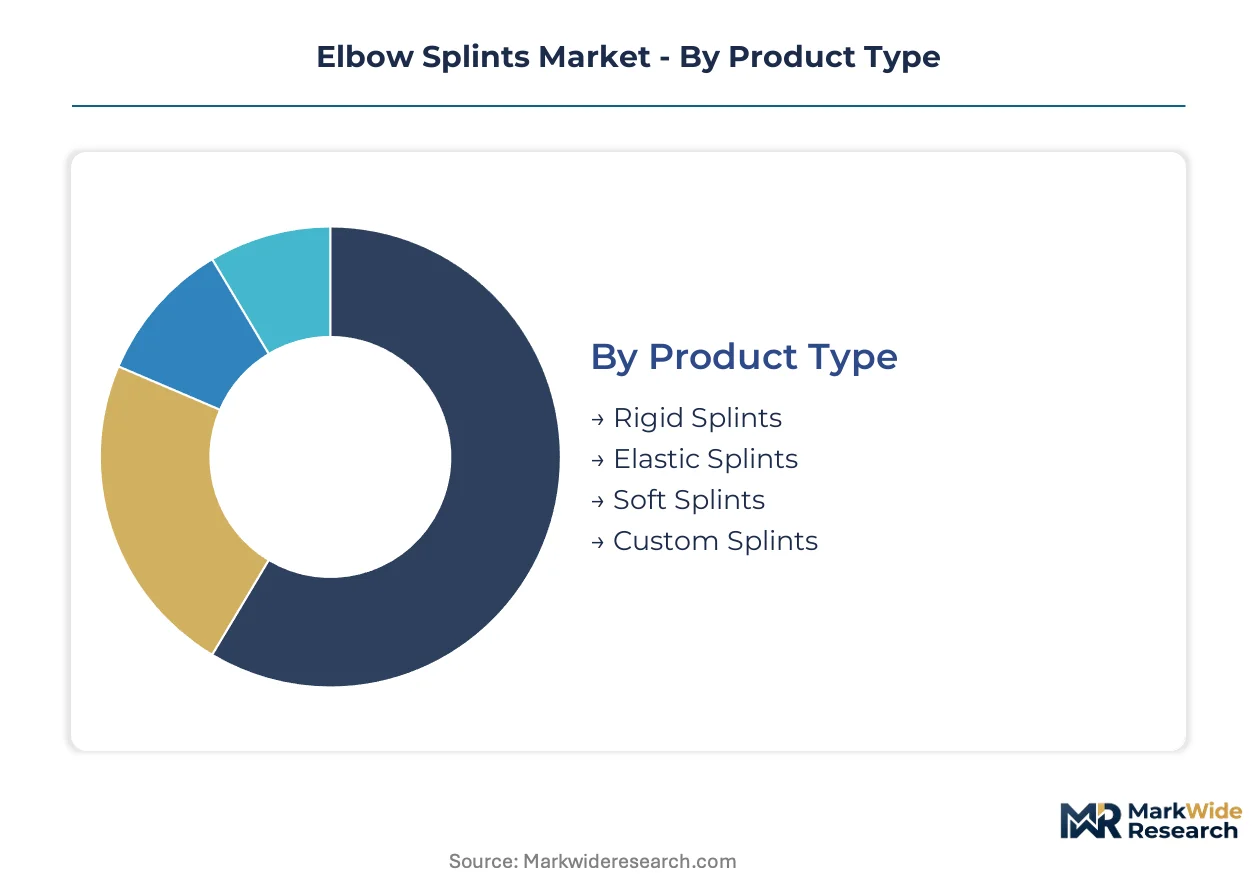
Elbow splint procurement decisions diverge sharply across clinical versus consumer channels, with reimbursement eligibility and orthotist availability dictating product-mix priorities. Material selection and fabrication method determine margin structures that separate premium custom fabricators from volume-driven soft-goods suppliers.
Product Type:
Price tolerance and fitting complexity separate institutional buyers from retail purchasers in this category.
- Rigid Splints:Constructed from aluminum framing or thermoplastic shells with adjustable hinge mechanisms, these devices immobilize the elbow joint through mechanical locking. Demand concentrates in orthopedic clinics across Germany where statutory health insurance eliminates patient cost barriers for custom-fabricated configurations. Orthotist labor intensity sustains premium pricing tiers.
- Soft Splints:Foam-padded fabric assemblies with Velcro strapping provide compression and mild stabilization without joint immobilization. Hospital systems in the United States are standardizing on disposable variants for short-term post-surgical discharge, compressing margins for reusable alternatives. Volume scales through centralized procurement contracts.
- Elastic Splints:Knitted compression sleeves with integrated gel pads deliver proprioceptive feedback during activity. Athletes in throwing sports drive preventive applications distinct from medical device channels.
- Custom Splints:Patient-specific thermoplastic molding fabricated in-clinic by certified orthotists matches anatomical irregularities. Low-temperature thermoplastic advances are reducing heating equipment requirements and expanding point-of-care capacity.
Volume sits with soft splints; growth tilts toward custom configurations as reimbursement frameworks mature.
Material:
Supply chain geography and processing energy intensity differentiate input cost structures for fabricators.
- Thermoplastic:Low-temperature activated polymers enable in-clinic molding without specialized heating infrastructure. German orthopedic practices leverage these materials to expand same-day fabrication capacity while reducing orthotist labor time per unit.
- Aluminum:Lightweight alloy framing delivers structural rigidity for trauma immobilization. Primary smelting concentration in China and Russia exposes manufacturers to tariff volatility and forced diversification into higher-cost European sources.
- Fabric:Breathable textile laminates with moisture-wicking properties serve high-wear compliance requirements in athletic and home-use segments.
- Neoprene:Synthetic rubber foam provides thermal retention and compression for soft-tissue injury management in retail pharmacy channels.
Procurement weighting favors thermoplastic; carbon fiber composites are gaining share fastest in premium categories.
End User:
Professional fitting requirements and outcome accountability determine service bundling expectations.
- Hospitals:Centralized supply chains demand integrated service contracts covering fitting, adjustment, and maintenance rather than discrete product transactions. US integrated delivery networks with capitated reimbursement contracts concentrate procurement authority.
- Physiotherapy Clinics:DJO Global leverages its clinic network to sustain recurring revenue through post-sale maintenance subscriptions. Orthotist staffing shortages constrain custom fabrication capacity even where patient demand exists.
- Athletes:Throwing sports participants represent an underpenetrated preventive application with motion-limiting training brace requirements distinct from medical devices.
- Home Users:Direct-to-consumer channels favor soft and elastic configurations with self-fitting capability, bypassing professional orthotist involvement.
Revenue concentrates in physiotherapy clinics; expansion tilts toward home users as telehealth-integrated sizing platforms mature.
Application:
Tissue healing timelines and range-of-motion requirements dictate product substitution patterns across recovery phases.
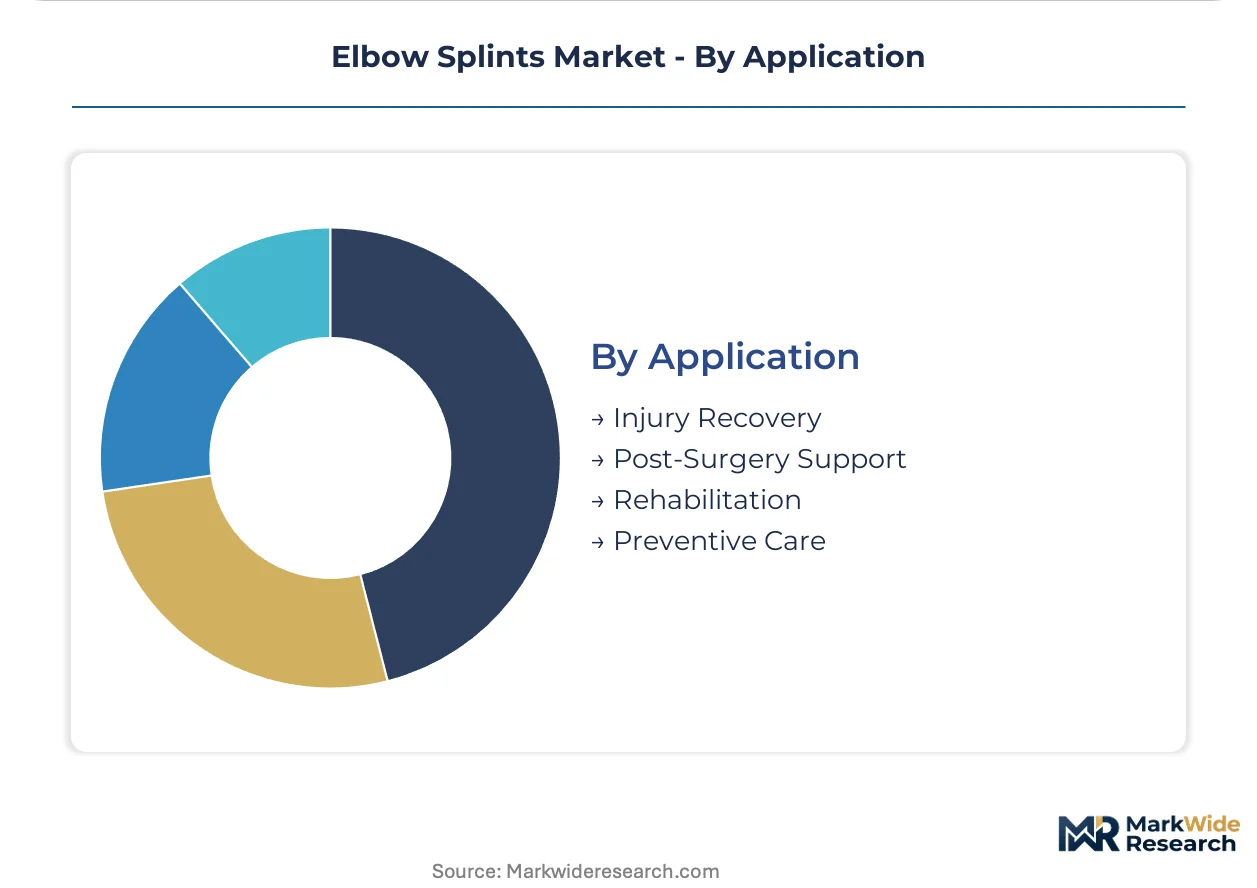
- Post-Surgery Support:Ambulatory surgery centers expanding same-day discharge programs require adjustable splints that patients can self-manage during early recovery. FDA 510(k) premarket notification requirements elevate compliance costs for device classification.
- Rehabilitation:Progressive range-of-motion protocols demand modular splint architectures with removable hinge stops. EU MDR clinical evidence requirements for Class IIa devices extend notified body review periods.
- Injury Recovery:Traumatic ligament and tendon injuries require immediate immobilization transitioning to controlled mobilization.
- Preventive Care:Occupational and athletic stress loading applications drive demand for sport-specific designs outside medical device regulatory frameworks.
Procedure volume anchors post-surgery support; preventive care climbs fastest as athletic participation rates rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European splint procurement volume through its dense cluster of orthopedic device distributors and statutory reimbursement administration centers serving the Rhine-Ruhr metropolitan region.
United States
Ambulatory surgery centers in Phoenix and Dallas drive demand for patient-managed adjustable splints under same-day discharge protocols. The FDA enforces 510(k) premarket notification requirements for Class II medical devices, elevating compliance costs for new market entrants. DJO Global leverages its physical therapy clinic network across the Southeast to sustain recurring revenue through post-sale maintenance subscriptions.
Germany
Orthopedic practices in Berlin and Munich expand same-day custom fabrication capacity using low-temperature thermoplastic advances. Statutory health insurance mandates coverage for custom-fabricated orthoses, eliminating patient cost friction and accelerating prescription volume. Bauerfeind anchors premium positioning through certified orthotist training programs that lock in provider loyalty across Bavaria and Baden-Württemberg.
Japan
Tokyo's aging demographic concentrates demand for lightweight composite splints targeting osteoarthritis management in elderly populations. METI's Silver Innovation initiative subsidizes assistive device development, creating regulatory tailwinds for domestic manufacturers. Osaka-based distributors consolidate supplier relationships around vendors with in-house composite layup capability.
China
Primary aluminum smelting capacity clusters in Shandong and Xinjiang, exposing splint manufacturers to tariff volatility and forced supply diversification. The NMPA enforces medical device registration requirements that extend market access timelines for imported configurations. Shenzhen's electronics manufacturing ecosystem enables sensor-embedded monitoring capabilities for next-generation rehabilitation devices.
United Kingdom
London's integrated delivery networks unbundle splint provision from professional fitting fees, creating demand for vendors willing to assume ongoing patient interface responsibility. The MHRA enforces EU MDR-aligned clinical evidence requirements for Class IIa devices post-Brexit. Manchester's NHS procurement hubs standardize on disposable soft alternatives for short-term immobilization, compressing margins for reusable configurations.
Elbow Splints Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the elbow splint market, with integrated manufacturers maintaining captive orthotist networks while specialized fabricators outsource distribution to orthopedic clinic chains. The vendor base stratifies into three tiers: premium custom fabricators with certified training ecosystems, mid-market thermoplastic suppliers serving centralized hospital procurement, and volume-driven soft-goods competitors in retail pharmacy channels. Dominant competitive moves include backward integration into composite material production and strategic partnerships with telehealth platforms for remote fitting capabilities.
Among US-based diversified orthopedic device corporations, DJO Global and Stryker exemplify the integrated service-contract archetype, bundling hardware with ongoing fitting and maintenance obligations. Bauerfeind, a German GmbH-structured specialist, anchors the premium custom-fabrication tier through provider certification programs. Össur, an Icelandic-origin prosthetics and orthotics group, occupies a transnational position spanning both medical device and athletic preventive applications.
| Leading Market Players |
|---|
| DJO Global |
| Breg |
| Össur |
| 3M |
| Stryker |
| Ottobock |
| Medi |
| Novamed |
| Bauerfeind |
| Others |
Supply Flow & Price Mechanics
Centralized hospital procurement programs in the United States are compressing transaction economics toward subscription-based service contracts that bundle hardware with ongoing fitting obligations. This buyer concentration is reshaping margin structures across rigid and soft splint categories, rewarding vendors with orthotist network scale while squeezing metal-dependent fabricators facing aluminum tariff exposure.
Pricing Analysis
Outcome-based pricing anchored to patient adherence metrics is displacing traditional per-unit transactions in capitated reimbursement environments. Three-tier pricing structure across premium custom-fabricated, standard thermoplastic, and economy disposable levels separates certified orthotist-delivered configurations from self-fitting retail alternatives. Cost compression in soft splint categories is intensifying because hospital systems are standardizing on single-use alternatives, while rigid splint margins remain protected by orthotist labor scarcity. Price sensitivity concentrates among home users in direct-to-consumer channels, whereas orthopedic clinics demonstrate inelastic demand for custom-fabricated configurations under statutory reimbursement frameworks.
Supply Chain Analysis
Refurbishment and remanufacturing flows for adjustable hinge mechanisms are emerging as secondary value streams for clinic networks managing splint lifecycle costs. Primary aluminum smelting capacity draws from China and Russia, exposing manufacturers to tariff volatility and forced diversification into European sources. Low-temperature thermoplastic polymers and carbon fiber composite prepregs constitute critical input dependencies alongside breathable textile laminates. Single-source vulnerability concentrates in Chinese aluminum alloy supply, with Shandong and Xinjiang smelters dominating global primary production. Distribution runs through orthopedic device distributors in Düsseldorf and integrated delivery networks in Phoenix and Dallas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's 18-24 month notified body review timelines for Class IIa devices have erected a formidable cost-of-compliance barrier that entrenches incumbent positions and deters speculative entry. This regulatory moat rewards players with captive MDR expertise and serialized quality management infrastructure.
For Market Incumbents: To counter certified orthotist scarcity constraining custom fabrication capacity, secure backward integration into low-temperature thermoplastic resin production and expand point-of-care molding capacity in German orthopedic practices. Anchor provider loyalty through certified training ecosystems that lock in prescription volume under statutory reimbursement frameworks. For New Entrants and Emerging Players: Launch via telehealth-integrated smartphone photogrammetry platforms targeting rural and homebound patient segments currently underserved by orthotist staffing shortages. Penetrable white space sits in sport-specific preventive designs for throwing athletes, with motion-limiting training braces falling outside medical device regulatory pathways. Pursue direct-to-consumer channels with self-fitting elastic configurations bypassing professional orthotist involvement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap composite fabricators with in-house carbon fiber layup capability in Japan and Germany, where METI subsidies and statutory reimbursement frameworks provide regulatory tailwinds. Long-term viability over a five-to-ten year window hinges on MDR compliance infrastructure and orthotist network scale. Monitor EU notified body queue lengths as an inflection indicator for market access velocity and competitive entry dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body certification unlocks German statutory reimbursement volume. |
| Hospital System Partnership | Integrated service contracts with US IDNs secure recurring revenue under capitated models. |
| Software Companion Development | Telehealth-integrated sizing apps expand addressable reach beyond orthotist-constrained geographies. |
| Reimbursement Strategy | CMS coding alignment determines provider willingness to prescribe custom versus off-the-shelf configurations. |
| Backward Integration | In-house carbon fiber composite production compresses material costs and insulates against aluminum tariff exposure. |
Methodological Framework
Document review covered FDA 510(k) premarket notification databases, EU MDR notified body certification records, and statutory health insurance reimbursement frameworks, complemented by interviews with orthopedic clinic procurement directors, certified orthotists, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare claims data, and customs trade records for aluminum alloy and thermoplastic resin imports. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored market size estimation across the analysis window.
Historical procedure volume trends were cross-referenced against panel input from ambulatory surgery center administrators and orthopedic practice managers to calibrate adoption trajectory assumptions. Segmentation modeling captured product type, material composition, end user channel, and application phase dimensions alongside regional regulatory cluster variations. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions tied to reimbursement code consolidation patterns and material cost dynamics.
Regulatory timeline delays, orthotist credentialing rate stagnation, and aluminum tariff volatility are the dominant revision risks that could materially alter competitive positioning and market access velocity. Forecasts reflect documented assumptions regarding MDR implementation pace and statutory reimbursement stability. Material deviation in named triggers warrants pause and re-evaluation of capacity commitment and geographic prioritization decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Global Lancets Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Medical Liners Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Skin Tac Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Asia-Pacific N95 Mask Market